
 Single-Use Assemblies Market | 2026-2036
Single-Use Assemblies Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Use Assemblies Market Intelligence
Buyer concentration among Contract Manufacturing Organizations is decoupling from traditional pharmaceutical hierarchies as biotech outsourcing accelerates. Thermo Fisher Scientific Inc. leverages its integrated life sciences platform to dominate upstream disposable supply. Sartorius AG anchors European bioprocessing demand through specialized single-use bioreactor design. Danaher Corporation extends its position via Pall Corporation filtration expertise embedded in assembly workflows.
Single-use assemblies comprise pre-sterilized, gamma-irradiated plastic components—typically polypropylene or polyethylene tubing, bags, and connectors—engineered for aseptic fluid handling in biomanufacturing without cleaning validation cycles. These systems eliminate cross-contamination risk while reducing facility capital expenditure versus stainless-steel infrastructure. Bags and tubing capture the largest volume share as cell culture media storage and transfer applications standardize on disposable formats. Filters represent the fastest-expanding margin pool as tangential flow filtration shifts entirely to single-use cassettes in clinical-scale operations. Bioreactors remain the highest-value per-unit segment though adoption concentrates in mammalian cell lines for monoclonal antibody production.
FDA enforces Current Good Manufacturing Practice for finished pharmaceuticals through rigorous extractables and leachables testing protocols that shape supplier qualification timelines. EMA's Annex 1 revision on sterile manufacturing mandates closed-system design, directly accelerating demand for welded tube sets over open connections. China's NMPA aligns with ICH Q5A viral safety guidelines, creating harmonized entry requirements for multinational assembly suppliers. Stakeholders must monitor regulatory divergence on plasticizer restrictions and end-of-life disposal mandates as sustainability pressures intensify across jurisdictions.
Market Dynamics
Contract Manufacturing Organizations are consolidating purchasing power as biologics pipelines deepen, forcing single-use assembly suppliers to absorb validation costs and compress lead times for gamma-irradiated components.
Growth Catalysts
- EMA Annex 1 revision:The sterile manufacturing mandate for closed-system design accelerates demand for welded tube sets over open connections across European bioprocessing facilities.
- Monoclonal antibody production:Mammalian cell line expansion in mammalian cell culture media storage applications standardizes on disposable bag-and-tubing formats.
- China biomanufacturing clusters:Dense concentration of biotech facilities in Shanghai and Suzhou creates localized pull for pre-sterilized fluid handling systems aligned with NMPA viral safety guidelines.
Market Restraints
- Specialized resin supply concentration:Medical-grade polypropylene and polyethylene feedstock production concentrates among a limited supplier base, exposing converters to input cost volatility.
- Extractables testing burden:FDA Current Good Manufacturing Practice protocols extend supplier qualification timelines by 12-18 months for novel assembly designs.
- Stainless-steel retention in large-scale:Commercial antibody manufacturing above 10,000-liter scale maintains stainless-steel infrastructure due to per-unit cost advantages.
Strategic Opportunities
- Cell and gene therapy manufacturing:Viral vector production workflows demand smaller-batch, higher-changeover disposable systems not optimized by incumbent suppliers.
- Continuous bioprocessing adoption:Perfusion cell culture technology converges with single-use bioreactor design, creating white space for integrated perfusion-ready assembly platforms.
- Indian biopharma expansion:CDSCO manufacturing incentives and PLI scheme subsidies attract multinational biotech investment, driving virgin demand for disposable filtration and transfer systems.
Industry Challenges
- Polymer science expertise scarcity:Gamma-irradiation validation and leachables testing require specialized analytical chemists in short supply across contract manufacturers.
- Legacy equipment interoperability:Welded connector standards vary across supplier platforms, complicating integration with existing stainless-steel skids and control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Use Assemblies Market |
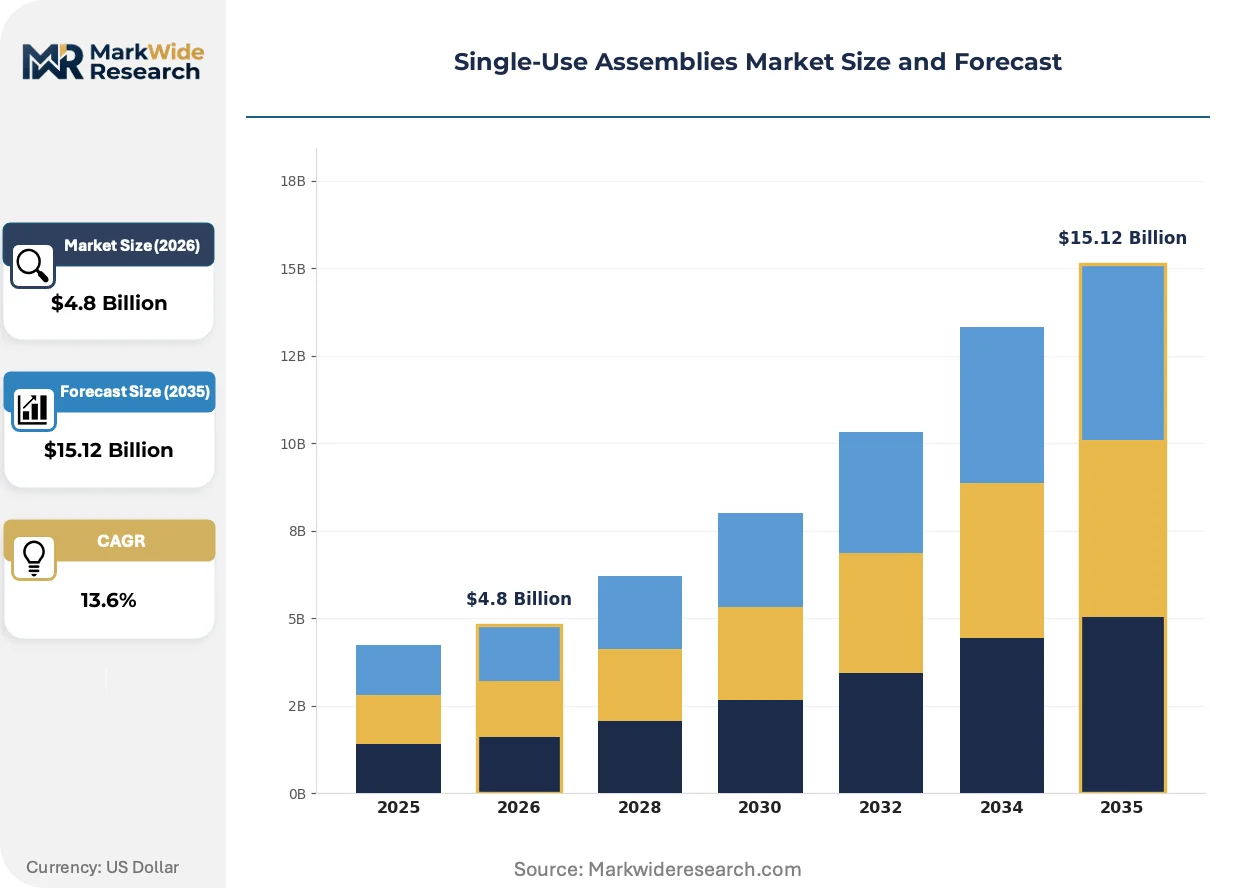
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.12 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioreactors, Bags, Tubing, Filters End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturing Organizations, Research Laboratories Application: Cell Culture, Vaccine Production, Bioprocessing, Drug Development Material: Polypropylene, Polyethylene, Polyvinyl Chloride, Nylon |
| Companies Covered | Thermo Fisher Scientific Inc., Sartorius AG, Merck KGaA, Danaher Corporation, Avantor Inc., Corning Incorporated, Entegris, Saint-Gobain, Lonza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Use Assemblies Market Strategic Shifts & Innovations
Closed-system architecture and modular fluid path design are compressing facility build-out timelines while regulatory pressure on extractables documentation intensifies material science investment.
Multi-layer film technology is integrating ethylene vinyl alcohol and cyclic olefin polymer barrier layers to extend product stability for cell culture media with sensitive chemistries. Mid-scale biologics manufacturers are adopting these advanced films for 2,000-liter single-use bioreactors. The technology is integrating upstream and downstream unit operations into unified disposable trains, eliminating intermediate transfer steps.
FDA extractables and leachables testing protocols are tightening documentation requirements for plasticizers and slip agents in gamma-irradiated assemblies. Suppliers must now submit comprehensive chemical characterization data prior to qualification. Mammalian cell therapy manufacturers in the United States face the steepest compliance burden, accelerating partnerships with film converters possessing in-house analytical capabilities.
Buyer consortiums at large Contract Manufacturing Organizations are consolidating supplier relationships and demanding outcome-based validation packages rather than component-level purchasing. This procurement evolution compresses vendor margins while transferring qualification risk to assembly suppliers. The shift is most visible in Germany, where Sartorius and Thermo Fisher compete for preferred supplier status at multi-site CDMO networks.
Single-Use Assemblies Market Segmentation
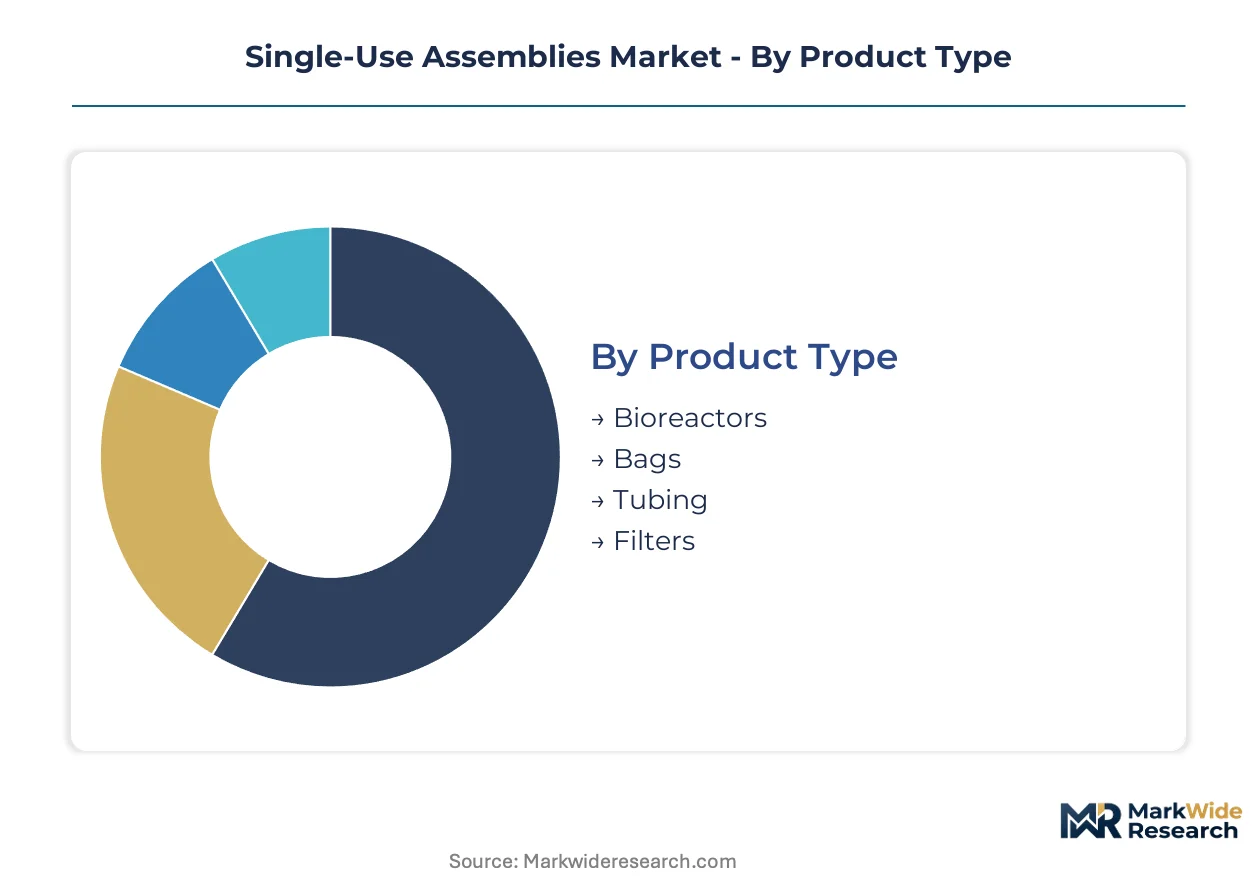
Single-use assembly procurement varies sharply across product categories and end-user scale, with standardization dominant in high-volume tubing while bioreactors demand extensive customization for cell-line-specific configurations. Material selection and application requirements further fragment supplier strategies, creating distinct margin profiles across the value chain.
Product Type:
Customization intensity spans from commodity tubing to engineered bioreactor systems, with gamma-irradiation validation requirements and film-layer complexity determining supplier qualification burdens.
- Bioreactors:Multi-layer film vessels with integrated sensor ports and agitation mechanisms, engineered for mammalian cell culture at 50-2,000 liter scales. Demand concentrates among Contract Manufacturing Organizations in Germany and the United States as monoclonal antibody pipelines deepen, though stainless-steel retention above 10,000 liters constrains addressable volume in commercial-scale manufacturing.
- Filters:Tangential flow filtration cassettes and depth filter capsules designed for sterile clarification and viral clearance. Adoption is accelerating fastest in cell and gene therapy viral vector production, where smaller batch sizes and higher changeover frequency favor disposable formats over cleanable stainless-steel housings.
- Bags:Multi-chamber containers for media storage, buffer preparation, and harvest collection, typically 2D pillow or 3D cylindrical geometries with welded tube ports.
- Tubing:Extruded polypropylene or polyethylene conduit with welded connectors for aseptic fluid transfer, the most standardized and price-competitive segment.
Leading the category by volume: Tubing. Growing fastest: Filters.
End User:
Procurement sophistication varies from centralized global sourcing at pharmaceutical multinationals to project-based purchasing at emerging biotechs, with validation cost absorption becoming a competitive differentiator.
- Contract Manufacturing Organizations:Multi-site networks with consolidated supplier relationships and outcome-based validation requirements. These buyers dominate gamma-irradiated assembly procurement in China and India, leveraging purchasing scale to compress lead times and transfer qualification risk to vendors.
- Pharmaceutical Companies:In-house biologics manufacturing operations with legacy stainless-steel infrastructure and selective single-use adoption for clinical-scale production. FDA extractables documentation demands create the steepest compliance burden for mammalian cell therapy programs in the United States.
- Biotech Firms:Venture-funded developers with pipeline-stage assets, prioritizing facility flexibility and rapid product changeover over per-unit cost optimization.
- Research Laboratories:Academic and government institutions with small-volume, catalog-based purchasing and minimal customization requirements.
Dominant procurement volume: Contract Manufacturing Organizations. Steepest expansion trajectory: Biotech Firms.
Application:
Process stage determines sterility assurance requirements and closed-system design intensity, with downstream operations facing tighter EMA Annex 1 mandates than upstream cell expansion.
- Cell Culture:Media preparation, inoculation, and expansion workflows requiring sterile fluid handling from thaw through harvest. Perfusion technology adoption is converging with single-use bioreactor design, creating demand for integrated perfusion-ready assembly platforms with continuous media exchange capabilities.
- Vaccine Production:Viral seed expansion and inactivation processes with stringent viral safety protocols aligned to ICH Q5A guidelines. China's NMPA has harmonized entry requirements for multinational suppliers serving domestic vaccine manufacturing clusters in Shanghai and Suzhou.
- Bioprocessing:Unified upstream and downstream unit operations spanning clarification through final fill, where modular fluid path design eliminates intermediate transfer steps.
- Drug Development:Clinical-scale manufacturing with accelerated timeline requirements and flexible batch sizing for Phase I/II material supply.
Core volume concentration: Cell Culture. Gaining share fastest: Vaccine Production.
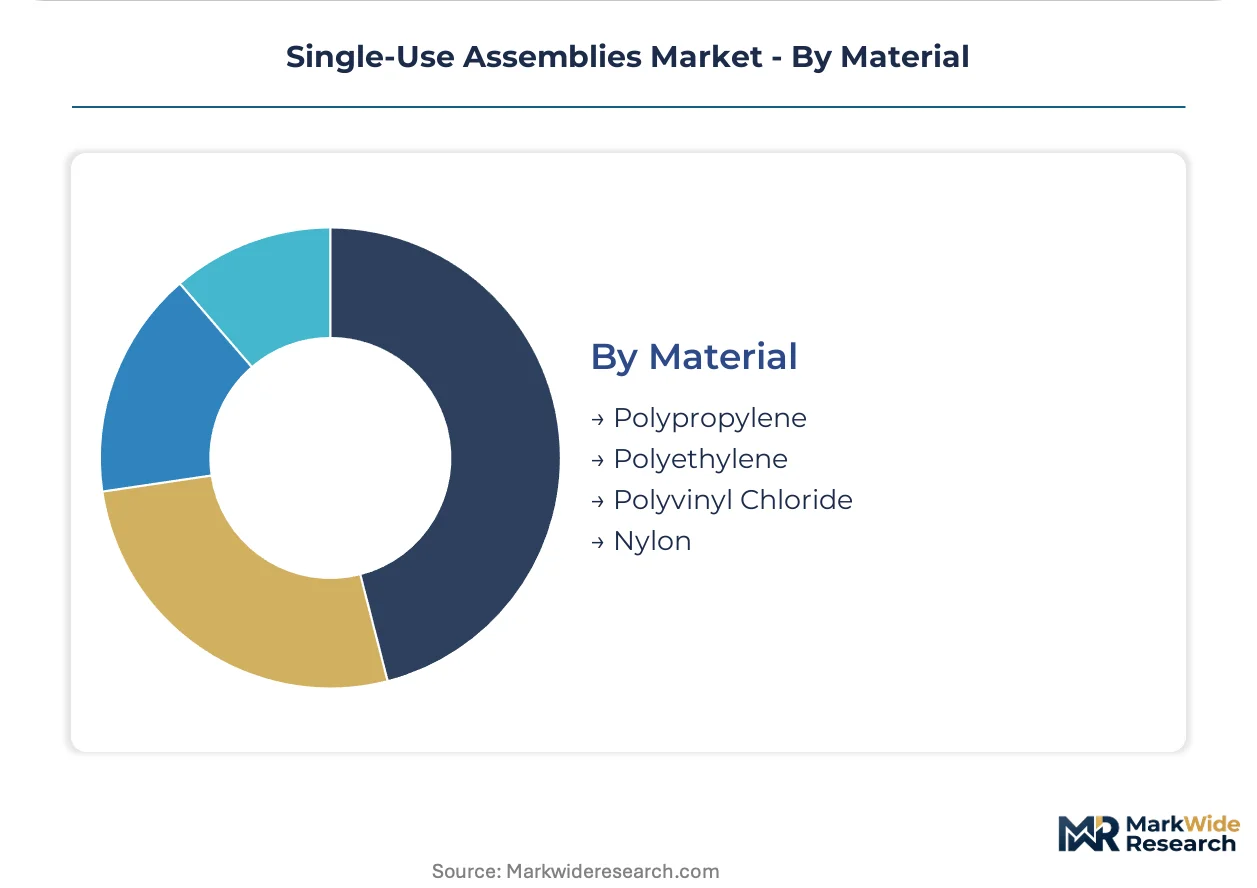
Material:
Resin grade and additive packages determine leachables profiles and gamma-irradiation stability, with medical-grade feedstock supply concentrating among limited polymer producers.
- Polypropylene:Gamma-stable thermoplastic with low extractables profiles, dominant in tubing and bag films for cell culture media storage. Specialized resin supply concentration exposes converters to input cost volatility, particularly for medical-grade grades with narrow molecular weight distributions.
- Polyethylene:Linear low-density and ultra-high molecular weight grades for flexible container applications and weldable tubing, with ethylene vinyl alcohol barrier layers extending product stability for sensitive chemistries.
- Polyvinyl Chloride:Plasticized formulations for specific fluid transfer applications, facing regulatory scrutiny on plasticizer restrictions across European jurisdictions.
- Nylon:High-strength polymer for connector components and filtration support structures requiring mechanical durability.
Highest volume utilization: Polypropylene. Expanding most quickly: Polyethylene with advanced barrier formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomanufacturing demand concentrates in three national clusters where regulatory frameworks and capital investment align most closely. The United States, Germany, and China each anchor distinct supply chain configurations shaped by local FDA, EMA, and NMPA enforcement priorities.
United States
Monoclonal antibody pipelines at Boston and San Francisco biotech clusters drive gamma-irradiated assembly procurement. FDA extractables and leachables testing protocols extend supplier qualification timelines, favoring incumbent vendors with established validation dossiers. Mammalian cell therapy manufacturers in Massachusetts face the steepest compliance documentation burdens.
Germany
Sartorius anchors European bioprocessing demand through specialized single-use bioreactor engineering. EMA Annex 1 sterile manufacturing mandates accelerate welded tube set adoption across Bavarian and North Rhine-Westphalia manufacturing sites. CDMO purchasing consortiums in Munich and Frankfurt consolidate supplier relationships around outcome-based validation packages.
China
Shanghai and Suzhou biomanufacturing clusters generate localized pull for pre-sterilized fluid handling systems. NMPA alignment with ICH Q5A viral safety guidelines harmonizes entry requirements for multinational assembly suppliers. Domestic vaccine producers expand disposable filtration capacity under centralized procurement incentives.
India
CDSCO manufacturing incentives and PLI scheme subsidies attract multinational biotech investment to Hyderabad and Bangalore. Virgin demand for disposable filtration systems emerges as contract manufacturers build greenfield capacity. Imported gamma-irradiated components dominate current supply, creating procurement bottlenecks during validation cycles.
Switzerland
Swissmedic oversight of sterile manufacturing reinforces Basel-region demand for closed-system disposable designs. Specialized resin supply relationships concentrate among polymer converters serving Roche and Novartis affiliate networks. Precision film engineering capabilities anchor local supplier differentiation in high-value bioreactor segments.
Single-Use Assemblies Market Key Industry Players
United States producers anchor one tier; German specialists hold differentiated positions in bioreactor engineering. Market structure consolidates around integrated life sciences platforms and focused component suppliers, with validation cost absorption separating sustainable competitors from marginal players. Two strategic archetypes dominate: diversified conglomerates leveraging cross-selling infrastructure, and pure-play bioprocessing specialists embedding film science expertise. Competitive moves concentrate on backward integration into polymer resin supply and captive gamma-irradiation capacity expansion.
Within the integrated platform tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify conglomerate strategies spanning upstream through downstream disposable workflows. Sartorius AG occupies a distinct position as a European specialist anchoring bioreactor design leadership. These three entities represent the primary competitive anchors shaping procurement standards for contract manufacturing organizations.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Sartorius AG |
| Merck KGaA |
| Danaher Corporation |
| Avantor Inc. |
| Corning Incorporated |
| Entegris |
| Saint-Gobain |
| Lonza |
| Others |
Cost & Logistics Intelligence
EMA Annex 1 sterile manufacturing mandates gate qualified supply access and premium-tier pricing power for gamma-irradiated assembly suppliers serving European bioprocessing facilities. Buyers absorbing validation cost burdens compress margins on standard tubing while extractables-tested bioreactor films command sustained premiums.
Pricing Analysis
Volume concentrates in commodity tubing while margins pool in validated bioreactor systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA-qualified film suppliers from regional converters and catalog distributors. Price differentiation rests on gamma-irradiation certification tier and in-house analytical capabilities. Cost compression in standard bag segments intensifies because CMO consortiums consolidate purchasing power, while biotech firms show least price sensitivity for cell-line-customized configurations.
Supply Chain Analysis
FDA and EMA qualification protocols gate supplier entry before geographic concentration determines fulfillment economics. Medical-grade polypropylene feedstock draws from United States, Germany, and Saudi Arabian resin producers, with specialized gamma-irradiation capacity anchoring in United States and European contract sterilization networks. Single-source vulnerability concentrates in ethylene vinyl alcohol barrier film supply from Asian converters. Distribution runs through direct vendor-managed inventory at multi-site CDMO networks and distributor stocking programs for emerging biotechs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gamma-irradiation sterilization capacity scarcity props pricing power for qualified suppliers while constraining new entrant scale-up. This bottleneck intensifies as mammalian cell therapy manufacturing expands faster than validation throughput.
For Market Incumbents: Anticipate CMO purchasing consortium consolidation by securing captive gamma-irradiation capacity in Germany and United States manufacturing corridors. Absorb extractables testing burdens through in-house analytical chemistry investments to defend margin position against emerging film converters. Prioritize backward integration into medical-grade resin supply relationships as polymer feedstock volatility threatens cost structures. For New Entrants and Emerging Players: Regional CDMOs in India and emerging biotechs in cell and gene therapy represent the most penetrable demand pools underserved by incumbent validation timelines. Target viral vector production workflows where smaller batch sizes and higher changeover frequency favor agile disposable system suppliers. Build go-to-market traction through partnership with specialized cell therapy CDMOs seeking alternative qualified supply sources. For Investors and Strategic Acquirers: CDMO announcements of multi-site preferred supplier consolidations are the leading indicator that qualification risk transfer to vendors is accelerating competitive shakeout. Long-term viability across the analysis window favors assembly suppliers with integrated film science capabilities and established FDA master files. Target acquisition profiles center on mid-scale converters possessing gamma-irradiation relationships and mammalian cell culture application expertise.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gamma-Irradiation Capacity Expansion | Secures sterilization throughput for EMA Annex 1 qualified supply commitments to German CMO networks. |
| In-House Extractables Testing Laboratory | Compresses FDA qualification timelines for novel multi-layer film bioreactor designs. |
| Medical-Grade Resin Supply Agreement | Locks polypropylene feedstock pricing through volatility cycles in petrochemical markets. |
| Cell and Gene Therapy Application Development | Captures viral vector production demand from emerging biotechs in Boston and San Francisco clusters. |
| Indian CDMO Distribution Partnership | Establishes local validation support for PLI scheme subsidized greenfield biomanufacturing capacity. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with bioprocess engineers, CMO procurement directors, regulatory affairs specialists, and gamma-irradiation facility operators combined with FDA 483 inspection databases, EMA manufacturing authorization records, and import-export manifests. Bottom-up assembly volume estimates triangulated against top-down biologics capacity expansion announcements.
Data-stream reconciliation across supplier shipment records, CMO capital expenditure disclosures, and resin producer sales data informed the analytical framework. Segmentation modeling spanned product type, end-user scale tier, application process stage, and material formulation across the projection horizon. CAGRs derived from weighted capacity build-out schedules and regulatory approval timelines for mammalian cell therapy assets.
Caveats apply where FDA extractables protocol revisions or EMA plasticizer restrictions could materially shift the outlook. Forecasts reflect assumptions on gamma-irradiation capacity expansion rates and CMO consolidation trajectories. A model refresh is warranted upon material change in sterilization validation backlogs or polymer feedstock supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Quadripodal Implants Market
Medical Devices
Wearable Medical Technology Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Coated Endotracheal Tube Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Allografts Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Global Ureteroscopes Market
Medical Devices
Endoscope Flushing Pumps Market
Medical Devices
Cardiac Implants Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Self-Destructing Syringe Market