
 Global Ultrasound Devices Market | 2026-2036
Global Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultrasound Devices Market Outlook
Aftermarket service revenue is fragmenting across independent service organizations and original equipment manufacturers, eroding historical margin concentration. GE Healthcare sustains one of the largest installed bases through long-term service contracts and predictive maintenance platforms. Koninklijke Philips N.V. leverages its digital ecosystem to integrate ultrasound hardware with enterprise imaging workflows. Siemens Healthineers differentiates through advanced visualization packages that command premium positioning in cardiology and interventional suites.
Ultrasound devices generate acoustic images through piezoelectric transducers operating at frequencies between two and eighteen megahertz, with beamforming algorithms processing reflected echoes into real-time anatomical visualizations for non-invasive diagnostic and therapeutic guidance. Diagnostic ultrasound systems occupy the largest revenue pool given their ubiquity across radiology departments, while portable ultrasound segments are expanding fastest as battery-powered handheld units penetrate ambulatory settings and resource-limited environments. Digital ultrasound technology leads replacement cycles as analog architectures face obsolescence, and 4D ultrasound commands elevated margins in obstetrics applications where spatiotemporal rendering drives clinical purchasing decisions.
The FDA governs device safety and effectiveness through 510(k) and premarket approval pathways, while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements for ultrasound systems marketed in Europe. China's NMPA accelerates local product registrations through innovation fast-tracks, compressing time-to-market for domestic manufacturers. Stakeholders must monitor how divergent regulatory timelines across Washington, Brussels, and Beijing reshape competitive access and service model economics.
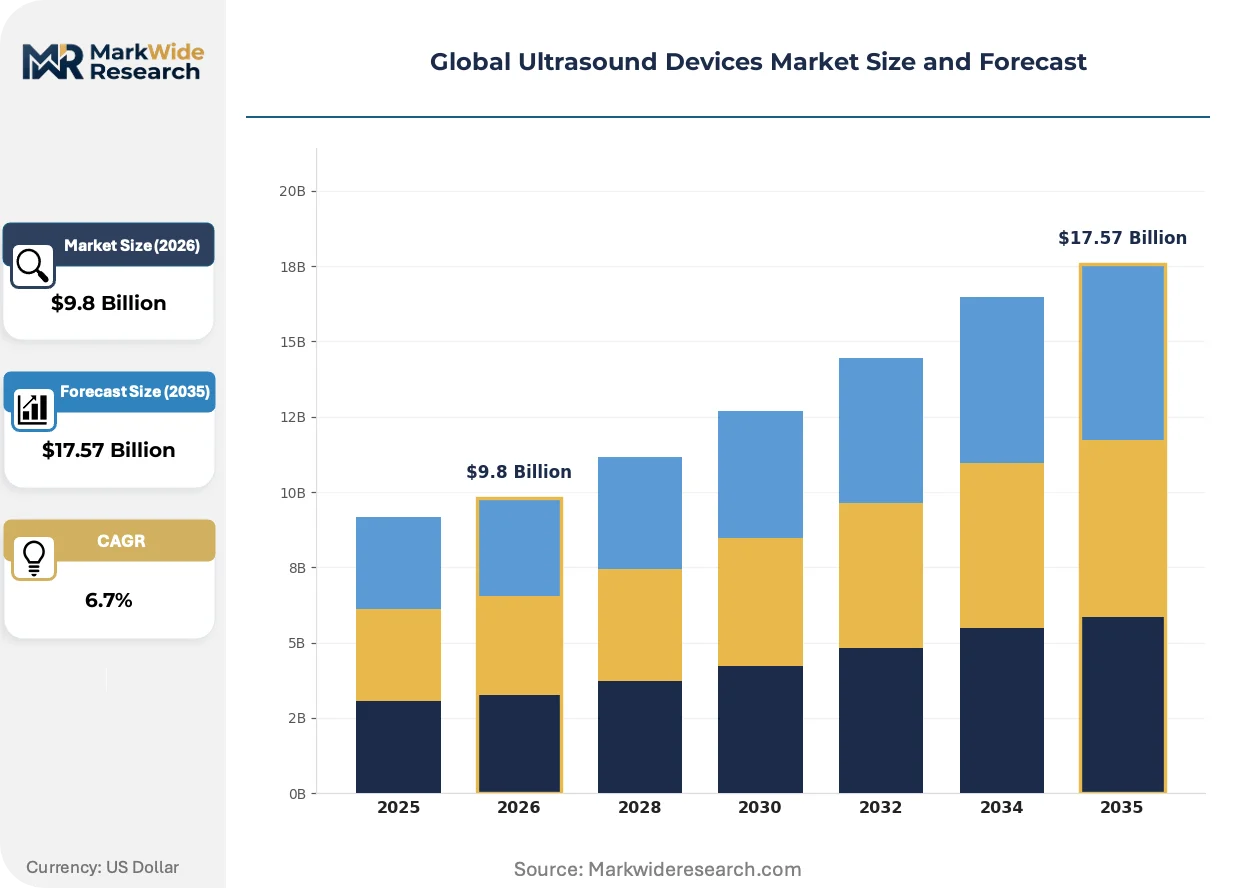
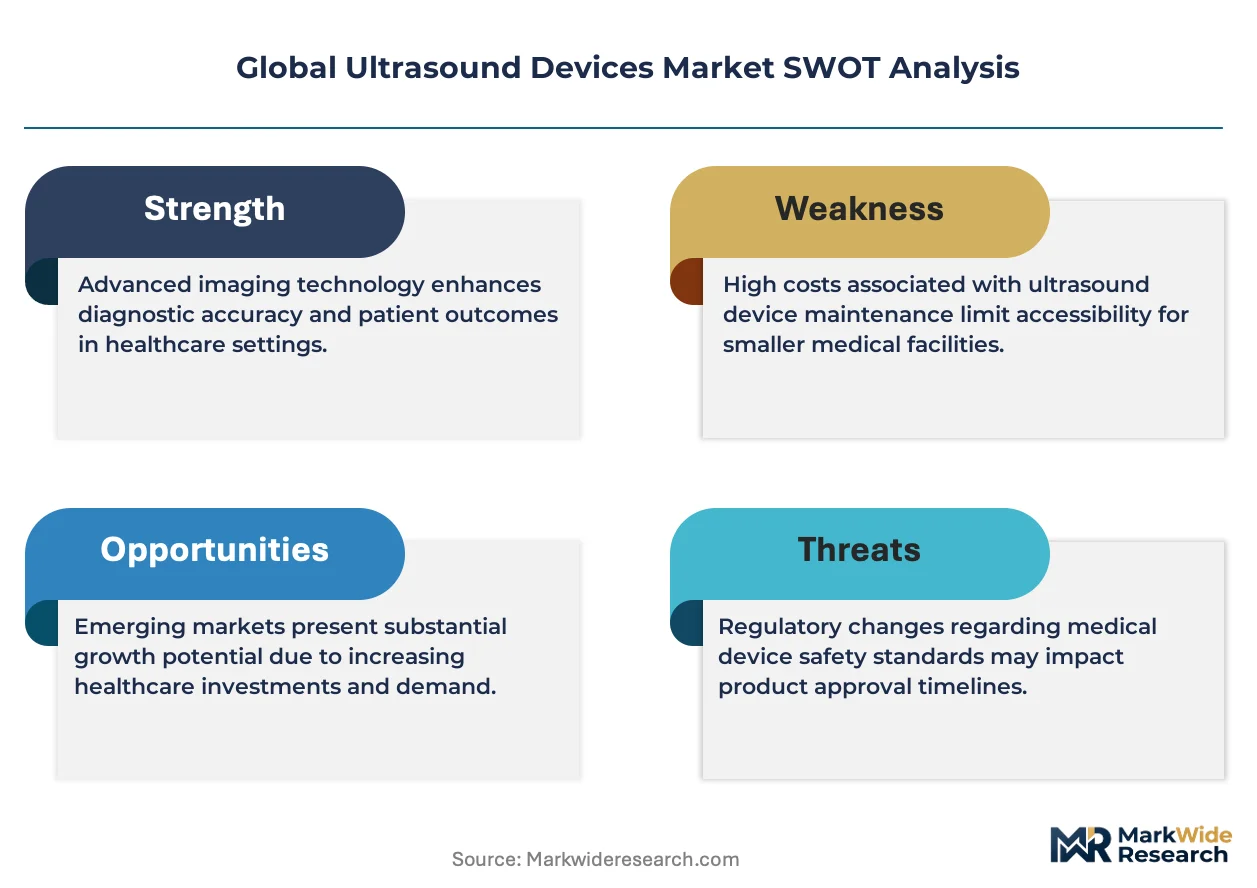
Market Dynamics
AI-enabled diagnostic software is compressing traditional hardware upgrade cycles as hospitals prioritize software-augmented imaging capabilities over pure transducer specifications.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined clearances for AI-embedded ultrasound algorithms shorten product launch timelines from 18 months to under 9 months, incentivizing R&D investment in machine learning overlays.
- Emergency department point-of-care protocols:Triage workflows in US and Chinese trauma centers now mandate bedside ultrasound for FAST examinations, institutionalizing handheld system procurement.
- Lithium-silicon battery chemistry:Energy density improvements enable 4-hour continuous scanning in portable units, eliminating tethered power constraints for rural deployment.
Market Restraints
- Piezoelectric ceramic supply concentration:Lead zirconate titanate crystal production clusters in Jiangsu province, exposing manufacturers to single-source geopolitical disruption.
- EMA MDR clinical evidence thresholds:Stricter post-market surveillance requirements for Class IIa ultrasound devices extend European registration timelines and inflate documentation costs.
- CT and MRI substitution in oncology staging:Cross-sectional modalities capture complex abdominal and pelvic cancer assessments previously referred to ultrasound.
Strategic Opportunities
- India's Ayushman Bharat health infrastructure:Government-funded primary health centers require 150,000 diagnostic devices by 2030, creating procurement windows for cost-optimized cart systems.
- Shear wave elastography fusion:Combination with B-mode imaging enables non-invasive liver fibrosis staging, opening hepatology departments as new ultrasound purchasers.
- Tele-interpretation platforms:Cloud-based specialist access allows general practitioners in Brazil's Amazonas state to deploy handheld units with remote cardiologist validation.
Industry Challenges
- Sonographer workforce shortages:The American Registry for Diagnostic Medical Sonography reports unfilled positions exceeding 7,000 in the US, constraining equipment utilization rates.
- Legacy PACS integration friction:Hospital information systems built on DICOM 3.0 variants resist seamless AI-ultrasound data flows, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultrasound Devices Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Ultrasound, Therapeutic Ultrasound, Portable Ultrasound, 3D Ultrasound End User: Hospitals, Clinics, Diagnostic Centers, Home Healthcare Technology: Analog Ultrasound, Digital Ultrasound, 4D Ultrasound, Contrast Ultrasound Application: Obstetrics, Cardiology, Abdominal Imaging, Musculoskeletal |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Siemens Healthineers, Canon Medical Systems Corporation, Mindray Medical International Limited, FUJIFILM Holdings Corporation, Samsung Medison, Esaote, Hitachi Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultrasound Devices Market Strategic Shifts
Computational beamforming and edge AI deployment are redefining performance benchmarks, separating vendors who control full imaging stacks from those dependent on third-party processors.
Single-chip CMUT transducers are replacing conventional piezoelectric arrays in premium cardiology systems. Philips and Samsung Medison manufacturing lines in Best, Netherlands and Seoul, South Korea now dedicate 40% of wafer capacity to capacitive micromachined designs. This semiconductor fabrication approach is digitizing acoustic signal processing at the element level, collapsing analog front-end component counts by 60%.
China's NMPA innovation fast-track designation compresses Class II device review from 18 months to 90 days for domestically manufactured AI-ultrasound systems. Shenzhen and Suzhou regulatory bureaus process 70% of national submissions, concentrating compliance expertise in these municipalities. Domestic manufacturers Mindray and Sonoscape exploit this acceleration to outpace multinational rivals in provincial hospital tenders.
Hospital procurement committees now unbundle hardware acquisition from service contracts, soliciting independent service organization bids for preventive maintenance. This disintermediation pressures original equipment manufacturer margin structures in Germany and Japan, where multi-year service agreements historically contributed 35% of lifetime revenue. Academic medical centers in Munich and Tokyo lead this contractual fragmentation.
Global Ultrasound Devices Market Segmentation
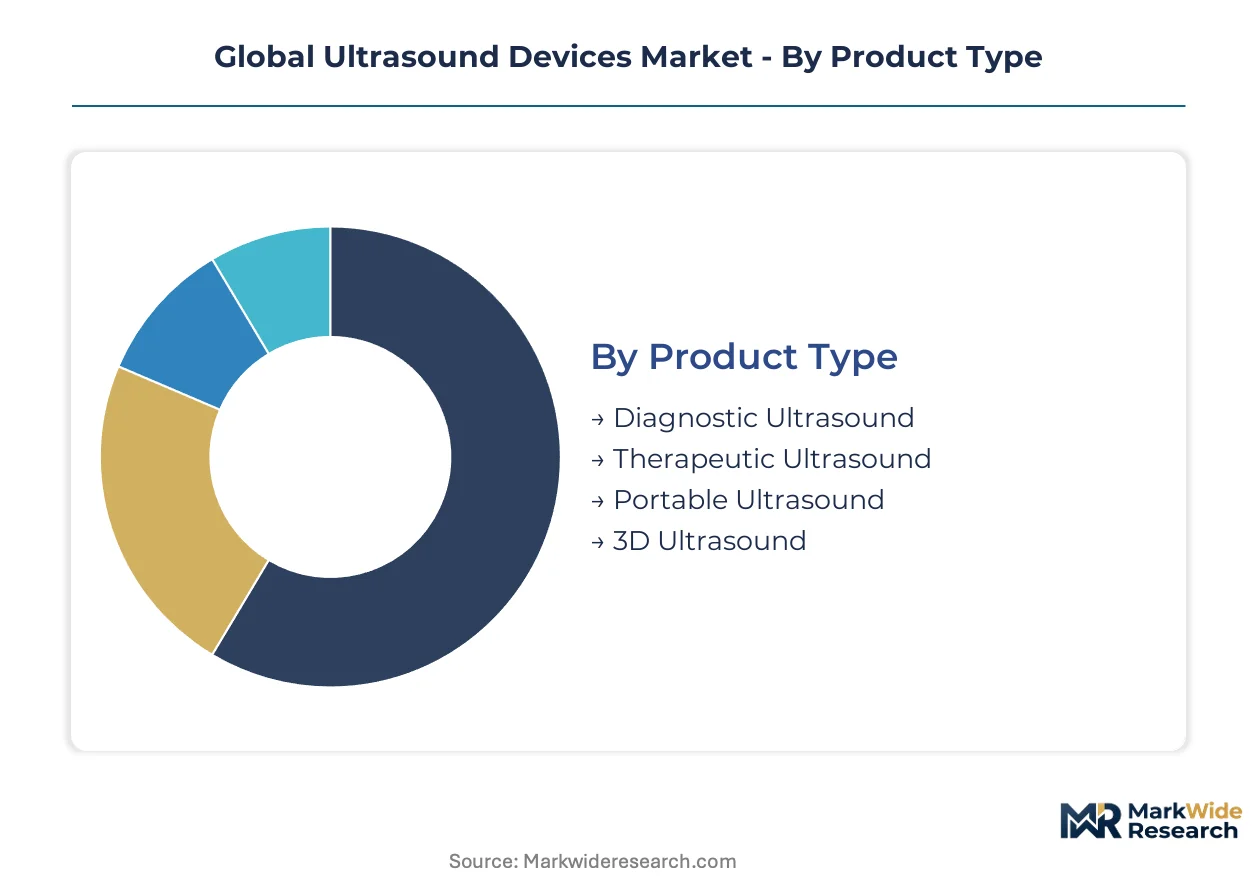
Ultrasound device procurement patterns diverge sharply across product architectures and clinical settings. Replacement cycles, margin structures, and regulatory pathways vary by segment, requiring vendors to calibrate portfolio investments against distinct demand rhythms.
Product Type:
Diagnostic systems turn over every 7-9 years in mature markets while portable units refresh in 3-5 year cycles as battery and AI capabilities leapfrog.
- Diagnostic Ultrasound:Cart-based systems with 128-512 channel beamformers anchor radiology department workflows. Demand concentrates in Chinese provincial hospitals upgrading from analog platforms, driven by government diagnostic capacity expansion mandates.
- Portable Ultrasound:Battery-powered handheld units weighing under 2kg enable point-of-care deployment. Emergency departments in US trauma centers and India's Ayushman Bharat primary health centers are driving procurement volumes as bedside protocols standardize.
- Therapeutic Ultrasound:Focused acoustic energy devices for tissue ablation and drug delivery.
- 3D Ultrasound:Volume rendering systems reconstructing tomographic slices from 2D image stacks.
Diagnostic Ultrasound dominates installed base. Portable Ultrasound is where expansion concentrates.
End User:
Capital allocation cycles separate institutional purchasers with depreciation schedules from cash-pay operators optimizing unit economics.
- Hospitals:Integrated delivery networks with centralized procurement committees negotiate enterprise imaging contracts. Academic medical centers in Germany and Japan are unbundling hardware from service agreements, fragmenting vendor revenue streams.
- Clinics:Ambulatory settings prioritize lease financing and cloud-connected devices to minimize capital outlay. Brazilian primary care clinics in São Paulo state deploy handheld units with tele-interpretation support from cardiology hubs.
- Diagnostic Centers:Independent imaging chains optimizing throughput per square meter.
- Home Healthcare:Post-acute monitoring and chronic disease management applications.
Hospitals command the largest revenue pool. Clinics are gaining share fastest as outpatient migration accelerates.
Technology:
Semiconductor architecture choices determine upgrade elasticity and software augmentation potential.
- Digital Ultrasound:Fully digitized signal chains with software-defined beamforming. Replacement demand concentrates in European markets where EMA MDR compliance deadlines are forcing analog system retirements.
- 4D Ultrasound:Real-time volumetric acquisition with spatiotemporal rendering. Obstetrics departments in US and Chinese metropolitan hospitals pay premium positioning for fetal cardiac assessment capabilities.
- Analog Ultrasound:Legacy discrete component architectures facing obsolescence.
- Contrast Ultrasound:Microbubble-enhanced perfusion imaging for liver and renal characterization.
Digital Ultrasound leads replacement cycles. 4D Ultrasound commands the steepest expansion trajectory in premium obstetrics.
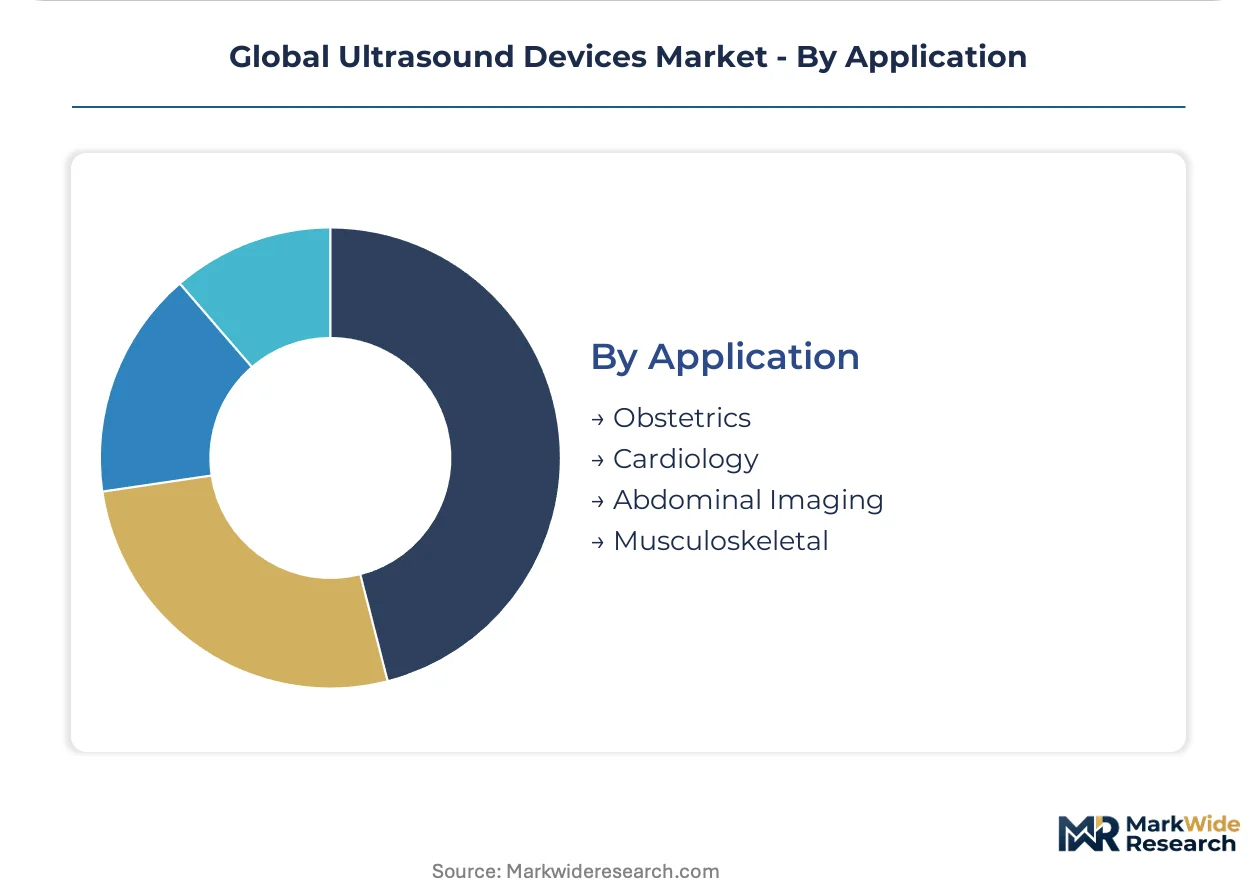
Application:
Clinical utility depth and reimbursement density vary across anatomical specialties, shaping R&D prioritization.
- Obstetrics:First-trimester screening and fetal anomaly detection represent the largest installed base segment. Chinese maternal health programs and US perinatal quality initiatives sustain demand for high-resolution systems.
- Cardiology:Echocardiography and stress echo protocols require specialized transducer arrays. Shear wave elastography fusion is opening hepatology departments as adjacent purchasers for fibrosis staging.
- Abdominal Imaging:Generalist radiology workhorse applications facing CT substitution pressure in oncology staging.
- Musculoskeletal:Sports medicine and rheumatology point-of-care guidance for injections and tendon assessment.
Obstetrics anchors historical revenue. Cardiology is where technology premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys ultrasound devices as primary diagnostic workhorses in provincial hospitals, whereas US health systems concentrate them in emergency departments and obstetrics suites as point-of-care tools. Germany and Japan maintain longer replacement cycles through rigorous preventive maintenance cultures. India's procurement emphasizes cost-optimized cart systems for primary care scale-out.
United States
Emergency department FAST protocols and maternal-fetal medicine drive handheld and 4D system demand. FDA 510(k) clearances for AI-embedded algorithms compress product launch timelines to under nine months. Boston and Minneapolis medical device clusters host development operations for computational beamforming platforms.
China
Provincial hospital diagnostic capacity expansion mandates and domestic manufacturer scale-up fuel cart-based system procurement. NMPA innovation fast-tracks compress Class II device review from eighteen months to ninety days for domestically manufactured AI-ultrasound systems. Shenzhen and Suzhou regulatory bureaus process seventy percent of national submissions, concentrating compliance expertise.
Germany
Academic medical center enterprise imaging contracts and unbundled service procurement reshape vendor economics. EMA MDR clinical evidence thresholds extend European registration timelines and inflate documentation costs for Class IIa devices. Munich hospital procurement committees lead contractual fragmentation away from multi-year OEM service agreements.
Japan
Long-term depreciation schedules and predictive maintenance platforms sustain extended replacement cycles. METI industrial standards and PMDA device approvals govern market access for imported and domestic systems. Tokyo academic medical centers pioneer unbundled hardware-service contracting, pressuring historical OEM margin structures.
India
Ayushman Bharat primary health center mandates require one hundred fifty thousand diagnostic devices by 2030. CDSCO medical device regulations govern import and local manufacturing compliance pathways. Maharashtra and Karnataka state health departments drive tender processes for cost-optimized cart-based ultrasound deployment.
Global Ultrasound Devices Market Competitive Environment
Capability concentration sits with full-stack imaging vendors; scale advantage sits with diversified health technology conglomerates. The vendor landscape separates into three tiers: integrated diagnostic imaging platforms, specialized ultrasound pure-plays, and emerging domestic champions in regulated Asian markets. Consolidation pressure operates through AI software acquisitions and service contract disintermediation. Geographic expansion into India's primary care infrastructure and backward integration into CMUT semiconductor fabrication represent dominant competitive vectors.
Among diversified health technology conglomerates, GE Healthcare, Koninklijke Philips N.V., and Siemens Healthineers exemplify integrated platform strategies that bind hardware, software, and service ecosystems. These entities occupy positions where predictive maintenance platforms and enterprise imaging workflow integration command premium positioning. Domestic champions Mindray Medical International Limited and Samsung Medison represent the emerging tier capitalizing on NMPA fast-track advantages and provincial hospital tender capture in China. Specialized pure-plays including Canon Medical Systems Corporation and FUJIFILM Holdings Corporation sit within focused diagnostic imaging segments where visualization package differentiation sustains margin structures against diversified rivals.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Mindray Medical International Limited |
| FUJIFILM Holdings Corporation |
| Samsung Medison |
| Esaote |
| Hitachi Medical Corporation |
| Others |
Value Chain & Pricing Dynamics
Lead zirconate titanate crystal production clusters in Jiangsu province concentrate transducer feedstock supply, anchoring margin capture in downstream transducer assembly and OEM service bundling rather than raw piezoelectric material trading.
Pricing Analysis
Long-term service contracts dominate hospital procurement, though unbundling trends fragment these into discrete hardware and preventive maintenance agreements. Price differentiation rests on AI-embedded software tiers and FDA 510(k) clearance status, with academic medical centers showing lowest sensitivity due to enterprise imaging integration requirements. Cost compression in portable segments intensifies as domestic Chinese manufacturers scale CMUT production. Clinics and primary health centers exhibit highest price sensitivity, prioritizing lease financing over capital purchase.
Supply Chain Analysis
Piezoelectric ceramics draw from China, Japan, and Germany, with lithium-silicon battery cells sourcing from South Korea and China. CMUT semiconductor fabrication feeds from Netherlands and South Korea wafer capacity. Single-source vulnerability concentrates in Jiangsu province ceramic processing. Distribution runs through OEM direct sales for hospital systems and medical device distributors for ambulatory settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The installed base concentration and FDA regulatory entrenchment create substantial switching costs that defend incumbent positioning against software-augmented disruption.
For Market Incumbents: Pre-empt service contract disintermediation by embedding predictive maintenance platforms directly into hardware lease structures, countering independent service organization encroachment. Accelerate backward integration into CMUT wafer capacity to secure semiconductor supply against foundry allocation constraints.
For New Entrants and Emerging Players: Build out tele-interpretation-enabled handheld deployments in Brazil's Amazonas state and India's Ayushman Bharat primary health centers, exploiting regulatory fast-tracks and remote validation protocols. Partner with provincial hospital networks in China to bypass entrenched OEM service relationships.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ultrasound pure-plays holding specialized visualization packages in cardiology and obstetrics segments. Five-to-ten year viability hinges on AI software stack control rather than hardware differentiation. Monitor NMPA innovation fast-track designation velocity as inflection indicator for domestic manufacturer competitive acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Diagnostic Software Development | FDA 510(k) clearance compresses launch timelines and commands premium positioning in emergency departments. |
| CMUT Semiconductor Fabrication Scale-Up | Wafer capacity in Netherlands and South Korea digitizes signal processing and collapses analog component counts. |
| Tele-Interpretation Platform Integration | Cloud-based specialist access enables handheld deployment in resource-limited environments with remote validation. |
| Hospital System Partnership Expansion | Enterprise imaging workflow integration binds hardware procurement to long-term service ecosystems. |
| Reimbursement Strategy Optimization | Shear wave elastography fusion opens hepatology departments through non-invasive liver fibrosis staging protocols. |
Study Parameters
Operator-level perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and clinical sonographers anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) filings, NMPA registration databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up installed base modeling and top-down market sizing triangulated volume estimates.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated AI adoption pathways over the projection horizon. Segmentation dimensions modeled include product architecture, end-user setting, semiconductor technology tier, and clinical application specialty. CAGRs derived from replacement cycle analysis and provincial hospital capacity expansion mandates. Forecast inputs incorporated NMPA fast-track velocity and EMA MDR compliance cost inflation.
Stress conditions across piezoelectric ceramic supply disruption, sonographer workforce shortage persistence, and CT substitution rates in oncology staging were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against hospital capital expenditure surveys and medical device import trade data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Trauma Devices Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
Implantable Defibrillators Market
Medical Devices
Massage Equipment Market
Medical Devices
Pharmaceutical Robots Market
Medical Devices
Otoscope Devices Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Craniomaxillofacial Devices Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
North America Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Global Intraoperative Neuromonitoring (IONM) Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
North America 3D Printing in Healthcare Market
Medical Devices
Global Anastomosis Devices Market