
 Global Hydrogel Based Drug Delivery System Market | 2026-2036
Global Hydrogel Based Drug Delivery System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydrogel Based Drug Delivery System Market Intelligence
Profitability from bulk, non-functionalized hydrogel production is narrowing as value shifts toward customized, stimuli-responsive formulation services for targeted therapies. Johnson & Johnson leverages its extensive R&D capabilities to develop advanced drug-eluting contact lenses and implants for various medical fields. Ocular Therapeutix specializes in ophthalmic applications, creating sustained-release therapies for complex eye diseases like glaucoma. Medtronic competes through its expertise in implantable devices, integrating hydrogel technology for localized drug delivery in chronic conditions.
A hydrogel based drug delivery system consists of a three-dimensional network of hydrophilic polymers capable of absorbing large amounts of water or biological fluids. These biocompatible structures are engineered to encapsulate and release therapeutic agents in a controlled, predictable manner over an extended period. Injectable hydrogels represent the fastest-growing product type due to their minimally invasive nature and ease of administration in outpatient clinical settings. Within therapy areas, oncology applications command significant R&D investment, while hospitals remain the dominant end-user channel for these advanced delivery systems.
Regulatory oversight from bodies like the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) dictates stringent requirements for biocompatibility, sterility, and clinical efficacy data. In parallel, China's National Medical Products Administration (NMPA) has established specific guidelines for novel drug delivery platforms, influencing market access strategies for multinational firms. Future success depends on navigating the complex intellectual property landscape for stimuli-responsive polymers and securing strategic partnerships for late-stage clinical development.
Market Dynamics
The central structural force shaping the market is the technological pivot from inert, bulk hydrogels toward intelligent, stimuli-responsive polymers. This shift enables precision drug delivery for complex therapeutic areas like oncology, fundamentally altering value creation and R&D priorities.
Growth Catalysts
- Stimuli-Responsive Polymers:Innovations in polymers that respond to specific biological cues like pH or temperature are enabling the development of highly targeted therapies, particularly for solid tumors where controlled, localized drug release is critical for efficacy and minimizing side effects.
- Aging Demographics:Expanding elderly populations in developed economies such as Japan and Germany are increasing the prevalence of chronic diseases like glaucoma and osteoarthritis, spurring demand for long-acting, sustained-release formulations that improve patient compliance.
- Regulatory Streamlining:The U.S. FDA's guidance for combination products provides a clearer development pathway for drug-eluting devices and implants. This clarity reduces regulatory uncertainty for manufacturers, encouraging investment in novel hydrogel-based systems.
Market Restraints
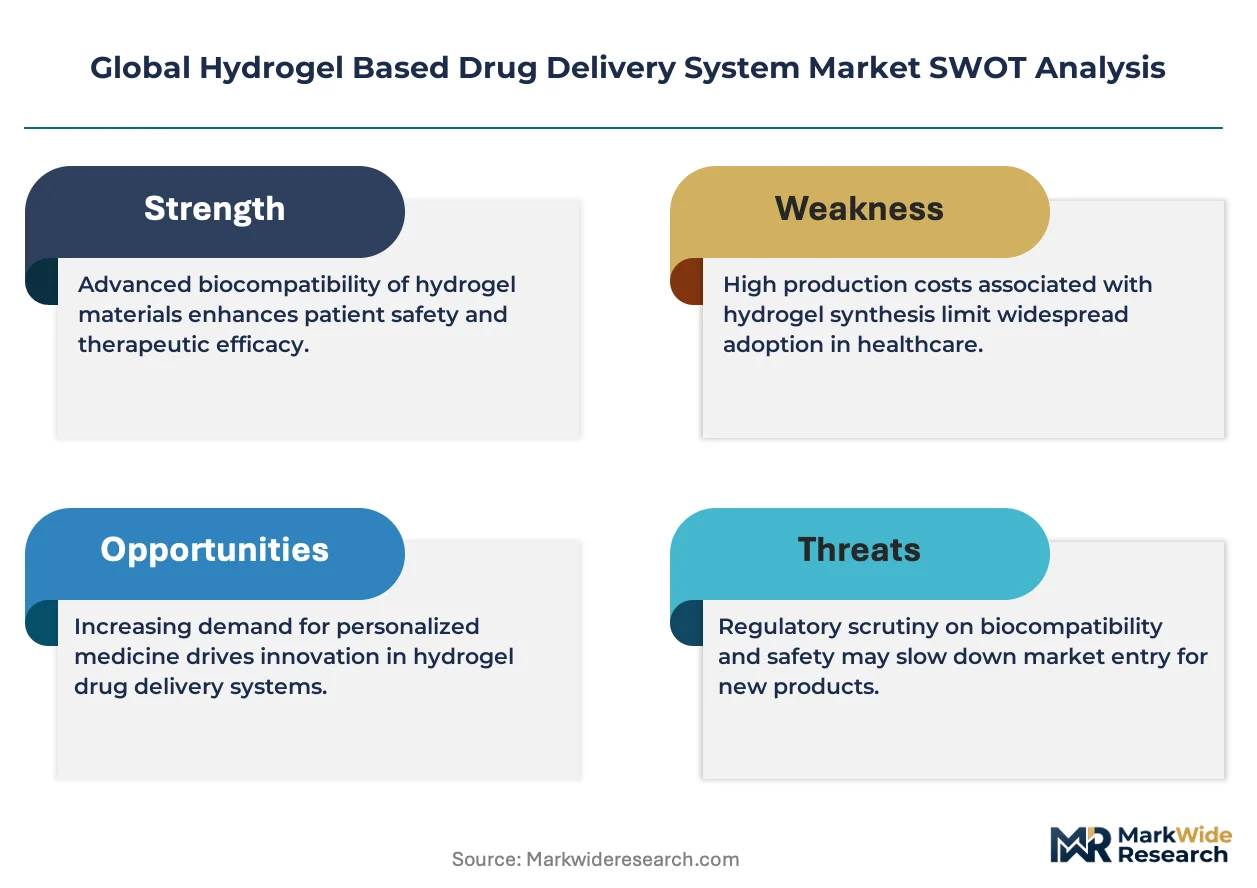
- High Manufacturing Costs:The synthesis and purification of advanced, functionalized polymers are complex and expensive processes. These high input costs translate to premium product pricing, limiting adoption in more cost-sensitive healthcare systems and for non-specialty applications.
- Biocompatibility and Degradation Hurdles:Ensuring long-term biocompatibility and predictable in-vivo degradation rates remains a significant technical barrier. Unpredictable material behavior can lead to adverse immune responses or inconsistent drug release, complicating clinical development.
- Stringent Efficacy Data Requirements:Regulatory bodies, including the European Medicines Agency (EMA), mandate extensive clinical data to prove the safety and efficacy of novel delivery systems. This requirement results in prolonged and costly development timelines before market approval.
Strategic Opportunities
- Regenerative Medicine Applications:The use of hydrogels as scaffolds for tissue engineering and cell encapsulation presents a significant high-value opportunity. These platforms can support cell growth and deliver therapeutic agents to promote tissue repair and regeneration.
- 3D Bioprinting Integration:Combining hydrogel bio-inks with 3D printing technology allows for the creation of patient-specific, drug-eluting implants and tissue constructs. This convergence enables unprecedented customization for complex anatomical and therapeutic needs.
- Emerging Market Penetration:Underpenetrated healthcare markets in Brazil and India offer substantial growth potential. As local biopharmaceutical research capabilities and healthcare spending increase, demand for advanced drug delivery technologies is set to expand.
Industry Challenges
- Intellectual Property Complexity:The patent landscape for novel polymers and stimuli-responsive mechanisms is densely populated and litigious. Navigating freedom-to-operate and securing robust IP protection for new formulations is a major operational hurdle for innovators.
- Manufacturing Scale-Up:Transferring hydrogel production from laboratory-scale synthesis to consistent, sterile, commercial-scale manufacturing is a significant technical challenge. Maintaining batch-to-batch consistency and purity at scale requires substantial process engineering expertise and capital investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydrogel Based Drug Delivery System Market |
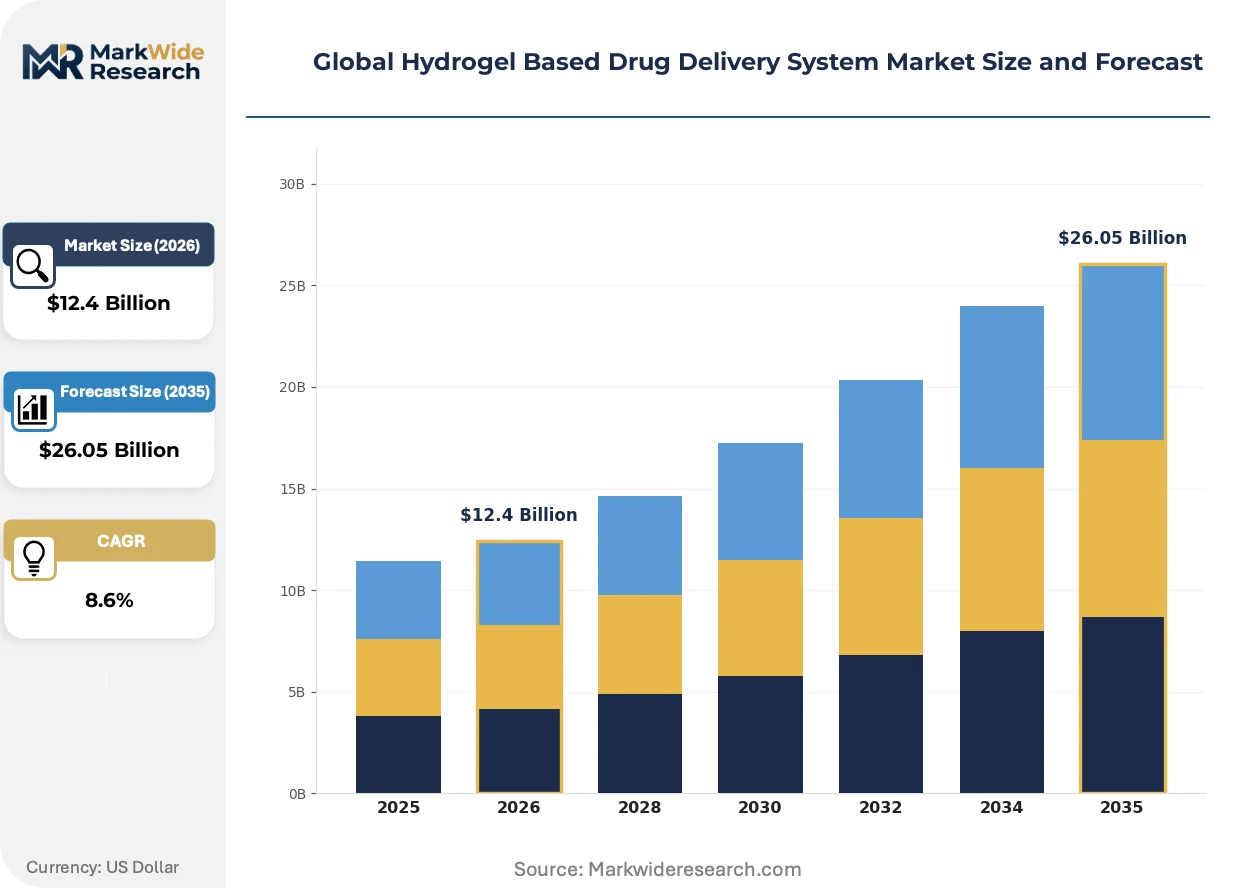
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
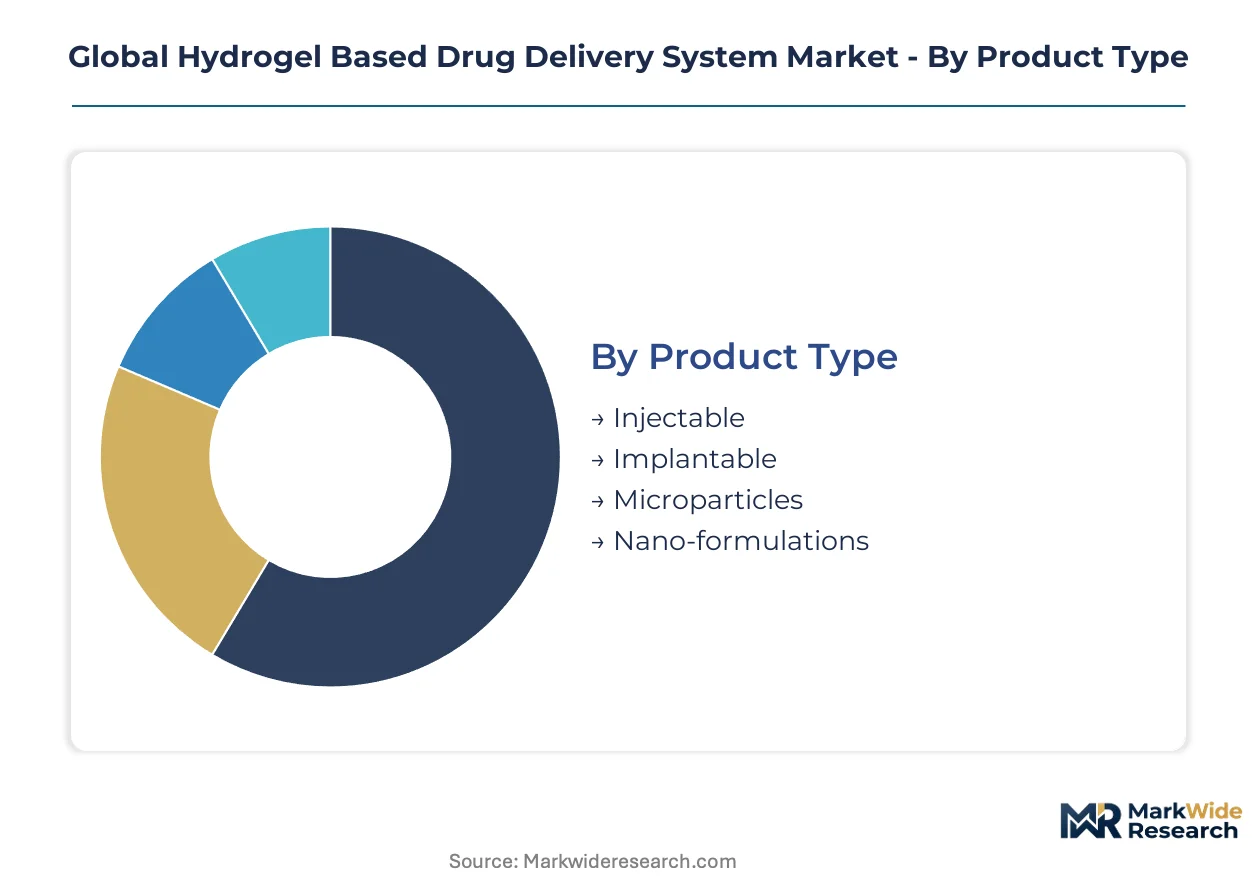
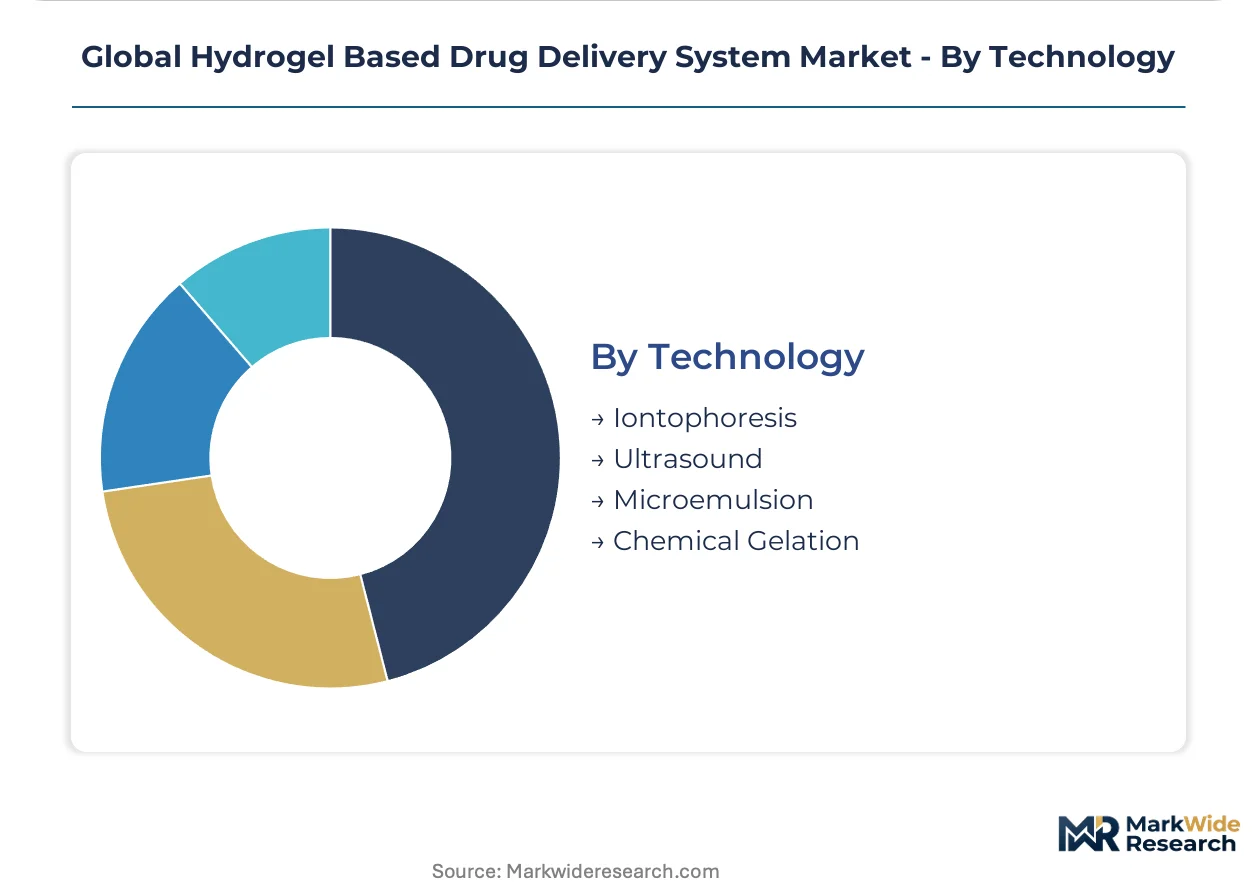
| Segmentation | Product Type: Injectable, Implantable, Microparticles, Nano-formulations Therapy Area: Oncology, Cardiovascular, Neurology, Autoimmune End User: Hospitals, Research Laboratories, Clinics, Home Care Technology: Iontophoresis, Ultrasound, Microemulsion, Chemical Gelation |
| Companies Covered | Johnson & Johnson, Bausch & Lomb, Ocular Therapeutix, Inc., GALDERMA, Medtronic, Blairex Laboratories, Inc., Ferring B.V., Tolmar Pharmaceuticals, Inc., Endo International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydrogel Based Drug Delivery System Market Strategic Shifts & Innovations
Precision and personalization are reshaping the hydrogel drug delivery landscape, steering innovation away from passive carriers toward active, intelligent systems. This evolution is most evident in the development of materials that interact dynamically with their biological environment to optimize therapeutic outcomes.
Multi-stimuli responsive hydrogels, which react to combinations of pH, temperature, and specific enzymes, offer highly precise spatiotemporal control over drug release. Pharmaceutical R&D labs focused on oncology and autoimmune diseases are rapidly adopting these materials in preclinical development. This level of precision is rendering obsolete earlier-generation, single-stimulus hydrogels that offered less targeted therapeutic action and higher risks of off-target effects.
The European Union's Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance requirements for drug-device combination products. This regulation is forcing manufacturers to generate more comprehensive data on biocompatibility and long-term in-vivo performance. Implantable hydrogel systems for orthopedic and cardiovascular applications are most affected, prompting greater investment in robust clinical trial designs to meet the heightened evidentiary standards.
A clear preference is emerging among hospital systems for injectable, in-situ gelling hydrogels over pre-formed implantable systems. This shift disrupts traditional surgical supply chains in favor of products suitable for minimally invasive procedures performed in outpatient clinics. The trend is most pronounced in the United States and Western Europe, where reimbursement policies increasingly favor procedures that reduce inpatient hospital stays and associated costs.
Global Hydrogel Based Drug Delivery System Market Segmentation
Understanding the market for hydrogel based drug delivery systems necessitates a granular segmentation to identify specific value pools and growth trajectories. The diverse applications and technological nuances within this sector influence development priorities and market access strategies. Each segment reflects distinct requirements for material properties and clinical utility.
Product Type:
The intensity of after-sales service and ongoing patient management varies significantly across different product types, influencing the commercialization model for hydrogel based drug delivery systems.
- Injectable:These systems are formulated for minimally invasive administration, often as in-situ gelling solutions that form a hydrogel upon injection into the body. Demand concentrates in outpatient clinical settings in the United States, driven by a preference for reduced hospital stays and lower procedural costs.
- Implantable:Designed for long-term drug release, these pre-formed hydrogel devices are surgically placed to deliver therapeutics over extended periods. Their development often targets chronic conditions, with significant R&D investment in Europe to meet stringent MDR requirements for long-term biocompatibility.
- Microparticles:Hydrogel microparticles encapsulate therapeutic agents, offering controlled release and targeted delivery through various administration routes.
- Nano-formulations:These ultra-small hydrogel carriers enable improved cellular uptake and enhanced bioavailability for potent drug compounds.
Implantable holds the largest share; momentum sits with Injectable.
Therapy Area:
The complexity of the disease application dictates the specific design parameters and regulatory hurdles for hydrogel based drug delivery systems, requiring highly specialized formulations.
- Oncology:Hydrogels provide targeted drug delivery for solid tumors, minimizing systemic toxicity and improving therapeutic indices for cancer treatments. Significant R&D investment in this area focuses on stimuli-responsive materials that enhance localized drug concentrations.
- Cardiovascular:These systems deliver drugs to treat heart disease, including post-infarction repair and anti-restenosis applications, often requiring biocompatible materials for long-term implantation. Patient populations in Germany and Japan drive demand for these chronic disease management solutions.
- Neurology:Hydrogels are explored for localized delivery of neuroprotective agents and treatments for neurodegenerative disorders, navigating the blood-brain barrier.
- Autoimmune:Controlled release hydrogels offer sustained delivery of immunosuppressants or anti-inflammatory drugs, reducing dosing frequency for chronic autoimmune conditions.
Demand for Oncology drives significant investment, while Cardiovascular applications expand rapidly.
End User:
Customer type and the primary access points for patient care profoundly shape the distribution channels and product requirements for hydrogel based drug delivery systems.
- Hospitals:These institutions serve as the primary end-user channel for complex hydrogel based drug delivery systems, particularly for surgical implants and inpatient treatments. High healthcare spending in the United States supports the adoption of advanced hydrogel devices for critical care.
- Clinics:Outpatient clinics increasingly utilize injectable hydrogel systems for minimally invasive procedures and sustained drug release, reducing the need for hospital admissions. This shift is pronounced in Western Europe, where reimbursement policies favor cost-effective outpatient interventions.
- Research Laboratories:Academic and industry research facilities employ hydrogels for preclinical studies, drug screening, and the development of novel delivery platforms.
- Home Care:Emerging applications for hydrogels in home care settings focus on simplified administration and patient-friendly devices for chronic condition management.
The majority of adoption occurs in Hospitals, with increasing penetration in Clinics.
Technology:
The maturity and innovative potential of various technologies determine their integration into hydrogel based drug delivery systems, influencing performance characteristics and market differentiation.
- Chemical Gelation:This fundamental method involves cross-linking polymer chains through chemical reactions to form a stable hydrogel network, often used for bulk production. It forms the basis for many biocompatible hydrogel formulations, with continuous refinement for controlled degradation.
- Iontophoresis:This technique uses a small electric current to enhance the transdermal delivery of charged drug molecules encapsulated within hydrogels. Demand for this non-invasive approach is notable in dermatology and pain management applications.
- Ultrasound:External ultrasound can trigger drug release from responsive hydrogels, offering a non-invasive method for on-demand therapeutic delivery.
- Microemulsion:Hydrogels formed from microemulsions offer enhanced drug solubilization and controlled release properties, particularly for hydrophobic active pharmaceutical ingredients.
While Chemical Gelation remains foundational, advanced applications leverage Iontophoresis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The supply-side concentration for hydrogel based drug delivery systems emphasizes regions with advanced biopharmaceutical research and high healthcare spending. The United States notably drives demand and innovation, particularly in outpatient clinical settings. This market structure influences global R&D priorities and commercialization strategies.
United States
The United States exhibits strong demand for injectable hydrogel systems due to advanced biopharmaceutical research and high healthcare spending. The U.S. FDA's guidance for combination products provides a clear regulatory pathway for novel drug-eluting devices. The Boston-Cambridge biotech hub actively develops new hydrogel systems for targeted therapies.
Germany
Germany's healthcare system generates demand for long-acting, sustained-release formulations, driven by an expanding elderly population and chronic disease prevalence. The European Medicines Agency (EMA) mandates extensive clinical data for novel delivery systems, influencing product development. Bavaria's pharmaceutical sector drives investment in advanced hydrogel solutions.
Japan
Japan faces increasing demand for chronic disease management solutions due to its aging demographics, particularly in cardiovascular and neurological applications. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures rigorous product safety and efficacy standards for new therapies. Tokyo's research institutions collaborate on neuroprotective hydrogel development.
China
China's biopharmaceutical sector shows significant growth potential for advanced drug delivery technologies, supported by increasing local research capabilities and healthcare spending. The National Medical Products Administration (NMPA) has established specific guidelines for novel drug delivery platforms. Shanghai's biopharma parks attract multinational firms for market access strategies.
India
Emerging markets like India offer substantial growth potential for hydrogel based drug delivery systems, driven by an underpenetrated healthcare market and rising biopharmaceutical research. The Central Drugs Standard Control Organization (CDSCO) oversees drug delivery system approvals and market entry. Hyderabad's Genome Valley fosters innovation in hydrogel microparticle development.
Global Hydrogel Based Drug Delivery System Market Key Industry Players
Large diversified pharmaceutical firms and specialized medical device manufacturers split the market for hydrogel based drug delivery systems. This structure reflects a competitive environment where extensive R&D capabilities and niche therapeutic focus both create value. Strategic partnerships and portfolio diversification represent common competitive moves among market participants.
Diversified healthcare conglomerates, such as Johnson & Johnson, anchor the market with extensive R&D capabilities, developing advanced drug-eluting contact lenses and implants across various medical fields. These players often pursue portfolio diversification to address a wide range of therapeutic areas. Specialized medical device manufacturers, including Medtronic, occupy a significant position through expertise in implantable devices, integrating hydrogel technology for localized drug delivery in chronic conditions. Ocular Therapeutix further exemplifies niche specialization, focusing on ophthalmic applications and creating sustained-release therapies for complex eye diseases like glaucoma. These focused firms often secure strategic partnerships to accelerate late-stage clinical development.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Bausch & Lomb |
| Ocular Therapeutix, Inc. |
| GALDERMA |
| Medtronic |
| Blairex Laboratories, Inc. |
| Ferring B.V. |
| Tolmar Pharmaceuticals, Inc. |
| Endo International plc |
| Others |
Cost & Logistics Intelligence
Undercapacity in advanced stimuli-responsive polymer synthesis drives premium pricing and strategic supplier behavior in the hydrogel drug delivery market. This utilization imbalance influences both R&D investment and market entry strategies.
Pricing Analysis
The U.S. FDA's guidance dictates the pricing tier structure for novel drug-eluting devices and combination products. Value-based pricing models dominate, reflecting therapeutic efficacy and R&D investment in advanced hydrogel systems. Customization for patient-specific applications and regulatory approval drive significant price differentiation. Pricing pressure stems from high manufacturing costs, limiting adoption in cost-sensitive healthcare systems, where hospitals show lower sensitivity for complex implants than clinics for injectable solutions.
Supply Chain Analysis
Specialized contract manufacturers in the United States and Germany hold significant capacity for advanced hydrogel production. Supply concentration for critical raw materials like stimuli-responsive polymers often originates from specialized chemical producers in China and India. The supply chain faces single-source vulnerability for highly specialized polymer inputs, complicating scale-up and market access. Distribution primarily runs through direct channels to hospitals and specialized outpatient clinics for both implantable and injectable systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogel based drug delivery market is undergoing a platform-economics inflection, driven by stimuli-responsive polymer innovation. This shift enables new interoperability between material science and targeted therapeutic applications.
For Market Incumbents:Insulate core market share by accelerating R&D investment in multi-stimuli responsive hydrogels and securing key intellectual property for novel polymer chemistries. Strategic partnerships with academic research institutions can mitigate the threat from emerging specialized entrants. Deepen clinical trial designs to meet heightened regulatory standards, particularly for implantable systems. This approach reinforces long-term market dominance against disruptive technologies.
For New Entrants and Emerging Players:Build out capabilities in regenerative medicine applications, leveraging hydrogels as scaffolds for tissue engineering and cell encapsulation. Target underpenetrated healthcare markets in Brazil and India with cost-effective injectable hydrogel systems for chronic conditions. Focus on localized manufacturing and distribution partnerships to gain market access. This strategy allows for rapid penetration into high-growth, underserved segments.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among firms specializing in sustained-release implantable devices for chronic conditions, offering attractive long-term viability over the next 5-10 years. Prioritize acquisition targets with robust intellectual property in novel stimuli-responsive polymers or advanced 3D bioprinting integration capabilities. Successful late-stage clinical trial outcomes for multi-stimuli responsive hydrogels represent a critical signal to watch for inflection. These assets will drive future value creation in precision drug delivery.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates regulatory approval for novel hydrogel systems, ensuring market access in the United States. |
| Manufacturing Scale-Up | Reduces per-unit costs for complex functionalized polymers, expanding adoption in cost-sensitive healthcare systems. |
| Strategic Partnership | Accesses specialized R&D capabilities for multi-stimuli responsive polymers, enhancing product innovation. |
| Regulatory Approval Pathway | Navigates stringent EMA requirements for implantable devices, facilitating European market entry. |
| Pipeline Diversification | Expands therapeutic applications beyond oncology, addressing unmet needs in cardiovascular and neurological disorders. |
Research Approach
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, hospital procurement managers, and material scientists, then refined through iterative analysis. This approach combined in-depth interviews with extensive secondary validation from sources like FDA filings, EMA submissions, and academic research databases. Bottom-up and top-down triangulation ensured data consistency and comprehensive market understanding.
Demand-supply balance formed the core analytical framework across the analysis window, integrating volume and value projections. Segmentation dimensions modeled included product type, therapy area, end-user, technology, and regional regulatory cluster. Compound Annual Growth Rates were derived from historical trends and anticipated regulatory approvals. Key forecast inputs included clinical trial success rates for novel therapies and polymer synthesis advancements.
Practitioners should monitor regulatory changes from the U.S. FDA and EMA for early signals. Forecasts reflect assumptions, but unforeseen biocompatibility issues or intellectual property disputes are critical risk factors. Quarterly review of regulatory approvals and R&D spending is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Biopsy Devices Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Liquid Oxygen Devices Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Water Flosser Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Global Anesthesia Gas Blender Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Ingestible Smart Pills Market
Medical Devices
Diode Laser Aesthetic Medical Device Market
Medical Devices
Deep Brain Stimulator Market
Medical Devices
Brazil Angioplasty Devices Market