
 Pain Monitoring Devices Market | 2026-2036
Pain Monitoring Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pain Monitoring Devices Market Analytics
ISO 13485 certification is rotating the competitive landscape toward manufacturers with established quality management systems. Medtronic leverages its vertically integrated manufacturing footprint across neurostimulation and patient monitoring divisions. Boston Scientific Corporation anchors its position through specialized pain modulation portfolios spanning spinal cord stimulation and peripheral nerve field stimulation. Abbott differentiates via its proprietary BurstDR neurostimulation waveform technology, which occupies a distinct segment within implantable pain therapy systems.
Pain monitoring devices comprise electromechanical and software-integrated systems that quantify physiological pain biomarkers through electromyography, optical sensors, or biomechanical transducers, typically operating at sampling frequencies between 250 Hz and 2 kHz for clinical-grade resolution. Their primary commercial purpose is to objectify subjective pain reports, enabling titrated pharmaceutical dosing and optimized interventional timing. Wearable devices lead volume shipments due to lower capital requirements and expanding remote patient monitoring protocols, while implantable devices command the dominant margin pool given surgical placement requirements and recurring neuromodulator replacement cycles. Electromyography-based systems sustain the fastest growth trajectory among technology segments, driven by their integration with closed-loop adaptive stimulation algorithms.
FDA 510(k) premarket notification requirements and the EU MDR conformity assessment process govern device commercialization, with both frameworks intensifying clinical evidence demands for software-as-medical-device functionalities. HIPAA in the United States and GDPR in Europe impose data governance constraints on cloud-connected pain monitoring platforms, shaping vendor architecture decisions and cross-border deployment strategies. Stakeholders must monitor evolving reimbursement coding for remote therapeutic monitoring to capture sustainable revenue streams from digitally enabled pain care delivery models.
Market Dynamics
Closed-loop adaptive algorithms are compressing device refresh cycles as manufacturers race to integrate real-time biomarker feedback into neuromodulation systems. FDA breakthrough device designation for AI-enabled pain quantification is accelerating clinical validation timelines.
Growth Catalysts
- Remote Therapeutic Monitoring (RTM) reimbursement codes:CMS billing pathways in the United States now cover digitally enabled pain management, expanding addressable revenue for connected device vendors.
- Electromyography sensor miniaturization:Surface EMG arrays with integrated signal processing are enabling wearable form factors previously restricted to clinical settings.
- Germany's DiGA fast-track:The BfArM digital health application approval pathway reimburses prescription pain monitoring apps, creating immediate market access for software-integrated hardware.
Market Restraints
- EU MDR clinical evidence requirements:Software-as-medical-device functionalities now demand prospective validation studies, extending conformity assessment timelines.
- Neurostimulator battery supply concentration:Lithium primary cell production clusters in East Asia, exposing implantable device manufacturers to logistics volatility.
- Optical sensor interference limitations:Photoplethysmography accuracy degrades with melanin variation and motion artifact, constraining demographic addressability.
Strategic Opportunities
- Pediatric pain quantification:Non-verbal patient populations in neonatal intensive care units represent an underserved application requiring adapted EMG algorithms.
- Japan's aging demographic:METI incentives for home-based medical devices align with chronic pain prevalence in rural prefectures lacking specialist access.
- Blockchain-secured pain diaries:Immutable timestamping of subjective reports addresses medicolegal documentation needs in workers' compensation cases.
Industry Challenges
- Biomedical signal processing talent scarcity:The intersection of neurophysiology and embedded systems engineering commands premium compensation, constraining R&D scaling.
- HIPAA-GDPR architectural bifurcation:Cloud infrastructure must maintain data residency compliance across transatlantic deployments, complicating platform unification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pain Monitoring Devices Market |
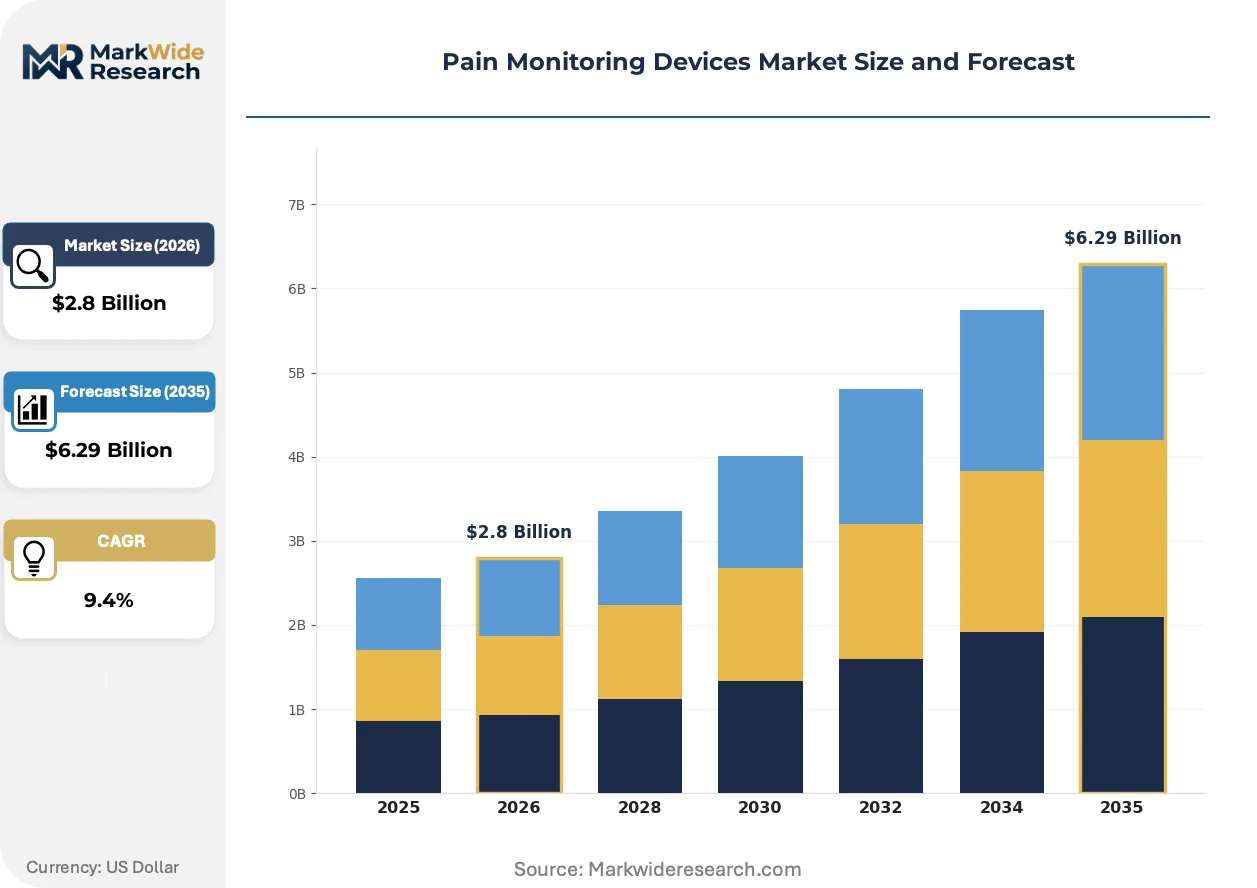
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Implantable Devices, Handheld Devices, Mobile Applications End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Electromyography, Optical Sensors, Infrared Sensors, Biomechanical Sensors Application: Chronic Pain Management, Acute Pain Monitoring, Postoperative Pain, Cancer Pain Assessment |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, Nevro Corp, Stryker, Baxter, B Braun Melsungen AG, LivaNova, ICU Medical Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pain Monitoring Devices Market Evolving Landscape
Algorithmic pain inference is displacing threshold-based stimulation paradigms across implantable and wearable platforms. Device architecture is pivoting toward edge computing to reduce latency in closed-loop response.
Multimodal sensor fusion is displacing single-modality pain quantification in next-generation wearables. Chronic pain clinics in the United States are piloting combined EMG-PPG- accelerometer systems for objective flare prediction. The structural consequence is compression of pharmaceutical rescue dosing cycles as preemptive intervention becomes feasible.
FDA's evolving guidance on adaptive AI in medical devices is tightening predicate device equivalence standards. Manufacturers must now submit locked algorithm versions with predetermined modification protocols. Implantable spinal cord stimulators with learning-enabled waveform adjustment face the steepest evidentiary burden.
Hospital procurement committees are consolidating vendor relationships around integrated pain management ecosystems. Standalone device suppliers lose access to IDN contracts as health systems prioritize interoperability with existing EHR infrastructure. This concentration is most visible in United States integrated delivery networks pursuing CMS accountable care organization metrics.
Pain Monitoring Devices Market Segmentation
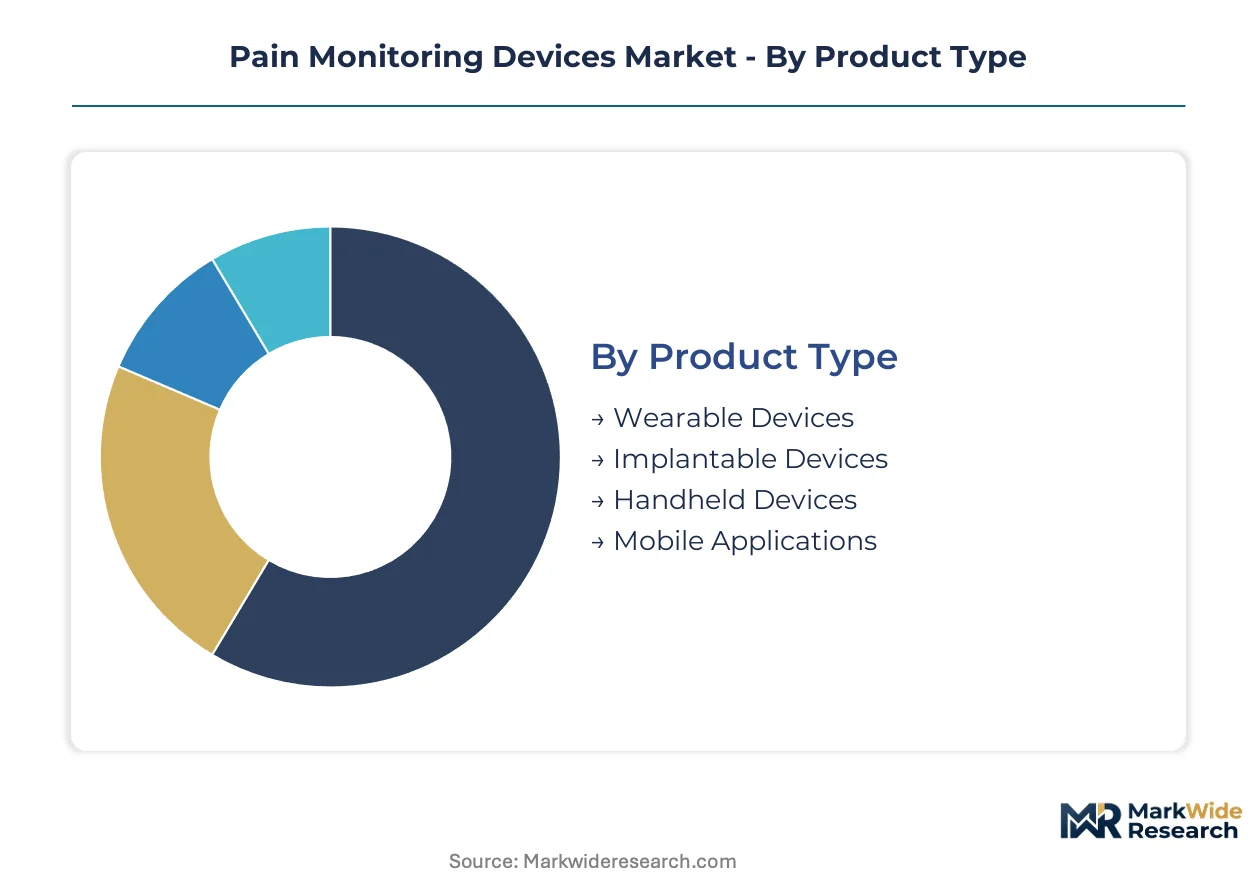
Pain monitoring devices segment across hardware form factors, care settings, sensor modalities, and clinical indications. Each dimension carries distinct regulatory pathways and margin profiles that shape vendor prioritization.
Product Type:
FDA 510(k) clearance timelines vary substantially by invasiveness level, with implantable systems requiring PMA supplements for algorithm updates while wearables navigate streamlined predicates.
- Wearable Devices:Surface-mounted biosensors integrate EMG arrays and accelerometers at sampling rates up to 1 kHz. Demand concentrates in United States home care settings where RTM reimbursement codes now cover remote pain quantification.
- Implantable Devices:Spinal cord and peripheral nerve stimulators with closed-loop feedback require surgical placement and periodic battery replacement. Germany's DiGA fast-track creates immediate access for companion apps that pair with these systems.
- Handheld Devices:Point-of-care instruments for clinical pain assessment.
- Mobile Applications:Software-as-medical-device platforms for subjective pain diary capture and algorithmic inference.
Wearable devices handle the majority of throughput; mobile applications are gaining share fastest as Germany's BfArM pathway accelerates prescription digital health adoption.
End User:
Procurement authority shifts from capital committees to individual clinicians as care migrates toward ambulatory and home-based models.
- Hospitals:Integrated delivery networks in the United States consolidate vendor relationships around EHR-interoperable platforms, favoring ecosystem suppliers over standalone device manufacturers.
- Home Care:Patients self-administer wearable systems with cloud connectivity for remote clinician oversight. Japan's METI incentives for home-based medical devices align with chronic pain prevalence in rural prefectures lacking specialist access.
- Clinics:Outpatient pain management facilities requiring portable diagnostic tools.
- Rehabilitation Centers:Post-acute facilities tracking functional recovery metrics.
Home care is expanding most quickly on reimbursement tailwinds; hospitals retain the dominant margin pool through implantable device surgical volumes.
Technology:
Sensor modality selection determines signal fidelity, artifact susceptibility, and demographic addressability across skin tone and motion conditions.
- Electromyography:Surface and intramuscular electrodes detect motor unit action potentials with microvolt resolution. Integration with closed-loop adaptive stimulation algorithms drives the steepest expansion trajectory among technology segments.
- Optical Sensors:Photoplethysmography modules face accuracy degradation with melanin variation and motion artifact, constraining addressability in diverse populations.
- Infrared Sensors:Thermal imaging for inflammation-mediated pain localization.
- Biomechanical Sensors:Strain gauges and accelerometers capturing movement-induced pain patterns.
Electromyography systems command premium pricing; optical sensors face the stiffest reimbursement scrutiny due to clinical validation gaps.
Application:
Clinical indication determines monitoring duration, algorithm complexity, and integration with pharmaceutical or interventional workflows.
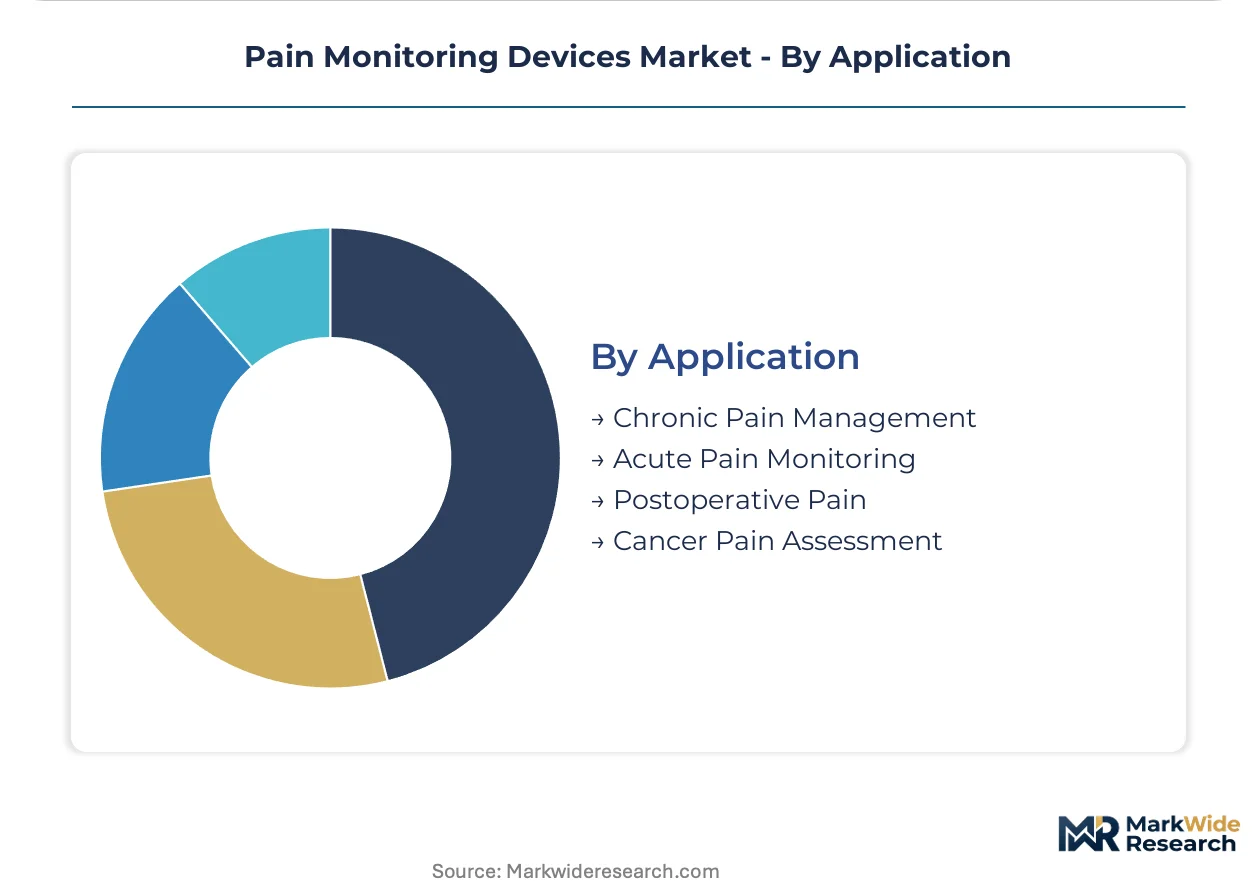
- Chronic Pain Management:Longitudinal monitoring of neuropathic and musculoskeletal conditions requiring months-to-years of data accumulation. United States pain clinics pilot multimodal EMG-PPG-accelerometer systems for objective flare prediction.
- Acute Pain Monitoring:Short-duration quantification in emergency and perioperative settings where immediate analgesic titration decisions carry safety implications.
- Postoperative Pain:Recovery-phase tracking to optimize opioid weaning protocols.
- Cancer Pain Assessment:Oncology-integrated monitoring for breakthrough pain in palliative care populations.
Chronic pain management absorbs the dominant development investment; acute pain monitoring is climbing fastest on hospital throughput pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement pathways are reshaping geographic adoption curves. Germany's BfArM DiGA fast-track reimburses prescription pain monitoring applications, creating immediate market access for software-integrated hardware vendors. Japan's METI incentives for home-based medical devices align with chronic pain prevalence in rural prefectures lacking specialist access.
United States
Remote therapeutic monitoring codes from CMS now cover digitally enabled pain management, expanding addressable revenue for connected device vendors. FDA breakthrough device designation for AI-enabled pain quantification accelerates clinical validation timelines. The Minneapolis medical technology corridor concentrates neuromodulation R&D activity, with manufacturers racing to integrate closed-loop adaptive algorithms.
Germany
The BfArM digital health application approval pathway reimburses prescription pain monitoring apps, creating immediate market access for software-integrated hardware. EU MDR conformity assessment processes govern device commercialization with intensifying clinical evidence demands. The Baden-Württemberg medical device cluster hosts specialized neuromodulation engineering talent pools.
Japan
METI incentives for home-based medical devices align with chronic pain prevalence in rural prefectures lacking specialist access. PMDA regulatory frameworks shape commercialization timelines for wearable biosensors. The Tokyo-Osaka corridor concentrates aging demographic demand for remote pain management solutions.
United Kingdom
NICE technology appraisals influence procurement decisions for implantable pain therapy systems across integrated care systems. GDPR data governance constraints shape vendor architecture decisions for cloud-connected platforms. The Cambridge-London medtech corridor hosts emerging EMG sensor miniaturization ventures.
India
CDSCO medical device regulations are evolving to accommodate software-as-medical-device classifications for pain monitoring platforms. PLI scheme incentives for electronics manufacturing attract component suppliers to domestic production. The Bengaluru-Hyderabad corridor concentrates health technology startups developing affordable wearable form factors.
Pain Monitoring Devices Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with vertically integrated manufacturing footprints. The competitive structure concentrates around three to five established neuromodulation specialists commanding implantable device margin pools alongside emerging wearable biosensor specialists capturing volume growth. Strategic archetypes include full-stack ecosystem suppliers, component-focused sensor specialists, and algorithm-centric software platforms. Dominant competitive moves encompass M&A activity targeting EMG signal processing capabilities and strategic partnerships securing cloud infrastructure compliance across HIPAA-GDPR jurisdictions.
Within the diversified conglomerate tier, Medtronic, Boston Scientific Corporation, and Abbott exemplify established quality management systems with ISO 13485 certification. Medtronic anchors vertically integrated manufacturing across neurostimulation divisions. Boston Scientific Corporation occupies a position within specialized pain modulation portfolios. Abbott represents proprietary waveform technology differentiation in implantable pain therapy systems.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| Nevro Corp |
| Stryker |
| Baxter |
| B Braun Melsungen AG |
| LivaNova |
| ICU Medical Inc |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with lithium primary cell manufacturers in East Asia lock in supply access and price visibility for implantable neuromodulation systems. These arrangements insulate device makers from spot-market volatility while embedding fixed cost structures that shape competitive positioning across wearable and implantable tiers.
Pricing Analysis
Certification level creates the primary spread between ISO 13485-certified implantable systems and uncertified wellness-tier wearables. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) pathway investment, with premium tiers commanding surgical placement bundling. Pricing pressure stems from EU MDR clinical evidence requirements extending conformity timelines. Home care settings exhibit highest price sensitivity; hospital implant volumes show lowest sensitivity due to bundled reimbursement.
Supply Chain Analysis
Japan and South Korea anchor lithium primary cell production for implantable neurostimulator batteries. Taiwan feeds semiconductor fabrication for EMG signal processing chips. Germany's Baden-Württemberg cluster concentrates precision sensor assembly. Raw material dependencies span lithium carbonate, medical-grade titanium, and biocompatible polymers. Single-source vulnerability in East Asian battery supply exposes manufacturers to logistics disruption. Distribution runs through specialized medical device distributors with GPO contracts in United States hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
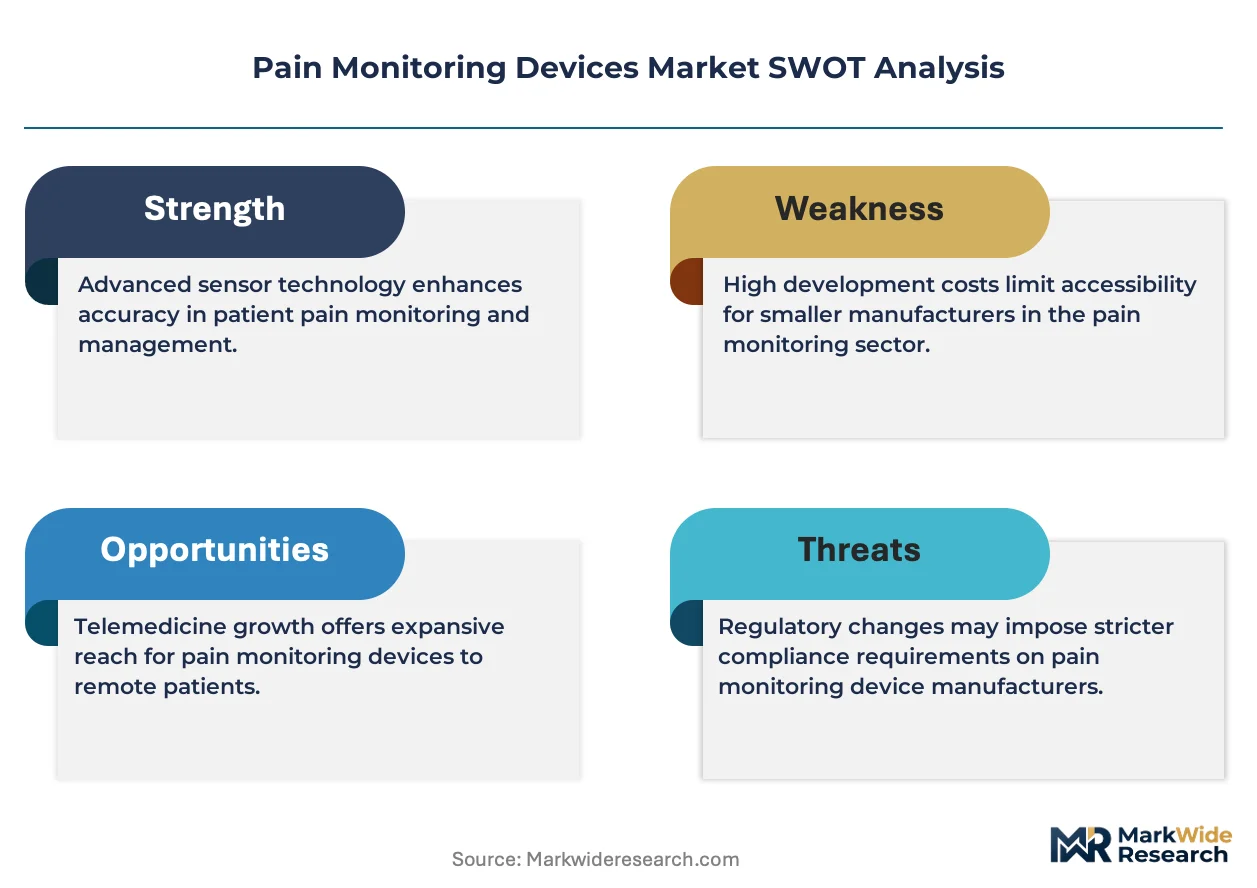
Pain monitoring devices constitute a regulatory-moat market where FDA breakthrough designation and ISO 13485 certification create switching costs that entrench incumbent positions. Network effects from EHR interoperability further deepen defensive positioning.
For Market Incumbents: Shield margin pools by accelerating backward integration into EMG sensor fabrication and securing locked algorithm protocols for FDA adaptive AI guidance compliance. Consolidate around ecosystem partnerships with United States integrated delivery networks before standalone suppliers lose IDN contract access. Prioritize Germany's DiGA fast-track for companion app reimbursement capture. For New Entrants and Emerging Players: FDA breakthrough device designation offers the fastest pathway to competitive parity in AI-enabled pain quantification. Pediatric pain quantification in neonatal intensive care represents the most penetrable white space, with adapted EMG algorithms addressing non-verbal patient populations. Japan's rural prefectures offer geographic entry via METI home-based device incentives paired with cloud-connected wearable form factors. For Investors and Strategic Acquirers: Algorithm-centric software platforms with proprietary closed-loop adaptive stimulation IP represent the highest-conviction acquisition archetype. Long-term viability hinges on reimbursement coding expansion for remote therapeutic monitoring across CMS and BfArM jurisdictions. Signal to monitor: FDA predicate device equivalence standard tightening for learning-enabled waveform adjustment submissions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates clinical validation timelines for AI-enabled pain quantification systems. |
| DiGA Fast-Track Submission | Unlocks immediate reimbursement for prescription pain monitoring apps in Germany. |
| EMG Signal Processing Acquisition | Captures scarce biomedical engineering talent for closed-loop algorithm development. |
| Hospital System Partnership | Secures IDN contract access against ecosystem consolidation pressures. |
| Reimbursement Strategy Investment | Positions for CMS remote therapeutic monitoring code expansion. |
Research Methodology
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists, then refined through secondary validation. FDA 510(k) filings, EU MDR conformity assessment databases, CMS Medicare reimbursement data, and hospital procurement records anchored quantitative sizing. Bottom-up unit economics triangulated against top-down expenditure flow analysis.
Variance decomposition across hardware form factor, sensor modality, care setting, and clinical indication shaped the analytical framework. CAGRs derived from logistic diffusion curves fitted to reimbursement pathway adoption timelines. Modeled inputs included EMG sensor miniaturization cost curves and DiGA prescription volume trajectories across the projection horizon.
Decision-makers should treat outputs as directional under stable reimbursement coding and regulatory pathway assumptions; material deviation would warrant model refresh. Specific risks include EU MDR evidence requirement escalation and lithium supply chain disruption. Recalibration cycles align with material shifts in FDA adaptive AI guidance and CMS remote monitoring policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
United Kingdom Remote Patient Monitoring Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market
Patient Monitoring
Global Hemodynamic Monitoring System Market
Patient Monitoring
North America Patient Temperature Management Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
Wearable Health Sensors Market
Patient Monitoring
Holter Monitor Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Cardiac Patch Monitor Market
Patient Monitoring
Transcutaneous Monitors Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Wearable Patient Monitor Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
Patient Scales Market
Patient Monitoring
United States Patient Monitoring Market