
 Chicken Flavor Market | 2026-2036
Chicken Flavor Market Size, Share, and Industry Trends Forecast 2026-2036
Chicken Flavor Market Intelligence
Ingredient customization revenue is tilting from standardized commodity blends toward application-specific savory solutions. Kerry Group leverages its integrated taste and nutrition platform to anchor large-scale supply contracts with processed food manufacturers across multiple continents. Givaudan competes through deep R&D investment in natural extraction technologies that sustain premium positioning in clean-label flavor portfolios.
Chicken flavor comprises thermally processed reaction flavors, enzyme-modified extracts, and compounded seasoning systems typically containing amino acids, reducing sugars, and poultry-derived precursors developed through Maillard reaction engineering for savory taste delivery. Powder formats dominate high-volume manufacturing due to shelf stability and blending efficiency, while liquid variants capture premium positioning in sauce and ready-meal applications where dissolution control matters. Snacks and seasonings represent the most mature application cluster, whereas soups and sauces offer faster expansion as convenience food formats proliferate.
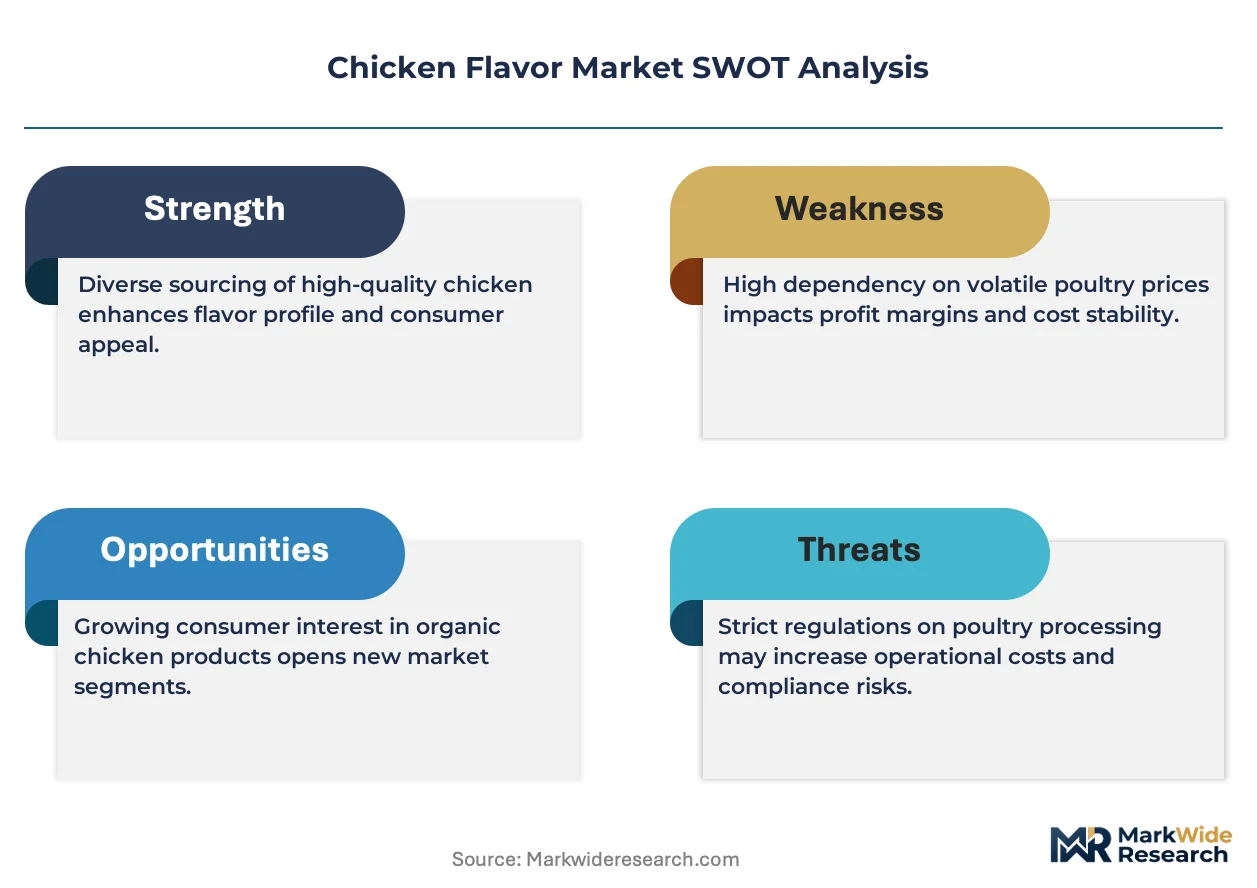
EFSA evaluates novel flavor substances under the Union list of food additives, while REACH governs chemical safety documentation for manufacturing inputs across Europe, and FDA GRAS determinations shape market access for U.S.-bound flavor compounds. These frameworks elevate compliance costs but simultaneously reward suppliers with robust regulatory dossiers and documented supply chain transparency. Stakeholders must monitor evolving natural-label definitions and precursor sourcing restrictions that will determine which flavor technologies retain commercial viability.
Market Dynamics
Clean-label formulation mandates from EFSA and REACH are compressing permissible ingredient lists while Southeast Asian processed food manufacturers scale procurement volumes, creating a structural squeeze between regulatory compliance and supply security.
Growth Catalysts
- Maillard reaction engineering:Advanced thermal processing technologies enable manufacturers to replicate complex savory profiles without synthetic additives, satisfying clean-label requirements in EU-bound exports.
- Indonesia instant noodle production:The country's position as the world's second-largest instant noodle market drives concentrated demand for standardized chicken flavor systems at industrial scale.
- EFSA Union list expansion:The regulator's systematic evaluation of novel flavor substances creates pathway clarity for suppliers investing in natural extraction dossiers.
Market Restraints
- Poultry-derived precursor volatility:Raw material costs fluctuate with avian influenza outbreaks and feed grain prices, compressing margins for reaction flavor manufacturers dependent on consistent protein supply.
- Swiss extraction technology concentration:Premium natural flavor production relies heavily on specialized enzymatic processing equipment manufactured in Switzerland, creating single-source vulnerability.
- REACH documentation burden:The regulation's chemical safety data requirements elevate compliance costs disproportionately for mid-tier suppliers lacking dedicated regulatory affairs infrastructure.
Strategic Opportunities
- Vietnam savory snack expansion:Domestic and foreign-owned manufacturers are building greenfield processing facilities, creating demand for localized flavor formulation partnerships.
- Plant-based chicken analogues:Alternative protein start-ups require engineered savory solutions that replicate mouthfeel and taste without animal-derived precursors.
- EU Green Deal procurement incentives:Carbon footprint disclosure requirements favor suppliers with documented sustainable sourcing and energy-efficient extraction processes.
Industry Challenges
- Maillard chemistry expertise scarcity:The specialized knowledge required to engineer thermally processed reaction flavors resides with a shrinking cohort of senior flavorists, constraining R&D throughput.
- Legacy ERP integration:Mid-sized manufacturers struggle to retrofit supply chain traceability systems that satisfy EFSA documentation requirements without disrupting existing production workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chicken Flavor Market |
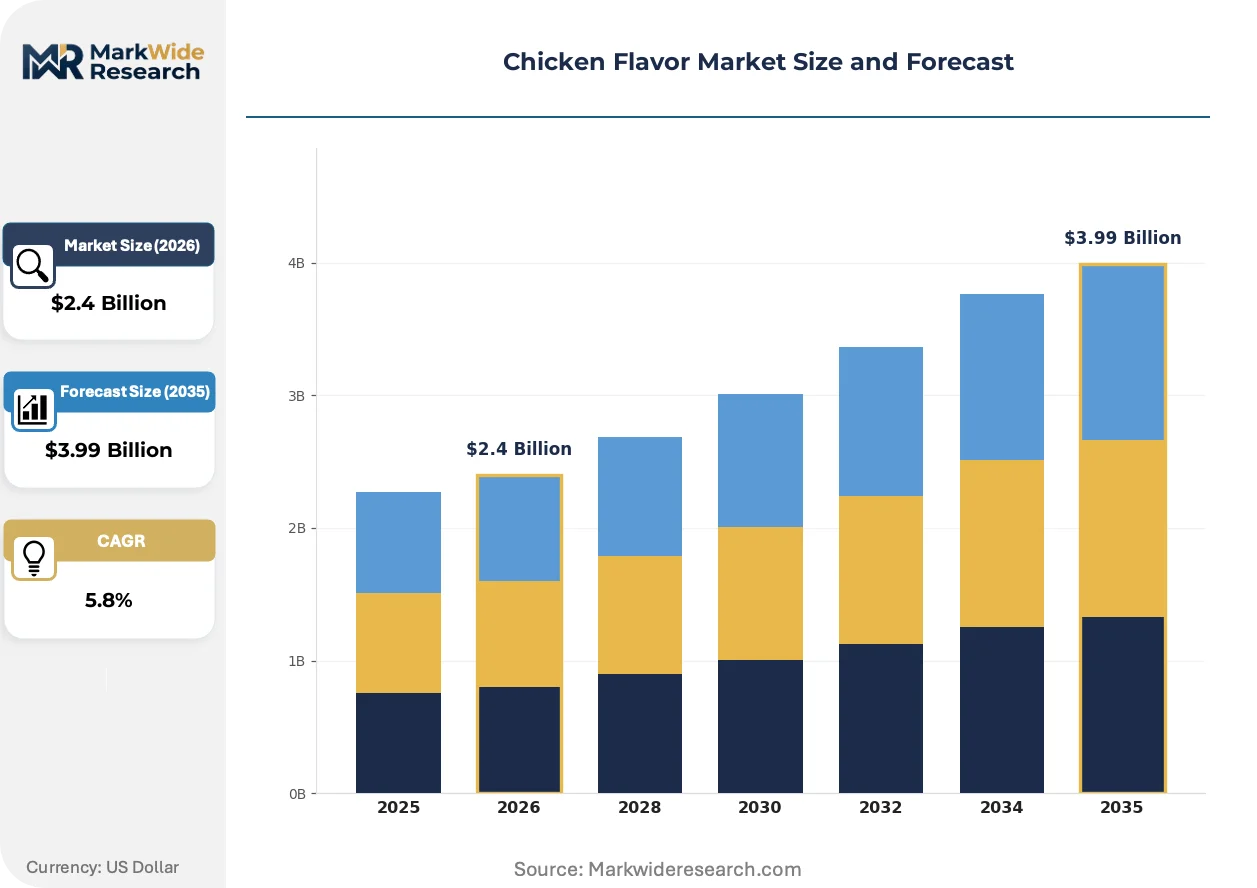
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granular, Paste Application: Snacks, Soups, Sauces, Seasonings End User: Food Manufacturers, Restaurants, Households, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Symrise, Sensient Technologies Corporation, Kerry Group, T. Hasegawa, Takasago International Corporation, International Flavors & Fragrances, Givaudan, Firmenich, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chicken Flavor Market Strategic Shifts & Innovations
Digital process control and biosensor-based quality assurance are displacing manual batch monitoring in flavor manufacturing, while regulatory transparency mandates accelerate documentation automation across the value chain.
Precision fermentation for savory peptide production is digitizing how manufacturers source amino acid precursors previously extracted from poultry processing byproducts. European flavor houses are piloting microbial platforms that generate Maillard-reactive compounds without animal inputs. The technology is digitizing supply chain risk management by decoupling flavor production from livestock commodity cycles.
REACH's 2023 update to substance identification requirements is forcing reformulation of compounded seasoning systems containing complex reaction mixtures. Manufacturers must now disaggregate and document individual precursor contributions to final flavor profiles. Powder format producers serving EU export markets are investing in analytical chemistry capabilities to maintain market access.
Buyer consolidation among Southeast Asian instant noodle manufacturers is compressing supplier negotiation cycles from annual to quarterly frameworks. Procurement teams at integrated food conglomerates now demand real-time inventory visibility and co-development agreements. Vietnam and Indonesia exhibit the most pronounced shift, with top five buyers controlling an expanding share of regional flavor procurement decisions.
Chicken Flavor Market Segmentation
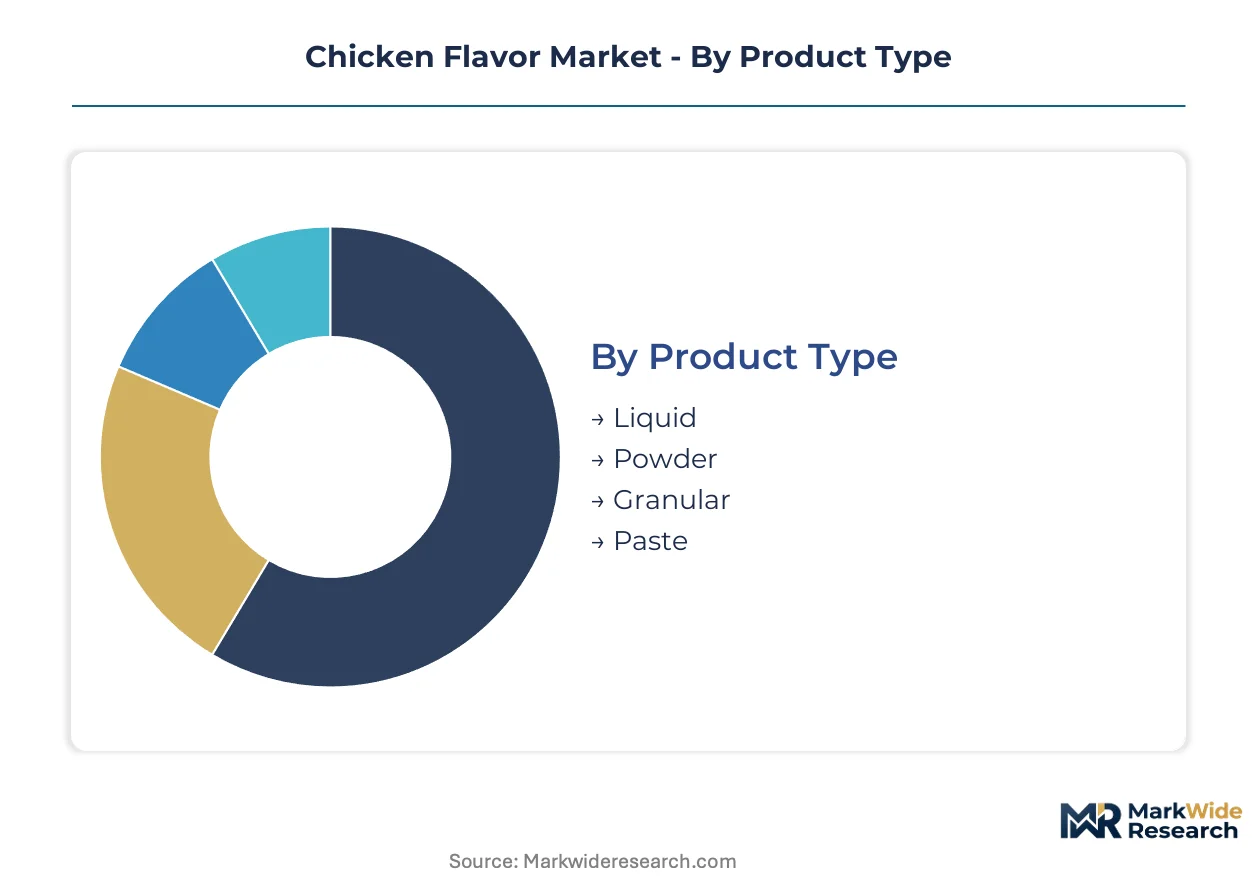
Segmentation in the chicken flavor market reveals how formulation format, application intensity, and procurement channel determine supplier strategy. Each dimension carries distinct technical requirements and margin structures that shape competitive positioning.
Product Type:
Maturity varies sharply across formats, with powder formats representing decades of industrial optimization while precision fermentation-derived liquids emerge as the frontier category.
- Liquid:Dissolution-controlled formulations enable precise dosing in sauce and ready-meal applications where homogeneity matters. Southeast Asian sauce manufacturers in Vietnam and Thailand concentrate procurement here to achieve clean-label positioning without synthetic emulsifiers.
- Powder:Spray-dried and agglomerated variants dominate high-volume manufacturing due to shelf stability, blending efficiency, and lower transportation costs. Indonesian instant noodle producers anchor global demand for standardized powder systems at industrial scale.
- Granular:Free-flowing particles reduce caking in humid climates, suiting tropical distribution networks across Malaysia and the Philippines where moisture sensitivity threatens powder integrity.
- Paste:Concentrated semi-solid formats capture artisanal and small-batch foodservice applications requiring intense flavor delivery without dilution.
Powder handles the majority of throughput; liquid is the fastest mover on share.
Application:
Cost tier segmentation separates commodity-scale applications from premium formulation opportunities where technical collaboration commands price premiums.
- Snacks:Extruded and fried snack coatings represent the most mature application cluster, with flavor loading optimized for high-temperature processing. Malaysian and Indonesian savory snack manufacturers drive volume procurement through co-development agreements with integrated flavor houses.
- Soups:Dehydrated and retort soup formats offer faster expansion as convenience food penetration deepens in Vietnam and urban Indonesia. Clean-label broth replication without MSG dependence attracts R&D investment from European exporters facing EFSA scrutiny.
- Sauces:Liquid and semi-liquid applications demand emulsion stability and heat resistance, favoring suppliers with hydrocolloid and lipid system expertise.
- Seasonings:Table-top and cooking-aid formulations compete on intensity-per-gram metrics, with price-sensitive household segments in the Philippines and Myanmar driving commoditization pressure.
Snacks absorb the largest production volumes; soups are expanding most quickly as convenience formats proliferate.
End User:
Customer type determines contract structure, with food manufacturers demanding technical partnership while foodservice and household segments prioritize logistics reliability.
- Food Manufacturers:Integrated processed food conglomerates in Indonesia and Vietnam negotiate quarterly procurement frameworks with real-time inventory visibility requirements. These buyers demand documented supply chain transparency for EU export compliance.
- Restaurants:Chain and independent foodservice operators concentrate demand in urban centers like Jakarta, Ho Chi Minh City, and Bangkok, favoring localized flavor formulation partnerships that accommodate regional taste preferences.
- Households:Retail-packaged seasonings and cooking aids face price elasticity constraints, with e-commerce penetration accelerating in Vietnam and the Philippines.
- Catering Services:Institutional and event catering requires bulk formats with extended shelf stability, often sourcing through distributor networks rather than direct manufacturer relationships.
Food manufacturers command the dominant procurement share; restaurants are gaining share fastest as foodservice formats expand.
Distribution Channel:
Channel selection reflects buyer scale and technical sophistication, with large manufacturers bypassing intermediaries while smaller users depend on distribution infrastructure.
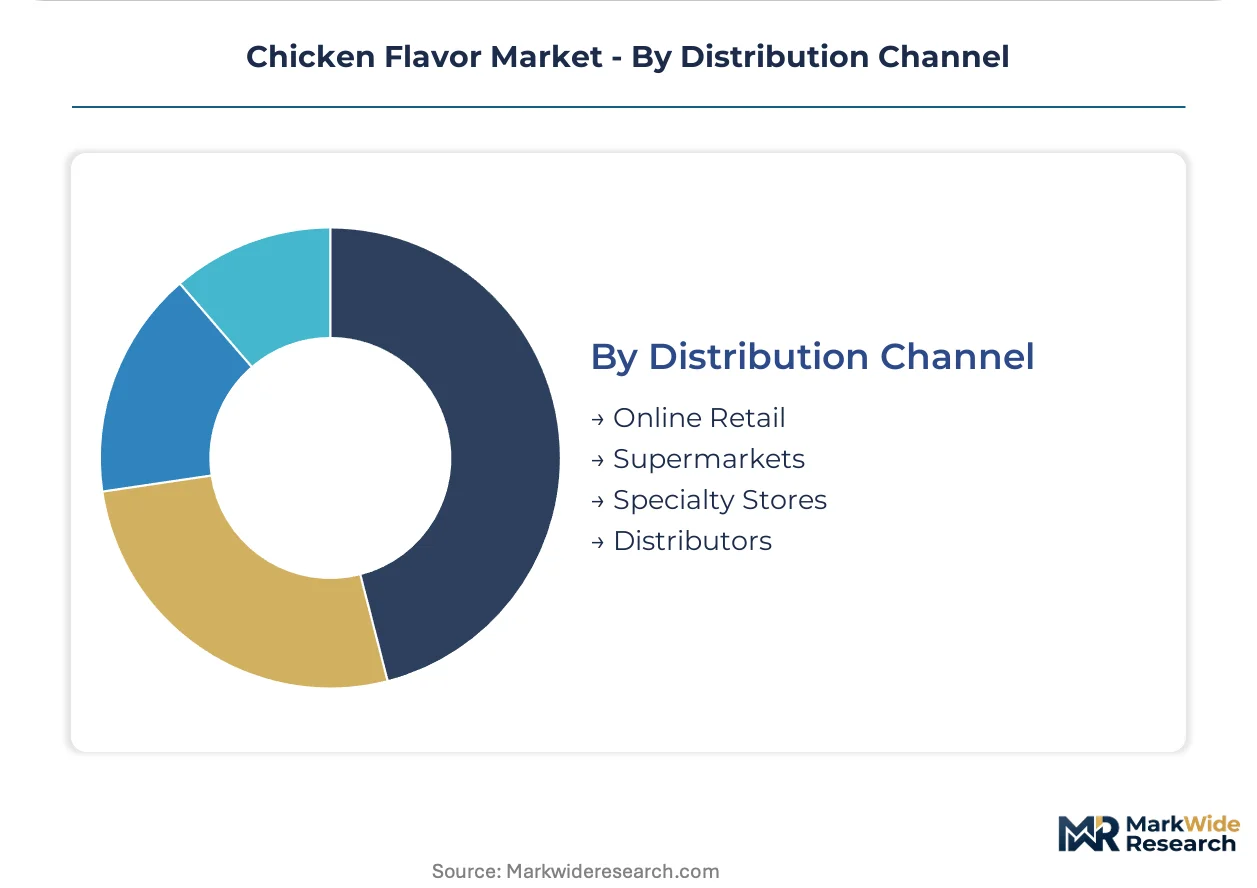
- Online Retail:E-commerce platforms capture growing household and small foodservice demand in Vietnam and Indonesia, particularly for specialty and imported flavor variants.
- Supermarkets:Mass retail chains dominate household seasoning sales across Southeast Asian urban centers, with private-label penetration intensifying price competition.
- Specialty Stores:Gourmet and ethnic food retailers serve artisanal manufacturers and high-end restaurants seeking differentiated flavor profiles.
- Distributors:Regional and national distributors maintain critical infrastructure for mid-tier food manufacturers lacking direct procurement scale, particularly in secondary Indonesian and Vietnamese markets.
Distributors handle the majority of industrial throughput; online retail is climbing the fastest as digital procurement penetrates smaller buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicken flavor consumption patterns diverge sharply across geographies. European buyers prioritize clean-label credentials and documented supply chain transparency for EFSA compliance. Southeast Asian markets emphasize cost-efficient industrial scale for instant noodle and savory snack manufacturing.
Indonesia
Instant noodle production drives concentrated demand for standardized powder formats. BPOM, the national food and drug regulator, enforces halal certification mandates that shape flavor precursor sourcing. West Java hosts the densest cluster of processing facilities, where domestic conglomerates operate integrated seasoning plants serving both local consumption and regional export.
Vietnam
Savory snack manufacturing expansion and soup format proliferation create dual demand channels. The Ministry of Health's food safety decrees align with ASEAN harmonization frameworks for additive disclosure. Ho Chi Minh City and Binh Duong Province anchor greenfield facility construction, with foreign-owned processors establishing localized formulation partnerships.
Germany
Clean-label formulation requirements from EFSA and REACH compliance elevate demand for natural extraction technologies. The Federal Institute for Risk Assessment evaluates novel flavor substances under EU harmonized standards. Bavaria and North Rhine-Westphalia concentrate R&D-intensive flavor houses developing precision fermentation capabilities for Maillard-reactive compounds.
United States
Plant-based protein analogues and ready-meal convenience formats expand application diversity. FDA GRAS determinations govern market access for reaction flavor compounds and enzyme-modified extracts. Chicago and New Jersey corridor facilities serve reformulation demand as CPG manufacturers reduce synthetic additive dependence.
Switzerland
Premium natural flavor production relies on specialized enzymatic processing equipment and extraction technology concentration. Swissmedic oversight applies to flavor-adjacent pharmaceutical applications, while REACH documentation requirements affect chemical safety data for manufacturing inputs. Basel and Zurich regions host precision equipment fabricators supplying global flavor houses.
Chicken Flavor Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another. The vendor base separates into integrated multinational platforms with end-to-end taste and nutrition portfolios, and specialized regional houses with deep local formulation expertise. Three archetypes dominate: diversified ingredient conglomerates anchoring long-term supply contracts, precision technology specialists commanding premium positioning, and regional formulators capturing procurement proximity advantages. Competitive moves center on backward integration into precursor supply and co-development agreements with processed food manufacturers.
Within the integrated platform tier, Kerry Group and Givaudan occupy positions exemplifying divergent strategic vectors. Kerry leverages its combined taste and nutrition infrastructure to anchor industrial-scale contracts across multiple continents. Givaudan represents the R&D-intensive archetype, with natural extraction capabilities sustaining premium portfolio positioning. Sensient Technologies Corporation sits within the specialized technology tier, its geographic naming indicating North American origins while serving formulation demands requiring advanced delivery systems.
| Leading Market Players |
|---|
| Symrise |
| Sensient Technologies Corporation |
| Kerry Group |
| T. Hasegawa |
| Takasago International Corporation |
| International Flavors & Fragrances |
| Givaudan |
| Firmenich |
| BASF |
| Others |
Cost & Logistics Intelligence
West Java's integrated seasoning plants anchor Southeast Asian powder format capacity, concentrating procurement leverage among Indonesian instant noodle conglomerates and compressing margin structures for mid-tier reaction flavor suppliers. EFSA documentation burdens and REACH compliance costs amplify pricing power asymmetries between integrated multinationals and regional formulators lacking dedicated regulatory infrastructure.
Pricing Analysis
Long-term offtake agreements dominate procurement between Indonesian and Vietnamese food manufacturers and integrated flavor houses, while spot purchasing persists for specialty extraction inputs subject to poultry-derived precursor volatility. Three-tier pricing structure across premium natural extraction, standard reaction flavor, and economy compounded systems differentiates on certification grade and documented supply chain transparency. Cost compression in standard powder formats intensifies as buyer consolidation shifts negotiation cycles to quarterly frameworks with real-time inventory visibility demands. Food manufacturers exhibit lowest price sensitivity given co-development dependency, whereas household retail segments face commoditization pressure from private-label penetration.
Supply Chain Analysis
Poultry processing byproduct streams from Indonesia, Thailand, and Brazil feed Maillard reaction precursor supply, while Swiss enzymatic processing equipment fabricators anchor premium natural extraction technology. Amino acid concentrates, reducing sugars, and lipid hydrolysates constitute critical input dependencies, with precision fermentation platforms emerging as alternative peptide sources. Single-source vulnerability concentrates in Swiss extraction equipment manufacturing, threatening capacity expansion timelines for clean-label flavor houses. Distribution runs through regional distributors serving mid-tier Indonesian and Vietnamese manufacturers lacking direct procurement scale, alongside integrated direct supply to multinational food conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation for savory peptide production is disrupting traditional poultry-dependent supply chains, while EFSA Union list expansion and REACH substance identification updates accelerate documentation automation investments across the value chain.
For Market Incumbents: Build regulatory dossier moats through backward integration into precision fermentation platforms and captive amino acid precursor supply. Anchor long-term offtake agreements with Indonesian instant noodle conglomerates expanding West Java capacity. Invest in analytical chemistry capabilities to disaggregate reaction mixture contributions for REACH compliance, defending against mid-tier suppliers lacking documentation infrastructure. For New Entrants and Emerging Players: Pursue plant-based chicken analogue formulation partnerships where alternative protein start-ups require engineered savory solutions without animal-derived precursors. Target Vietnam's greenfield savory snack facilities in Binh Duong Province for localized technical collaboration. Lead with precision fermentation-derived liquid formats capturing premium positioning in sauce and ready-meal applications. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation platform specialists with demonstrated microbial strain development and regulatory pathway clarity. Five-to-ten year viability hinges on decoupling from livestock commodity cycles and securing EFSA novel substance approvals. Monitor Swiss extraction equipment order backlogs as inflection indicator for premium natural flavor capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial platforms generating Maillard-reactive compounds reduce dependence on poultry processing byproduct volatility. |
| EFSA Dossier Investment | Documented natural extraction pathways secure Union list positioning for clean-label EU export compliance. |
| Backward Integration into Precursors | Captive amino acid supply insulates margins from avian influenza outbreak disruptions and feed grain price spikes. |
| Vietnam Greenfield Partnership | Localized formulation collaboration captures Binh Duong Province savory snack manufacturing expansion demand. |
| REACH Documentation Automation | Disaggregated precursor contribution tracking maintains market access under 2023 substance identification requirements. |
Research Approach
Operator-level perspectives from flavor formulation chemists, regulatory affairs directors at integrated food conglomerates, procurement leads at Indonesian instant noodle manufacturers, and Swiss extraction equipment fabricators anchored the qualitative base. Primary interview insights triangulated against BPOM halal certification databases, EFSA Union list evaluations, REACH substance registrations, and ASEAN trade flow records. Bottom-up volume modeling across powder, liquid, granular, and paste formats synthesized with top-down value projections from customs data and industry association filings.
Scenario-bracketing around regulatory approval timelines, precision fermentation yield trajectories, and poultry commodity price cycles shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product format, application intensity in snacks versus soups, end-user procurement scale, and distribution channel structure. CAGRs derived from historical volume trajectories adjusted for technology substitution elasticities and clean-label mandate acceleration. Industry-specific inputs incorporated Maillard reaction engineering adoption curves and EFSA novel substance evaluation throughput.
Sensitivities concentrate around precision fermentation yield improvements, avian influenza outbreak frequency, and EFSA evaluation backlog durations. Forecasts reflect assumptions on regulatory pathway clarity and technology cost curves. Cross-checking against ASEAN food additive trade statistics and Swiss precision equipment export data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Global Floral Flavors Market
Flavorings and Food Additives
Fiber Syrup Market
Flavorings and Food Additives
Vanilla Extract Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
North America Flavors and Fragrances Market
Flavorings and Food Additives
Cocoa Extract Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Botanical Flavors Market
Flavorings and Food Additives
United States Food Flavor and Enhancer Market
Flavorings and Food Additives
Flavor Ingredients Market
Flavorings and Food Additives
Orange Peel Extract Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Browning Solutions Market