
 United States Food Flavor and Enhancer Market | 2026-2036
United States Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
United States Food Flavor and Enhancer Market Analytics
Multi-sourced procurement of flavor compounds is restructuring how food manufacturers manage supplier relationships. Kerry Group leverages its integrated taste and nutrition platform to sustain long-term contracts with major processed food brands. International Flavors & Fragrances Inc. anchors its position through deep R&D investment in natural extraction technologies. Givaudan competes by dominating the premium natural flavor segment with specialized botanical sourcing networks.
Food flavors and enhancers comprise volatile aromatic compounds, taste-active molecules, and savory nucleotides formulated to modify or intensify sensory perception in finished food products. These ingredients typically undergo extraction, fermentation, or chemical synthesis to achieve precise flavor profiles with defined threshold concentrations measured in parts per million. Natural flavors command premium positioning as consumer preference shifts toward recognizable ingredient statements, while artificial flavors retain cost-sensitive applications in mass-market beverages. Flavor enhancers, particularly monosodium glutamate and yeast-derived alternatives, concentrate margin pools in savory snack and processed meat applications where umami intensity drives repeat purchase behavior.
FDA GRAS self-affirmation procedures, FEMA expert panel safety assessments, and USDA organic certification requirements collectively govern market access and product formulation standards. Clean-label pressure from retailers and food manufacturers is tightening the window for artificial flavor acceptance, pushing ingredient suppliers toward natural extraction and biotech-derived alternatives. Stakeholders must monitor evolving state-level labeling mandates and biotechnology regulatory frameworks to anticipate compliance costs and reformulation timelines.
Market Dynamics
Clean-label reformulation mandates from major retailers are compressing artificial flavor acceptance windows and forcing ingredient suppliers toward natural extraction and fermentation-derived alternatives with full supply chain traceability.
Growth Catalysts
- California Clean-Label Mandates:State-level legislation requiring ingredient disclosure on processed foods is accelerating natural flavor adoption in bakery and beverage applications.
- FDA GRAS Self-Affirmation:Streamlined safety determination procedures are shortening new flavor compound approval timelines for domestic manufacturers.
- Midwest Food Manufacturing Corridor:Concentrated meat processing and snack production in Illinois, Iowa, and Ohio sustains bulk demand for savory enhancers and smoke flavors.
Market Restraints
- Vanillin Feedstock Volatility:Guaiacol and lignin supply disruptions from Chinese chemical processors create price instability for natural vanilla alternatives.
- FEMA Expert Panel Backlog:Safety assessment queue delays for novel flavor substances extend commercialization timelines by 18-24 months.
- Biotech-Derived Ingredient Skepticism:Consumer resistance to precision-fermentation flavors limits market penetration despite clean-label positioning.
Strategic Opportunities
- Texas and Florida Expansion:Underpenetrated Southern markets offer whitespace for regional flavor houses targeting Hispanic and Asian cuisine segments.
- Plant-Based Meat Enhancers:Emerging application in analog protein products requires specialized masking and umami systems absent from legacy portfolios.
- USDA Organic Certification:Premium positioning through organic-compliant natural flavors captures price premiums in natural channel retail.
Industry Challenges
- Flavor Chemist Talent Scarcity:Specialized formulation expertise in natural extraction and encapsulation technologies commands compensation premiums that strain mid-tier suppliers.
- Dual Certification Burden:Simultaneous FEMA GRAS and USDA organic compliance timelines create resource allocation conflicts for product development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Food Flavor and Enhancer Market |
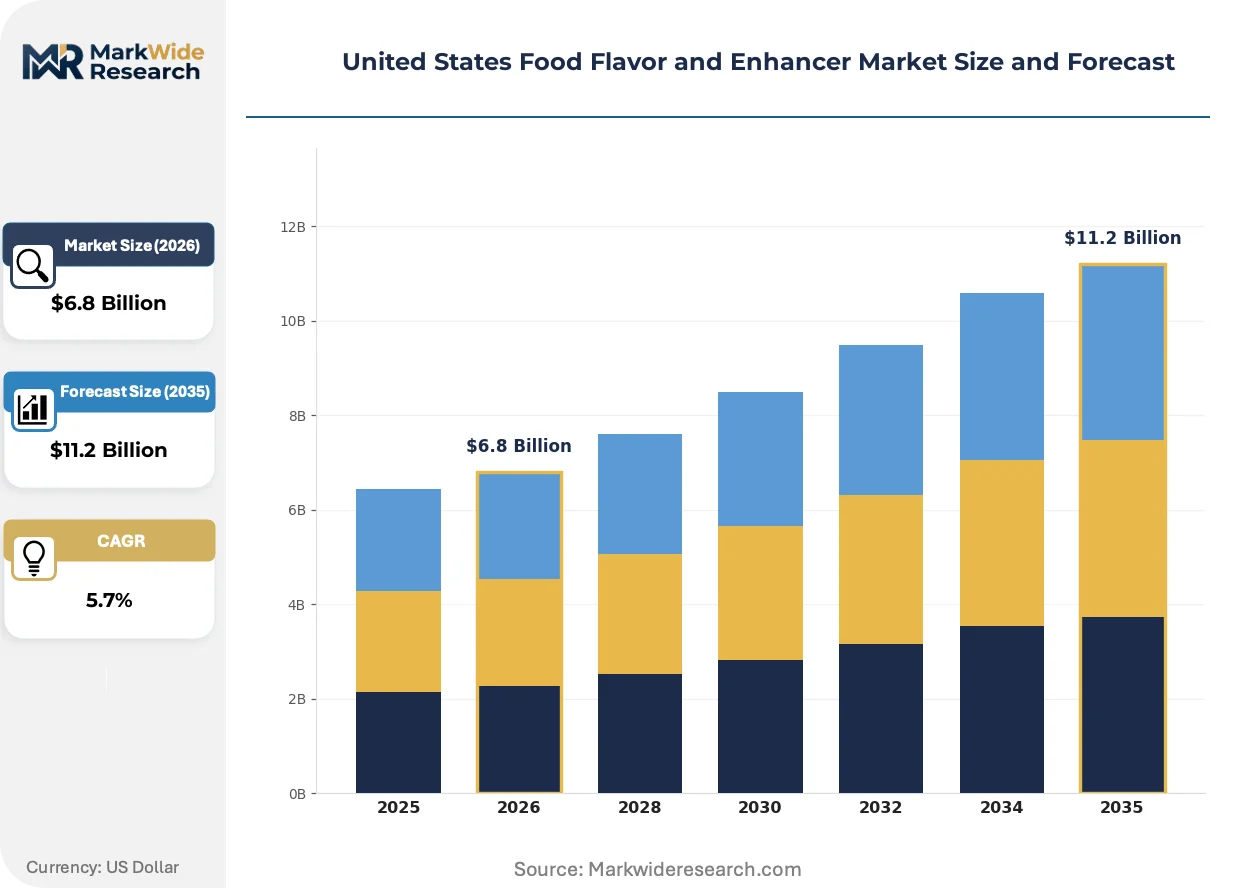
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Flavor Enhancers, Extracts Application: Bakery, Beverages, Dairy, Snacks End User: Food Manufacturers, Restaurants, Retailers, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Sensient Technologies Corporation, International Flavors & Fragrances Inc., Kerry Group, Givaudan, Archer Daniels Midland Company, Symrise AG, Firmenich SA, DSM, DuPont de Nemours, Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Food Flavor and Enhancer Market Evolving Landscape
Biotechnology and precision fermentation are rewriting raw material economics for natural flavor production. Three interconnected developments are compressing cost differentials and expanding application possibilities.
Precision fermentation platforms are unifying microbial strain engineering with downstream purification to produce rare botanical compounds at industrial scale. Specialty chemical suppliers are deploying these systems for saffron, vanilla, and citrus terpene replication. The technology is unifying quality consistency with cost structures that challenge conventional agriculture-dependent supply chains.
FDA guidance on New Dietary Ingredients and evolving GRAS notification requirements are tightening safety documentation standards for novel flavor substances. Ingredient suppliers must submit expanded toxicology packages and exposure assessments. Small and mid-sized flavor houses face compliance cost barriers that favor larger competitors with dedicated regulatory affairs functions.
Direct supplier relationships between ingredient manufacturers and retail private-label programs are displacing traditional distributor intermediaries. Walmart, Kroger, and Target are building captive flavor development partnerships that bypass conventional food manufacturer networks. This channel compression is most visible in store-brand snack and beverage categories where speed-to-shelf and cost control dominate procurement criteria.
United States Food Flavor and Enhancer Market Segmentation
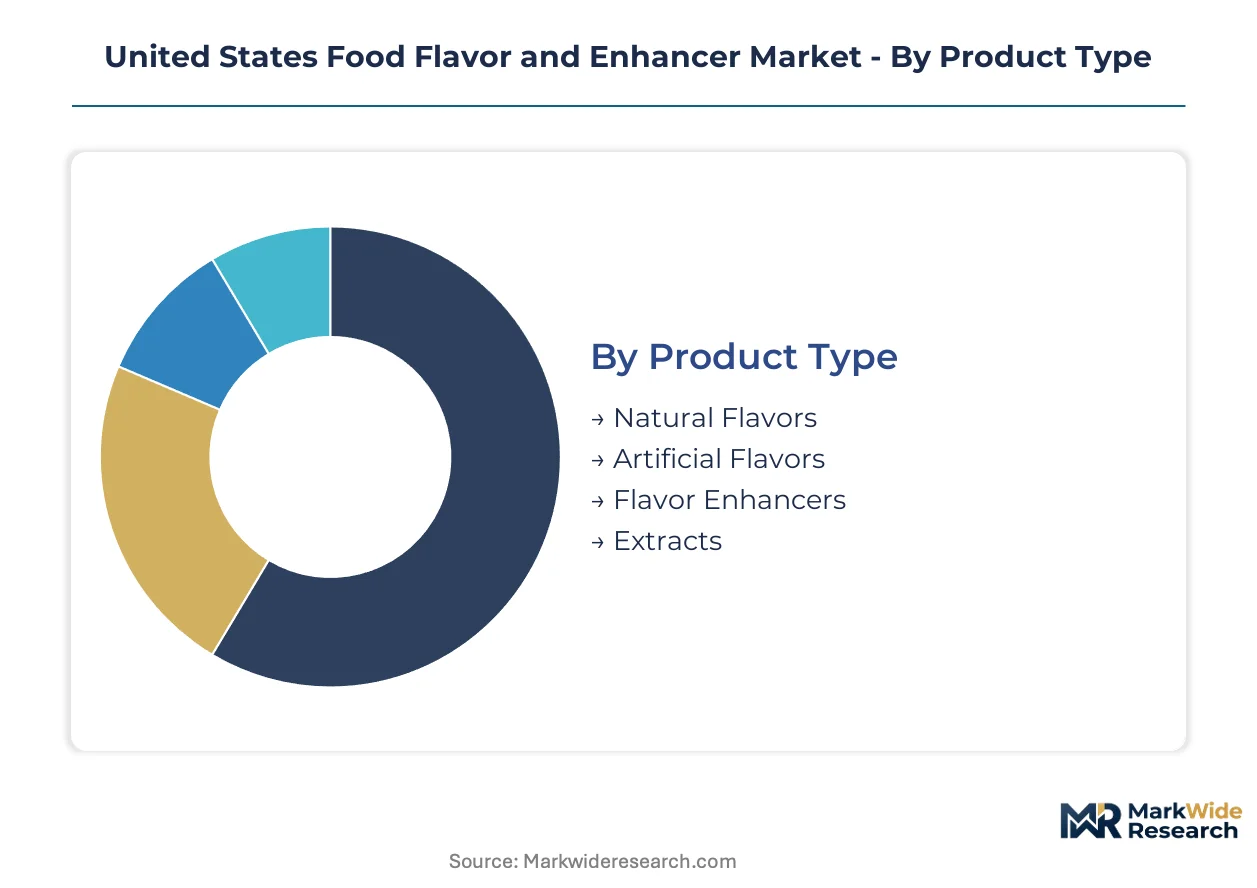
Flavor and enhancer procurement patterns diverge sharply between mass-market commodity buyers and premium-positioned clean-label formulators. Segmentation reveals how supply chain configuration, regulatory compliance burden, and end-use technical requirements reshape vendor selection criteria across distinct buyer archetypes.
Product Type:
Natural extracts command price premiums reflecting agricultural input volatility and extraction yield constraints, while synthetic alternatives anchor cost-sensitive volume applications.
- Natural Flavors:Derived from plant, animal, or microbial sources through distillation, fermentation, or enzymatic processes. California clean-label mandates and Midwest organic dairy processors concentrate procurement of USDA-certified natural vanilla and citrus terpenes. FDA GRAS self-affirmation timelines extend 12-18 months for novel botanical extracts.
- Artificial Flavors:Chemically synthesized aromatic compounds replicating natural taste profiles at fractional cost. Illinois and Ohio snack manufacturers sustain bulk demand for artificial cheese and smoke flavors where ingredient cost thresholds dominate formulation decisions.
- Flavor Enhancers:Nucleotide and glutamate-based compounds intensifying savory perception without adding distinct aroma character.
- Extracts:Concentrated flavoring preparations from named source materials with defined solvent residue limits.
Mature deployment sits with Artificial Flavors. Newer deployment is concentrated in Natural Flavors.
Application:
Technical performance requirements vary dramatically between thermally stable bakery systems and cold-processed beverage matrices.
- Beverages:Water-soluble flavor systems requiring emulsion stability, acid tolerance, and light-fastness in transparent packaging. California functional drink startups and Texas bottled water processors drive demand for heat-stable citrus and botanical extracts with clean-label positioning.
- Snacks:Lipid-compatible flavor coatings and topical seasoning systems demanding adhesion, oxidative stability, and controlled release. Iowa and Ohio meat snack and chip manufacturers anchor savory enhancer consumption where umami intensity drives repeat purchase metrics.
- Bakery:Heat-stable flavor encapsulation surviving Maillard reaction temperatures without degradation.
- Dairy:Fat-compatible flavor systems with freeze-thaw stability for ice cream and cultured applications.
Volume concentration centers on Snacks. Premium expansion is climbing the fastest in Beverages.
End User:
Procurement scale and technical service requirements separate enterprise food manufacturers from fragmented foodservice operators.
- Food Manufacturers:Large-scale processors with captive R&D facilities and dedicated flavor chemists negotiating long-term supply agreements. Midwest meat and snack conglomerates in Illinois and Ohio specify custom savory systems with full supply chain documentation for retailer compliance audits.
- Restaurants:Chain operators and independent establishments sourcing finished flavor concentrates through broadline distributors. Florida and Texas quick-service chains expanding Hispanic and Asian menu platforms drive regional flavor house technical service demands.
- Retailers:Private-label program managers building direct supplier relationships bypassing traditional food manufacturer intermediaries.
- Catering Services:Institutional and event-focused operators prioritizing cost-controlled bulk formats over technical customization.
Contract security sits with Food Manufacturers. Growth velocity is strongest with Retailers.
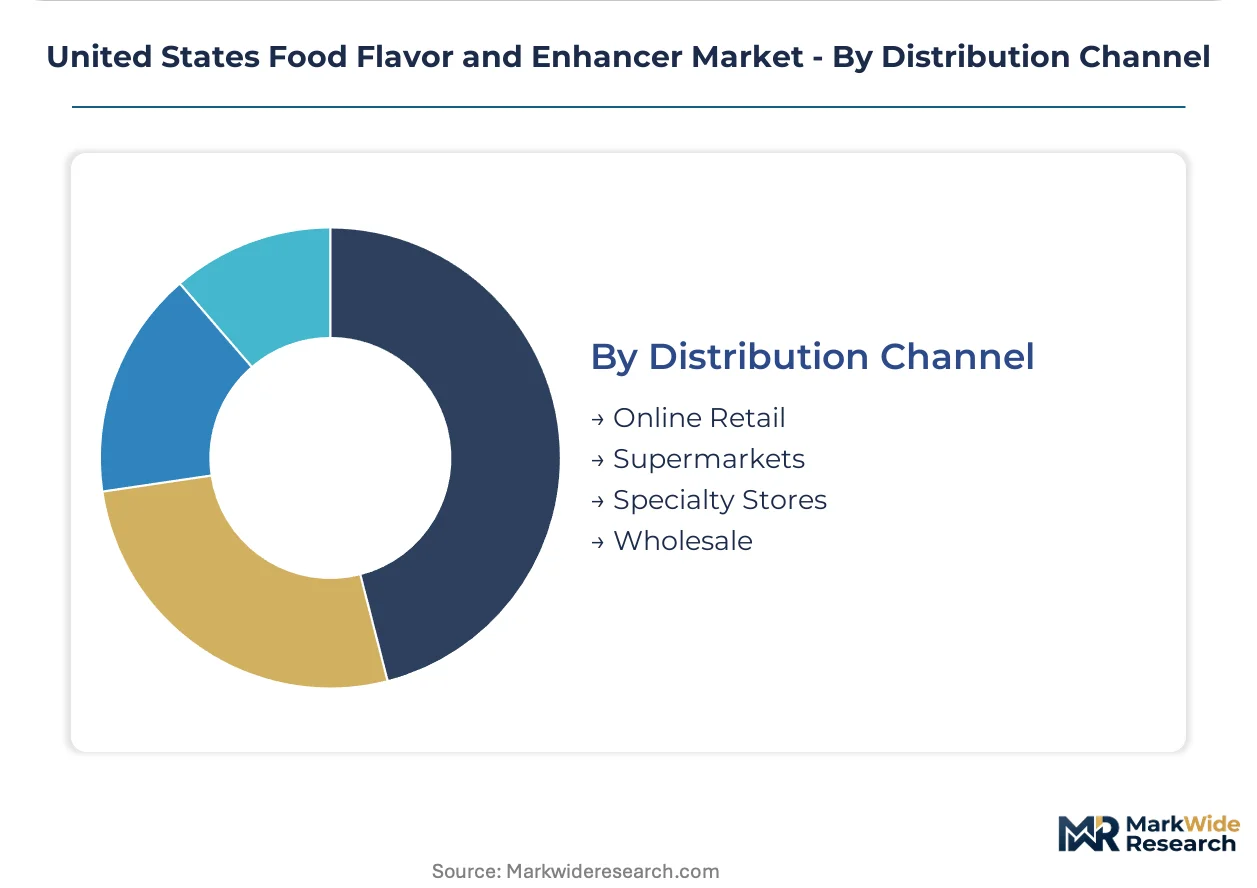
Distribution Channel:
Channel selection reflects order frequency, technical support requirements, and inventory carrying cost tolerance.
- Wholesale:Bulk ingredient distribution through foodservice and industrial distributors with technical sales support. Midwest manufacturing corridor concentration sustains regional distribution hub density for just-in-time savory enhancer delivery to meat and snack processors.
- Online Retail:Direct-to-formulator platforms serving small-batch and startup food manufacturers with sample quantities and rapid turnaround. California clean-label beverage startups leverage digital procurement for rare botanical extracts unavailable through conventional distribution.
- Supermarkets:Mass-market retail formats carrying consumer-facing flavor extracts and seasonings.
- Specialty Stores:Premium and ethnic-focused retailers serving artisan food producers and serious home cooks.
Established volume flows through Wholesale. Channel expansion is gaining share fastest through Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in California and the Midwest food manufacturing corridor, with state-level clean-label mandates and concentrated meat processing operations driving procurement patterns. Texas and Florida present underpenetrated expansion opportunities for regional flavor houses.
California
Clean-label beverage startups and functional drink manufacturers anchor demand for rare botanical extracts and heat-stable citrus systems. State legislation requiring ingredient disclosure on processed foods accelerates natural flavor adoption in bakery and beverage applications. Los Angeles and San Francisco Bay Area clusters sustain digital procurement platforms serving small-batch formulators.
Midwest Corridor
Illinois, Iowa, and Ohio meat processing and snack production sustain bulk consumption of savory enhancers and smoke flavors. FDA GRAS self-affirmation procedures streamline safety determinations for domestic manufacturers operating in this region. Chicago anchors distribution hub density for just-in-time savory enhancer delivery to meat and snack processors.
Texas
Quick-service chains expanding Hispanic and Asian menu platforms drive regional flavor house technical service demands. USDA organic certification requirements govern market access for suppliers targeting natural channel retail. Houston and Dallas-Fort Worth metro areas concentrate foodservice procurement for broadline distribution networks.
Florida
Independent restaurants and chain operators source finished flavor concentrates through distributor intermediaries. State-level labeling mandates tighten windows for artificial flavor acceptance in retail-facing applications. Miami and Orlando clusters support ethnic cuisine segment expansion for regional flavor development partnerships.
Pacific Northwest
Organic dairy processors concentrate procurement of USDA-certified natural vanilla and fermentation-derived alternatives. FEMA expert panel safety assessments shape approval timelines for novel botanical extracts from regional suppliers. Seattle and Portland anchor clean-label beverage manufacturing for premium positioning in natural retail channels.
United States Food Flavor and Enhancer Market Competitive Landscape
Capacity expansion dominates the current landscape as ingredient suppliers scale precision fermentation platforms and natural extraction capabilities. The vendor base stratifies across integrated multinational conglomerates, specialized botanical sourcing networks, and regional flavor houses with captive R&D functions. Three archetypes define competitive positioning: taste-and-nutrition integrators, premium natural segment specialists, and commodity-scale synthetic flavor manufacturers. M&A activity and strategic partnerships concentrate margin pools in savory snack and plant-based meat enhancer applications.
Among integrated taste-and-nutrition platforms, Kerry Group and International Flavors & Fragrances Inc. occupy positions exemplifying long-term contract security with major processed food brands. Givaudan represents the premium natural segment specialist archetype, with specialized botanical sourcing networks commanding price premiums in clean-label applications. These three companies anchor the competitive structure, while Archer Daniels Midland Company and Symrise AG sit within the commodity-scale synthetic and fermentation-derived tier serving cost-sensitive volume applications.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| International Flavors & Fragrances Inc. |
| Kerry Group |
| Givaudan |
| Archer Daniels Midland Company |
| Symrise AG |
| Firmenich SA |
| DSM |
| DuPont de Nemours, Inc |
| Others |
Value Network & Pricing Analysis
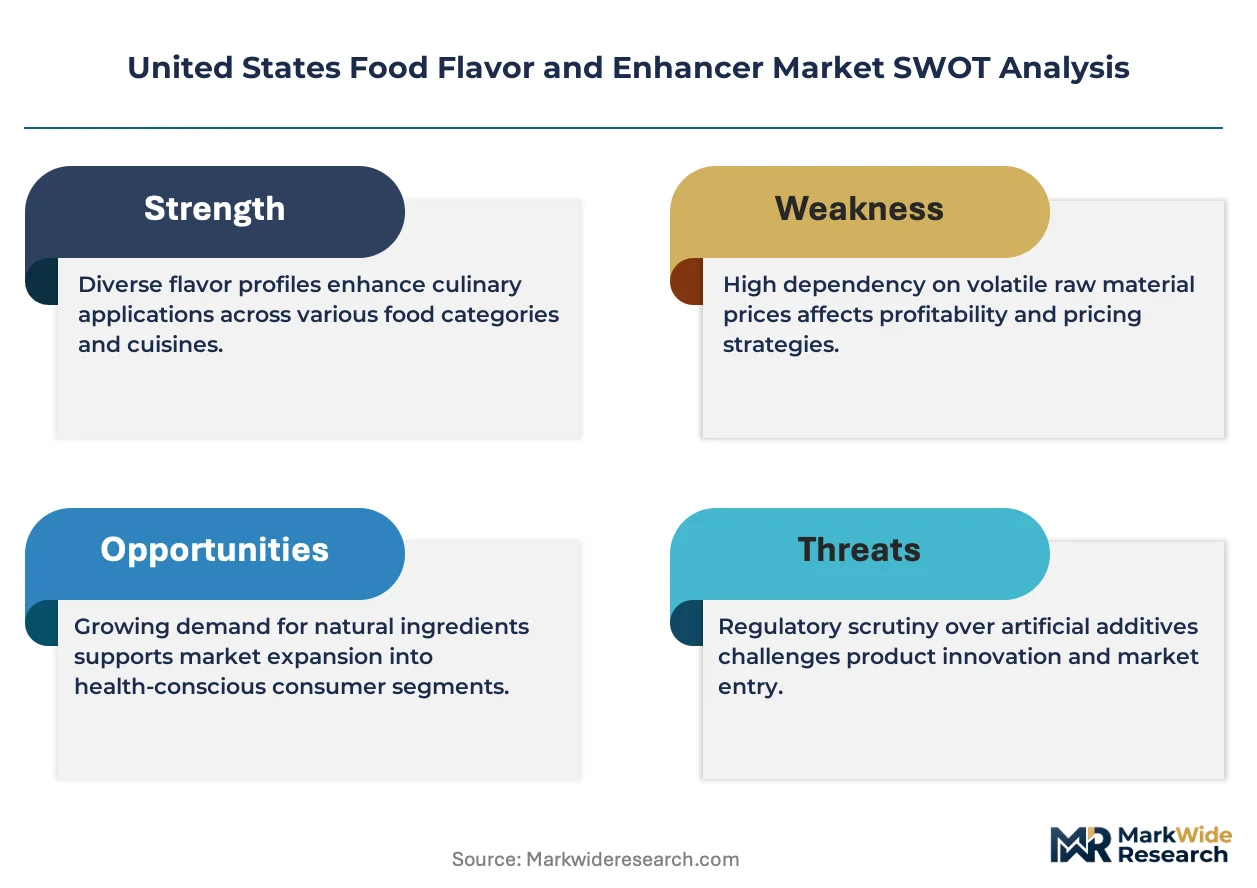
California clean-label mandates gate qualified supply and premium-tier pricing access by requiring full ingredient disclosure and supply chain traceability documentation. FDA GRAS self-affirmation timelines and FEMA expert panel backlogs create compliance cost barriers that stratify pricing power between certified natural extract suppliers and commodity artificial flavor manufacturers.
Pricing Analysis
Volume concentration in artificial flavors anchors economy-tier contract pricing for Illinois and Ohio snack manufacturers, while margin pools concentrate in natural extracts where USDA organic certification and California disclosure compliance command 40-60% premiums. Price differentiation rests on certification grade and supply chain documentation depth. Pricing pressure stems from vanillin feedstock volatility disrupting guaiacol and lignin supply chains from Chinese processors. Mass-market beverage formulators exhibit highest price sensitivity; clean-label bakery startups in California show lowest sensitivity due to premium positioning requirements.
Supply Chain Analysis
Reverse-logistics flows for spent botanical extraction materials and fermentation biomass are emerging as sustainability compliance requirements in California and Pacific Northwest organic dairy corridors. Raw material sourcing draws from Madagascar and Indonesia for vanilla, India and China for spice oleoresins, and Midwest corn belt processors for fermentation feedstocks. Single-source vulnerability concentrates in Chinese chemical processors supplying guaiacol precursors. Distribution runs through Chicago-based wholesale hubs serving the Midwest manufacturing corridor, with direct supplier relationships to Walmart and Kroger private-label programs displacing traditional food manufacturer intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA GRAS self-affirmation procedures and FEMA expert panel safety assessments constitute a cost-of-compliance moat that advantages established players with dedicated regulatory affairs functions and disadvantages mid-tier suppliers facing 18-24 month commercialization delays.
For Market Incumbents: Deploy precision fermentation capacity expansion to defend margin position against agricultural input volatility threatening natural extract economics. Kerry Group and International Flavors & Fragrances should deepen captive R&D partnerships with Midwest meat processors requiring custom savory systems with full supply chain documentation. Consolidate position in plant-based meat enhancers where legacy portfolios lack specialized masking and umami capabilities.
For New Entrants and Emerging Players: The premium-economy price-point gap in Texas and Florida quick-service chains creates whitespace for regional flavor houses targeting Hispanic and Asian cuisine segments. Target underpenetrated Southern markets with technical service capabilities absent from national distributor networks. Pursue direct retail private-label partnerships bypassing food manufacturer intermediaries where speed-to-shelf dominates procurement criteria.
For Investors and Strategic Acquirers: FEMA expert panel approval acceleration for novel biotech-derived flavor substances is the leading indicator that precision fermentation platforms are achieving regulatory acceptance and scalable unit economics. Long-term viability favors integrated taste-and-nutrition platforms with captive extraction capabilities and established retailer compliance audit relationships. Monitor California state-level labeling mandate expansion as signal for natural flavor demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial strain engineering for saffron and vanilla replication challenges agricultural supply chain volatility. |
| USDA Organic Certification Investment | Compliance with California disclosure mandates captures price premiums in natural channel retail. |
| Direct Retail Partnership Formation | Walmart and Kroger private-label programs bypass food manufacturer intermediaries for cost control. |
| Plant-Based Meat Enhancer Development | Specialized masking systems address analog protein flavor gaps absent from legacy savory portfolios. |
| Midwest Distribution Hub Consolidation | Chicago anchors just-in-time savory enhancer delivery to Illinois and Ohio meat processors. |
Research Methodology
Multi-period observation of FDA GRAS notification filings, FEMA expert panel approval timelines, and California state labeling mandate evolution anchored the trend analysis, supplemented by interviews with flavor chemists, regulatory affairs directors at ingredient suppliers, procurement managers at Midwest meat processors, and category buyers at Kroger and Walmart. Secondary validation drew from FDA GRAS notices, FEMA expert panel meeting minutes, USDA organic certification databases, and trade data on vanilla and spice oleoresin imports. Bottom-up segment sizing triangulated against top-down market value estimates.
Segment-weighting across product type, application, end user, and distribution channel dimensions structured the analytical framework over the projection horizon. Natural flavor and artificial flavor splits were modeled separately given divergent growth trajectories. CAGRs were derived from trend extrapolation adjusted for regulatory approval timeline impacts and clean-label mandate diffusion patterns. Forecast inputs incorporated FEMA expert panel queue dynamics and precision fermentation cost curve assumptions.
Inputs from FDA GRAS filings and FEMA expert panel records were available through the study window; gaps in private-label contract terms and direct supplier pricing introduce uncertainty bands around volume and value estimates. Forecasts reflect documented assumptions on regulatory approval acceleration and biotechnology acceptance curves. Practitioners should monitor California labeling mandate expansion and FEMA expert panel staffing increases for early demand and supply signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
United States Food Colorants Market
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
Ginkgo Biloba Extract Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
Annatto Extract Market
Flavorings and Food Additives
Flavor Drops Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Royal Jelly Extract Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Food Aroma Market
Flavorings and Food Additives
North America Licorice Extract Market