
 Flavor Ingredients Market | 2026-2036
Flavor Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Flavor Ingredients Market Insights
Multi-source botanical procurement is decoupling from traditional petrochemical feedstock dependence across the flavor ingredients supply base. Givaudan S.A. leverages captive cultivation partnerships in Madagascar and Haiti to secure vanilla and vetiver supply chains. Symrise AG anchors its competitiveness through R&D intensity in fermentation-derived molecules, while DSM-Firmenich AG sustains manufacturing scale advantages across European and Asian production hubs.
Flavor ingredients comprise volatile aromatic compounds, essential oils, oleoresins, and synthetic molecules formulated to impart taste and olfactory profiles to consumer products, typically dosed at parts-per-million to percent-level concentrations depending on application intensity and matrix stability. Natural extracts and synthetic molecules represent the dominant product type split, with natural extracts commanding premium positioning in beverage and bakery applications while synthetic variants retain cost advantages in high-volume snack seasoning. The liquid form category leads in processing flexibility for industrial batching, though powder formats are gaining traction in dry-mix confectionery and instant beverage platforms where moisture sensitivity governs shelf-life performance.
FDA GRAS self-affirmation pathways and EFSA flavoring substance evaluations create divergent compliance burdens for suppliers operating across Atlantic markets, with the EU's stricter positive-list approach limiting novel molecule introduction relative to American notification procedures. FSSAI in India is progressively harmonizing additive standards with Codex Alimentarius frameworks while imposing stricter origin-labeling requirements for natural claims. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of formulation portfolio viability and capital allocation for regional production assets.
Market Dynamics
Clean-label mandates are compressing synthetic molecule portfolios while redirecting capital toward captive botanical cultivation and fermentation infrastructure. Formulation budgets now prioritize supply security over unit cost optimization.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Tightening permissible synthetic additive lists forces beverage and bakery manufacturers toward natural extract procurement, expanding addressable demand for botanical suppliers.
- India PLI scheme incentives:Domestic food processing subsidies accelerate flavor compound production capacity, reducing import dependence for oleoresin and essential oil inputs.
- Fermentation-derived molecules:Precision fermentation platforms enable scalable production of rare aromatic compounds previously constrained by agricultural harvest cycles and climate volatility.
Market Restraints
- Vanilla supply concentration:Madagascar and Haiti dominate vanilla bean cultivation, exposing processors to cyclone disruption and price spikes that compress margin stability.
- EFSA positive-list friction:Novel molecule introduction requires exhaustive safety dossiers, creating eighteen-to-thirty-six-month approval timelines that deter R&D investment relative to FDA notification pathways.
- Natural extract yield variability:Botanical harvest quality fluctuates with precipitation and temperature patterns, forcing inventory carrying costs and hedging expenditures that synthetic chemistry avoids.
Strategic Opportunities
- India FSSAI labeling harmonization:Codex-aligned additive standards combined with stricter origin-labeling requirements create first-mover advantage for domestic producers certifying natural claim authenticity.
- Powder format penetration:Dry-mix confectionery and instant beverage platforms favor moisture-stable flavor delivery systems, opening formulation partnerships outside traditional liquid-dominant supply relationships.
- Biotechnology-conventional extraction convergence:Enzymatic pre-treatment of botanical feedstocks improves essential oil yield rates, enabling unit cost parity with select synthetic alternatives in mid-market applications.
Industry Challenges
- Flavor chemist talent scarcity:Cross-disciplinary expertise spanning organic chemistry, sensory science, and regulatory navigation commands premium compensation, constraining mid-tier supplier technical capabilities.
- Dual-jurisdiction compliance burden:Parallel FDA GRAS self-affirmation and EFSA flavoring substance evaluations require redundant toxicology studies, stretching quality assurance resources.
- Legacy batching system integration:Powder format adoption demands capital retooling of liquid-optimized manufacturing lines, complicating product line diversification for established processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavor Ingredients Market |
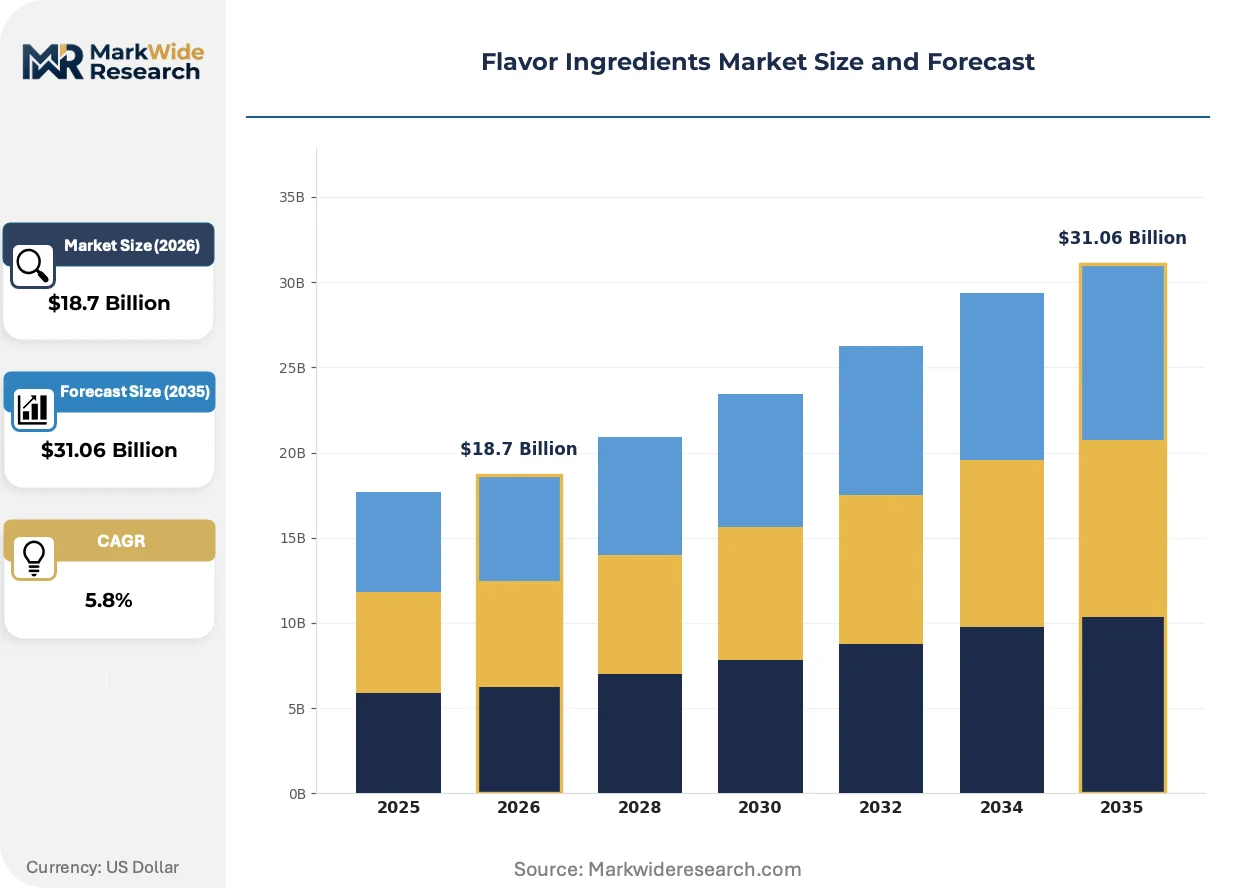
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Organic, Extracts Application: Beverages, Snacks, Bakery, Confectionery Form: Liquid, Powder, Granular, Paste End User: Food Manufacturers, Beverage Producers, Restaurants, Caterers |
| Companies Covered | Givaudan S.A., International Flavors & Fragrances Inc., Symrise AG, DSM-Firmenich AG, Sensient Technologies Corporation, Kerry Group plc, Firmenich SA, Takasago International Corporation, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavor Ingredients Market Trends and Innovations
Fermentation platforms and precision agriculture are decoupling aromatic compound production from traditional cultivation constraints. Regulatory divergence between Atlantic markets is fragmenting formulation standardization.
Precision fermentation technology converts microbial cell factories into scalable production vessels for complex aromatic molecules. Beverage manufacturers with clean-label commitments are accelerating adoption timelines from pilot to commercial scale. This biotechnology is expanding into cost-sensitive snack seasoning applications previously reserved for petrochemical-derived alternatives.
REACH regulation amendments and the EU F-Gas Regulation are tightening environmental accountability for solvent-based extraction processes. Industrial consequence includes mandatory carbon footprint disclosure for imported botanical derivatives. Natural extract suppliers serving European confectionery and dairy applications are investing in supercritical CO2 infrastructure to maintain market access.
Direct sourcing contracts between end-use manufacturers and cultivation cooperatives are displacing traditional multi-tier distribution. Ingredient procurement teams at multinational beverage and bakery corporations now negotiate multi-year offtake agreements with Madagascar vanilla and Haitian vetiver producers. This relationship compression is most visible in premium chocolate and spirits verticals where provenance authentication commands price premiums.
Flavor Ingredients Market Segmentation
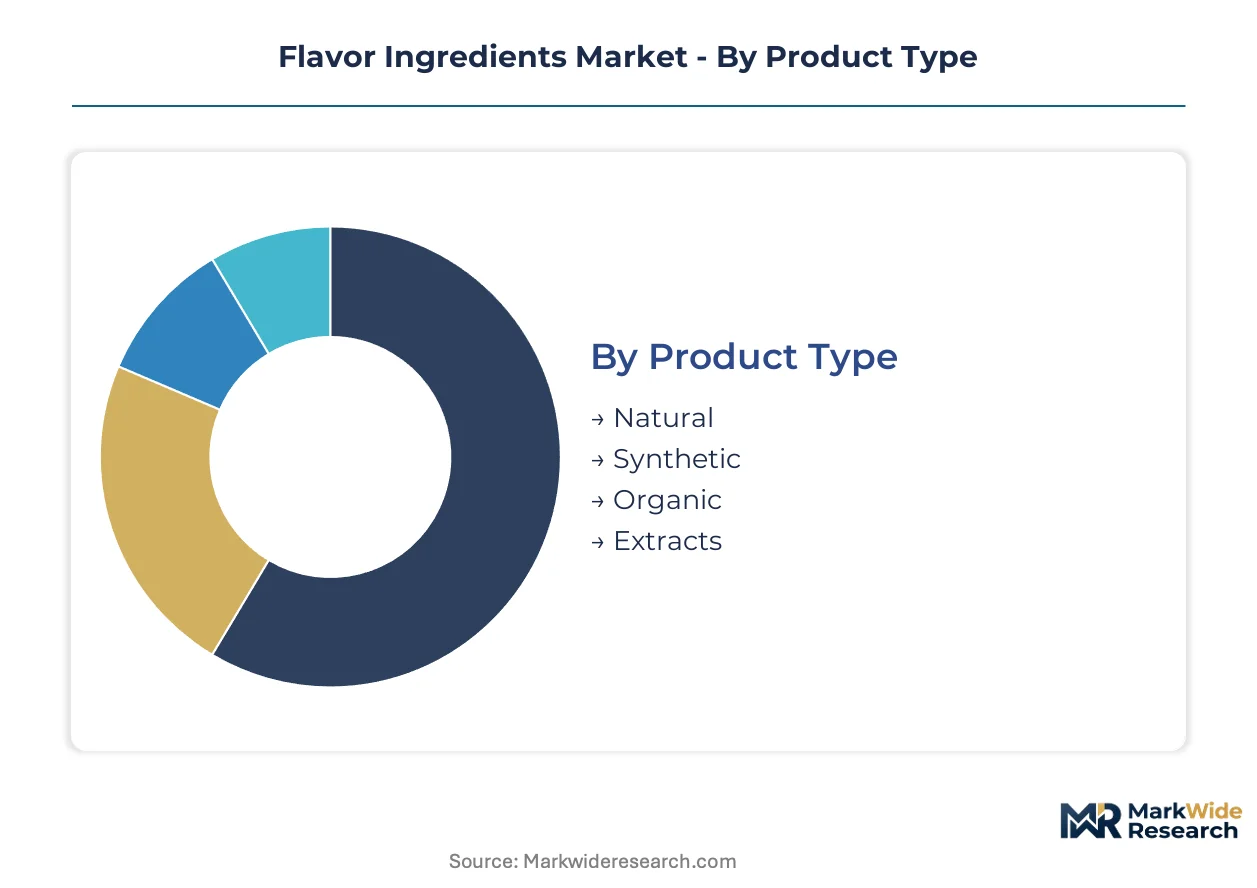
Flavor ingredient procurement patterns diverge sharply across formulation requirements, regulatory exposure, and processing infrastructure. Segmentation reveals where premium positioning commands margin and where commodity scale dominates volume economics.
Product Type:
Standardization intensity varies from batch-consistent synthetics to harvest-variable naturals, reshaping supplier qualification protocols and inventory strategies across the value chain.
- Natural:Botanical-derived volatile compounds, essential oils, and oleoresins extracted through steam distillation or solvent processing. Beverage producers in India are expanding procurement of natural extracts to satisfy FSSAI origin-labeling requirements and clean-label portfolio mandates, though Madagascar vanilla supply concentration exposes formulators to cyclone-driven price volatility.
- Synthetic:Petrochemical-derived aromatic molecules engineered for batch-to-batch consistency and cost efficiency. Snack seasoning manufacturers retain synthetic procurement for high-volume applications where EFSA positive-list compliance is already established and unit cost optimization governs formulation budgets.
- Organic:Certified botanical inputs grown without synthetic pesticides or fertilizers, commanding premium positioning in European confectionery channels where EU Green Deal Farm to Fork procurement standards restrict conventional additive sourcing.
- Extracts:Concentrated flavor preparations obtained through maceration, percolation, or supercritical CO2 processing, preferred by bakery manufacturers seeking moisture-stable delivery systems with extended shelf-life performance.
Most installed capacity flows through Synthetic. Expansion is steepest in Natural.
Application:
End-use intensity ranges from parts-per-million beverage dosing to percent-level snack seasoning, determining formulation service relationships and technical support requirements.
- Beverages:Liquid-dominant flavor systems requiring solubility optimization and heat stability for pasteurization regimes. Clean-label commitments from multinational beverage producers are redirecting procurement budgets toward fermentation-derived natural alternatives with Codex-aligned safety profiles.
- Snacks:Dry-mix and topical seasoning applications favoring powder formats with oil solubility and adhesion properties. Synthetic molecules retain cost advantages here, though biotechnology-conventional extraction convergence is narrowing the premium gap in mid-market savory categories.
- Bakery:Heat-stable flavor compounds formulated to withstand oven temperatures without volatilization or degradation. EFSA flavoring substance evaluations create compliance friction for novel molecule introduction relative to established GRAS-affirmed alternatives.
- Confectionery:Precision-dosed flavor systems balancing release kinetics with shelf-life stability, where supercritical CO2 extraction infrastructure is becoming mandatory for European market access under REACH solvent disclosure amendments.
Volume concentrates in Beverages. Margin expansion is strongest in Confectionery.
Form:
Physical state determines processing line compatibility, moisture sensitivity, and distribution economics across manufacturing footprints.
- Liquid:Solvent-based or oil-carrier solutions offering processing flexibility for industrial batching and automated dosing systems. Most legacy manufacturing infrastructure is optimized for liquid handling, preserving incumbent supplier relationships.
- Powder:Encapsulated or spray-dried formats enabling moisture-stable storage and dry-mix incorporation. Instant beverage and confectionery platforms are accelerating powder adoption, forcing capital retooling of liquid-optimized production lines.
- Granular:Free-flowing particulate systems for topical snack seasoning with controlled particle size distribution. Oil absorption and adhesion properties govern technical specification.
- Paste:High-viscosity concentrates for bakery and confectionery applications requiring precise portion control and minimal moisture addition.
Processing infrastructure favors Liquid. Adoption velocity is highest in Powder.
End User:
Customer scale spans multinational manufacturing to distributed foodservice, fragmenting sales channel configuration and technical service intensity.
- Food Manufacturers:Large-scale processors with captive R&D and quality assurance functions negotiating direct sourcing contracts with cultivation cooperatives for provenance authentication.
- Beverage Producers:Category-specific formulators prioritizing supply security over unit cost, driving multi-year offtake agreements with Madagascar vanilla and Haitian vetiver suppliers.
- Restaurants:Distributed foodservice operators sourcing through broadline distribution with limited technical specification control.
- Caterers:Event-scale food preparation with volatile demand patterns and minimal inventory carrying capacity.
Procurement volume aggregates at Food Manufacturers. Relationship compression is most advanced with Beverage Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grasse, France anchors the highest concentration of flavor ingredient R&D infrastructure worldwide, with formulation laboratories clustering around historic essential oil distillation heritage. Procurement teams from multinational beverage and confectionery manufacturers maintain permanent technical liaison offices in this Alpes-Maritimes hub. Regional demand patterns diverge sharply between Atlantic regulatory jurisdictions and Asia-Pacific processing scale economies.
United States
Beverage producers in California and Texas are expanding fermentation-derived natural flavor procurement to satisfy clean-label portfolio mandates. FDA GRAS self-affirmation pathways enable faster novel molecule introduction than European counterparts, attracting R&D-intensive suppliers to Chicago and New Jersey technical centers. Indianapolis hosts concentrated snack seasoning formulation activity where synthetic molecules retain cost advantages in high-volume applications.
Germany
Confectionery manufacturers in Cologne and Hamburg are investing in supercritical CO2 extraction infrastructure to maintain European market access under REACH solvent disclosure amendments. EFSA positive-list compliance requirements create eighteen-to-thirty-six-month approval timelines that favor established molecule portfolios over novel introductions. Bavaria's dairy processing clusters drive demand for heat-stable flavor compounds formulated to withstand ultra-high-temperature treatment regimes.
India
FSSAI labeling harmonization with Codex Alimentarius frameworks is redirecting procurement budgets toward domestic oleoresin and essential oil producers in Maharashtra and Gujarat. PLI scheme incentives for food processing accelerate flavor compound production capacity expansion in Karnataka and Tamil Nadu. Mumbai-based beverage formulators negotiate multi-year offtake agreements with Madagascar vanilla suppliers to secure provenance-authenticated supply chains.
China
Dual carbon goals under MEE oversight are tightening environmental accountability for solvent-based extraction processes in Guangdong and Jiangsu provinces. Shanghai and Hangzhou host concentrated precision fermentation R&D activity targeting scalable production of rare aromatic compounds. NMPA alignment with international food additive standards is accelerating import substitution for high-value natural extracts previously sourced from Southeast Asian suppliers.
Brazil
São Paulo's beverage manufacturing corridor is expanding procurement of tropical fruit extracts and native botanical derivatives for regional clean-label product lines. ANVISA progressive harmonization with FDA safety assessment frameworks reduces dual-jurisdiction compliance burdens for multinational suppliers. Campinas clusters fermentation technology providers serving cost-sensitive snack seasoning applications where biotechnology-derived alternatives narrow the premium gap with synthetic chemistry.
Flavor Ingredients Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fermentation-derived specialty molecules and captive botanical cultivation partnerships. The supplier base concentrates around integrated flavor houses with captive R&D and quality assurance functions, while mid-tier processors compete on regional formulation service intensity. Three archetypes dominate: biotechnology-anchored precision fermentation specialists, vertically integrated botanical extractors with cooperative sourcing contracts, and diversified ingredient conglomerates leveraging manufacturing scale across multiple production hubs. Competitive dynamics center on M&A activity consolidating regional formulation capabilities and strategic partnerships securing multi-year offtake agreements with Madagascar and Haitian cultivation cooperatives.
Within the integrated multinational tier, Givaudan S.A., Symrise AG, and DSM-Firmenich AG exemplify divergent strategic positioning. Givaudan S.A. occupies a position emphasizing captive cultivation partnerships in biodiversity-rich sourcing regions. Symrise AG exemplifies biotechnology-intensive competitiveness through fermentation-derived molecule platforms. DSM-Firmenich AG represents manufacturing scale advantages sustained across European and Asian production infrastructure. These three entities anchor the premium tier where supply security commitments and regulatory navigation capabilities command formulation budget allocation from multinational beverage and confectionery manufacturers.
| Leading Market Players |
|---|
| Givaudan S.A. |
| International Flavors & Fragrances Inc. |
| Symrise AG |
| DSM-Firmenich AG |
| Sensient Technologies Corporation |
| Kerry Group plc |
| Firmenich SA |
| Takasago International Corporation |
| Archer Daniels Midland Company |
| Others |
Pricing and Supply Chain Analysis
Madagascar vanilla bean futures and cyclone-disruption indices cascade through three distinct pricing tiers, compressing margins for processors without captive cultivation contracts while amplifying premiums for provenance-authenticated supply chains serving European confectionery and spirits manufacturers.
Pricing Analysis
Input-cost pass-through from botanical harvest volatility governs pricing dynamics across natural extract portfolios. Three-tier pricing structure across premium, standard, and economy levels separates certified organic Madagascar vanilla from conventional Haitian vetiver and commodity-grade oleoresin alternatives. Price differentiation centers on certification grade and volume scale, with FSSAI origin-labeling compliance commanding premiums in India. Pricing pressure stems from cyclone-driven supply interruptions that force inventory carrying costs onto processors. Snack seasoning manufacturers exhibit highest price sensitivity, while beverage producers prioritize supply security over unit cost optimization.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for oleoresin and essential oil inputs, accelerating capacity expansion in Maharashtra and Gujarat. Madagascar, Haiti, and India concentrate botanical cultivation, while Germany and France anchor extraction infrastructure. Raw material dependencies center on vanilla beans, vetiver roots, and tropical fruit feedstocks. Supply chain risk crystallizes around single-source vulnerability from cyclone exposure in Madagascar. Distribution runs through direct sourcing contracts between multinational beverage manufacturers and cultivation cooperatives, displacing traditional multi-tier distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Flavor Ingredients Market functions as a stable compounder anchored by regulatory-driven clean-label mandates that perpetually redirect formulation budgets toward natural extract procurement.
For Market Incumbents: Deepen captive cultivation partnerships in Madagascar and Haiti to secure vanilla and vetiver supply chains against cyclone disruption. Expand supercritical CO2 extraction infrastructure in Germany to maintain European market access under REACH solvent disclosure amendments. Precision fermentation platforms from emerging biotechnology specialists threaten established synthetic molecule portfolios. For New Entrants and Emerging Players: EU Green Deal Farm to Fork strategy in Europe opens a window for fermentation-derived natural alternatives previously constrained by agricultural harvest cycles. Target powder format penetration in dry-mix confectionery and instant beverage platforms where moisture-stable delivery systems command formulation partnerships. Pursue enzymatic pre-treatment technology licensing to achieve unit cost parity with synthetic alternatives in mid-market savory applications. For Investors and Strategic Acquirers: Asymmetric upside sits with precision fermentation specialists possessing scalable production platforms for rare aromatic compounds. Long-term viability favors biotechnology-anchored entities with regulatory navigation capabilities spanning FDA GRAS and EFSA positive-list frameworks. Monitor EFSA novel molecule approval timelines as inflection indicator for R&D investment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Cultivation Partnership | Madagascar and Haitian cooperative contracts secure provenance-authenticated vanilla supply against cyclone volatility. |
| Precision Fermentation Scale-Up | Microbial cell factory platforms enable cost-competitive production of rare aromatic compounds for beverage applications. |
| Supercritical CO2 Infrastructure Investment | REACH-compliant extraction technology maintains European confectionery market access under solvent disclosure mandates. |
| FSSAI Certification Investment | Codex-aligned additive standards and origin-labeling compliance create first-mover advantage in India procurement. |
| Enzymatic Pre-Treatment Licensing | Biotechnology-conventional extraction convergence improves essential oil yields for mid-market cost parity. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Primary interviews engaged flavor chemists, procurement leads at multinational beverage manufacturers, regulatory affairs directors, cultivation cooperative managers, and supercritical extraction plant engineers. Secondary sources incorporated FSSAI additive notifications, EFSA flavoring substance evaluations, FDA GRAS affirmation records, and customs trade data for oleoresin and essential oil flows. Bottom-up volume modeling triangulated against top-down expenditure analysis across formulation budgets.
Rate-of-change decomposition anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, application intensity, physical form, and end-user scale, with regulatory jurisdiction clusters treated as a cross-cutting variable. CAGRs derived from weighted average of historical trajectory and policy-induced inflection assumptions. Industry-specific inputs included vanilla harvest forecasts from Madagascar agricultural ministries and PLI scheme capacity expansion timelines from Indian state industrial development corporations.
Revisions become necessary when cyclone frequency intensifies beyond historical baselines, EFSA positive-list expansion accelerates, or fermentation technology cost curves steepen beyond modeled assumptions. Forecasts reflect documented assumptions about regulatory harmonization progress and biotechnology adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Smoked Dextrose Market
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market
Flavorings and Food Additives
Japan Food Colorants Market
Flavorings and Food Additives
Dry Powder Flavors Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Dairy Flavors Market
Flavorings and Food Additives
Argentina Food Flavor and Enhancer Market
Flavorings and Food Additives
Lemon Essential Oil Market
Flavorings and Food Additives
Edible Food Paints Market
Flavorings and Food Additives
Australia Vanilla Flavor Market
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
Food Aroma Market
Flavorings and Food Additives
Royal Jelly Extract Market
Flavorings and Food Additives
All-Natural Flavors System Market