
 Instant Curry Market | 2026-2036
Instant Curry Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Curry Market Insights
Single-serve pouch bundling into multi-flavor variety packs is hardening as the dominant retail configuration, forcing manufacturers to rethink production line flexibility. Ottogi leverages its Korean domestic scale to anchor premium paste assortments in bundled formats. House Foods Corporation sustains R&D intensity on retort technology for shelf-stable curry. S&B Foods competes through specialized regional flavor portfolios that occupy distinct convenience store shelf positions.
Instant curry comprises dehydrated or thermally processed spice-and-roux formulations, typically containing turmeric, coriander, cumin, and fenugreek in standardized Scoville-consistent profiles, manufactured through blending, extrusion, or retort sterilization for rapid meal preparation. The powder segment retains mature volume leadership in South Asian household pantries where consumers prioritize cost-per-serving and customization control. Ready-to-eat pouches represent the fastest-expanding margin pool, particularly in Japanese and Korean convenience channels where heating time under ninety seconds determines purchase. Paste formats in jar packaging capture specialty store premiums through authentic positioning and extended refrigeration stability.
Japan's Ministry of Health, Labour and Welfare enforces Food Sanitation Act standards that mandate allergen labeling and additive ceilings for retort curry products, directly shaping formulation costs and export eligibility. Thailand's FDA aligns with CODEX Alimentarius guidelines for spice purity while imposing local microbiological limits that filter small-scale importers. The EU's REACH regulation and F-Gas framework indirectly pressure packaging material choices for European-bound production. Stakeholders must monitor evolving front-of-pack labeling mandates across their priority export corridors to preempt reformulation cycles and maintain shelf access.
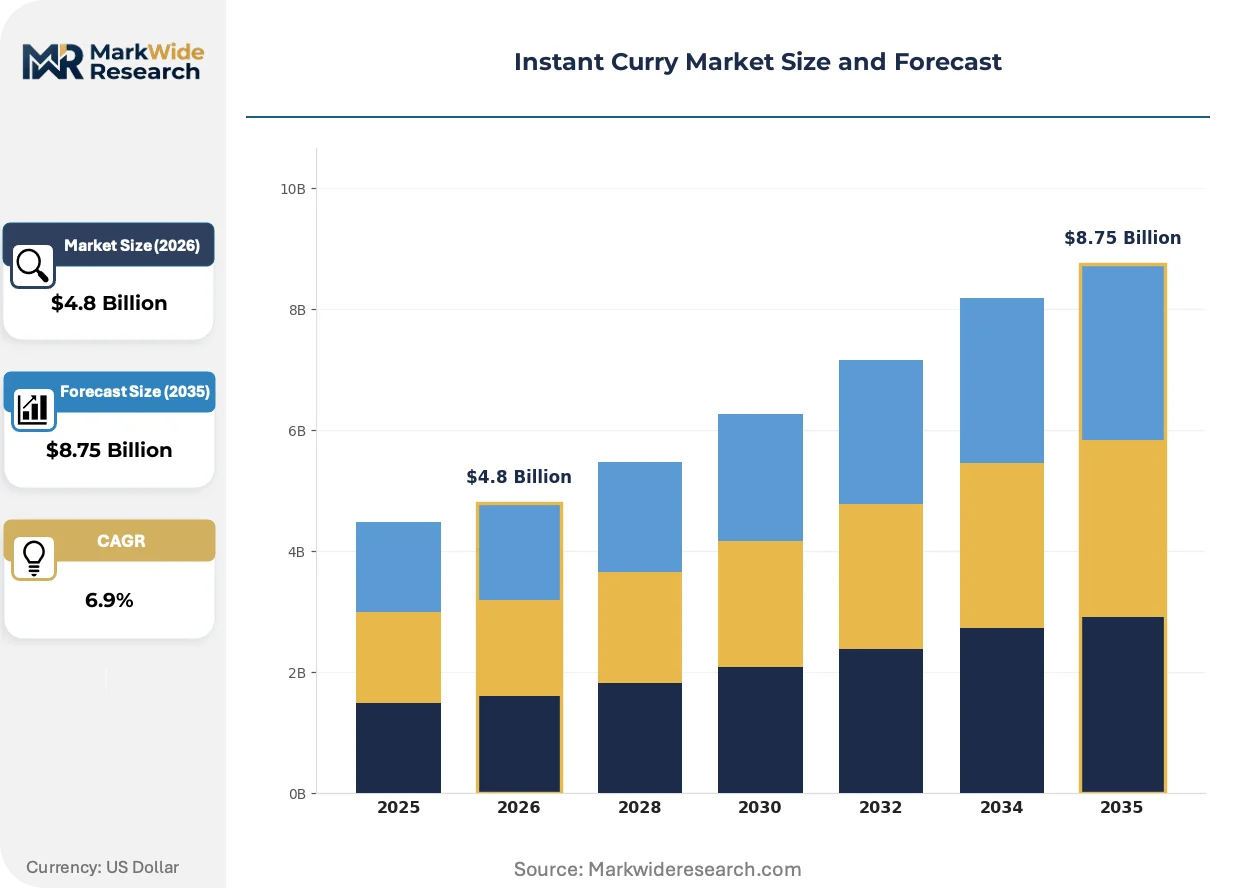
Market Dynamics
Retort sterilization technology is compressing production cycle times while Japan's Food Sanitation Act revisions force simultaneous reformulation investments, creating a capital efficiency squeeze that favors manufacturers with flexible multi-format lines.
Growth Catalysts
- Quick-service restaurant expansion:Southeast Asian fast-food chains are absorbing ready-to-eat pouches at volume, converting industrial-zone canteens into high-throughput distribution nodes for single-serve formats.
- CODEX-aligned harmonization:Thailand's FDA adoption of international spice purity standards is reducing cross-border testing burdens for exporters targeting Bangkok metropolitan retail clusters.
- Convenience channel density:Japanese and Korean convenience stores now stock heated curry within arm's-reach of checkout, cutting consumer decision time below ninety seconds and driving impulse purchase velocity.
Market Restraints
- Raw material concentration:Turmeric and cumin supply concentrates in Indian agricultural belts, exposing processors to monsoon-driven harvest volatility and quality inconsistency.
- Additive disclosure ceilings:Japan's Food Sanitation Act mandates granular additive labeling that inflates packaging redesign costs and disqualifies legacy formulations from shelf eligibility.
- Refrigerated paste competition:Jarred curry pastes with extended chill stability are capturing specialty store premiums, diverting margin from ambient-stable retort formats.
Strategic Opportunities
- Industrial zone penetration:Thailand's eastern seaboard manufacturing corridors remain underserved by branded instant curry, presenting white-space entry for retort pouch suppliers.
- EU packaging compliance:REACH and F-Gas frameworks are filtering out non-compliant Asian exporters, creating shelf vacancy for producers investing in compliant barrier films.
- Multi-flavor bundling:Single-serve variety packs are hardening as the dominant retail configuration, rewarding production lines capable of rapid changeover between Scoville profiles.
Industry Challenges
- Retort engineering talent scarcity:Specialized thermal processing engineers capable of optimizing sterilization cycles for spice-heavy matrices command premium wages and limited geographic mobility.
- Legacy line retrofit costs:Existing dehydration equipment requires substantial capital outlay to accommodate pouch-format flexibility, straining mid-tier manufacturer balance sheets.
- Allergen testing throughput:Japan's mandated allergen screening for fenugreek and coriander derivatives is extending batch release timelines and compressing working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Curry Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.75 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Paste, Ready-to-Eat, Sauce Distribution Channel: Online, Supermarkets, Specialty Stores, Convenience Stores Packaging Type: Pouches, Tins, Jars, Sachets End User: Households, Restaurants, Food Service, Catering |
| Companies Covered | Ottogi, House Foods Corporation, S&B Foods, Unilever, Nestlé, ASDA, Premium Golden, Aroy-D, Thai President Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Curry Market Trends and Innovations
Automation of sterilization monitoring and front-of-pack transparency mandates are converging to reshape competitive requirements. Manufacturers must now synchronize line intelligence with regulatory documentation systems.
AI-driven thermal profiling is automating retort cycle optimization for complex spice matrices. Mid-tier Japanese processors are deploying these systems to reduce over-processing waste while maintaining Food Sanitation Act compliance. The technology is automating quality variance reduction that previously required manual technician intervention.
Japan's Food Sanitation Act revisions are tightening additive disclosure rules and pushing manufacturers toward clean-label reformulations. The industrial consequence is accelerated R&D spend on natural preservation alternatives. Retort curry exporters targeting Japanese convenience channels are responding by front-loading stability testing to preempt regulatory rejection.
Single-serve pouch bundling into multi-flavor variety packs is displacing standalone SKU dominance in Japanese and Korean convenience retail. Convenience store chains are consolidating shelf space behind curated assortments rather than individual flavor blocks. This pattern is most visible in Tokyo and Osaka metropolitan areas where space constraints favor density-optimized merchandising.
Instant Curry Market Segmentation
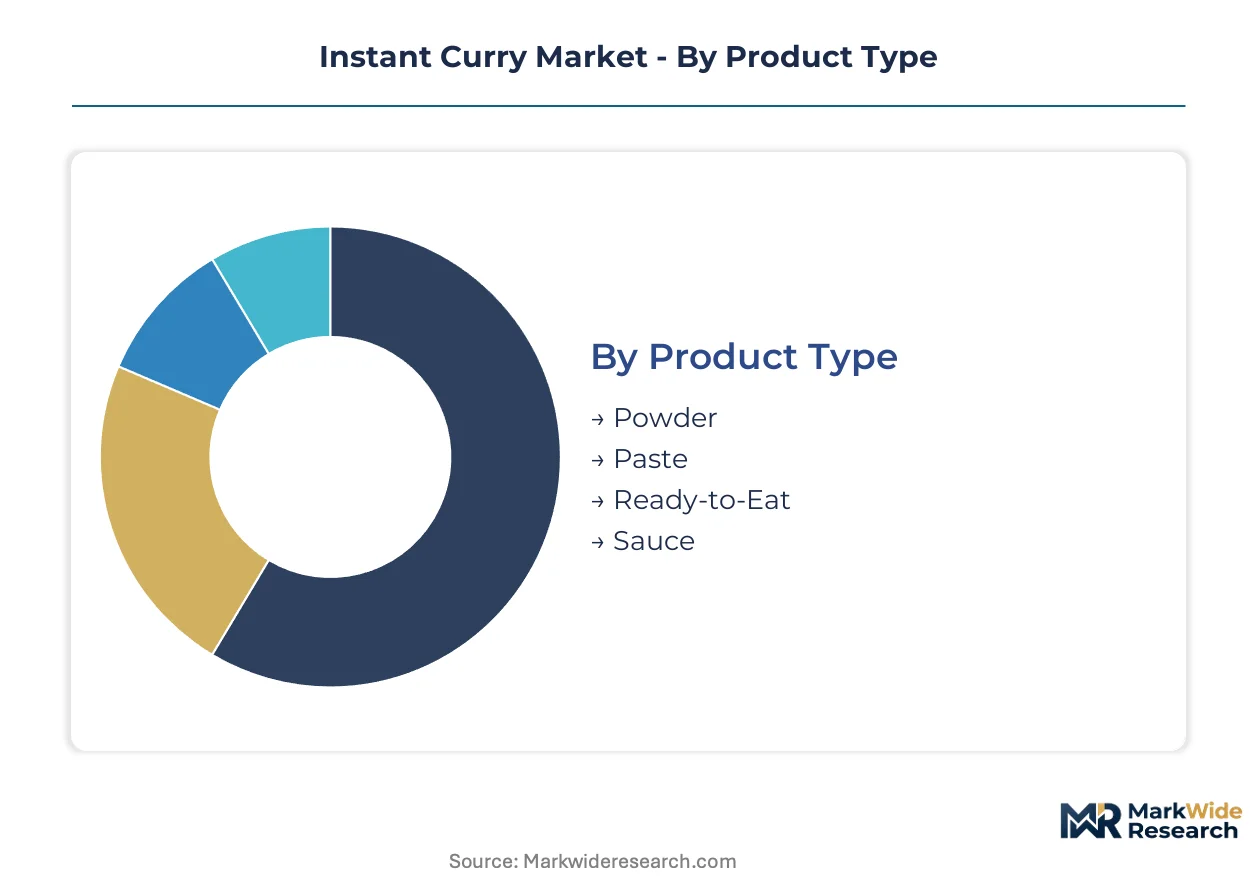
Instant curry manufacturers navigate distinct demand profiles across preparation formats, with powder formats commanding household volume while ready-to-eat pouches capture convenience premiums. Channel and packaging configurations further stratify margin structures, requiring production assets calibrated to specific throughput and shelf-life specifications.
Product Type:
Powder formats anchor volume leadership through cost-per-serving efficiency, while paste and ready-to-eat alternatives extract premium positioning through preparation speed and flavor authenticity.
- Powder:Dehydrated spice-and-roux blends containing turmeric, coriander, cumin, and fenugreek in standardized Scoville profiles. South Asian household pantries in India and Pakistan prioritize this format for customization control and extended shelf stability without refrigeration.
- Ready-to-Eat:Retort-sterilized pouches requiring under ninety seconds of heating. Japanese and Korean convenience channels absorb this format fastest, with Tokyo metropolitan stores positioning heated units at checkout proximity to compress decision time.
- Paste:Concentrated curry bases in jar packaging with extended refrigeration stability. Specialty retailers in Bangkok and Osaka capture authentic positioning premiums through this format.
- Sauce:Pre-thickened liquid formulations targeting food service batch preparation. Industrial canteens across Thailand's eastern seaboard manufacturing corridors specify this format for portion consistency.
Today's leader: Powder. Tomorrow's challenger: Ready-to-Eat.
Distribution Channel:
Channel selection determines packaging format requirements, heating infrastructure obligations, and inventory velocity expectations across retail and food service touchpoints.
- Convenience Stores:Heated display units within arm's-reach of checkout drive impulse velocity for single-serve pouches. Japanese chains now consolidate shelf space behind multi-flavor variety packs rather than individual SKUs.
- Supermarkets:Multi-format assortments spanning powder blocks, jarred pastes, and bundled pouch varieties. Bangkok metropolitan retailers allocate premium shelf positioning to House Foods and S&B regional flavor portfolios.
- Online:Direct-to-consumer bundling of multi-flavor assortments with subscription replenishment. Korean domestic platforms leverage Ottogi's scale for premium paste assortment anchoring.
- Specialty Stores:Authentic positioning through extended refrigeration stability and artisanal provenance claims. Jarred pastes command margin premiums in this channel.
Convenience stores concentrate the steepest expansion trajectory; online channels are climbing fastest in subscription penetration.
Packaging Type:
Barrier properties and format flexibility shape export eligibility, with retort pouch engineering separating compliant exporters from filtered competitors.
- Pouches:Flexible retort-sterilized films with multi-layer barrier construction. EU REACH and F-Gas frameworks filter non-compliant Asian exporters, creating shelf vacancy for producers investing in compliant materials.
- Jars:Glass or PET containers with extended chill stability for paste formats. Specialty store premiums in Japan and Thailand depend on this packaging for authenticity signaling.
- Tins:Metal cans for bulk institutional formats. Food service procurement in Thailand's industrial zones specifies this packaging for portion control.
- Sachets:Single-serve flexible packets for trial and travel formats. Powder samples and sauce portions utilize this configuration.
Pouches dominate convenience velocity; jars defend specialty margins.
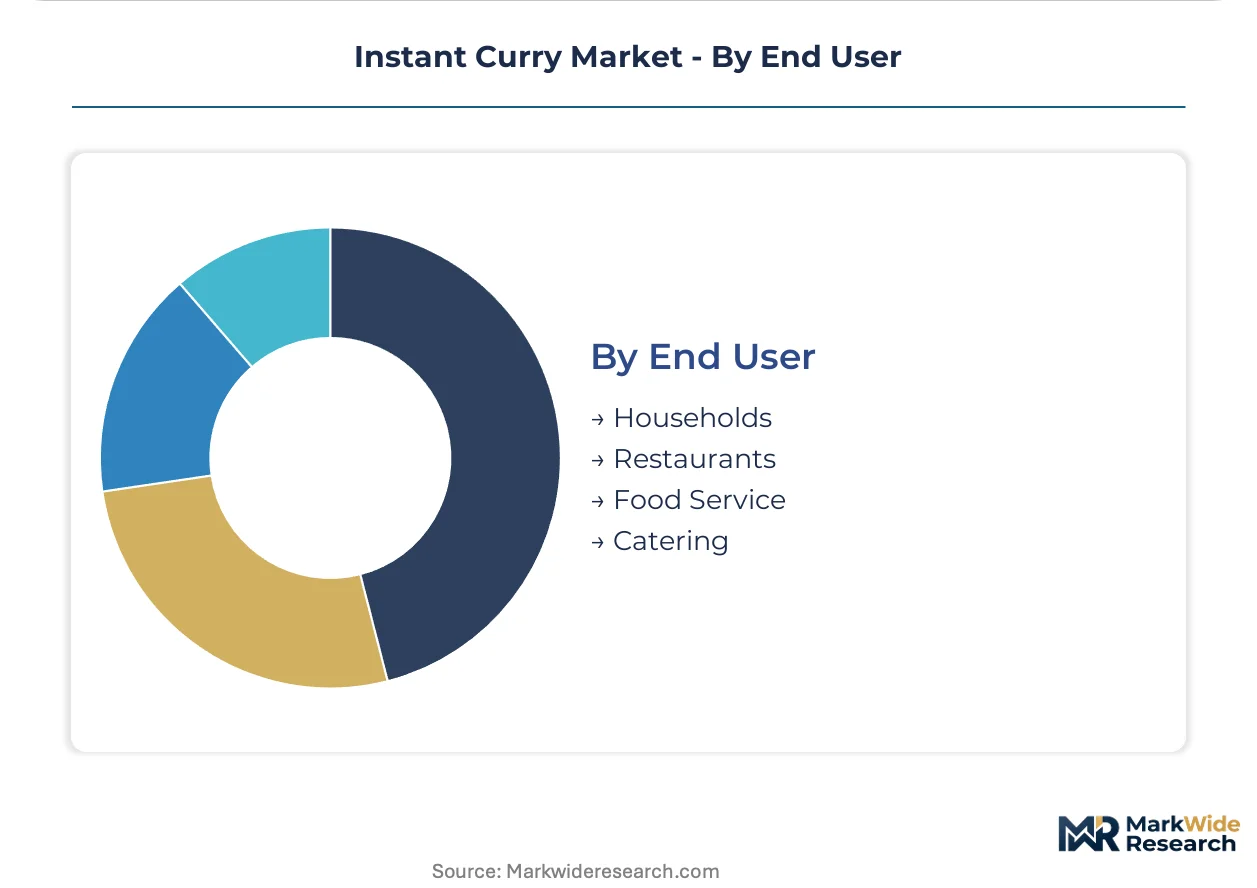
End User:
User segmentation dictates Scoville consistency requirements, batch sizing, and heating infrastructure investment.
- Households:Individual and family-sized preparations across powder, paste, and ready-to-eat formats. Customization preference in South Asia sustains powder demand; speed priority in East Asia drives pouch adoption.
- Restaurants:Consistent batch preparation requiring standardized spice profiles. Quick-service chains in Southeast Asia absorb ready-to-eat pouches at volume for menu standardization.
- Food Service:Industrial canteens and institutional feeding operations. Thailand's eastern seaboard manufacturing corridors present white-space entry for retort pouch suppliers targeting this segment.
- Catering:Event-scale preparation with portion predictability requirements. Sauce formats dominate this application for batch efficiency.
Households retain volume concentration; food service is gaining share fastest in Southeast Asian industrial zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instant curry industrialized in post-war Japan, where retort sterilization technology first scaled for shelf-stable roux blocks. Commercial production migrated to South Korea and Thailand as convenience channel density expanded across East Asia.
Japan
Tokyo and Osaka metropolitan convenience stores drive single-serve pouch velocity through heated checkout-proximity displays. Japan's Ministry of Health, Labour and Welfare enforces Food Sanitation Act standards mandating allergen labeling and additive ceilings. Nagoya's Chubu industrial corridor hosts retort engineering specialists optimizing sterilization cycles for spice-heavy matrices.
South Korea
Seoul Capital Area consumers absorb premium paste assortments through subscription-enabled online platforms. The Ministry of Food and Drug Safety (MFDS) regulates spice purity under harmonized CODEX-aligned frameworks. Busan-Ulsan manufacturing zones supply pouch-format flexibility for multi-flavor bundling configurations.
Thailand
Bangkok metropolitan retail clusters and eastern seaboard industrial canteens absorb ready-to-eat formats for quick-service restaurant standardization. Thailand's FDA imposes local microbiological limits beyond CODEX Alimentarius spice purity guidelines. Rayong manufacturing corridors present white-space entry for retort pouch suppliers targeting institutional food service.
India
South Asian household pantries in Maharashtra and Gujarat sustain powder format demand through cost-per-serving efficiency priorities. The Food Safety and Standards Authority of India (FSSAI) governs spice additive thresholds and labeling requirements. Turmeric and cumin supply concentrates in Andhra Pradesh agricultural belts, exposing processors to monsoon-driven harvest volatility.
United Kingdom
London and Southeast retail channels stock multi-format assortments spanning powder blocks and jarred pastes for diaspora and mainstream consumers. The Food Standards Agency enforces EU-retained REACH and F-Gas framework compliance for packaging materials. Midlands distribution hubs filter non-compliant Asian exporters, creating shelf vacancy for barrier-film-compliant producers.
Instant Curry Market Competitive Landscape
Premium-margin players sit above commodity-margin players across retort engineering capability and convenience channel access. The vendor base stratifies into three tiers: multinational FMCG conglomerates with diversified spice portfolios, regional specialists concentrating single-format excellence, and private-label suppliers serving retail consolidation. Dominant competitive moves include production line flexibility investments for multi-flavor bundling and backward integration into spice sourcing to defend against agricultural volatility.
Within the regional specialist tier, Ottogi and House Foods Corporation exemplify scale-driven format diversification, while S&B Foods occupies a position defined by specialized regional flavor portfolios. These three companies represent distinct archetypes: the Korean domestic market anchor, the Japanese retort technology incumbent, and the convenience channel curator respectively.
| Leading Market Players |
|---|
| Ottogi |
| House Foods Corporation |
| S&B Foods |
| Unilever |
| Nestlé |
| ASDA |
| Premium Golden |
| Aroy-D |
| Thai President Foods |
| Others |
Pricing and Supply Chain Analysis
Turmeric and cumin procurement costs from Indian agricultural belts flow through three distinct pricing tiers downstream, with monsoon-driven harvest volatility compressing margins at the economy end while premium retort pouch formats absorb input inflation through convenience store channel power.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs instant curry markets, with differentiation driven by retort engineering sophistication and CODEX-aligned certification status. Price differentiation intensifies as Japanese Food Sanitation Act compliance costs filter non-compliant exporters from convenience channel access. Margins are tightening due to additive disclosure mandate compliance investments. Food service buyers in Thailand's industrial zones exhibit highest price sensitivity; Japanese convenience channel operators show lowest sensitivity due to velocity-driven throughput economics.
Supply Chain Analysis
Spice input supply rests on Indian agricultural concentration for turmeric and cumin, Japanese retort film engineering for pouch barriers, and Thai manufacturing for quick-service restaurant format assembly. Raw material dependencies span monsoon-exposed harvest cycles, EU REACH-compliant packaging substrates, and fenugreek allergen testing protocols. Single-source vulnerability concentrates in Indian spice belt weather exposure. Distribution runs through Japanese convenience store heated display networks and Bangkok metropolitan retail clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Instant curry markets function as a geographic-arbitrage play between Japanese regulatory stringency and Thai industrial zone cost bases, with Food Sanitation Act compliance investments in Tokyo-Osaka corridors creating margin expansion opportunities for producers locating formulation in Southeast Asian manufacturing zones.
For Market Incumbents: Cement retort engineering capability advantages through Nagoya Chubu corridor talent retention and multi-flavor bundling line flexibility investments. House Foods Corporation and Ottogi scale positions defend against private-label consolidation by anchoring premium paste assortments in subscription-enabled Korean domestic platforms. Backward integration into Andhra Pradesh spice sourcing hedges monsoon volatility exposure.
For New Entrants and Emerging Players: Industrial canteen buyers across Thailand's eastern seaboard manufacturing corridors represent the most penetrable white-space target, with Rayong food service procurement specifying sauce formats for batch consistency. Quick-service restaurant chains in Bangkok metropolitan areas absorb ready-to-eat pouches at volume for menu standardization. Go-to-market through Thai FDA CODEX-aligned certification accelerates cross-border eligibility.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier retort pouch specialists because Japan's additive disclosure ceilings are filtering legacy formulation assets at distressed valuations. Long-term viability centers on production line flexibility for variety pack configurations and EU REACH-compliant barrier film capabilities. Watch Thai FDA microbiological limit enforcement as inflection indicator for export eligibility compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Retort Line Flexibility Investment | Multi-flavor bundling capability captures Japanese convenience store shelf consolidation toward variety packs. |
| Backward Integration into Spice Sourcing | Andhra Pradesh turmeric procurement hedges monsoon-driven harvest volatility compressing economy-tier margins. |
| EU REACH-Compliant Packaging Transition | Barrier film compliance creates shelf vacancy in London and Southeast retail channels filtering non-compliant Asian exporters. |
| Clean-Label Reformulation R&D | Natural preservation alternatives preempt Japan's Food Sanitation Act regulatory rejection risk for retort curry exports. |
| Industrial Zone Distribution Expansion | Thailand's eastern seaboard manufacturing corridors present white-space entry for retort pouch suppliers targeting institutional food service procurement. |
Research Methodology
Multiple input streams — executive interviews with retort engineering specialists and convenience channel buyers, customs records of spice and packaging material trade flows, and regulatory filing analysis of Japan's Ministry of Health, Labour and Welfare standards — were reconciled through bottom-up manufacturing capacity assessment and top-down retail velocity estimation. Primary engagement spanned plant managers at Thai and Korean processing facilities, category buyers at Tokyo metropolitan convenience store chains, and procurement leads at Bangkok quick-service restaurant operators. Secondary validation drew from Thai FDA CODEX alignment documentation, EU REACH substance restriction databases, and Food Safety and Standards Authority of India additive threshold notifications.
Segmentation-level projections across powder, ready-to-eat, paste, and sauce formats were modeled against convenience store channel density metrics, industrial canteen procurement patterns, and subscription platform penetration rates throughout the forecast period. CAGRs were derived from reconciling historical production volume trends with forward-looking retail space allocation shifts. Industry-specific inputs included retort sterilization cycle optimization rates and front-of-pack labeling mandate implementation timelines across priority export corridors.
Inputs from Japanese and Thai regulatory filings were available through the study window; gaps in real-time spice harvest yield data introduce uncertainty bands around raw material cost assumptions. Forecasts reflect documented assumptions about convenience channel expansion velocity and additive disclosure compliance cost trajectories. Monsoon severity, EU packaging framework enforcement intensity, and retort engineering talent mobility warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Yogurt Dip Market
Processed Foods
China Freeze-Dried Food Market
Processed Foods
Africa Soup Market
Processed Foods
Low Moisture Food Market
Processed Foods
Europe Soup Market
Processed Foods
United States Fresh Noodles Market
Processed Foods
Accompanying Marinated Product Market
Processed Foods
India Ready to Mix Food Market
Processed Foods
Fermented Foods Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Asia-Pacific Soup Market
Processed Foods
Low Fat Soups Market
Processed Foods
Noodles Market
Processed Foods
Soup & Broth Market
Processed Foods
Dairy Desserts Market
Processed Foods
Europe Egg Powder Market