
 Browning Solutions Market | 2026-2036
Browning Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Browning Solutions Market Analytics
The EU Green Deal is expanding the addressable market for enzymatic and natural browning solutions as European food manufacturers reformulate away from synthetic caramel colorants. Kerry Group PLC leverages its enzyme technology portfolio to capture premium clean-label contracts across continental Europe. Cargill anchors supply security through backward integration into maize-derived dextrose feedstocks for Maillard reaction precursors. Royal DSM competes on fermentation-derived browning intermediates that bypass traditional thermal processing.
Browning solutions encompass chemical and biological formulations that catalyze or enhance the Maillard reaction and caramelization in food matrices, typically operating at temperatures between 110°C and 180°C with pH ranges of 4.0 to 8.0 to achieve target color development in baked goods, beverages, and savory applications. The application dimension shows hunting and sport shooting representing mature volume channels with stable replacement cycles, while law enforcement procurement is shifting toward optics-integrated platforms that demand specialized finishing treatments. Within distribution channels, specialty stores sustain margin pools through technical consultation and customization services that online retail cannot replicate.
The European Food Safety Authority enforces strict purity criteria for caramel colors under E150a-d classifications, while the U.S. FDA maintains GRAS oversight for enzymatic browning preparations used in processed foods. These frameworks compel manufacturers to maintain dual certification portfolios for transatlantic market access. Stakeholders must monitor evolving classification debates around 4-MeI levels in Class III and IV caramel colors, as regulatory tightening in one jurisdiction typically cascades into buyer specification changes across others.
Market Dynamics
Clean-label reformulation is compressing demand for synthetic caramel colorants across European food manufacturing, forcing ingredient suppliers to rebuild portfolios around enzymatic and fermentation-derived alternatives that satisfy EFSA purity criteria while maintaining Maillard reaction performance.
Growth Catalysts
- EU Green Deal disclosure mandates:Tightening additive transparency rules across Germany, France, and Italy are compelling manufacturers to replace E150c and E150d classifications with natural browning precursors.
- Enzymatic browning technology:Advances in polyphenol oxidase stabilization are enabling cold-process color development in beverage applications previously dependent on thermal caramelization.
- Bakery sector concentration:Industrial bread and pastry producers in the European food manufacturing belt are consolidating procurement around single-source clean-label ingredient systems.
Market Restraints
- Maize feedstock volatility:Dextrose precursor costs fluctuate with agricultural commodity cycles, squeezing margins for Maillard reaction-based browning agents.
- EFSA 4-MeI thresholds:Stricter purity criteria for Class III and IV caramel colors are forcing costly reformulation or product withdrawal across multiple applications.
- Natural extract supply concentration:Apple and pear-derived enzymatic sources cluster in limited European growing regions, creating geographic vulnerability.
Strategic Opportunities
- Fermentation-derived intermediates:Microbial production of browning precursors bypasses agricultural feedstock constraints and thermal processing entirely.
- Savory application expansion:Meat analog and plant-based protein manufacturers represent underpenetrated demand for umami-enhancing Maillard reaction systems.
- Specialty store channel development:Technical consultation services in ingredient distribution create premium positioning unavailable through commodity procurement.
Industry Challenges
- Dual certification complexity:Manufacturers must maintain parallel EFSA and FDA compliance portfolios for transatlantic market access, extending product development timelines.
- Enzyme stability expertise gap:Formulation chemists with polyphenol oxidase stabilization experience remain scarce relative to synthetic colorant specialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Browning Solutions Market |
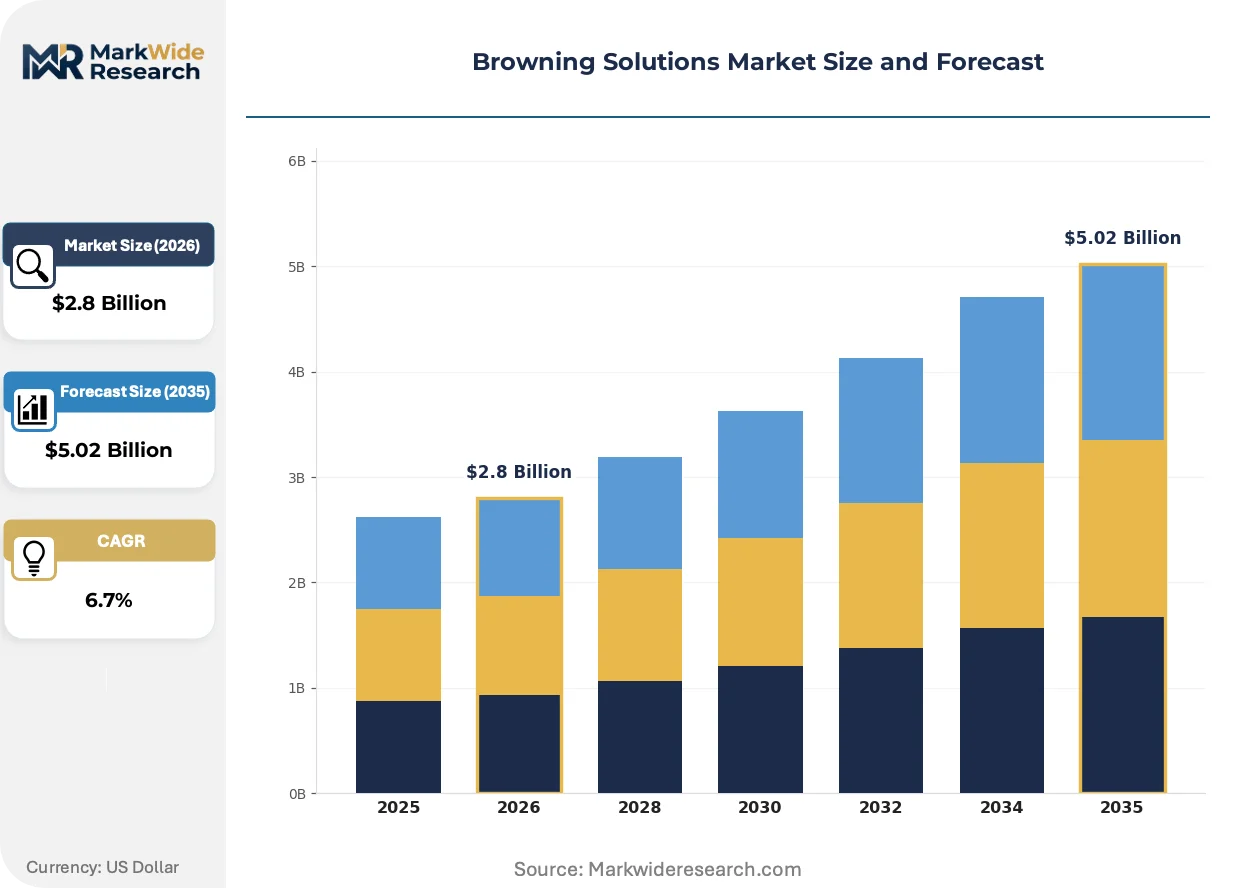
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firearms, Ammunition, Accessories, Optics Application: Hunting, Sport Shooting, Law Enforcement, Military End User: Outdoor Enthusiasts, Sports Clubs, Government Agencies, Private Security Distribution Channel: Online Retail, Specialty Stores, Trade Shows, Direct Sales |
| Companies Covered | Kerry Group PLC, Advance Food Systems, John R White Company Inc., Chr. Hansen, Cargill, Archer Daniels Midland, Royal DSM, Tate & Lyle PLC, Flavour Stream srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Browning Solutions Market Evolving Landscape
Biological browning systems are displacing thermal processes across multiple food matrices, while regulatory scrutiny of 4-MeI compounds accelerates investment in alternative color development pathways.
Enzymatic browning preparations utilizing immobilized polyphenol oxidase are expanding into ready-to-drink coffee and tea beverages where cold-fill processing preserves volatile aromatic compounds. Beverage manufacturers in Germany and the Netherlands are adopting these systems to eliminate thermal degradation of flavor precursors. This technology is expanding into premium positioning that commands ingredient cost premiums over conventional caramel solutions.
EFSA's 2023 re-evaluation of 4-methylimidazole limits in Class III and IV caramel colors is triggering wholesale reformulation across the European savory snack and prepared sauce sectors. Manufacturers must now validate alternative browning pathways or face product withdrawal from member state markets. The bakery segment is responding fastest, with industrial producers in Italy and Spain already completing enzymatic system transitions.
Ingredient buyers are consolidating supplier relationships around integrated color-flavor-texture systems rather than discrete additive procurement. Food manufacturers are reducing qualified vendor lists from multiple single-function suppliers to fewer platform providers capable of co-developing clean-label solutions. This concentration is most visible in France, where major industrial bakery groups have halved their browning ingredient supplier base since 2022.
Browning Solutions Market Segmentation
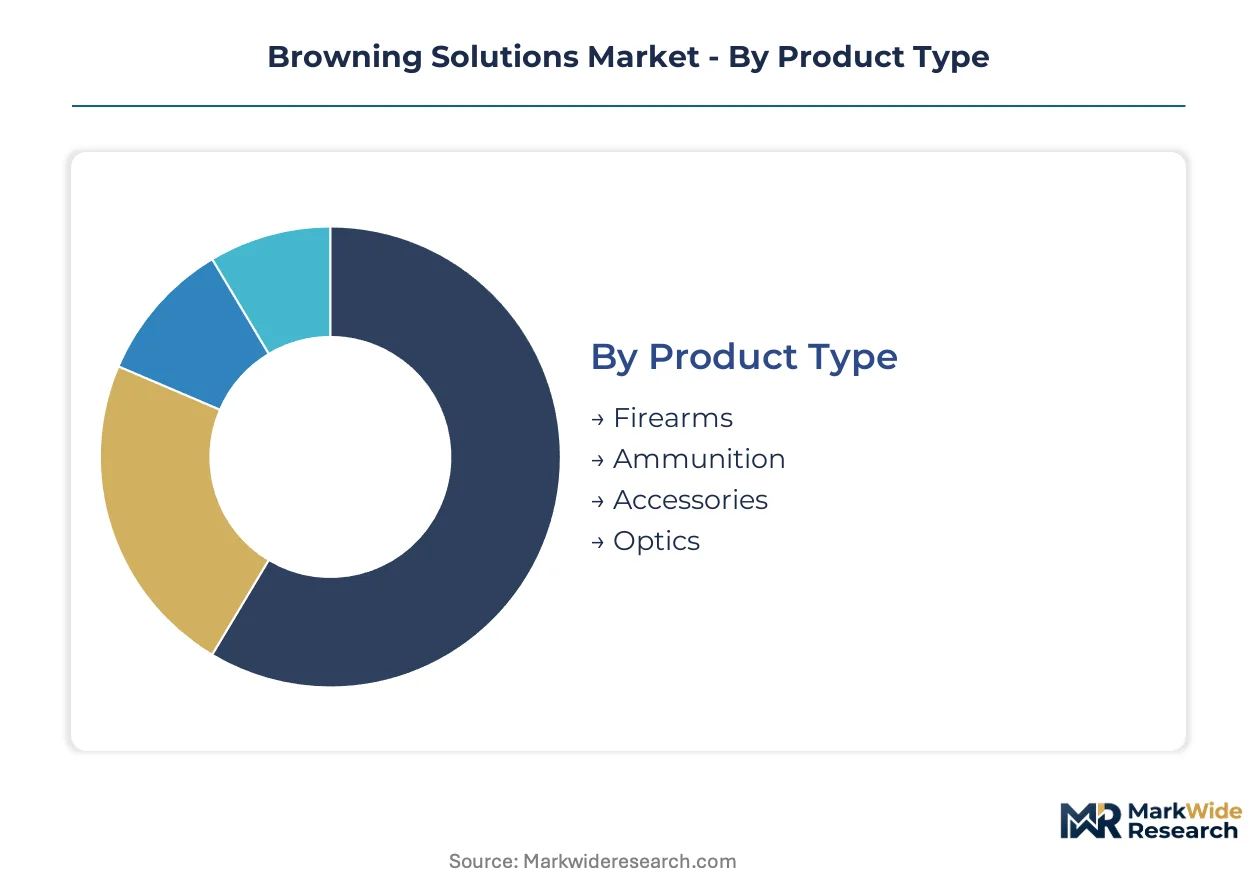
Segmentation in the Browning Solutions Market reveals divergent procurement logics across product categories, with thermal finishing requirements varying sharply between volume firearms manufacturing and precision optics fabrication. Understanding these structural differences enables suppliers to align formulation portfolios with specific performance specifications and regulatory exposure profiles.
Product Type:
Cost tier differentiation separates commodity surface treatments from specialized coatings commanding formulation premiums.
- Firearms:Thermal browning formulations for carbon steel receivers and barrels operate at 120-150°C, with salt bath nitriding alternatives displacing traditional oxide finishes in German and Austrian manufacturing clusters. Industrial producers in Suhl and Ferlach consolidate procurement around integrated corrosion protection systems.
- Ammunition:Brass casing oxidation control and projectile coating applications require low-temperature enzymatic precursors to prevent propellant degradation. Czech and Serbian ammunition plants are converting from synthetic sealants to Maillard-derived protective layers that satisfy REACH disclosure mandates.
- Accessories:Magazines, grips, and mounting hardware utilize spray-applied browning lacquers with accelerated cure cycles.
- Optics:Lens housing treatments demand ultra-thin deposition compatible with anodized aluminum substrates.
Volume sits with Firearms; growth tilts toward Optics as precision platform adoption accelerates.
Application:
Customer maturity cycles determine replacement frequency and specification stringency across use cases.
- Hunting:Seasonal equipment refresh patterns in Nordic and Alpine regions sustain steady demand for traditional hot-bluing and browning services. Norwegian and Swedish gunsmithing cooperatives maintain captive finishing operations using heritage formulations.
- Sport Shooting:Competitive disciplines in Italy's Val Trompia and Germany's Bavaria drive customization intensity, with Olympic-grade triggers and match barrels requiring specialized low-friction browning treatments. Federations are tightening finish uniformity standards for equipment certification.
- Law Enforcement:Agency procurement specifications prioritize corrosion resistance in maritime and tropical deployment conditions.
- Military:NATO standardization agreements are converging on CARC-compatible coating systems with infrared signature management.
Procurement concentration favors Law Enforcement; customization intensity peaks in Sport Shooting.
End User:
Technical sophistication and volume scale create distinct service requirements across buyer types.
- Outdoor Enthusiasts:Individual hunters and collectors in rural France and Poland drive artisanal gunsmithing demand, with small-batch cold browning solutions preserving historical firearm aesthetics. Regional craft associations are documenting traditional techniques for heritage certification.
- Sports Clubs:Competitive shooting organizations in the Netherlands and Belgium aggregate equipment purchases, negotiating standardized finishing specifications across member inventories.
- Government Agencies:Centralized armory operations in Rome and Berlin specify certified coating applicators with ECHA-registered chemical management protocols.
- Private Security:Corporate protection details in London and Zurich prioritize rapid turnaround on discrete firearm refurbishment.
Contract value concentrates with Government Agencies; margin expansion targets Private Security.
Distribution Channel:
Information intensity and customization requirements shape channel viability for browning solution procurement.
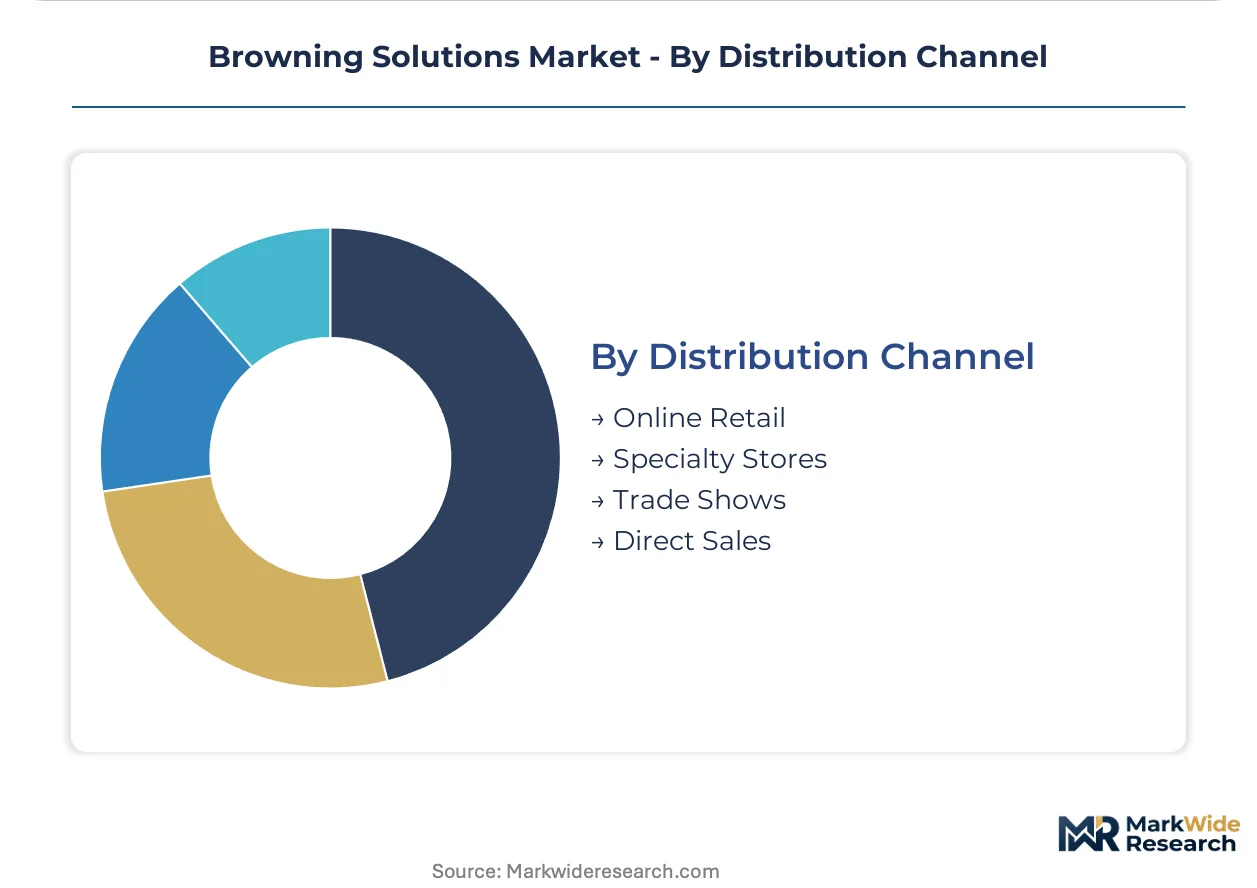
- Online Retail:Standardized cold-bluing kits and DIY browning compounds reach dispersed hobbyist markets through German and UK e-commerce platforms. Product liability exposure limits formulation complexity available through direct-to-consumer channels.
- Specialty Stores:Technical consultation on substrate compatibility and application technique sustains premium positioning for Vienna and Paris firearms retailers. Staff chemists guide customers through E150-compliant finish selection for restored collectibles.
- Trade Shows:IWA OutdoorClassics in Nuremberg and Eurosatory in Paris-Villepinte concentrate annual specification negotiations between finish suppliers and OEM procurement teams.
- Direct Sales:Major manufacturers in Liège and Eibar maintain technical service agreements with integrated coating providers.
Transaction volume flows through Online Retail; technical complexity anchors Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of browning solutions concentrates in European fermentation clusters, while consumption patterns diverge between industrial food manufacturing hubs and artisanal processing regions. The EU Green Deal is redrawing procurement geography as reformulation timelines compress.
Germany
Industrial bakery groups in Bavaria and North Rhine-Westphalia are consolidating supplier relationships around integrated clean-label systems. EFSA purity criteria enforcement is accelerating withdrawal of E150c and E150d colorants from sauerkraut and prepared sauce portfolios. The Stuttgart-Rhine-Neckar manufacturing corridor hosts multiple enzymatic technology providers serving pan-European reformulation contracts.
France
Artisanal charcuterie and sauce producers in Auvergne-Rhône-Alpes are adopting cold-process enzymatic browning to preserve volatile aromatic compounds. REACH disclosure mandates are forcing reformulation of traditional thermal caramelization methods in Île-de-France industrial kitchens. Lyon-based ingredient distributors are building technical consultation capabilities around Maillard reaction precursors.
Italy
Pasta and baked goods manufacturers in Emilia-Romagna are completing transitions to enzymatic browning systems ahead of EFSA's 4-MeI threshold enforcement. Val Trompia firearms finishing cooperatives maintain heritage hot-bluing operations using traditional oxide formulations. The Parma food cluster is integrating fermentation-derived browning intermediates into industrial-scale production lines.
Netherlands
Beverage manufacturers in Randstad cities are deploying immobilized polyphenol oxidase systems for cold-fill coffee and tea processing. Dutch regulators are aligning national additive disclosure rules with EU Green Deal transparency mandates ahead of the 2027 compliance deadline. Wageningen University partnerships are accelerating commercialization of microbial browning precursor production.
Spain
Industrial bread producers in Catalonia have halved qualified browning ingredient supplier counts since 2022. Spanish food safety authorities are tightening 4-MeI monitoring in Class III and IV caramel colors used in savory snack applications. The Valencia agricultural belt is expanding apple and pear cultivation to secure enzymatic feedstock supply for domestic processors.
Browning Solutions Market Competitive Landscape
The competitive structure tilts toward diversified ingredient conglomerates with fermentation technology platforms. Three to five multinational food ingredient suppliers anchor volume supply through backward integration into agricultural feedstocks. Specialist enzyme technology providers occupy premium positioning in cold-process applications. Consolidation pressure is intensifying as food manufacturers reduce vendor lists, while fermentation-derived intermediate startups attract technology licensing interest from established players.
Within the diversified conglomerate tier, Kerry Group PLC and Cargill exemplify scale-driven positioning through captive supply chains and cross-category ingredient portfolios. Royal DSM occupies a distinctive niche in fermentation-derived browning intermediates that bypass thermal processing constraints. Among specialist enzyme providers, Chr. Hansen represents technology-focused positioning built on microbial cultivation expertise. Tate & Lyle PLC anchors British-origin supply security through maize-derived dextrose feedstock control.
| Leading Market Players |
|---|
| Kerry Group PLC |
| Advance Food Systems |
| John R White Company Inc. |
| Chr. Hansen |
| Cargill |
| Archer Daniels Midland |
| Royal DSM |
| Tate & Lyle PLC |
| Flavour Stream srl |
| Others |
Value Network & Pricing Analysis
Enzymatic browning technology maturation is simultaneously compressing thermal processing costs and redrawing supplier concentration as fermentation-derived alternatives displace traditional caramel colorant production. This shift rewards players with captive biotechnology infrastructure while squeezing commodity chemical processors dependent on maize feedstock volatility.
Pricing Analysis
Margin tightening in synthetic caramel colorants reflects EFSA's 4-MeI threshold enforcement and the EU Green Deal's disclosure mandates. Three-tier pricing structure across enzymatic premium, fermentation-derived standard, and conventional economy levels separates clean-label certifiable solutions from commodity alternatives. Pricing pressure stems from agricultural input volatility in dextrose precursors. Industrial bakery groups in Germany exhibit lowest price sensitivity due to reformulation urgency, while smaller sauce manufacturers in Spain face acute cost compression.
Supply Chain Analysis
Freight cost escalation from limited enzymatic feedstock zones in northern Spain and southern France is forcing geographic diversification of apple and pear extract sourcing. Supply concentrates in the Netherlands, Germany, and Italy for fermentation infrastructure, with raw material dependencies on maize-derived dextrose, immobilized enzyme carriers, and microbial cultivation media. Single-source vulnerability sits with concentrated polyphenol oxidase suppliers. Distribution runs through specialty ingredient distributors with technical consultation capabilities rather than commodity chemical traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EFSA's evolving 4-MeI purity criteria construct a regulatory moat favoring players with dual EFSA-FDA certification portfolios and fermentation technology assets.
For Market Incumbents: Acquire enzymatic stabilization patent portfolios to defend against cold-process beverage entrants exploiting polyphenol oxidase advances. Consolidate backward integration into regional maize processing in Bavaria and Lombardy to neutralize feedstock volatility exposure from commodity suppliers. For New Entrants and Emerging Players: Specialty store channel partners with staff chemists represent the most penetrable entry vector for artisanal firearm restoration markets in rural France and Poland. Target heritage certification programs for traditional hot-bluing techniques as a differentiation anchor against industrial enzymatic suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified ingredient conglomerates seeking fermentation platform augmentation. Long-term viability favors targets with microbial browning intermediate capabilities and established EFSA compliance documentation. Watch EFSA's classification debates around natural versus processing-aid definitions as the critical inflection signal for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Maize Processing | Captive dextrose supply secures Maillard reaction precursor cost stability against agricultural commodity cycles. |
| Enzyme Stabilization Patent Acquisition | Polyphenol oxidase immobilization IP enables cold-fill beverage positioning at premium pricing tiers. |
| Dual Certification Portfolio Investment | Parallel EFSA and FDA compliance documentation accelerates transatlantic market access timelines. |
| Fermentation-Derived Intermediate Scale-Up | Microbial production bypasses thermal processing constraints and 4-MeI regulatory exposure entirely. |
| Specialty Store Technical Consultancy Buildout | Staff chemist capabilities in Vienna and Paris retailers create defensible margin pools against online commoditization. |
Research Methodology
Document review covered EFSA additive safety assessments, EU Green Deal implementation guidance, and REACH disclosure protocols, complemented by interviews with fermentation technology directors, industrial bakery procurement leads, specialty firearms retailer owners, and enzymatic formulation chemists. Secondary validation drew from customs trade data on dextrose imports, SEC filings of listed ingredient suppliers, and European Food Safety Authority re-evaluation reports. Bottom-up demand modeling across application segments was triangulated against top-down supply capacity estimates from major production clusters.
Historical volume trajectories were cross-referenced against expert panel inputs on reformulation timelines to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and distribution channel, with regulatory compliance tier as an additional industry-specific dimension. CAGRs were derived from trend extrapolation adjusted for policy implementation schedules and technology substitution curves. Forecast inputs incorporated EFSA enforcement probability assessments and enzymatic technology cost reduction trajectories.
Caveats apply where EFSA 4-MeI threshold revisions or EU Green Deal disclosure deadline shifts could materially shift the outlook for synthetic caramel colorant demand destruction. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Natural Flavors and Fragrances Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Russia Food Flavor and Enhancer Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Chicken Flavor Market
Flavorings and Food Additives
Food Flavors Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Culinary Essence Market
Flavorings and Food Additives
Naringin Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Brazil Food Flavor and Enhancer Market
Flavorings and Food Additives
North America Flavors and Fragrances Market
Flavorings and Food Additives
Citrus-Based Sugar-Reduction Flavor Modulators Market
Flavorings and Food Additives
United States Food Colorants Market