
 Vanilla Extract Market | 2026-2036
Vanilla Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Vanilla Extract Market Intelligence
Buyer concentration among food and beverage manufacturers is restructuring procurement dynamics across the vanilla extract supply chain. McCormick & Company leverages its retail distribution scale to secure long-term vanilla contracts. Symrise AG anchors its position through backward integration into vanilla bean curing operations in Madagascar. Givaudan differentiates via biotechnology investments in yeast-derived vanillin alternatives.
Vanilla extract comprises an ethanolic infusion of cured vanilla pods, typically containing minimum vanillin concentrations of one to three percent by volume depending on origin grade and extraction method. The product serves as a flavoring agent across bakery, confectionery, and dairy manufacturing where heat-stable aromatic profiles remain essential. Natural vanilla extract commands premium positioning in clean-label applications while synthetic vanilla extract dominates volume in mass-market confectionery. Vanilla bean paste occupies a narrowing niche in artisanal baking channels where visual seed presence carries sensory value.
FDA food additive regulations and EU flavoring regulations govern labeling thresholds distinguishing natural from artificial vanilla, directly shaping product formulation decisions and market access requirements. Madagascar's national vanilla quality standards and Uganda's export certification protocols further constrain supply consistency for international buyers. Stakeholders must monitor biotechnology maturation and climate adaptation investments in East African growing regions as decisive variables for long-term sourcing security.
Market Dynamics
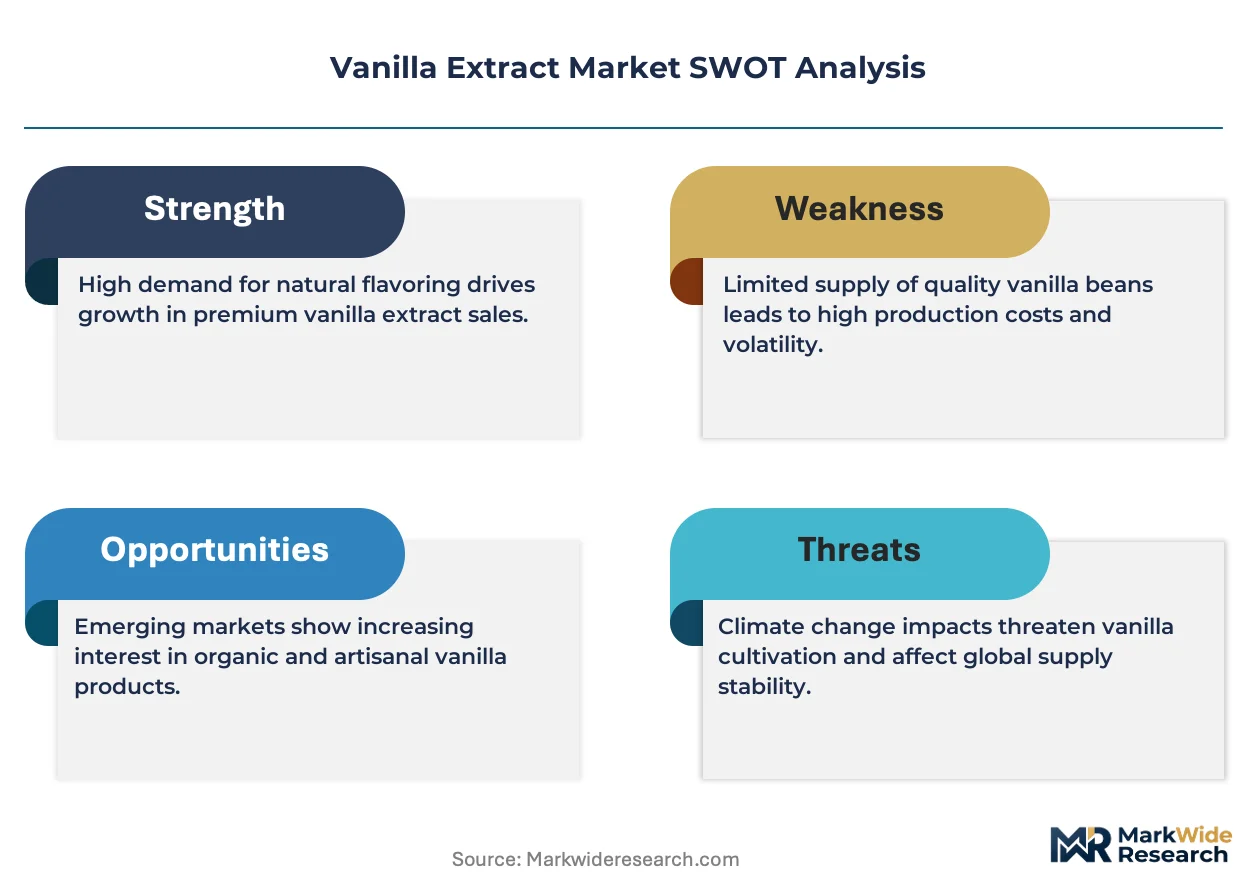
Climate volatility in Madagascar, Indonesia, and Uganda is compressing vanilla bean harvest cycles and forcing food manufacturers to restructure multi-year procurement contracts. FDA and EU flavoring regulations are simultaneously tightening purity thresholds, creating dual compliance pressure on extract suppliers.
Growth Catalysts
- Clean-label bakery demand:Food and beverage manufacturers are reformulating product lines to replace artificial vanillin with natural vanilla extract, driven by consumer ingredient transparency preferences in North American and European retail channels.
- EU flavoring regulations:The European Union's stricter origin disclosure requirements for natural flavorings are accelerating premium positioning for Madagascar Bourbon vanilla extracts with traceable curing documentation.
- Biotechnology maturation:Yeast-derived vanillin production is expanding supply elasticity for industrial bakery applications where heat-stable aromatic profiles remain non-negotiable.
Market Restraints
- Cyclone-induced supply volatility:Madagascar's Sava region concentrates over seventy percent of global vanilla bean output, exposing buyers to concentrated weather disruption risk with limited geographic diversification alternatives.
- Multi-year curing cycles:Vanilla orchid cultivation requires eighteen to thirty-six months from pollination to cured bean readiness, creating structural inventory mismatches against quarterly food manufacturer demand planning.
- Synthetic vanillin price compression:Guaiacol and lignin-derived artificial vanilla dominates mass-market confectionery applications, capping natural extract penetration in cost-sensitive product categories.
Strategic Opportunities
- Uganda cultivation expansion:The country's western highlands offer underdeveloped vanilla acreage with shorter supply chains to European processors, attracting agricultural investment for certified organic production.
- Direct-to-artisan distribution:E-commerce platforms are enabling specialty extract suppliers to bypass traditional foodservice distributors and capture margin in small-batch bakery and craft ice cream channels.
- Carbon credit integration:Agroforestry vanilla cultivation under shade trees qualifies for voluntary carbon market mechanisms, creating dual revenue streams for Madagascar and Indonesian farming cooperatives.
Industry Challenges
- Certified curing technician scarcity:Traditional Bourbon curing requires skilled labor for sweating, drying, and conditioning phases, with training pipelines failing to replace aging specialists in Madagascar's Sambava district.
- Blockchain traceability implementation:Food manufacturers demanding farm-to-bottle documentation face integration complexity with smallholder cooperatives lacking digital infrastructure for immutable supply chain records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vanilla Extract Market |
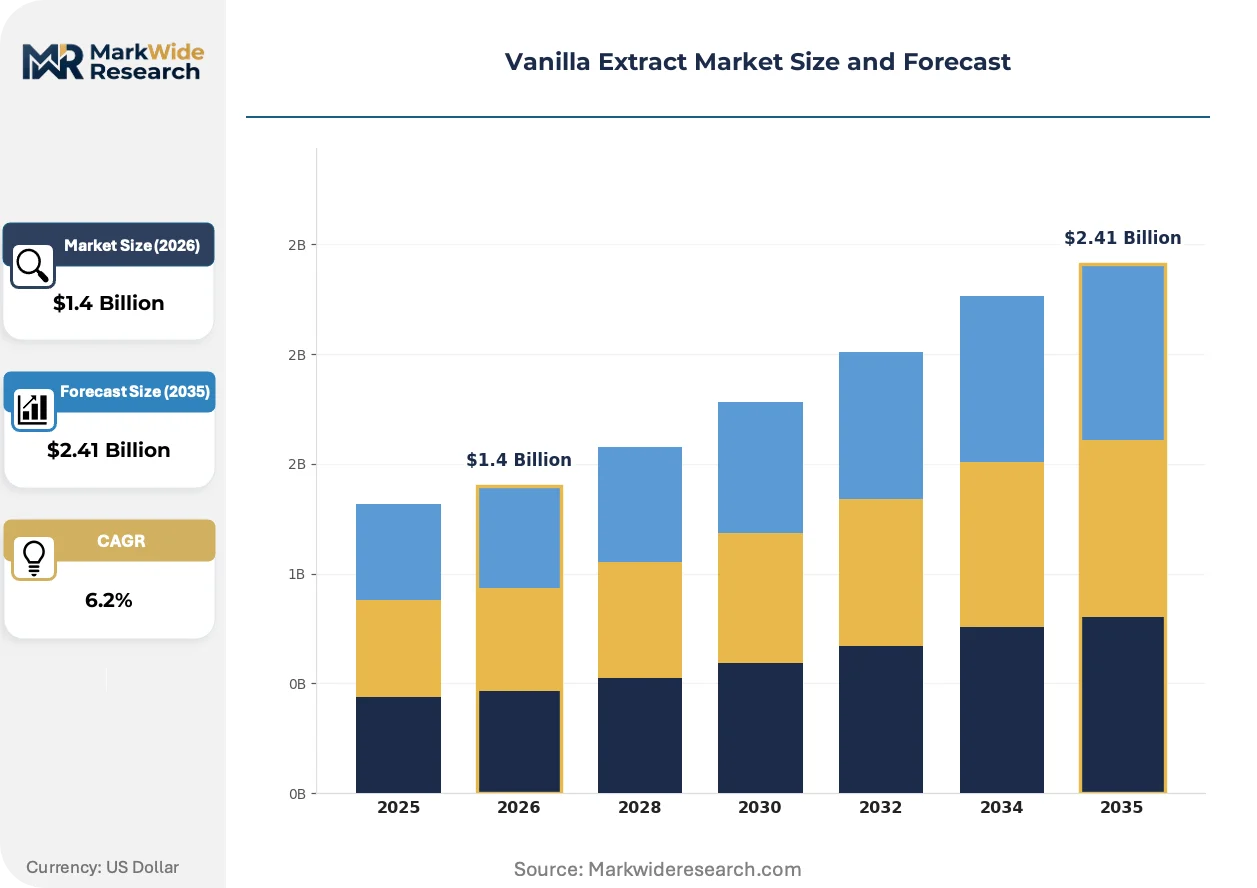
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Vanilla Extract, Synthetic Vanilla Extract, Bourbon Vanilla, Tahitian Vanilla, Vanilla Bean Paste Application: Bakery Products, Confectionery, Beverages, Dairy Products, Personal Care Products End User: Food & Beverage Manufacturers, Cosmetic Producers, Pharmaceuticals, Household Consumers, Flavor & Fragrance Companies Packaging Type: Glass Bottles, Plastic Bottles, Sachets, Bulk Containers, Dropper Bottles |
| Companies Covered | Nielsen-Massey Vanillas, Sensient Technologies Corporation, Symrise AG, Firmenich, Archer Daniels Midland Company, Givaudan, McCormick & Company, Evolva Holding AG, International Flavors & Fragrances (IFF), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vanilla Extract Market Strategic Shifts & Innovations
Biotechnology, regulatory transparency mandates, and procurement model evolution are restructuring how vanilla extract moves from bean to formulated product. These forces are compressing traditional supply chain layers and redefining competitive advantage.
Precision fermentation platforms using engineered yeast strains are decentralizing vanillin production away from agricultural dependency. Industrial bakery and confectionery manufacturers in North America are piloting these biocatalytic alternatives to hedge against cyclone-driven supply interruptions. The technology is decentralizing geographic risk concentration that has long defined vanilla procurement strategy.
EU flavoring regulations now mandate quantitative ingredient declaration thresholds distinguishing natural from nature-identical vanillin. This policy shift forces reformulation disclosure on packaged goods sold in European Economic Area markets. Premium dairy and ice cream brands are responding by securing segregated supply chains with third-party organic certification.
Long-term offtake contracts with fixed volume floors are replacing spot market purchasing among multinational food manufacturers. This behavioral shift compresses price volatility exposure for buyers while locking in cultivation financing for Madagascar and Indonesian farming cooperatives. The pattern is most visible in North American clean-label bakery segments where ingredient consistency carries brand equity risk.
Vanilla Extract Market Segmentation
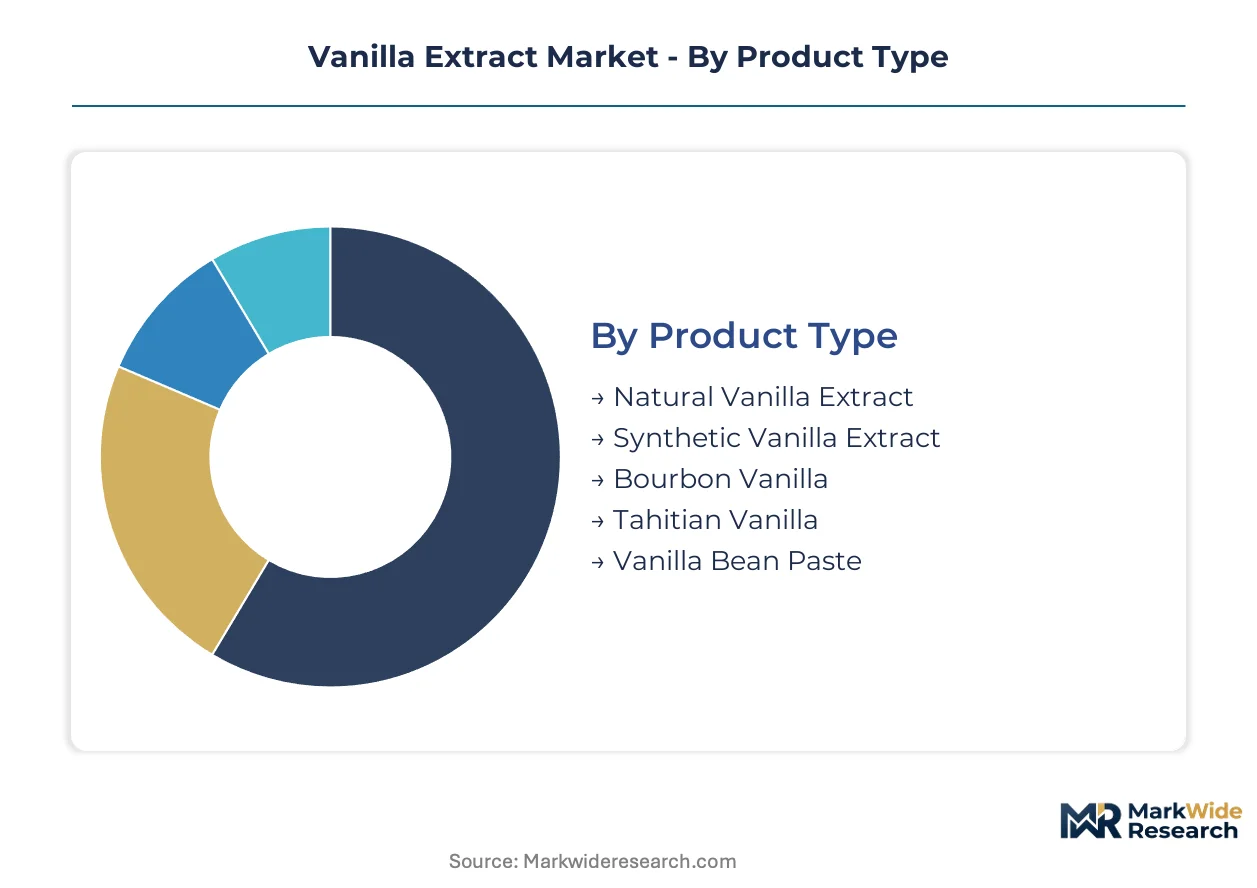
Vanilla extract segmentation reflects divergent supply chain architectures across purity grades, end-use thermal stability requirements, and procurement scale tiers. Manufacturers navigate formulation trade-offs between cost-engineered synthetic alternatives and certified natural extracts with traceable provenance.
Product Type:
Standardization intensity varies sharply across this category, from commodity synthetic formulations to terroir-specific origin denominations with multi-year curing documentation.
- Natural Vanilla Extract:Ethanolic infusion of cured vanilla pods containing vanillin concentrations between one and three percent by volume. Demand concentrates in North American clean-label bakery and premium ice cream manufacturing where FDA labeling requirements favor natural flavoring declarations.
- Synthetic Vanilla Extract:Guaiacol or lignin-derived vanillin produced through chemical synthesis. Mass-market confectionery manufacturers in cost-sensitive categories rely on this grade for heat-stable aromatic profiles at fractional input costs.
- Bourbon Vanilla:Madagascar-origin vanilla planifolia with high vanillin content and characteristic creamy, sweet aromatic profile. European dairy processors prize this grade for EU flavoring regulation compliance with origin disclosure mandates.
- Tahitian Vanilla:Vanilla tahitensis species with anisyl compounds delivering floral, fruity notes distinct from Bourbon profiles. Specialty chocolate and high-end pastry applications in French and Japanese markets absorb limited harvest volumes.
- Vanilla Bean Paste:Concentrated extract suspension with visible seed particulates. Artisanal bakeries and craft ice cream channels value sensory authenticity despite narrower distribution reach.
Most installed capacity flows through Natural Vanilla Extract. Expansion is steepest in Bourbon Vanilla.
Application:
Volume scale separates industrial commodity formulations from precision-dosed specialty applications with formulation complexity premiums.
- Bakery Products:Industrial bread, cake, and cookie manufacturing represents the dominant volume sink. North American manufacturers reformulating for clean-label positioning are accelerating natural extract procurement despite price premiums over synthetic alternatives.
- Confectionery:Chocolate, candy, and chewing gum applications require heat-stable vanillin that survives high-temperature processing. Synthetic vanilla dominates this segment due to cost engineering pressures in mass-market product tiers.
- Beverages:Soft drinks, flavored waters, and alcoholic spirits incorporate vanilla as base or accent notes. Premium spirits and craft beverage producers in Kentucky and Scotland favor Madagascar Bourbon for barrel-aging synergy.
- Dairy Products:Ice cream, yogurt, and flavored milk applications demand low-dose aromatic intensity. EU-origin dairy brands leverage segregated supply chains with organic certification for regulatory positioning.
- Personal Care Products:Fragrances, lotions, and aromatherapy formulations utilize vanilla absolute and extract for scent profiles. Cosmetic producers face ECHA fragrance allergen disclosure requirements affecting formulation thresholds.
Most installed capacity flows through Bakery Products. Expansion is climbing the fastest in Dairy Products.
End User:
Procurement sophistication divides this category between multinational manufacturers with long-term offtake contracts and fragmented buyers dependent on spot market access.
- Food & Beverage Manufacturers:Multinational bakery, confectionery, and dairy processors with quarterly demand planning cycles. These buyers are restructuring toward multi-year procurement contracts with fixed volume floors to hedge against Madagascar cyclone exposure.
- Cosmetic Producers:Fragrance houses and personal care formulators requiring cosmetic-grade vanilla absolute. EU REACH compliance and fragrance allergen labeling drive supplier qualification complexity.
- Pharmaceuticals:Excipient and flavor-masking applications in oral dosage forms. Regulatory filing requirements favor qualified suppliers with DMF documentation and batch consistency records.
- Household Consumers:Retail purchasers through grocery and specialty food channels. E-commerce platforms are enabling direct-to-consumer distribution bypassing traditional foodservice intermediaries.
- Flavor & Fragrance Companies:Symrise, Givaudan, and Firmenich-tier compounders sourcing raw extract for downstream formulation. These intermediaries concentrate backward integration investments in Madagascar curing operations.
Most installed capacity flows through Food & Beverage Manufacturers. Expansion is gaining share fastest in Flavor & Fragrance Companies.
Packaging Type:
Unit economics and shelf-life requirements shape format selection from single-use sachets to industrial bulk totes with nitrogen flushing.
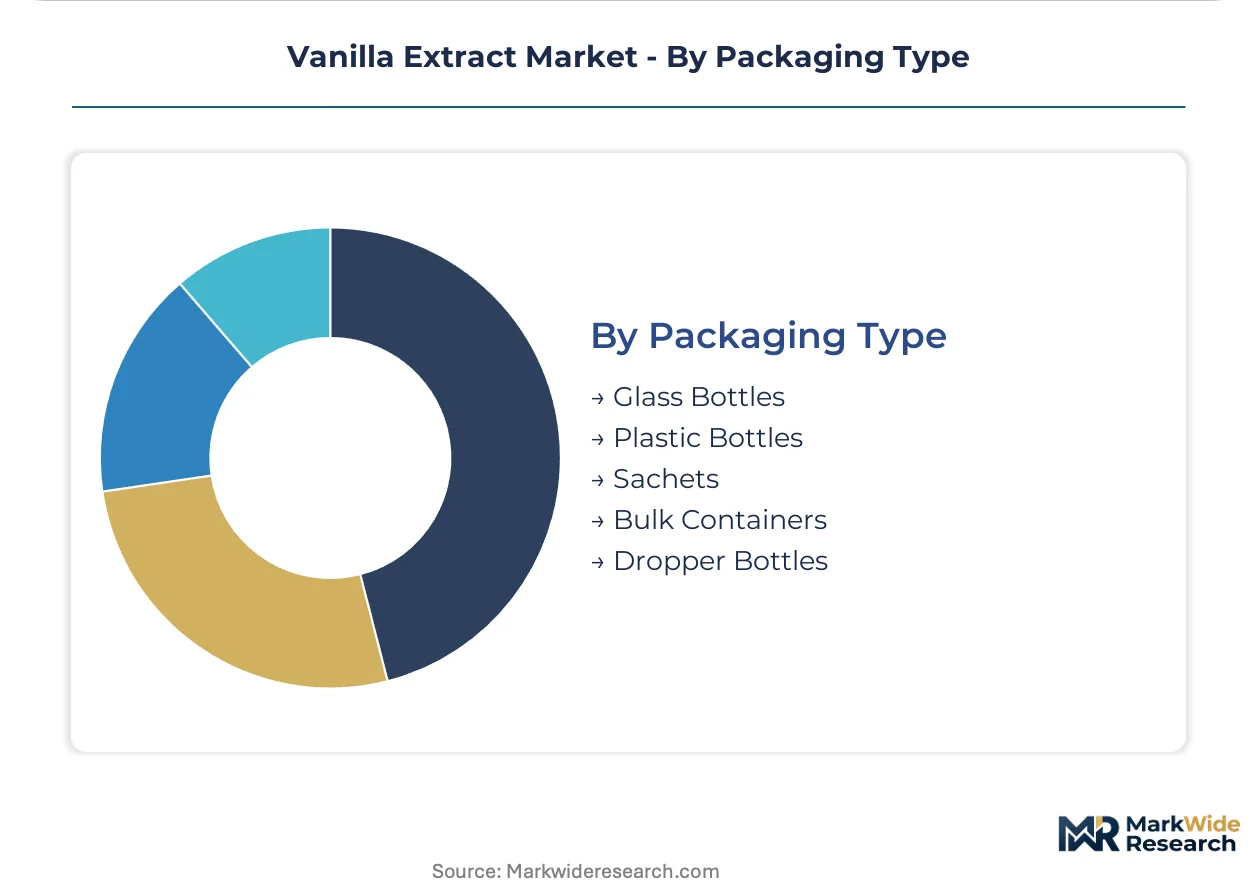
- Glass Bottles:Premium retail formats with UV protection for light-sensitive aromatic compounds. Specialty food retailers and gift channels favor this packaging for perceived quality signaling.
- Plastic Bottles:Cost-engineered retail and foodservice formats. Mass-market grocery distribution relies on PET and HDPE containers for shatter resistance and logistics efficiency.
- Sachets:Single-serve portions for foodservice and institutional baking. Quick-service restaurant chains and airline catering operations value portion control and waste reduction.
- Bulk Containers:Stainless steel drums and intermediate bulk containers for industrial manufacturing. Food and beverage manufacturers with dedicated extraction facilities procure at this scale for formulation integration.
- Dropper Bottles:Precision-dosing formats for artisanal baking and home enthusiast segments. Craft chocolate makers and specialty coffee roasters utilize controlled dispensing for small-batch consistency.
Most installed capacity flows through Bulk Containers. Expansion is expanding most quickly in Glass Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madagascar and Indonesia dominate vanilla bean cultivation, yet procurement patterns diverge sharply between European traceability requirements and North American clean-label reformulation cycles.
Madagascar
Cyclone exposure in the Sava region compresses harvest reliability for bourbon vanilla planifolia. The country's national vanilla quality standards mandate curing documentation that EU flavoring regulations now require for origin disclosure. Antalaha and Sambava districts concentrate backward integration investments from flavor houses seeking curing operation control.
Indonesia
Papua and Sulawesi highlands expand vanilla acreage under agroforestry shade systems. The agriculture ministry's export certification protocols align with EU flavoring regulation thresholds for natural flavoring declarations. Maluku Islands processing clusters specialize in tahitensis species for Japanese and French specialty chocolate channels.
Uganda
Western highlands near Bundibugyo and Kasese attract agricultural investment for certified organic production with shorter supply chains to European processors. The Uganda Export Promotion Board coordinates traceability documentation meeting EU flavoring regulation mandates. Rwenzori Mountain cooperatives pilot carbon credit integration under shade-tree cultivation models.
United States
Kentucky bourbon distilleries and Vermont ice cream manufacturers drive Madagascar bourbon procurement for barrel-aging synergy and clean-label positioning. FDA labeling requirements distinguish natural from artificial vanilla in packaged goods reformulation. Brooklyn and San Francisco specialty food clusters sustain direct-to-artisan distribution bypassing traditional foodservice intermediaries.
France
Paris and Lyon pastry channels absorb limited tahitensis volumes for high-end applications where anisyl compound profiles justify price premiums. ANSM fragrance allergen disclosure requirements affect cosmetic-grade vanilla absolute formulation thresholds. Grasse fragrance houses concentrate cosmetic and flavor compound formulation for EU Economic Area distribution.
Vanilla Extract Market Key Industry Players
Madagascar-based curing operations anchor one tier; European and North American formulation specialists hold downstream flavor and fragrance positioning. The vendor base stratifies across three archetypes: agricultural integrators controlling bean-to-extract supply chains, biotechnology platforms pursuing yeast-derived vanillin alternatives, and retail-branded distributors securing long-term procurement contracts. Dominant competitive moves include backward integration into Madagascar curing facilities and multi-year offtake agreements with fixed volume floors.
Within the agricultural integration tier, Symrise AG and Givaudan exemplify backward integration strategies through Madagascar curing operation investments. McCormick & Company occupies retail distribution scale positioning for long-term vanilla contract security. Sensient Technologies Corporation represents the mid-tier formulation specialist archetype serving industrial bakery and confectionery channels with certified extract supply.
| Leading Market Players |
|---|
| Nielsen-Massey Vanillas |
| Sensient Technologies Corporation |
| Symrise AG |
| Firmenich |
| Archer Daniels Midland Company |
| Givaudan |
| McCormick & Company |
| Evolva Holding AG |
| International Flavors & Fragrances (IFF) |
| Others |
Cost & Logistics Intelligence
Multinational food and beverage manufacturers with quarterly demand planning cycles anchor pricing power through multi-year procurement contracts with fixed volume floors. Madagascar Bourbon extract premiums over synthetic alternatives widen when cyclone exposure compresses harvest reliability in the Sava region.
Pricing Analysis
Capacity additions in Uganda's western highlands are reshaping price floors for certified organic vanilla extracts. Three-tier pricing structure across premium, standard, and economy levels separates Madagascar Bourbon with traceable curing documentation from Indonesian planifolia and mass-market synthetic vanillin. Price differentiation rests on certification grade and geographic delivery cost to European processors. Cost compression in synthetic alternatives is intensifying because lignin-derived production scales in Asian chemical plants. Mass-market confectionery manufacturers remain most price-sensitive; premium dairy brands exhibit least sensitivity due to clean-label brand equity requirements.
Supply Chain Analysis
Madagascar's national vanilla quality standards and EU flavoring regulations are reshaping sourcing toward documented origin supply chains. Geographic supply concentrates in Madagascar, Indonesia, and Uganda. Raw material dependencies draw from vanilla orchid cultivation, ethanolic extraction solvents, and glass or bulk packaging materials. Single-source vulnerability runs through Madagascar's Sava region where over seventy percent of global vanilla bean output faces cyclone disruption risk. Distribution runs through flavor and fragrance compounders with backward integration into Madagascar curing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vanilla extract market represents a late-cycle quality story as food manufacturers reformulate toward clean-label natural flavoring declarations. Consumer ingredient transparency preferences in North American and European retail channels drive demand-shift toward premium specifications with traceable provenance.
For Market Incumbents: Acquire Madagascar curing operation assets to secure bean-to-extract supply chain control against biotechnology substitution threats. Invest in blockchain traceability infrastructure to meet EU flavoring regulation documentation mandates. Expand certified organic acreage partnerships in Uganda's Rwenzori Mountain cooperatives to diversify geographic risk concentration.
For New Entrants and Emerging Players: Enter via direct-to-artisan distribution channels bypassing traditional foodservice intermediaries. Target specialty food clusters in Brooklyn and San Francisco with small-batch vanilla bean paste formats. Leverage e-commerce platforms to capture margin in craft ice cream and artisanal baking segments where visual seed presence carries sensory value.
For Investors and Strategic Acquirers: Flavor and fragrance compounders are the most active acquirer in this space seeking upstream control over curing operations. Long-term viability hinges on climate adaptation investments in East African growing regions and biotechnology maturation timelines. Watch precision fermentation yield improvements as the inflection indicator for yeast-derived vanillin substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Curing Operations | Symrise AG and Givaudan secure Madagascar Bourbon supply consistency against cyclone volatility. |
| Biotechnology Platform Investment | Evolva Holding AG decentralizes vanillin production from agricultural dependency through engineered yeast strains. |
| Carbon Credit Integration Program | Rwenzori Mountain cooperatives create dual revenue streams under shade-tree agroforestry cultivation models. |
| Blockchain Traceability Implementation | Food manufacturers meet EU flavoring regulation farm-to-bottle documentation requirements with immutable supply chain records. |
| Direct-to-Artisan Distribution Launch | Specialty extract suppliers bypass traditional foodservice distributors to capture margin in craft channels. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary interviews engaged vanilla bean curing technicians, food and beverage manufacturer procurement leads, flavor house R&D directors, and agricultural cooperative managers. Secondary validation drew from FDA food additive filings, EU flavoring regulation documentation, Madagascar national quality standards, and customs trade data. Bottom-up cultivation volume estimates and top-down extract demand modeling triangulated across the analysis window.
Segment-weighting approaches distributed value and volume across product type, application, and end user dimensions. The analytical framework modeled natural versus synthetic extract splits, bakery versus dairy application growth, and food manufacturer versus flavor company procurement patterns. CAGRs derived from historical price elasticity and substitution dynamics between agricultural and biotechnology supply sources. Forecast inputs incorporated climate volatility indices for Madagascar's Sava region and precision fermentation yield improvement trajectories.
The model holds under stable EU flavoring regulation enforcement and consistent FDA labeling requirements; deviation in biotechnology substitution acceleration or cyclone frequency would shift demand elasticity assumptions. Forecasts reflect documented assumptions about curing technician training pipeline recovery and carbon credit market mechanism adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
Chicory Products Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Vanilla Oleoresin Market
Flavorings and Food Additives
Citrus Flavors Market
Flavorings and Food Additives
Food Aroma Market
Flavorings and Food Additives
Global Chicory Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
Marshmallow Root Extract Market
Flavorings and Food Additives
Natural Flavor Extract Market
Flavorings and Food Additives
United States Food Flavor Market