
 Italy Plant Protein Market | 2026-2036
Italy Plant Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Plant Protein Market Foresight
Netherlands-based pea protein extraction capacity is reconfiguring supply dynamics for Italian food manufacturers. Roquette Frères leverages its European processing network to anchor ingredient security for southern European customers. Cargill Incorporated competes through backward integration into European oilseed crushing, while Kerry Group PLC specializes in customized protein blends for Italian bakery and snack applications.
Italy Plant Protein encompasses isolates, concentrates, and textured formats derived from legume and cereal biomass through aqueous extraction, enzymatic hydrolysis, and mechanical fractionation, serving as functional ingredients for emulsification, gelation, and nutritional fortification in formulated foods. Isolates command premium positioning due to protein content exceeding 90 percent and superior functionality in beverage applications. Pea protein sustains the fastest expansion trajectory among source categories, while wheat gluten occupies mature volume pools in traditional Italian bakery systems.
Italy's Ministry of Health enforces EU Novel Food regulations for emerging protein sources, while EFSA safety assessments determine market access for hydrolysates and fermentation-derived ingredients. The EU Green Deal Farm to Fork strategy pressures domestic formulators to document sustainability credentials across supply chains. Stakeholders must monitor how BIS-equivalent conformity pressures from Italian retail chains reshape procurement specifications ahead of anticipated EU protein strategy revisions.
Market Dynamics
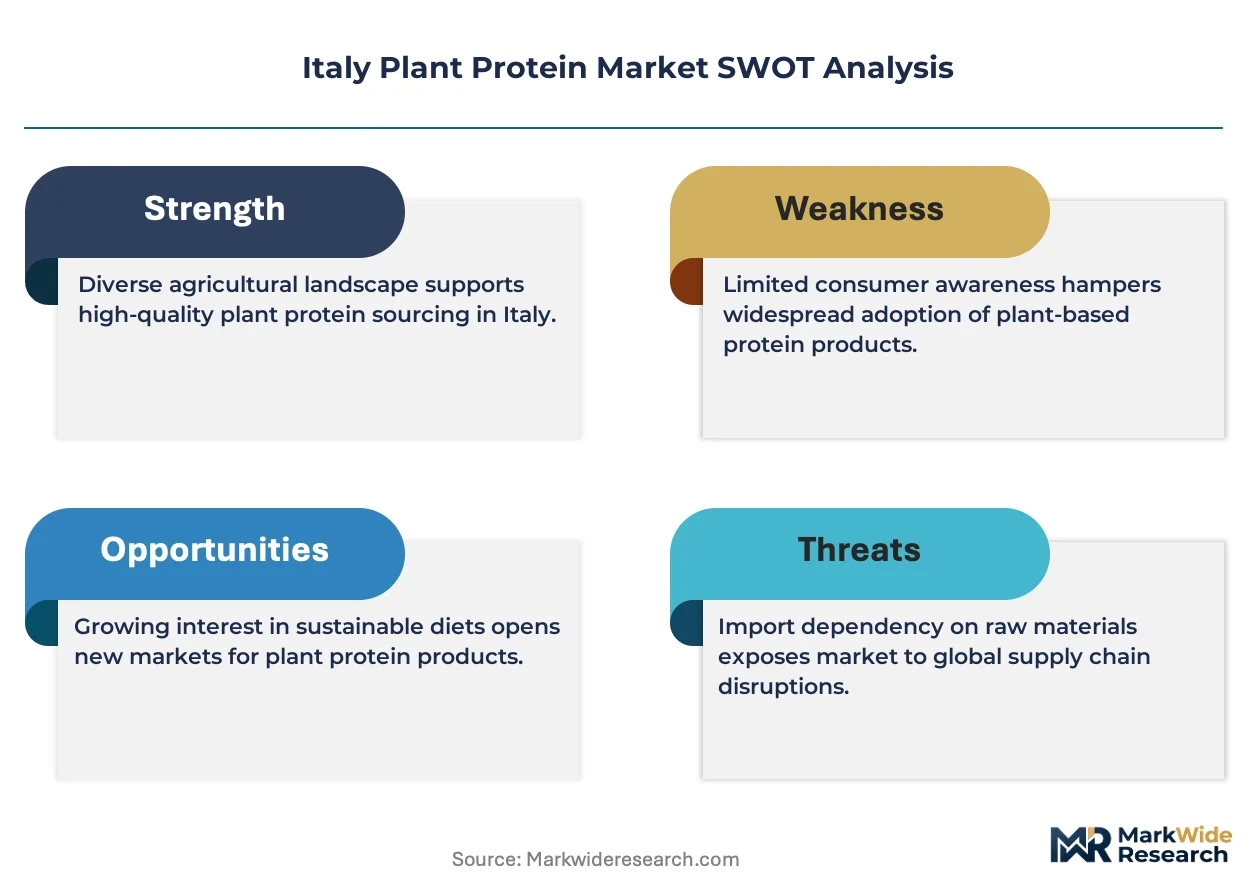
Italian food manufacturers face a supply-side squeeze as Netherlands-based pea protein extraction capacity reconfigures procurement patterns, forcing domestic processors to secure long-term offtake agreements or invest in captive extraction assets to maintain formulation autonomy.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Sustainability documentation mandates are accelerating investment in traceable supply chains across Lombardy and Emilia-Romagna processing clusters.
- Meat analogue formulation:Northern Italian CPG brands are expanding pea and soy isolate incorporation into retail-ready products for pan-European distribution.
- National Recovery and Resilience Plan incentives:Sustainable food system subsidies are unlocking domestic processing capacity expansion for ingredient security.
Market Restraints
- Input cost volatility:Yellow pea and fava bean prices fluctuate with Black Sea grain corridor disruptions and Canadian harvest variability.
- Supply concentration risk:Isolates above 90% protein content depend on a limited set of European extraction facilities, creating single-source vulnerability.
- Regulatory friction:EU Novel Food classification delays market entry for emerging protein sources including single-cell and precision-fermentation ingredients.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily food manufacturing bases remain underserved by high-functionality protein ingredient distribution networks.
- Precision fermentation convergence:Integration of enzymatic hydrolysis with biomass fermentation is opening novel ingredient categories for beverage fortification.
- Direct-to-manufacturer platforms:Digital procurement channels are compressing distributor margins and enabling smaller formulators to access bulk isolates previously reserved for volume buyers.
Industry Challenges
- Protein functionality expertise gap:Formulation chemists capable of optimizing gelation and emulsification in plant-based meat systems command premium compensation and limited availability.
- EFSA safety assessment timelines:Hydrolysate and fermentation-derived ingredient approvals require 18-24 month evaluation windows that delay product launch schedules.
- Legacy equipment retrofit costs:Traditional Italian pasta and bakery production lines require substantial capital modification to handle high-viscosity protein-enriched dough systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Plant Protein Market |
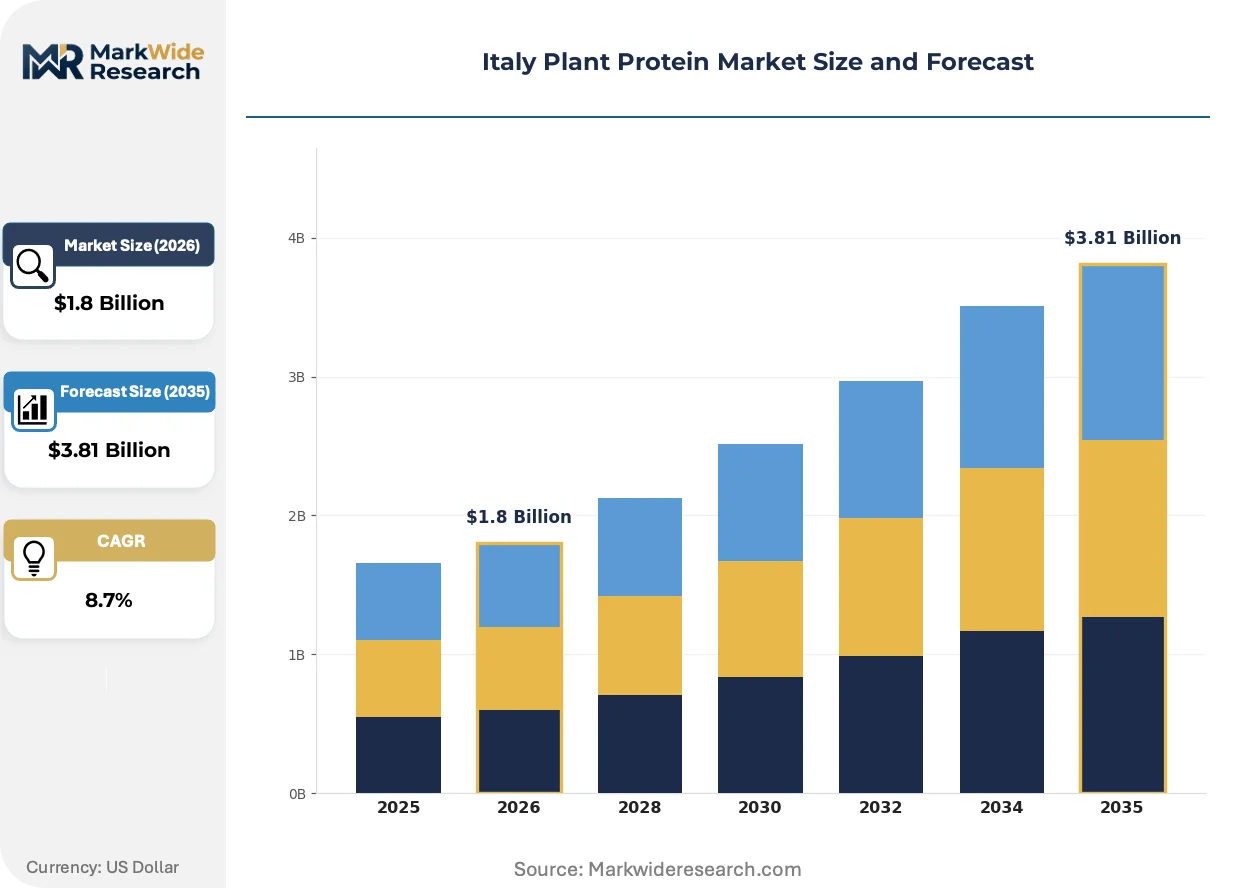
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Protein, Isolate, Concentrate, Hydrolysate Source: Pea, Soy, Wheat, Rice Application: Food & Beverage, Nutritional Supplements, Animal Feed, Bakery end User: Fitness Enthusiasts, Vegetarians, Vegans, Health-Conscious Consumers |
| Companies Covered | Ingredion Incorporated, Roquette Frères, A. Costantino & C. spa, Brenntag SE, Cargill Incorporated, Archer Daniels Midland Company, Kerry Group PLC, The Scoular Company, DuPont de Nemours Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Plant Protein Market Shifts & Advancements
Enzymatic processing advances are collapsing cost differentials between commodity concentrates and premium isolates, while regulatory pressure on sustainability documentation is reshaping procurement specifications across Italian food manufacturing.
Extrusion texturization technology is collapsing the formulation barrier between mid-tier concentrates and premium isolates in meat analogue applications. Emilia-Romagna-based meat substitute manufacturers are adopting twin-screw extrusion at accelerated rates to achieve fibrous textures without 90%+ protein isolates. This capability compression is enabling regional brands to compete with multinational analogues at 60-70% ingredient cost.
EFSA safety assessment protocols for novel protein hydrolysates are tightening documentation requirements for allergenicity and bioactive peptide characterization. Italian ingredient importers must now submit extended clinical data packages that extend market access timelines by 12-18 months. Small and mid-sized formulators in Lombardy are responding by prioritizing established pea and soy sources over emerging fermentation-derived alternatives.
Ingredient sourcing decisions now pivot on verified carbon intensity metrics rather than unit pricing alone. Large retail chains in Northern Italy are unbundling sustainability certification from volume rebates, forcing suppliers to adopt third-party lifecycle assessment tools. This specification shift concentrates procurement power with processors capable of documenting scope 3 emissions across agricultural inputs, extraction energy, and logistics.
Italy Plant Protein Market Segmentation
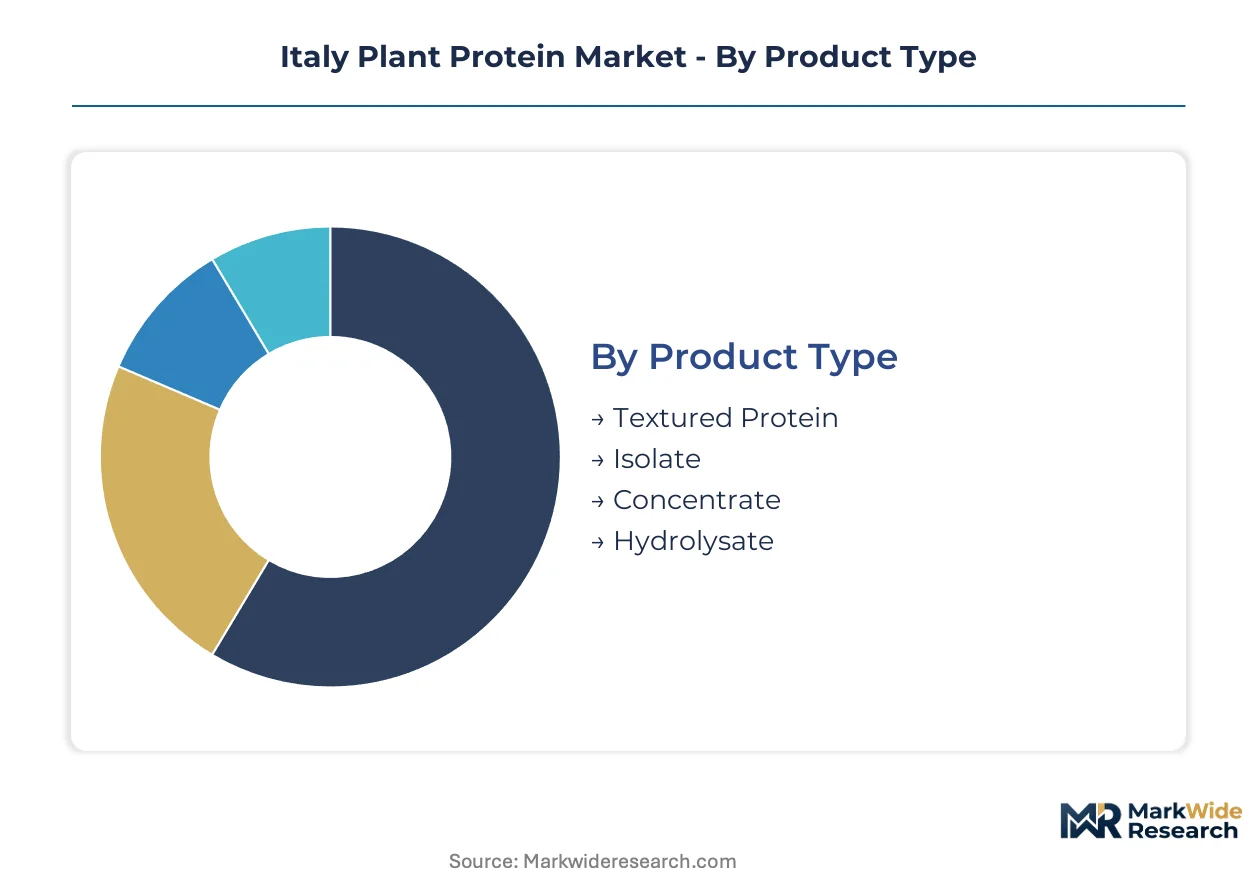
Italian formulators select protein ingredients based on functional requirements, nutritional targets, and processing compatibility. Segmentation reveals how supply-side capabilities align with demand from meat analogue manufacturers, sports nutrition brands, and traditional bakery operations across Northern and Southern Italy.
Product Type:
Cost tier differentiation separates commodity concentrates from premium isolates and emerging hydrolysates in Italian procurement specifications.
- Isolate:Protein content exceeding 90% enables clean-label beverage fortification and high-water-holding meat analogue formulations. Lombardy-based CPG manufacturers prioritize isolates for pan-European retail distribution where EFSA nutritional claims require verified amino acid profiles.
- Textured Protein:Extruded fibrous structures from pea and soy concentrates replicate meat mouthfeel at 40-60% lower ingredient cost than isolate-based systems. Emilia-Romagna meat substitute producers are adopting twin-screw extrusion to achieve texture parity with multinational brands.
- Concentrate:Mid-tier protein content (60-80%) serves cost-sensitive bakery enrichment and animal feed applications.
- Hydrolysate:Pre-digested peptide formats accelerate absorption for sports nutrition powders targeting fitness enthusiasts in Milan and Rome.
Isolate holds installed capacity. Textured protein is rotating up the share rankings.
Source:
Application requirements and allergen management drive source selection across Italian food manufacturing clusters.
- Pea:Low allergenicity and neutral flavor profile position yellow pea as the default choice for next-generation meat analogues. Netherlands-based extraction capacity supplies Northern Italian formulators, though domestic processing investments under the National Recovery and Resilience Plan are reducing import dependency.
- Soy:Established supply chains and cost efficiency sustain soy's dominance in traditional bakery applications and animal feed. Wheat gluten occupies mature volume pools in pasta and bread systems where Italian heritage recipes require specific rheological properties.
- Wheat:Gluten fractions provide viscoelastic structure in traditional Italian bakery applications resistant to plant protein substitution.
- Rice:Hypoallergenic positioning serves specialized infant nutrition and clinical formulations with strict allergen exclusion protocols.
Soy maintains formulation ubiquity. Pea is climbing the fastest in new product development pipelines.
Application:
Volume concentration varies by end-use maturity and regulatory scrutiny intensity across Italian food sectors.
- Food & Beverage:Meat analogues, dairy alternatives, and functional beverages absorb the majority of high-functionality isolates. Northern Italian manufacturers leverage proximity to Emilia-Romagna ingredient clusters for just-in-time procurement of extruded textures.
- Bakery:Traditional pasta and bread production lines require substantial retrofit investment to handle high-viscosity protein-enriched dough systems, slowing adoption outside premium positioned brands.
- Nutritional Supplements:Sports powders and clinical nutrition target fitness enthusiasts and aging populations in urban centers.
- Animal Feed:Cost-driven substitution of fishmeal and soy meal in aquaculture and pet food applications.
Food & Beverage commands primary offtake. Nutritional Supplements is gaining share fastest in value terms.
End User:
Customer type segmentation reveals divergent price sensitivity and functionality requirements across Italian consumer bases.
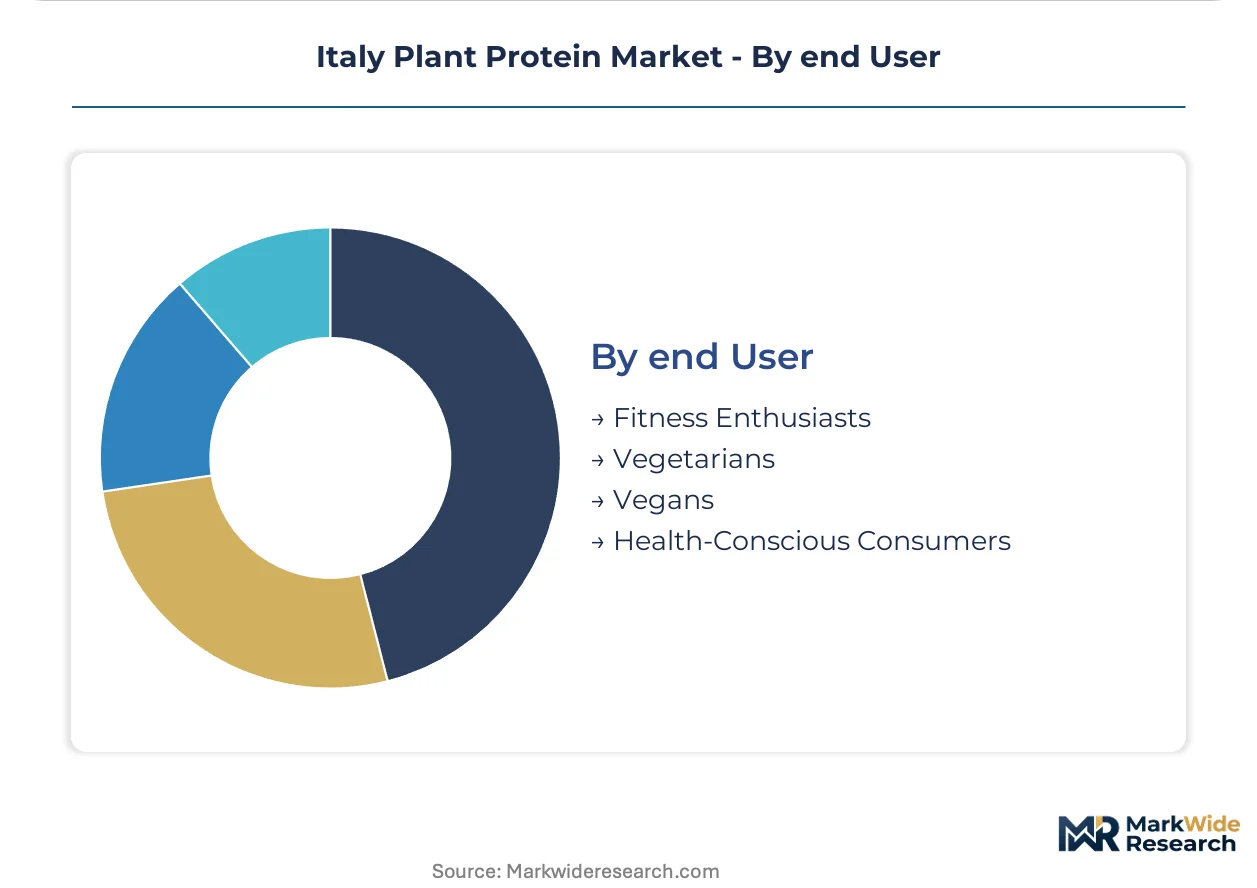
- Health-Conscious Consumers:Flexitarian households seeking protein diversification drive mainstream retail adoption of plant-based alternatives. This cohort accepts taste trade-offs for perceived nutritional benefits and sustainability credentials verified through third-party lifecycle assessments.
- Vegans:Ethical positioning demands complete animal protein exclusion, creating demand for multi-source blends that deliver complete amino acid profiles without dairy or egg cross-contamination.
- Vegetarians:Lacto-ovo flexibility permits dairy and egg protein combinations, reducing pressure on plant protein functionality requirements.
- Fitness Enthusiasts:Performance-oriented consumers prioritize leucine content and digestibility scores in post-workout formulations.
Health-Conscious Consumers anchor volume demand. Vegans is rotating up the share rankings as product ranges expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extraction capacity concentrates in the Netherlands and Northern Italy, creating procurement dependencies that domestic processors are addressing through National Recovery and Resilience Plan investments. Regional demand clusters in Lombardy and Emilia-Romagna serve pan-European CPG distribution networks.
Lombardy
Milan-based food manufacturers drive isolate demand for beverage fortification and meat analogue formulations. EFSA nutritional claim requirements shape procurement specifications for pan-European retail distribution. The Milan metropolitan area anchors Northern Italy's ingredient processing cluster with just-in-time supply relationships to Emilia-Romagna extrusion facilities.
Emilia-Romagna
Bologna and Modena host twin-screw extrusion adoption for textured protein production at 40-60% lower ingredient cost than isolate-based systems. EU Green Deal Farm to Fork sustainability documentation mandates accelerate investment in traceable supply chains. Regional meat substitute manufacturers achieve texture parity with multinational brands through advanced extrusion capabilities.
Piedmont
Turin-based CPG brands expand pea protein incorporation into retail-ready products for European distribution. National Recovery and Resilience Plan subsidies unlock domestic processing capacity expansion for ingredient security. The region's automotive supplier heritage transfers precision manufacturing expertise to food processing equipment adaptation.
Veneto
Verona and Padua formulators prioritize established pea and soy sources over fermentation-derived alternatives due to EFSA safety assessment timeline uncertainties. Italy's Ministry of Health enforces EU Novel Food regulations that delay market entry for emerging protein sources. Regional dairy alternative producers leverage proximity to Alpine water resources for clean-label positioning.
Lazio
Rome-centered sports nutrition brands drive hydrolysate demand for fitness enthusiasts prioritizing leucine content and digestibility scores. EFSA safety assessment protocols require 18-24 month evaluation windows that constrain product launch schedules. The capital region's clinical nutrition concentration serves aging population segments with specialized allergen exclusion formulations.
Italy Plant Protein Market Competitive Landscape
Multinational ingredient suppliers and specialized European processors split the market between scale-driven commodity supply and customized functional solutions. Netherlands-based extraction capacity anchors supply security for Southern European customers, while domestic Italian distributors compete on formulation technical service. Three archetypes dominate: global agribusiness conglomerates with backward integration into oilseed crushing, specialized protein extraction technology licensors, and regional compounders with blending capabilities for bakery and snack applications. Competitive moves concentrate on long-term offtake agreements for capacity reservation and sustainability certification investments for retail chain compliance.
Within the multinational supplier tier, Roquette Frères and Cargill Incorporated exemplify divergent strategic positions. Roquette leverages its European processing network to anchor ingredient security for Southern European customers requiring consistent isolate supply. Cargill competes through backward integration into European oilseed crushing that secures feedstock autonomy. Kerry Group PLC occupies a specialized position in customized protein blends, representing the technical service archetype that supports Italian bakery and snack formulators with application-specific solutions.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Roquette Frères |
| A. Costantino & C. spa |
| Brenntag SE |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Kerry Group PLC |
| The Scoular Company |
| DuPont de Nemours Inc. |
| Others |
Supply & Pricing Matrix
Single-source dependency on Netherlands-based pea protein extraction capacity determines both the three-tier pricing structure across premium isolates, standard concentrates, and economy-grade textured formats, and the supply chain shape that forces Italian manufacturers into long-term offtake agreements or captive asset investments.
Pricing Analysis
EU Green Deal Farm to Fork sustainability documentation mandates dictate the pricing tier structure, separating premium isolates with verified carbon intensity metrics from standard concentrates and economy-grade extruded textures. Price differentiation hinges on certification grade for EFSA nutritional claims and volume scale commitments from Lombardy-based CPG manufacturers. Cost compression in textured protein tiers is intensifying because twin-screw extrusion advances enable regional brands to achieve isolate-comparable functionality at reduced ingredient spend. Small formulators exhibit highest price sensitivity, while multinational meat analogue producers absorb premium isolate costs for pan-European retail compliance.
Supply Chain Analysis
Yellow pea and fava bean feedstock sourcing draws from Canadian prairie harvests, Ukrainian Black Sea corridor flows, and domestic Italian acreage expansion under National Recovery and Resilience Plan subsidies. Raw material dependencies center on protein crop variability, enzymatic processing inputs, and extrusion equipment components from German precision manufacturers. Single-source vulnerability concentrates in Netherlands-based extraction facilities above 90% protein isolate output. Distribution runs through Emilia-Romagna ingredient clusters serving Northern Italian formulators with just-in-time textured protein delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across application requirements and regional penetration gaps creates acquisition and expansion opportunities as flexitarian demand diversifies procurement specifications beyond commodity supply.
For Market Incumbents: Harden formulation autonomy through backward integration into domestic extraction assets under National Recovery and Resilience Plan incentives, and anchor customer relationships via sustainability certification investments that satisfy Northern Italian retail chain procurement specifications against emerging precision-fermentation ingredient suppliers. For New Entrants and Emerging Players: Build out direct-to-manufacturer digital procurement platforms that compress distributor margins and grant Campania and Sicily food manufacturers access to bulk isolates previously reserved for volume buyers, while targeting underserved Southern Italian regions with technical service capabilities for high-viscosity protein-enriched dough systems. For Investors and Strategic Acquirers: Anticipated EU protein strategy revisions reshape the acquisition landscape toward processors capable of documenting scope 3 emissions across agricultural inputs and extraction energy. Long-term viability favors specialized European extraction technology licensors with established EFSA safety assessment track records. Monitor EFSA hydrolysate approval timelines as inflection indicators for fermentation-derived ingredient category viability.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Extraction Capacity Expansion | National Recovery and Resilience Plan subsidies reduce import dependency on Netherlands-based supply. |
| Sustainability Certification Investment | Third-party lifecycle assessment tools satisfy EU Green Deal Farm to Fork documentation mandates. |
| Twin-Screw Extrusion Adoption | Emilia-Romagna facilities achieve texture parity with multinational brands at reduced ingredient cost. |
| Direct-to-Manufacturer Platform Launch | Digital procurement channels enable smaller Lombardy formulators to access bulk isolates. |
| Precision Fermentation R&D Partnership | Enzymatic hydrolysis integration opens novel beverage fortification categories pending EFSA approval. |
Research Methodology
The analysis maps isolates, concentrates, textured proteins, and hydrolysates, each validated through primary interviews with ingredient procurement managers, food formulation chemists, extrusion equipment specialists, and retail category buyers, combined with secondary validation from EFSA safety assessment databases, EU customs trade records, National Recovery and Resilience Plan disbursement filings, and CPG manufacturer sustainability reports. Bottom-up volume modeling and top-down value triangulation cross-check segment estimates.
Assumptions held fixed include EFSA regulatory timelines, Netherlands extraction capacity utilization rates, and Black Sea grain corridor stability, while variables tested encompass pea crop yield volatility, precision fermentation technology cost curves, and flexitarian adoption rates across Northern versus Southern Italian regions. CAGRs were derived from segmented growth trajectory analysis across product type, source, application, and end user dimensions, incorporating protein functionality premium decay rates and extrusion technology diffusion curves.
Stress conditions across Canadian harvest variability, energy input cost spikes, and EFSA novel food classification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with revision triggers tied to EU protein strategy publication and domestic processing subsidy allocation shifts. Cross-checking against pan-European ingredient trade flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Meat Alternatives Market
Plant Based Food
Tempeh Market
Plant Based Food
Plant Derived Proteins Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Asia-Pacific Rice Protein Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Plant-Based Wafer Biscuits Market
Plant Based Food
Africa Soy Beverages Market
Plant Based Food
Plant-Based Fish Market
Plant Based Food
Asia-Pacific Pea Protein Market
Plant Based Food
Plant-Based Diet Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Plant Based Meat Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
Vegan Alternatives Market