
 Fiber Syrup Market | 2026-2036
Fiber Syrup Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Syrup Market Analytics
Food manufacturers is collapsing as the dominant buyer archetype while health stores and direct-to-consumer channels gain procurement share. Cargill leverages its corn wet-milling infrastructure to anchor supply of resistant starch syrups for North American beverage clients. Roquette Frères dominates European pea-derived fiber syrup output through its Lestrem biorefinery complex. Tate & Lyle differentiates via vertical control from chicory cultivation through refined inulin syrup distribution.
Fiber syrup denotes concentrated aqueous solutions of soluble dietary fibers—predominantly inulin, oligofructose, or methylcellulose—typically standardized to 70-75% dry solids content through enzymatic hydrolysis or aqueous extraction, serving primarily as bulking agents, prebiotic substrates, and sugar replacers in reduced-calorie formulations. Inulin and oligofructose product types occupy the largest volume share due to established GRAS status and broad compatibility with dairy and bakery matrices. The dietary supplements application segment records the fastest expansion as encapsulation technologies improve fiber syrup stability in gummy and softgel formats.
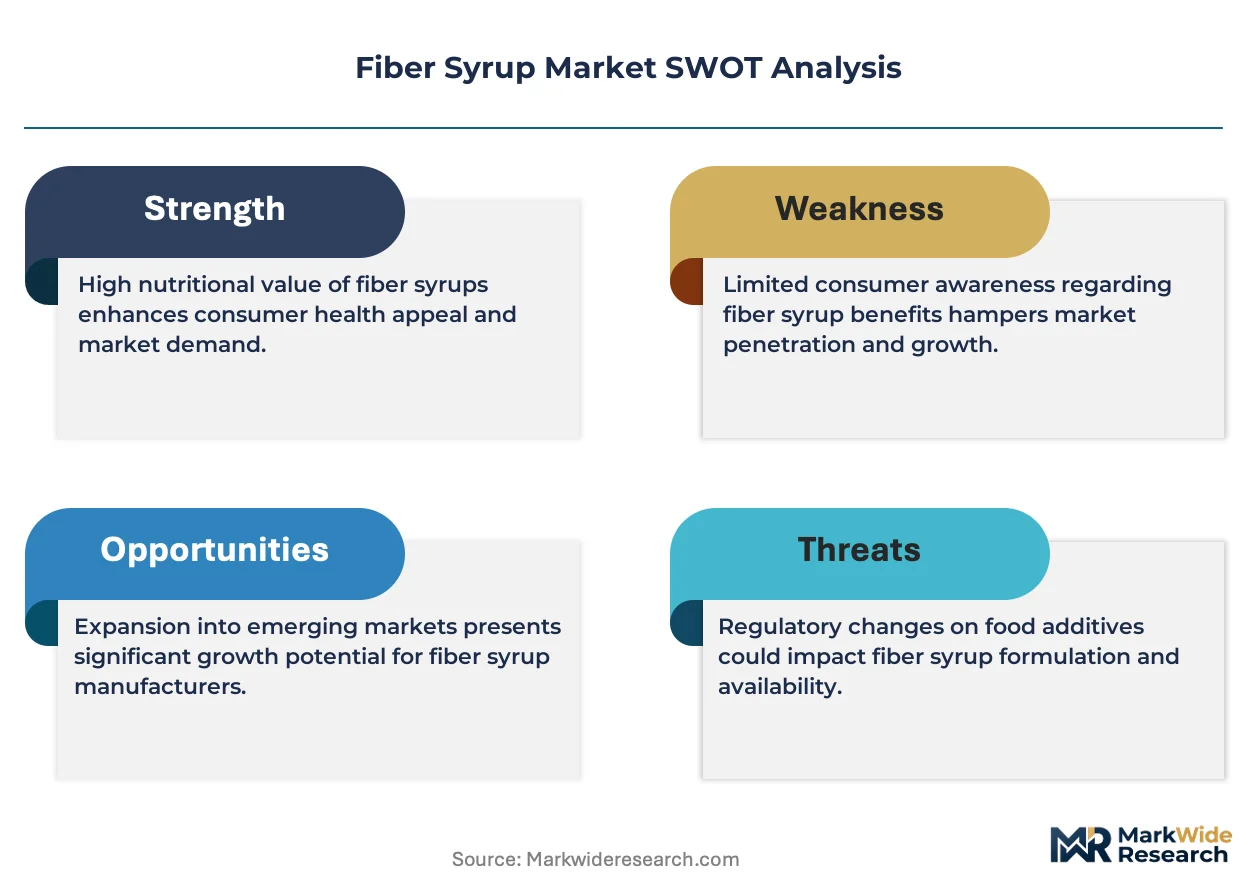
EFSA novel food approvals, FDA GRAS notifications, and EU F-Gas Regulation compliance requirements collectively elevate entry barriers for new fiber syrup suppliers while redirecting R&D investment toward fermentation-derived alternatives. The USDA BioPreferred program and Health Canada labeling standards further condition product positioning in North American retail channels. Stakeholders must monitor evolving prebiotic health claim substantiation standards across EFSA and FDA jurisdictions to anticipate reformulation cycles and qualification timelines.
Market Dynamics
Clean-label sugar replacement mandates are compressing procurement timelines for inulin and oligofructose syrups as functional beverage formulators accelerate reformulation cycles to meet EFSA novel food authorization requirements.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined approvals for fermentation-derived fiber syrups are accelerating product qualification timelines for European suppliers seeking GRAS-equivalent status.
- Prebiotic Health Claim Substantiation:Evidentiary standards for gut microbiome benefits are creating qualification moats that favor established chicory-root processors with clinical trial portfolios.
- Resistant Starch Syrup Adoption:Corn wet-milling infrastructure in North America is enabling cost-competitive supply of low-glycemic bulking agents for sports nutrition applications.
Market Restraints
- Chicory Root Supply Concentration:Belgian and Dutch agricultural zones dominate raw material sourcing, exposing processors to climate-induced harvest volatility and input price spikes.
- EU F-Gas Regulation Compliance:Refrigeration-dependent extraction facilities face retrofitting costs and purity benchmark tightening for imported fiber syrups entering European distribution.
- Enzymatic Hydrolysis Energy Intensity:Aqueous extraction and refining processes carry elevated thermal energy requirements that compress margins against fermentation-derived alternatives.
Strategic Opportunities
- Pea-Derived Fiber Syrups:European pulse protein processors are capturing stranded starch fractions for upcycling into prebiotic syrups serving plant-based dairy alternatives.
- Direct-to-Consumer Channel Expansion:Health stores and subscription wellness platforms are bypassing traditional food manufacturer intermediaries for encapsulated fiber syrup formats.
- USDA BioPreferred Program Alignment:Federal procurement preferences for biobased ingredients are opening institutional foodservice channels for domestically produced resistant starch syrups.
Industry Challenges
- Encapsulation Technology Talent Scarcity:Gummy and softgel stability engineering requires specialized formulation chemists in short supply across contract manufacturing organizations.
- Multi-Jurisdictional Labeling Harmonization:Divergent prebiotic claim substantiation standards between EFSA and FDA jurisdictions force parallel qualification investments and reformulation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Syrup Market |
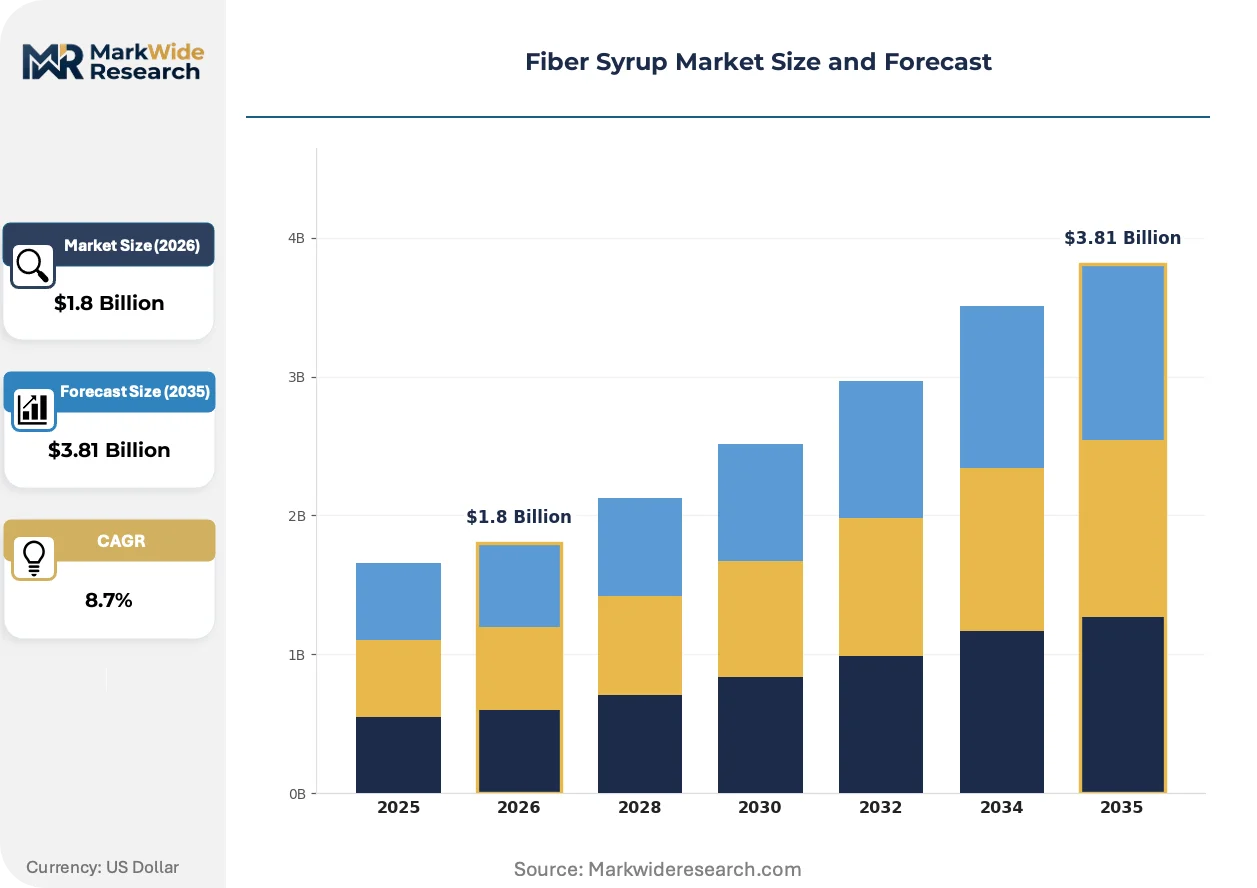
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
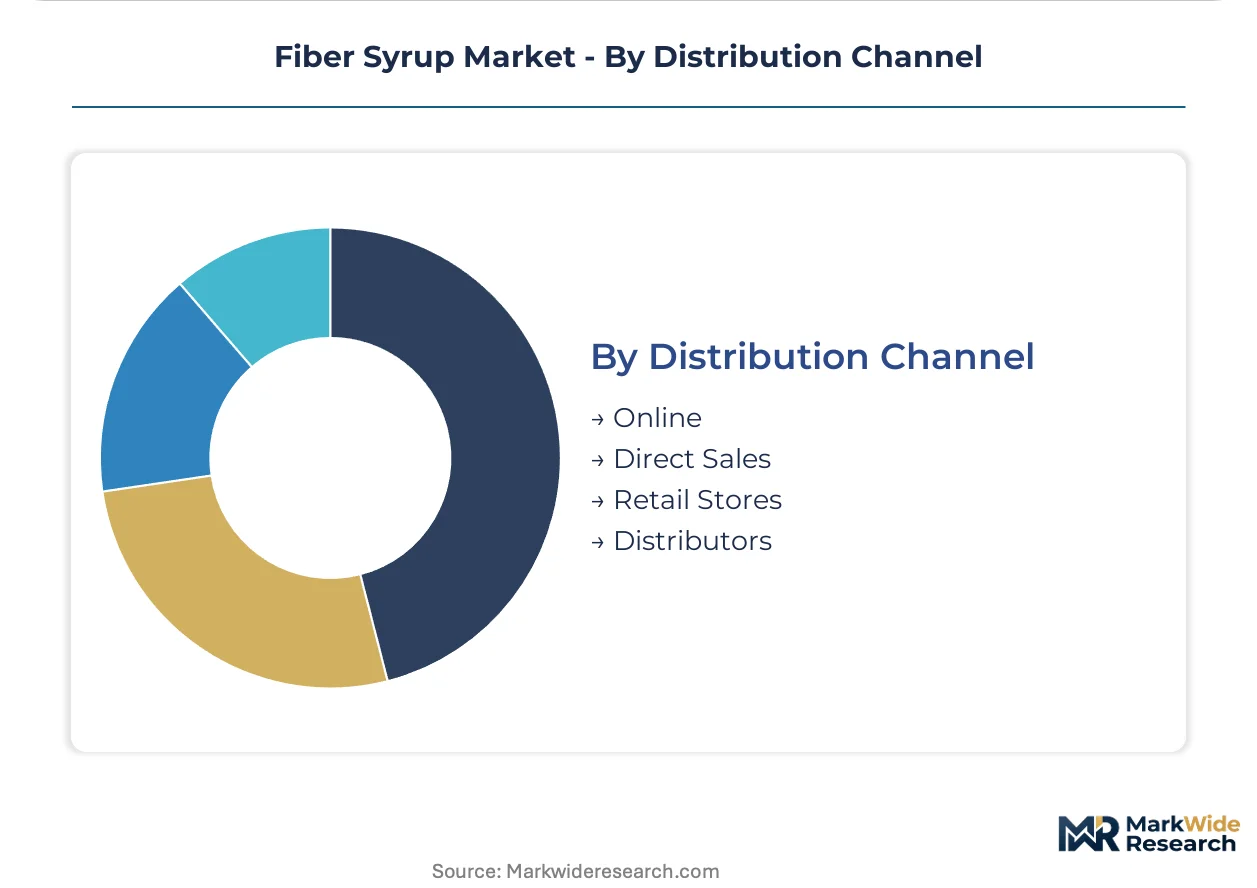
| Segmentation | Product Type: Inulin, Oligofructose, Methylcellulose, Psyllium Application: Food & Beverage, Dietary Supplements, Pharmaceuticals, Confectionery End User: Food Manufacturers, Health Stores, Restaurants, Hospitals Distribution Channel: Online, Direct Sales, Retail Stores, Distributors |
| Companies Covered | Tate & Lyle PLC, Cargill, Ingredion Incorporated, Roquette Frères, Archer Daniels Midland Company, BENEO GmbH, Grain Processing Corporation, Tereos, BeghinSay S.A.S., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Syrup Market Evolving Landscape
Fermentation-derived soluble fiber production is reshaping cost structures and supply geography as biotechnology platforms achieve commercial scale for alternative substrates to chicory extraction.
Precision fermentation of microbial cellulose is supplanting root-based extraction for high-purity methylcellulose syrups. North American ingredient suppliers are deploying this technology to bypass agricultural commodity cycles. The shift is compressing capital intensity requirements for new market entrants while enabling year-round production scheduling independent of harvest seasons.
REACH and EU F-Gas Regulation amendments are tightening solvent recovery and emissions benchmarks for extraction facilities. Chicory-root processors in Belgium and northern France face mandatory equipment upgrades. The regulatory pressure is redirecting capital expenditure toward closed-loop aqueous systems and bioreactor-based alternatives with lower thermal footprints.
Functional beverage brands are consolidating supplier relationships around vertically integrated chicory processors with captive cultivation and refining capabilities. Direct sourcing contracts are displacing spot-market procurement for inulin syrups. Germany and the Netherlands host the densest concentration of these preferred supplier arrangements, with formulators prioritizing batch traceability and novel food dossier completeness over unit cost minimization.
Fiber Syrup Market Segmentation
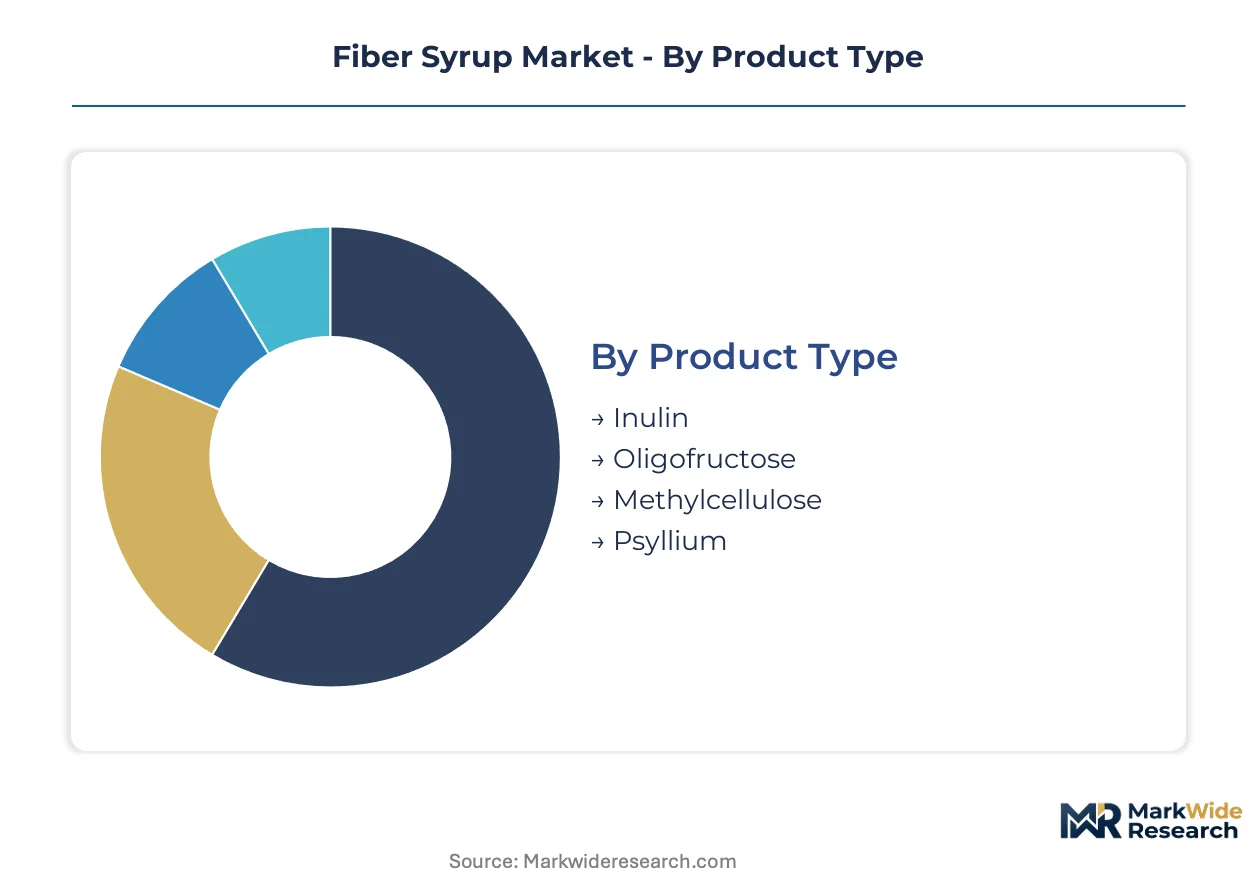
Fiber syrup procurement patterns diverge sharply across product chemistry, end-use formulation requirements, and channel access. Understanding where each segment concentrates geographically reveals sourcing vulnerabilities and margin pressure points for procurement teams.
Product Type:
Domestic cultivation capacity determines supply security, with root-based extraction concentrated in northwest European agricultural zones while fermentation-derived alternatives expand through North American biotechnology infrastructure.
- Inulin:Chicory-root extraction yields linear fructan polymers with 2-60 degree of polymerization, standardized to 70% dry solids for dairy and bakery applications. German and Belgian processors dominate volume through integrated cultivation-to-refining operations, though climate volatility in these zones elevates price risk for North American buyers dependent on import contracts.
- Oligofructose:Shorter-chain fructooligosaccharides produced through partial enzymatic hydrolysis of inulin or direct synthesis from sucrose. Sports nutrition formulators in the United States drive accelerating demand for low-glycemic bulking agents, with corn wet-milling infrastructure enabling domestic supply alternatives to European chicory dependence.
- Methylcellulose:Fermentation-derived soluble fiber from microbial cellulose processing achieves high purity without agricultural commodity exposure. Precision biotechnology platforms in North America and Asia-Pacific are scaling commercial production to bypass root-extraction seasonality.
- Psyllium:Seed husk extraction from Plantago ovata cultivation in India supplies bulk laxative and pharmaceutical applications. Indian processors control upstream agricultural sourcing, with export volumes conditioning on monsoon-dependent harvest yields.
Inulin holds the largest share; momentum sits with oligofructose as beverage reformulation accelerates.
Application:
Formulation complexity and regulatory qualification burden separate commodity-grade from specialty-grade demand, with health claim substantiation requirements creating tiered entry barriers across end-use categories.
- Food & Beverage:Clean-label sugar replacement in dairy alternatives, functional beverages, and reduced-calorie baked goods constitutes the foundational volume base. EFSA novel food authorization and FDA GRAS notification pathways determine supplier qualification timelines for European and North American CPG brands respectively.
- Dietary Supplements:Encapsulation-stable fiber syrups for gummy and softgel formats command premium pricing as prebiotic positioning gains retail shelf space. Stability engineering requirements and specialized formulation chemist scarcity constrain contract manufacturing capacity expansion.
- Pharmaceuticals:Excipient-grade methylcellulose and psyllium serve controlled-release tablet matrices and bulk-forming laxative formulations. Pharmacopeial compliance with USP-NF or EP monographs elevates purity specifications above food-grade alternatives.
- Confectionery:Sugar-free and reduced-glycemic candy applications leverage inulin and oligofructose for humectancy and mouthfeel replication. European confectionery manufacturers source predominantly through direct contracts with Belgian and Dutch chicory processors.
Food and beverage commands volume leadership; dietary supplements are climbing the fastest as encapsulation technologies mature.
End User:
Procurement scale and technical specification sophistication vary dramatically, from bulk ingredient buyers with captive R&D capabilities to channel intermediaries dependent on finished-goods distributors.
- Food Manufacturers:Integrated CPG and beverage companies with in-house formulation teams purchase syrup in tanker quantities, specifying dry solids content, microbiological standards, and novel food dossier completeness. Direct supplier relationships with chicory processors predominate over distributor intermediaries.
- Health Stores:Independent and chain retailers of natural products are expanding private-label fiber supplement lines, sourcing encapsulated formats through contract manufacturers rather than bulk syrup procurement.
- Restaurants:Foodservice operators experimenting with functional menu items represent emerging demand for pre-portioned fiber syrup formats, though volume remains marginal against manufacturing-scale buyers.
- Hospitals:Clinical nutrition and therapeutic food applications require pharmaceutical-grade documentation, with procurement flowing through group purchasing organizations and specialized medical nutrition suppliers.
Food manufacturers dominate procurement tonnage; health stores are gaining share fastest through direct-to-consumer channel expansion.
Distribution Channel:
Channel selection reflects buyer scale, technical capability, and geographic proximity to processing infrastructure, with digital platforms eroding traditional distributor dominance in smaller-lot transactions.
- Online:E-commerce platforms and B2B marketplaces serve small-lot buyers, specialty ingredient seekers, and direct-to-consumer wellness brands lacking established supplier relationships. Digital procurement is displacing traditional distributor relationships for volumes below tanker-truck thresholds.
- Direct Sales:Large food manufacturers and pharmaceutical companies contract directly with chicory processors, corn wet-millers, or fermentation biotechnology firms. These arrangements prioritize batch traceability, long-term price stability, and joint R&D collaboration over spot-market flexibility.
- Retail Stores:Physical distribution of consumer-packaged fiber supplements through mass-market and specialty retail channels represents finished-goods rather than ingredient-level demand.
- Distributors:Regional ingredient distributors maintain inventory positions for mid-tier food manufacturers without direct processor relationships, though margin compression from online alternatives is forcing consolidation.
Direct sales anchor volume concentration; online channels show steepest expansion trajectory as digital procurement platforms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicory-root processing clusters in northwest Europe anchor supply security for inulin and oligofructose syrups, while North American biotechnology infrastructure scales fermentation-derived alternatives. Procurement patterns diverge sharply between these zones.
Germany
Functional beverage formulators in Hamburg and Cologne drive accelerating demand for clean-label sugar replacers. The EU F-Gas Regulation tightens purity benchmarks for imported fiber syrups entering German distribution. Tate & Lyle operates integrated chicory-root processing facilities in the Lower Saxony region serving pan-European food manufacturers.
United States
Sports nutrition brands and beverage reformulators in Chicago and Minneapolis expand procurement of resistant starch syrups. FDA GRAS notification pathways determine supplier qualification timelines for domestic CPG brands. Cargill leverages corn wet-milling infrastructure in the Midwest to anchor supply for North American clients.
Belgium
Dairy alternative manufacturers source inulin syrups through direct contracts with Belgian chicory processors. REACH amendments tighten solvent recovery benchmarks for extraction facilities in Flanders. The port of Antwerp handles bulk syrup shipments bound for confectionery manufacturers across the Low Countries.
France
Reduced-calorie bakery applications in Paris and Lyon concentrate demand for oligofructose bulking agents. EFSA novel food authorization requirements elevate entry barriers for new fiber syrup suppliers. Roquette Frères dominates pea-derived fiber syrup output through its Lestrem biorefinery complex in the Hauts-de-France region.
India
Pharmaceutical excipient buyers in Mumbai and Hyderabad source psyllium fiber for bulk-forming laxative formulations. The country's national food safety regulator conditions import clearances on microbiological documentation. Indian processors control upstream Plantago ovata cultivation in Gujarat and Rajasthan, with export volumes tied to monsoon-dependent harvest yields.
Fiber Syrup Market Competitive Landscape
Concentration sits with integrated agricultural processors and fermentation biotechnology platforms. The supplier base separates into chicory-root extractors with captive cultivation, corn wet-millers leveraging starch infrastructure, and precision fermentation specialists. Strategic moves center on backward integration into raw material supply and geographic expansion of refining capacity.
Among European chicory processors, Tate & Lyle PLC and BENEO GmbH exemplify the integrated archetype with upstream control over cultivation through distribution. Cargill anchors the North American resistant starch segment. These three occupy positions defined by feedstock access and regulatory dossier completeness rather than unit cost competition.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Cargill |
| Ingredion Incorporated |
| Roquette Frères |
| Archer Daniels Midland Company |
| BENEO GmbH |
| Grain Processing Corporation |
| Tereos |
| BeghinSay S.A.S. |
| Others |
Value Network & Pricing Analysis
Chicory-root processing scale in Belgium and the Netherlands anchors price floors for European inulin syrups while fermentation-derived alternatives from North American biotechnology platforms compress margins through year-round production scheduling independent of harvest cycles. Contract structures bifurcate between long-term offtake agreements favored by integrated CPG manufacturers and spot-market procurement serving mid-tier formulators without captive supplier relationships.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade methylcellulose with USP-NF certification from food-grade inulin and commodity oligofructose. Price differentiation rests on purity benchmarks and novel food dossier completeness rather than brand premiums. Pricing pressure stems from fermentation-derived substitutes achieving cost parity with root-extraction methods. Health stores and direct-to-consumer wellness brands exhibit highest price sensitivity, while pharmaceutical excipient buyers prioritize pharmacopeial compliance over unit cost.
Supply Chain Analysis
Inventory lead times for chicory-root inulin extend through seasonal harvest windows in Belgium, northern France, and the Netherlands, forcing buyers to lock annual contracts before autumn processing campaigns. Raw material sourcing draws from agricultural cultivation zones vulnerable to climate-induced yield volatility, corn wet-milling infrastructure in the United States Midwest, and precision fermentation bioreactors scaling in North America. Single-source vulnerability concentrates in Belgian and Dutch chicory processors controlling upstream cultivation. Distribution runs through direct sales contracts for large manufacturers and regional distributors for mid-tier buyers lacking processor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fiber syrup procurement is shifting toward platform economics as functional beverage brands consolidate around vertically integrated suppliers with captive cultivation and complete novel food dossiers, creating interoperability moats that lock out spot-market competitors.
For Market Incumbents: Fortify backward integration into chicory cultivation in Belgium and the Netherlands to secure raw material supply against climate volatility. Expand fermentation-derived capacity in North America to capture sports nutrition demand resistant to European import dependence. Prioritize EFSA novel food authorization investments to maintain qualification moats against biotechnology entrants.
For New Entrants and Emerging Players: Encapsulation technology scarcity in contract manufacturing organizations presents white-space opportunity for gummy and softgel stability engineering capabilities. Target dietary supplement brands seeking direct-to-consumer channel expansion with finished-format fiber syrups bypassing bulk ingredient procurement. Deploy precision fermentation platforms to bypass agricultural commodity cycles and achieve cost-competitive methylcellulose production.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation biotechnology specialists with commercial-scale microbial cellulose platforms over capital-intensive root-extraction infrastructure. Long-term viability hinges on regulatory qualification speed and prebiotic health claim substantiation portfolios. Monitor EFSA novel food approval timelines as inflection indicator for European market access competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Tate & Lyle and BENEO secure Belgian and Dutch chicory supply against climate volatility. |
| Fermentation Capacity Expansion | North American biotechnology platforms bypass harvest seasonality through precision microbial cellulose production. |
| Novel Food Dossier Investment | EFSA authorization pathways create qualification barriers favoring established processors with clinical trial portfolios. |
| Encapsulation Technology Acquisition | Contract manufacturers address formulation chemist scarcity for gummy and softgel stability engineering. |
| Direct-to-Consumer Channel Launch | Health stores and wellness platforms bypass traditional food manufacturer intermediaries for finished supplement formats. |
Research Methodology
Operator-level perspectives from chicory processing plant managers, functional beverage formulation directors, dietary supplement contract manufacturing executives, and pharmaceutical excipient procurement leads anchored the qualitative base. Secondary validation drew from EFSA novel food registers, FDA GRAS notifications, EU F-Gas Regulation compliance filings, and customs trade data for inulin and oligofructose syrup movements. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Sensitivity analysis tested forecast robustness across alternative scenarios for prebiotic health claim substantiation timelines and fermentation technology cost curves. Segmentation dimensions spanned product chemistry, application formulation requirements, end-user procurement scale, and distribution channel access. CAGRs were derived from trend extrapolation adjusted for regulatory qualification velocity and substitution elasticity between root-extraction and fermentation-derived supply sources.
Underlying assumptions cover EFSA novel food authorization throughput rates and chicory harvest yield stability, with deviation risk concentrated in climate-induced agricultural volatility and biotechnology scale-up timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Smoked Dextrose Market
Flavorings and Food Additives
North America Flavors and Fragrances Market
Flavorings and Food Additives
Apple Essence Market
Flavorings and Food Additives
Dairy Flavors Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
De Oiled Lecithin Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Taste Modulators Market
Flavorings and Food Additives
Flavor Oil Market
Flavorings and Food Additives
Beverage Flavoring Agent Market
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Caralluma Extract Market