
 Global Beverage Flavoring Systems Market | 2026-2036
Global Beverage Flavoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Beverage Flavoring Systems Market Analysis
EU F-Gas Regulation is broadening the cost-of-entry calculus for flavor houses operating emulsion-based systems. Givaudan leverages its botanical extraction network to sustain natural flavor leadership across premium soft drink portfolios. Kerry Group anchors its position through integrated taste and nutrition platforms that span beverage manufacturers and food service channels.
Beverage flavoring systems comprise formulated flavor compounds—natural extracts, synthetic molecules, and enhancers—typically dosed at 0.01-0.5% by volume to impart or intensify sensory profiles in finished drinks. These systems serve the industrial purpose of standardizing taste consistency across high-volume production runs while enabling rapid product line extensions. Natural flavors command margin premiums as clean-label positioning spreads from soft drinks into alcoholic beverages and dairy applications. Liquid formulations dominate high-throughput bottling operations, whereas concentrates gain traction in functional drinks where precise micronutrient co-delivery matters.
FDA oversight of generally recognized as safe substances, EFSA flavoring substance evaluations under EU Regulation 1334/2008, and China's NMPA food additive approvals collectively determine which molecules enter regional formulations. REACH compliance costs in Europe and evolving GB standards in China are pushing multinationals toward unified global ingredient palettes rather than region-specific variants. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of R&D allocation and supply chain architecture.
Market Dynamics
Clean-label mandates from EFSA and FDA are forcing beverage manufacturers to purge synthetic molecules from formulations, compressing reformulation timelines and elevating natural extraction capacity as the binding constraint on output expansion.
Growth Catalysts
- Functional beverage proliferation:Sports nutrition and nootropic drink manufacturers are integrating flavor systems with bioactive delivery, expanding addressable volume per SKU.
- EU F-Gas Regulation:Emulsion-based cooling systems face phase-down schedules, redirecting capital toward ambient-stable natural extract technologies.
- China NMPA pathway streamlining:Accelerated food additive approval timelines for botanical extracts are shortening product launch cycles in the world's largest soft drink market.
Market Restraints
- Vanilla and citrus extract supply volatility:Madagascar and Florida weather disruptions propagate price spikes through natural flavor portfolios within one harvest cycle.
- REACH compliance cost concentration:Small and mid-sized flavor houses lack toxicology dossier budgets, consolidating formulation expertise among multinationals with captive regulatory affairs teams.
- Natural-synthetic parity gap:Heat-stable synthetic molecules still outperform botanical extracts in ultra-high-temperature processing, limiting clean-label penetration in ambient dairy.
Strategic Opportunities
- India FSSAI enforcement gaps:Localized natural flavor production for masala-based carbonated drinks remains underdeveloped relative to demand growth in tier-two cities.
- Precision fermentation convergence:Biosynthesized rare terpenes from microbial hosts are collapsing cost curves for boutique flavor molecules previously extracted from scarce botanicals.
- Direct-to-manufacturer digital platforms:Flavor houses are bypassing traditional distribution layers to offer bespoke formulation services through cloud-based sensory matching tools.
Industry Challenges
- Sensory scientist scarcity:Cross-training chemists in both gas chromatography and consumer preference modeling extends hiring timelines to nine months in competitive labor markets.
- Legacy ERP integration friction:Flavor dosing automation on 1990s-era bottling lines demands custom middleware development that delays line certification.
- Co-manufacturer IP exposure:Shared production facilities risk formulation leakage when multiple beverage brands operate under non-exclusive tolling agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Beverage Flavoring Systems Market |
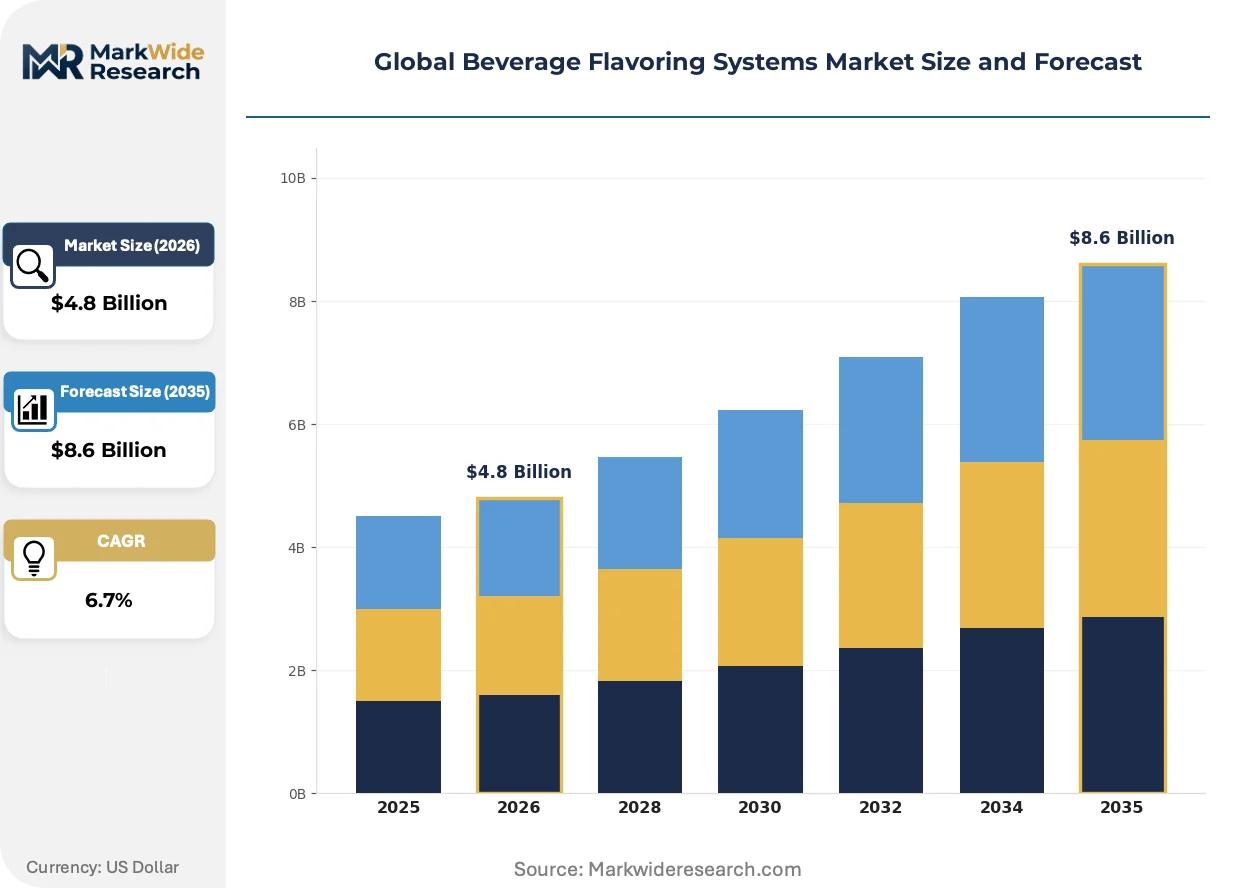
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Natural Flavors, Artificial Flavors, Flavor Enhancers, Flavor Extracts Application: Soft Drinks, Alcoholic Beverages, Functional Drinks, Dairy Beverages Formulation Type: Concentrates, Powders, Liquids, Emulsions End User: Beverage Manufacturers, Food Service Providers, Retailers, Home Brew Enthusiasts |
| Companies Covered | Cargill, Archer Daniels Midland Company, Givaudan, Sensient Technologies, Kerry Group, International Flavors & Fragrances, Tate & Lyle, Döhler, Takasago International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Beverage Flavoring Systems Market Emerging Trajectories
Digital sensory mapping tools and biotechnology-derived molecules are collapsing the traditional gap between artisan flavor craft and industrial scale, rewriting how beverage manufacturers source and specify taste systems.
Precision fermentation is decentralizing rare flavor molecule production by enabling biosynthesis of saffron-derived picrocrocin and oak lactones in stainless steel bioreactors. Mid-sized flavor houses in Germany and the United States are commissioning 10,000-liter fermentation capacity to bypass agricultural supply chains. This technology is decentralizing geographic dependence on tropical botanical harvests while compressing batch-to-batch variation below 3% coefficient.
REACH authorization requirements under EU Regulation 1907/2006 are forcing systematic substitution of persistent synthetic musks with biodegradable alternatives. Flavor houses operating emulsion systems face 2026 deadlines for full substance dossier submission. The premium spirits segment in France and Italy is accelerating natural maceration programs to preempt authorization denials on legacy molecules.
Beverage manufacturers are consolidating supplier rosters from twelve flavor vendors to three preferred partners with integrated taste-nutrition platforms. This compression is displacing transactional spot purchasing with multi-year co-development contracts indexed to volume tiers. The shift is most visible in Germany, where private-label functional drink producers are locking in exclusive botanical extraction partnerships.
Global Beverage Flavoring Systems Market Segmentation
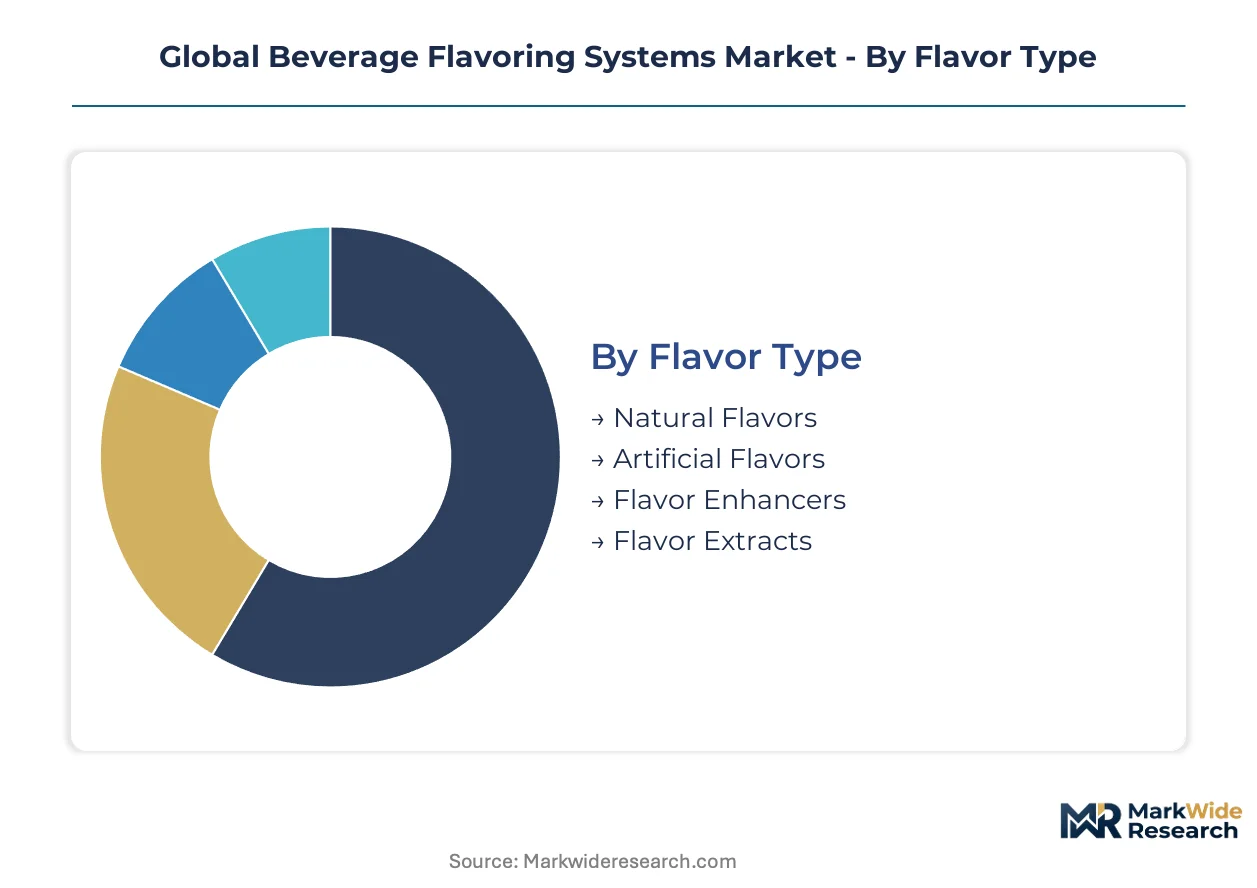
Beverage flavoring systems fragment across four intersecting dimensions that determine capital deployment, margin structure, and regulatory exposure. Each category carries distinct technical barriers and customer concentration patterns that reshape competitive positioning.
Flavor Type:
Natural extraction infrastructure demands the heaviest upfront capital outlay among flavor type segments, with botanical sourcing networks and solvent recovery systems consuming disproportionate investment.
- Natural Flavors:Botanical extracts and essential oils derived from named-source raw materials. Demand concentrates in premium soft drink portfolios across Germany and France, where EFSA clean-label mandates are compressing synthetic alternatives. Madagascar vanilla and Florida citrus supply disruptions propagate price volatility through formulations within single harvest cycles.
- Artificial Flavors:Chemically synthesized molecules engineered for heat stability and batch consistency. Alcoholic beverage manufacturers in the United States anchor volume, leveraging synthetic cost advantages in high-proof neutral spirits where thermal processing degrades botanical extracts.
- Flavor Enhancers:Potentiators and modulators that amplify perceived intensity without adding distinct taste notes.
- Flavor Extracts:Concentrated preparations from single botanical sources, typically standardized for key aromatic compounds.
Most installed capacity flows through Artificial Flavors. Expansion is steepest in Natural Flavors.
Application:
Volume concentration and margin tier diverge sharply across beverage categories, with functional drinks commanding formulation premiums while soft drinks anchor throughput scale.
- Functional Drinks:Sports nutrition, nootropics, and wellness beverages requiring co-delivery of bioactives and taste masking. China NMPA approval streamlining is accelerating launch velocity for botanical-based functional formulations in the world's largest addressable market.
- Soft Drinks:Carbonated and still beverages representing the foundational demand base. United States bottlers are consolidating supplier rosters from twelve vendors to three preferred partners with integrated taste-nutrition platforms.
- Alcoholic Beverages:Spirits, beer, and ready-to-drink cocktails with distinct thermal and alcohol-solubility constraints.
- Dairy Beverages:Flavored milk and fermented drinks where ultra-high-temperature processing limits clean-label penetration.
Soft Drinks absorb the majority of flavor system volume. Functional Drinks are climbing the fastest.
Formulation Type:
Processing equipment compatibility and shelf-stability requirements segment formulation demand by customer technical sophistication and line automation level.
- Liquids:Pumpable solutions optimized for high-throughput bottling operations with automated dosing systems. United States and German beverage manufacturers dominate procurement, prioritizing line integration over ingredient cost minimization.
- Concentrates:High-potency preparations enabling precise micronutrient co-delivery in functional drink applications. Precision fermentation-derived rare terpenes are collapsing cost curves for boutique molecules previously extracted from scarce botanicals.
- Powders:Spray-dried or encapsulated formats for dry-mix beverage applications.
- Emulsions:Oil-in-water dispersions for fat-soluble flavor delivery, facing EU F-Gas Regulation phase-down pressures on cooling-dependent production systems.
Liquids dominate current installed dosing infrastructure. Concentrates are gaining share fastest.
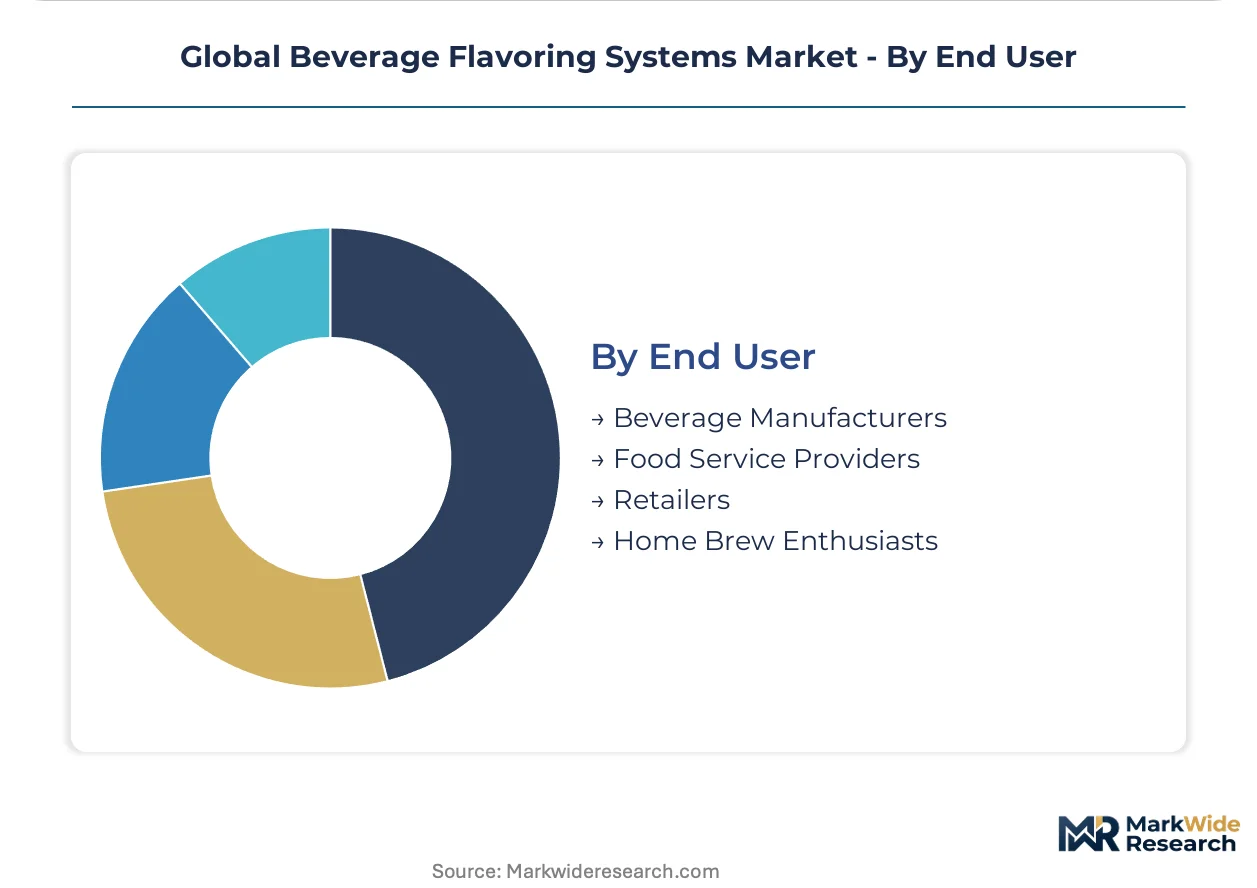
End User:
Procurement sophistication and technical specification authority fragment sharply between industrial-scale manufacturers and fragmented downstream channels.
- Beverage Manufacturers:Multinational and regional bottlers with captive R&D and regulatory affairs teams. Kerry Group and Givaudan are anchoring positions through multi-year co-development contracts indexed to volume tiers, displacing transactional spot purchasing.
- Food Service Providers:Fountain and dispensed beverage operators with limited formulation control.
- Retailers:Private-label brand owners outsourcing formulation to contracted flavor houses.
- Home Brew Enthusiasts:Small-batch producers and craft beverage makers purchasing through direct-to-manufacturer digital platforms.
Beverage Manufacturers command the majority of flavor system procurement. Home Brew Enthusiasts are expanding most quickly through cloud-based sensory matching tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flavor chemists and sensory scientists cluster disproportionately in Germany, the United States, and Switzerland, anchoring formulation expertise near major beverage manufacturing hubs. This talent concentration shapes where multinationals locate R&D centers and where regulatory compliance capabilities concentrate.
United States
Functional drink manufacturers in California and Texas are driving demand for co-delivery flavor systems that mask bioactive off-notes. FDA oversight of generally recognized as safe substances determines which molecules enter formulations, compressing reformulation timelines for clean-label transitions. Chicago and Atlanta host concentrated beverage innovation centers where manufacturers test localized flavor profiles before national rollout.
Germany
Private-label functional drink producers are consolidating supplier rosters from twelve vendors to three preferred partners with integrated taste-nutrition platforms. EFSA flavoring substance evaluations under EU Regulation 1334/2008 and REACH compliance costs are pushing manufacturers toward unified global ingredient palettes. Bavaria and North Rhine-Westphalia anchor natural extraction partnerships for botanical-based carbonated drinks.
China
NMPA food additive approval streamlining for botanical extracts is shortening product launch cycles in the world's largest soft drink market. Domestic beverage manufacturers in Shanghai and Guangdong are investing in localized flavor innovation centers to capture regional taste preferences. GB standards evolution is accelerating reformulation toward natural flavor extracts in premium portfolios.
France
Premium spirits manufacturers are accelerating natural maceration programs to preempt REACH authorization denials on legacy synthetic molecules. ANSM and CNIL oversight intersects with flavor safety assessments for alcoholic beverages. The Cognac and Champagne regions are anchoring heritage extraction methods that supply boutique flavor houses serving luxury portfolios.
India
FSSAI enforcement gaps in natural flavor labeling are creating opportunities for localized production of masala-based carbonated drinks in tier-two cities. Maharashtra and Gujarat beverage manufacturers are expanding capacity faster than domestic flavor extraction infrastructure can match. Imported natural extracts face customs complexity that favors regional formulation partnerships.
Global Beverage Flavoring Systems Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that concentrates formulation expertise among multinationals with captive regulatory affairs teams. Tier-one players anchor positions through multi-year co-development contracts indexed to volume tiers, displacing transactional spot purchasing. Three strategic archetypes dominate: integrated taste-nutrition platforms, botanical extraction specialists, and precision fermentation technology providers. Competitive moves center on supplier roster consolidation by beverage manufacturers and backward integration into natural extraction capacity.
Among Swiss and Irish flavor houses, Givaudan and Kerry Group exemplify the integrated platform archetype, anchoring positions through combined sensory and nutritional formulation capabilities. Cargill represents the agricultural-input-to-flavor value chain model, occupying a position that spans raw botanical sourcing through finished flavor systems. These three companies sit within the tier where scale and regulatory compliance capabilities have become the primary competitive moats.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Givaudan |
| Sensient Technologies |
| Kerry Group |
| International Flavors & Fragrances |
| Tate & Lyle |
| Döhler |
| Takasago International Corporation |
| Others |
Supply Flow & Price Mechanics
Madagascar vanilla futures and Florida citrus concentrate indices cascade through natural flavor portfolios into three-tier pricing structures across premium, standard, and economy levels. EFSA clean-label mandates compress synthetic alternatives while REACH compliance costs concentrate formulation expertise among multinationals with captive regulatory affairs teams.
Pricing Analysis
Bundled sensory-nutrition platforms versus unbundled spot purchasing splits the pricing architecture. Premium-mid-economy pricing differentiation rests on certification grade under EU Regulation 1334/2008 and volume scale in multi-year co-development contracts. Cost compression in economy-tier artificial flavors is intensifying because beverage manufacturers consolidate supplier rosters from twelve vendors to three preferred partners. Private-label functional drink producers in Germany exhibit highest price sensitivity; premium spirits manufacturers in France show least.
Supply Chain Analysis
Ocean freight rate volatility from Southeast Asian botanical hubs to European compounding facilities feeds into working capital requirements for natural extraction infrastructure. Supply concentrates in Madagascar for vanilla, Florida for citrus, and India for spice oleoresins. Raw material dependencies center on named-source botanicals, solvent recovery systems, and precision fermentation feedstocks. Single-source vulnerability propagates through agricultural harvest cycles. Distribution runs through integrated taste-nutrition platforms with multi-year offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
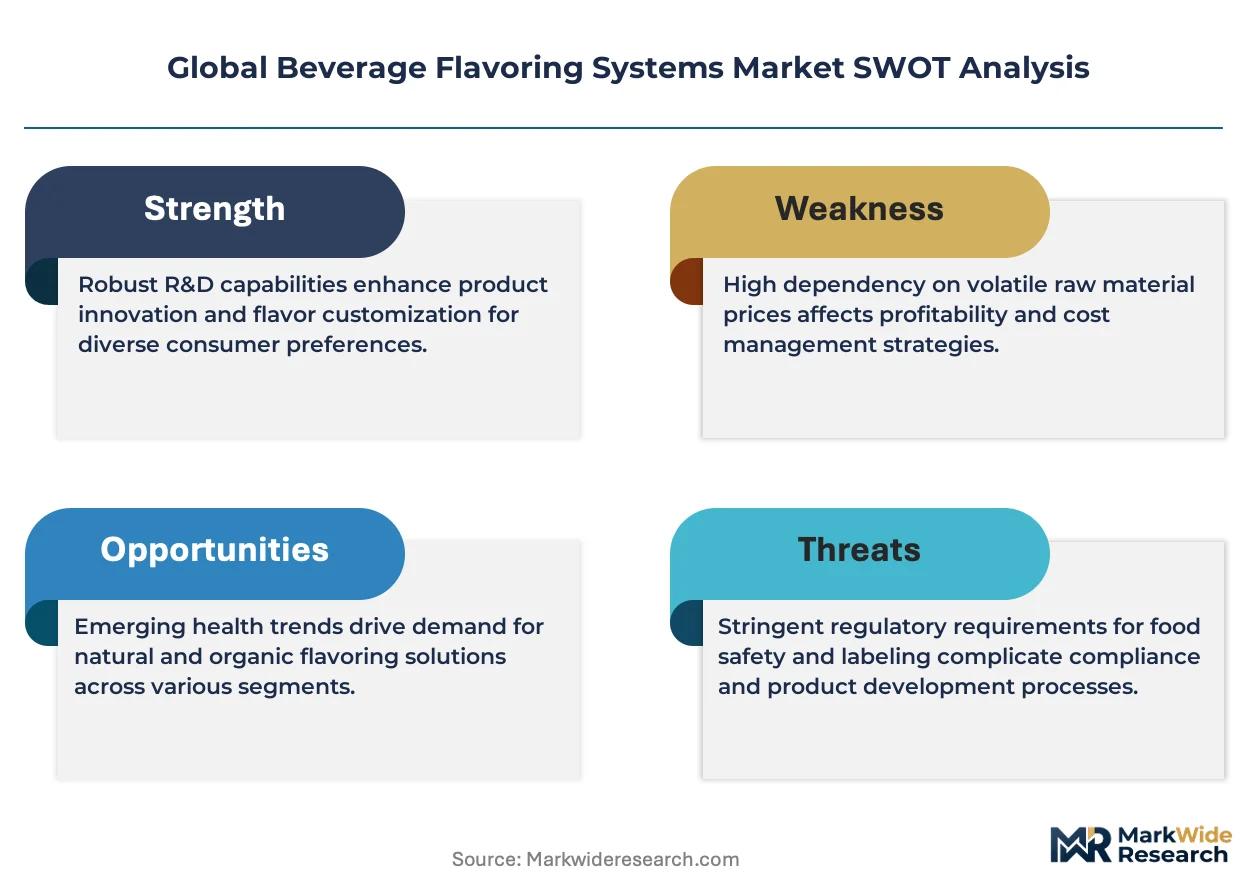
The beverage flavoring systems market operates as a regulatory compounder where EU F-Gas Regulation phase-down schedules on emulsion-based cooling systems redirect capital toward ambient-stable natural extract technologies.
For Market Incumbents: Lock in exclusive botanical extraction partnerships in Bavaria and North Rhine-Westphalia before REACH authorization deadlines force systematic substitution of legacy molecules. Deepen upstream control over Madagascar vanilla and Florida citrus sourcing networks to buffer price volatility from weather disruptions. Consolidate formulation expertise through captive regulatory affairs teams that small and mid-sized flavor houses cannot replicate. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian masala-based carbonated drinks offers immediate white-space opportunity where FSSAI enforcement gaps outpace domestic extraction infrastructure. Precision fermentation-derived rare terpenes provide a second entry vector through collapsing cost curves for boutique molecules. Target cloud-based sensory matching tools for home brew enthusiasts as the most penetrable channel with lowest incumbent saturation. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance cost concentration eliminates small and mid-sized flavor houses lacking toxicology dossier budgets. Long-term viability favors precision fermentation technology providers with 10,000-liter bioreactor capacity commissioned in Germany and the United States. Watch NMPA approval velocity for botanical extracts in China as the inflection signal determining which multinationals capture launch-cycle advantages in the world's largest soft drink market.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Biosynthesized terpenes from microbial hosts collapse cost curves for saffron-derived picrocrocin and oak lactones. |
| Natural Extraction Partnership | Exclusive botanical sourcing agreements in Cognac and Champagne regions anchor heritage extraction methods for luxury portfolios. |
| Regulatory Compliance Integration | Captive toxicology dossier teams under EU Regulation 1907/2006 preempt authorization denials on legacy synthetic molecules. |
| Direct-to-Manufacturer Platform | Cloud-based sensory matching tools bypass traditional distribution layers for bespoke formulation services. |
| Co-Development Contract Lock-In | Multi-year agreements indexed to volume tiers displace transactional spot purchasing across German private-label producers. |
Methodological Framework
Bottom-up beverage manufacturer modeling reconciled against top-down flavor house capacity tracking forms the analytical core of this study. Primary interviews with sensory scientists, regulatory affairs directors at multinationals, procurement leads at bottling operations, and precision fermentation R&D heads combined with secondary validation from FDA GRAS notifications, EFSA flavoring substance evaluations, NMPA food additive filings, and customs trade data. Triangulation across these sources ensures convergence between demand-side consumption patterns and supply-side production constraints.
Historical trendline analysis of natural versus artificial flavor adoption rates, clean-label penetration curves, and functional drink launch velocities informs the projection framework. Segmentation dimensions span flavor type, application category, formulation format, and end-user procurement sophistication across the modeling period. CAGRs derive from volume-weighted averaging of segment growth trajectories calibrated against regulatory milestone timelines and technology diffusion curves. Forecast inputs incorporate REACH authorization schedules, NMPA streamlining progress, and precision fermentation capacity commissioning.
The model assumes a particular technology adoption path; alternative pathways for biosynthesized rare terpenes would alter the outlook if microbial production economics shift faster than botanical extraction scaling. Forecasts reflect assumptions about EFSA enforcement consistency, F-Gas Regulation phase-down adherence, and China NMPA approval velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Flavoring Oil Market
Flavorings and Food Additives
Sour Cream Powder Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Kokumi Flavor Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
Mint Essential Oils Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Flavor Drops Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Nature Identical Flavorings Market