
 Dry Powder Flavors Market | 2026-2036
Dry Powder Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Powder Flavors Market Analytics
Clean-label specification tiers are redrawing competitive boundaries in dry powder flavors. Givaudan leverages captive botanical sourcing to sustain premium positioning across natural flavor portfolios. Symrise anchors European supply security through integrated extraction infrastructure in Germany and France. Firmenich differentiates via biotechnology-derived natural molecules that reduce agricultural feedstock dependence.
Dry powder flavors comprise concentrated aromatic compounds—volatile oils, oleoresins, and encapsulated essences—spray-dried or plated onto carrier substrates such as maltodextrin or gum arabic for shelf-stable dispersion in heat-processed matrices. The natural flavors segment commands margin premiums as EU Flavouring Regulation (EC) No 1334/2008 and FDA 21 CFR 101.22 labeling mandates tighten synthetic disclosure thresholds. Within end-use verticals, nutraceuticals and functional beverages represent the fastest-expanding application pool, driven by protein fortification and masking requirements in powdered supplements.
Regulatory oversight spans EFSA safety evaluations under EU Flavouring Regulation, FDA GRAS self-affirmation pathways for US market entry, and FSSAI flavor additive standards in India's expanding processed food sector. Compliance costs favor suppliers with dedicated regulatory affairs teams and pre-validated ingredient master files. Stakeholders must monitor evolving naturalness definitions and carrier substrate sustainability credentials as procurement criteria harden across multinational food manufacturers.
Market Dynamics
Clean-label migration is compressing synthetic flavor margins while concentrating procurement power among multinational food manufacturers with dedicated regulatory compliance teams. EU Flavouring Regulation (EC) No 1334/2008 disclosure thresholds are forcing reformulation cycles across bakery and savory snack portfolios.
Growth Catalysts
- EU Flavouring Regulation (EC) No 1334/2008:Disclosure mandates for synthetic additives are accelerating natural powder flavor adoption across German and French processed food corridors.
- Protein fortification:Nutraceutical manufacturers are expanding dry powder flavor procurement to mask off-notes in plant-based and dairy protein concentrates.
- Encapsulation technology:Advanced spray-drying and plating techniques are extending shelf stability in heat-processed matrices, opening new application categories.
Market Restraints
- Agricultural feedstock volatility:Natural flavor production depends on botanical sourcing subject to climate-induced supply fluctuations and price spikes.
- Carrier substrate concentration:Maltodextrin and gum arabic supply chains concentrate in specific producing regions, creating input vulnerability.
- Regulatory friction from EFSA evaluations:Novel natural molecule approvals face extended safety assessment timelines, delaying product commercialization.
Strategic Opportunities
- Biotechnology-derived molecules:Precision fermentation and enzymatic synthesis are reducing agricultural feedstock dependence while maintaining natural labeling status.
- Functional beverage expansion:Powdered hydration and energy drink mixes represent underpenetrated application white space for flavor masking solutions.
- Indian processed food sector:FSSAI flavor additive standard harmonization is opening procurement pathways for compliant international suppliers.
Industry Challenges
- Regulatory affairs talent scarcity:Specialized expertise in EU Flavouring Regulation compliance and GRAS self-affirmation pathways commands premium compensation.
- Legacy equipment retrofitting:Existing spray-drying infrastructure requires capital-intensive upgrades to handle heat-sensitive natural volatile compounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Powder Flavors Market |
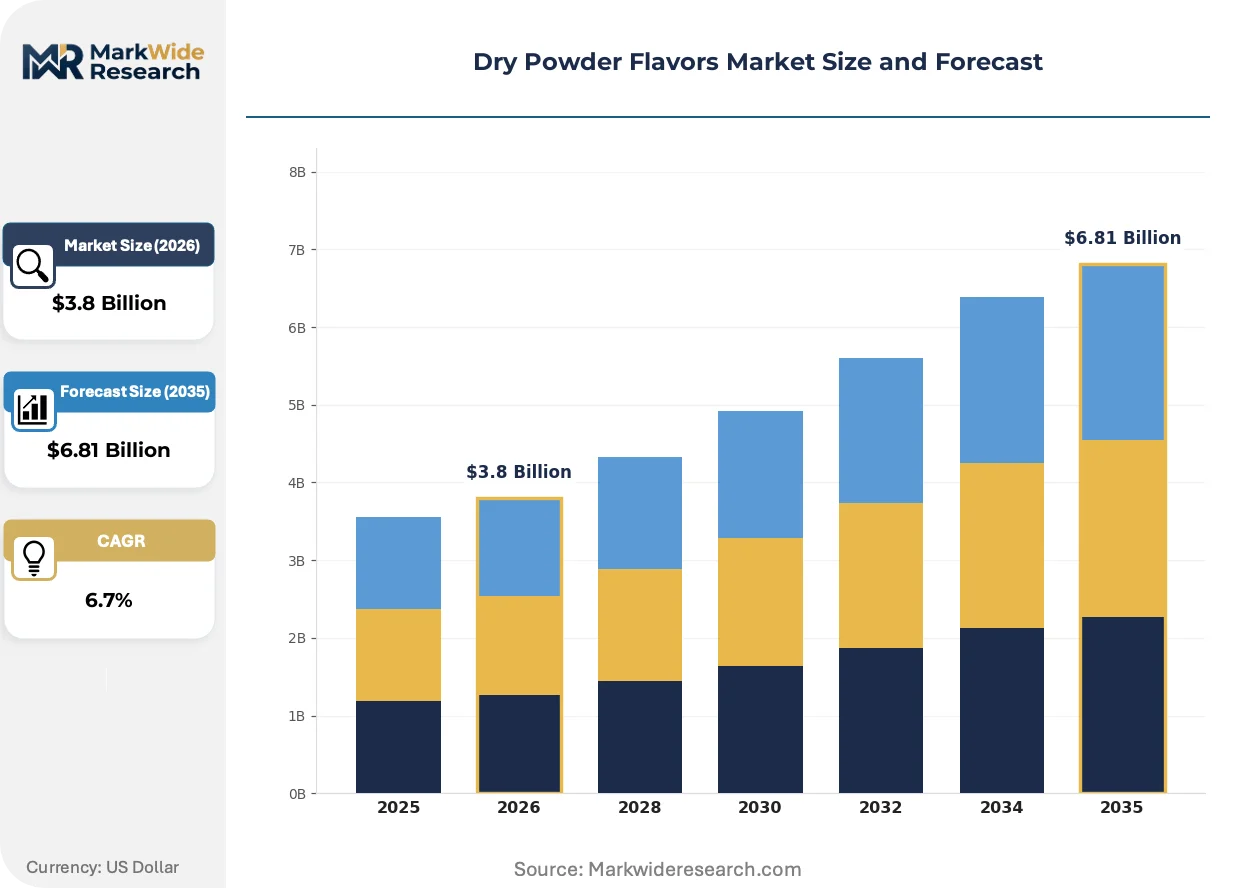
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Synthetic Flavors, Organic Flavors, Flavor Blends End Use: Food & Beverage, Nutraceuticals, Pharmaceuticals, Cosmetics Application: Baking, Seasoning, Dairy Products, Snack Foods Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Givaudan, Symrise, Firmenich, International Flavors & Fragrances, Sensient Technologies, Frutarom, Takasago, Robertet, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Powder Flavors Market Evolving Landscape
Biotechnology and precision fermentation are rewriting naturalness definitions while regulatory disclosure mandates compress synthetic flavor viability windows. Three convergent forces are reshaping competitive positioning.
Encapsulation technology is decomposing traditional spray-drying limitations by enabling higher volatile oil loading rates and improved heat stability. Bakery and savory snack manufacturers in Germany are adopting these systems at accelerated pace. The technology is decomposing cost barriers between premium natural and standard synthetic flavor tiers.
EU Flavouring Regulation (EC) No 1334/2008 disclosure thresholds are forcing label transparency across synthetic additive portfolios. Reformulation costs are compressing margins for non-compliant suppliers. Natural powder variants in bakery applications are capturing displaced procurement volumes as manufacturers preempt regulatory enforcement.
Direct procurement relationships between flavor houses and multinational food manufacturers are displacing traditional distributor intermediaries. Category managers at processed food conglomerates are consolidating supplier panels and demanding validated ingredient master files. This concentration is most visible in Germany's processed food corridor, where three-tier pricing structures are flattening into premium-standard bifurcation.
Dry Powder Flavors Market Segmentation
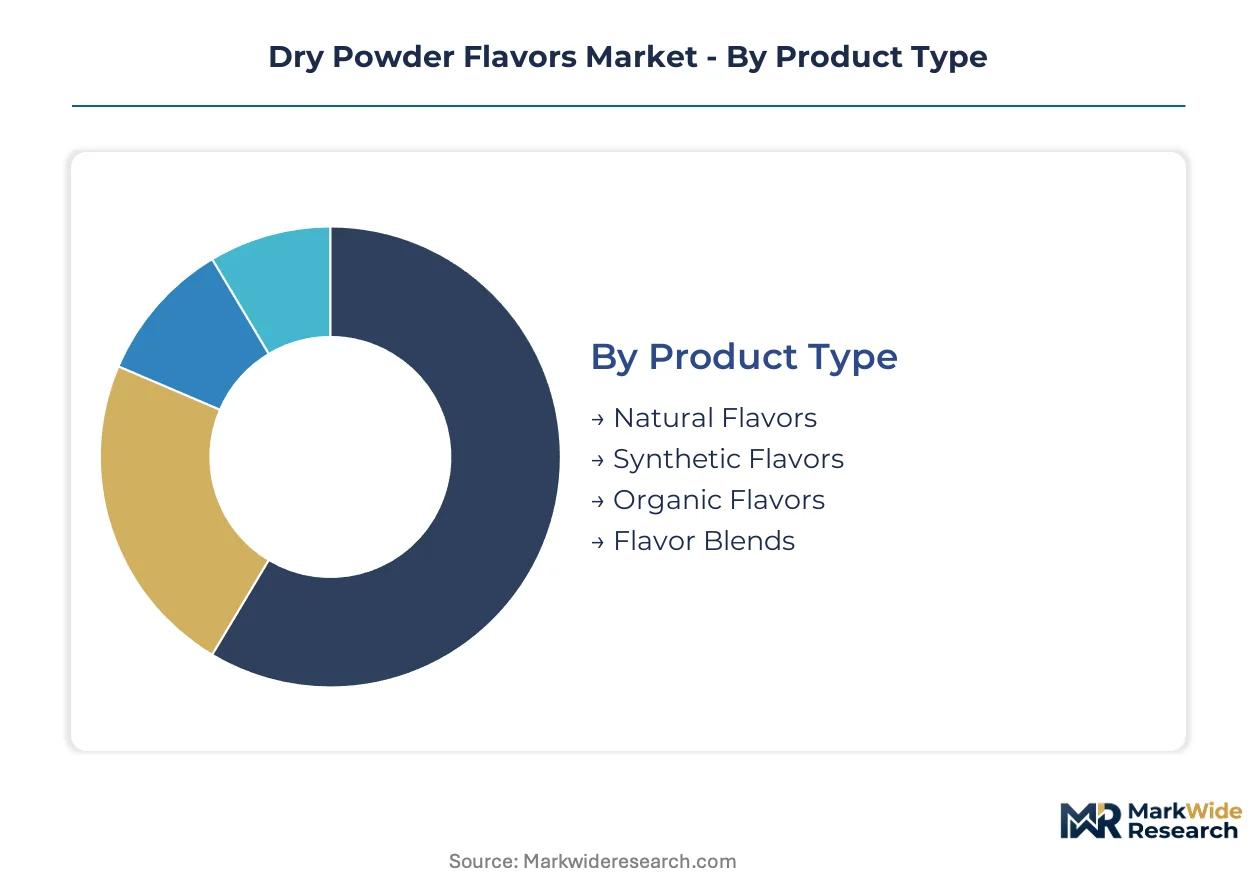
Dry powder flavors fragment across four intersecting dimensions that determine procurement patterns and margin architecture. Product type governs regulatory compliance burden and naturalness certification tiers. End-use concentration in processed food corridors shapes volume contracting and technical service requirements.
Product Type:
Natural and organic variants dominate export-led procurement from EU flavor houses, while synthetic flavors retain domestic processing concentration in cost-sensitive emerging markets.
- Natural Flavors:Derived from botanical extraction and essential oil distillation, these powders carry EU Flavouring Regulation (EC) No 1334/2008 compliance documentation. German bakery manufacturers anchor procurement volumes as clean-label mandates tighten disclosure thresholds for volatile oil concentrates.
- Synthetic Flavors:Chemically synthesized aromatic molecules plated onto maltodextrin carriers. Cost-sensitive snack producers in India and Southeast Asia sustain procurement as FSSAI flavor additive standards permit broader synthetic disclosure.
- Organic Flavors:Certified organic botanical sourcing with full traceability documentation. Premium nutraceutical manufacturers in Switzerland and France drive specification intensity.
- Flavor Blends:Proprietary combinations balancing cost and performance across natural and synthetic components. Mid-tier processed food conglomerates consolidate procurement around validated master files.
Natural Flavors commands the established base. The steepest expansion runs through Organic Flavors.
End Use:
Application requirements diverge sharply between heat-processed matrices demanding thermal stability and ambient-dispersion formats prioritizing solubility.
- Food & Beverage:Dominant consumption vertical spanning bakery, savory snacks, and beverage powders. German processed food corridors concentrate procurement as reformulation cycles accelerate under EU disclosure mandates.
- Nutraceuticals:Protein fortification and off-note masking in powdered supplements. Plant-based protein concentrates in North American functional beverage mixes drive specification intensity for encapsulation technology.
- Pharmaceuticals:Palatability enhancement for pediatric and geriatric dosage forms. Regulatory affairs teams validate excipient compatibility under FDA GRAS and EMA guidelines.
- Cosmetics:Fragrance encapsulation in powder-based personal care. Niche volume relative to ingestible applications.
Food & Beverage retains volume leadership. Nutraceuticals climbs fastest on protein fortification demand.
Application:
Heat exposure tolerance separates premium encapsulation requirements from standard plating specifications.
- Baking:High-temperature stability requirements favor advanced spray-dried encapsulation systems. German and French industrial bakeries specify volatile oil retention rates above standard thresholds.
- Seasoning:Savory snack coating applications demand uniform particle size distribution. Powder flow characteristics determine manufacturing line efficiency.
- Dairy Products:Flavored milk powders and yogurt mixes require solubility optimization. Protein interaction effects complicate flavor delivery.
- Snack Foods:Extruded and puffed product categories balance cost against heat stability. Mid-tier procurement consolidates around flavor blend solutions.
Baking anchors technical specification intensity. Snack Foods gains share on emerging market volume expansion.
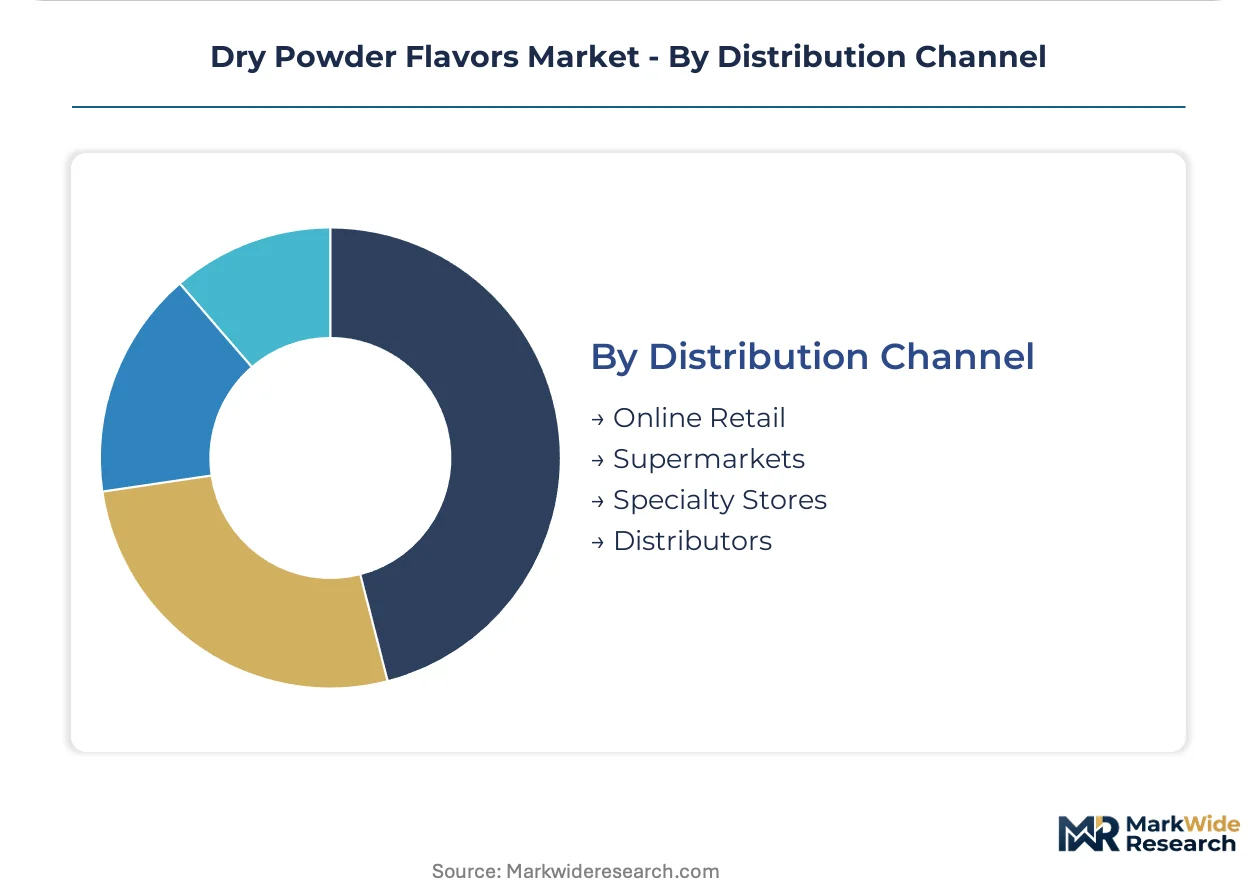
Distribution Channel:
Channel selection correlates with customer scale and technical service requirements.
- Online Retail:Direct procurement portals for small-batch and specialty manufacturers. Technical documentation access and rapid sample fulfillment drive platform selection.
- Supermarkets:Indirect route for private-label food manufacturers sourcing standardized flavor profiles. Volume contracting through retail-aligned food producers.
- Specialty Stores:Artisan and craft food producer access to premium natural and organic portfolios. Curated selection with regulatory compliance support.
- Distributors:Traditional intermediaries serving regional processed food manufacturers. Panel consolidation pressures margin structures as multinational buyers direct-source.
Distributors retain legacy volume. Online Retail expands fastest on small manufacturer digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in dry powder flavors tilt toward European flavor houses supplying reformulated natural variants to North American and Asian processors, while botanical feedstock sourcing concentrates in equatorial growing belts.
Germany
Industrial bakeries in Baden-Württemberg and North Rhine-Westphalia drive natural powder flavor procurement as EU Flavouring Regulation (EC) No 1334/2008 disclosure deadlines approach. EFSA safety evaluations govern novel molecule approvals. The Stuttgart-Mannheim corridor hosts spray-drying facilities upgrading to handle heat-sensitive volatile compounds.
United States
Protein fortification in functional beverages accelerates demand for masking flavors in plant-based concentrates. FDA GRAS self-affirmation pathways structure market entry for natural variants. Chicago and Minneapolis-St. Paul anchor Midwestern procurement clusters serving nutraceutical manufacturers.
France
Premium organic flavor specifications from Swiss and domestic nutraceutical buyers concentrate demand in the Rhône-Alpes region. ANSM oversees excipient compatibility in pharmaceutical palatability applications. Lyon-based extraction facilities integrate with German encapsulation technology suppliers.
India
Processed food expansion in Maharashtra and Gujarat sustains synthetic flavor volumes despite clean-label migration elsewhere. FSSAI flavor additive standards permit broader synthetic disclosure than EU equivalents. Mumbai-Pune industrial corridor attracts international suppliers seeking FSSAI-compliant export platforms.
Switzerland
Swissmedic guidelines for pediatric and geriatric dosage forms drive pharmaceutical-grade flavor demand. Premium nutraceutical manufacturers in Basel and Zurich specify certified organic botanical traceability. The Basel agglomeration anchors biotechnology-derived natural molecule development.
Dry Powder Flavors Market Competitive Landscape
Concentration sits with integrated European flavor houses possessing captive botanical sourcing and regulatory compliance infrastructure. Mid-tier regional blenders occupy cost-sensitive segments in emerging markets. Three archetypes dominate: vertically integrated Swiss-German houses with extraction-to-encapsulation control, biotechnology specialists leveraging precision fermentation, and regional distributors serving reformulating bakery and snack processors. M&A activity targets encapsulation technology assets, while capacity expansion concentrates in German and French spray-drying corridors.
Among the integrated European tier, Givaudan, Symrise, and Firmenich exemplify divergent strategic anchors. Givaudan represents captive botanical sourcing depth across premium natural portfolios. Symrise occupies integrated extraction infrastructure positioning across German and French supply security. Firmenich sits within biotechnology-derived molecule development, reducing agricultural feedstock exposure while preserving natural labeling status under EU Flavouring Regulation frameworks.
| Leading Market Players |
|---|
| Givaudan |
| Symrise |
| Firmenich |
| International Flavors & Fragrances |
| Sensient Technologies |
| Frutarom |
| Takasago |
| Robertet |
| ADM |
| Others |
Value Network & Pricing Analysis
Botanical feedstock substitution for synthetic precursors is redrawing procurement geography and compressing margin structures across natural flavor tiers. EU Flavouring Regulation (EC) No 1334/2008 disclosure mandates accelerate this shift, concentrating pricing power with integrated houses possessing captive extraction infrastructure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with natural certification grade and volume scale as primary differentiation drivers. Cost compression in synthetic tiers is intensifying because reformulation cycles displace volumes toward natural variants. Mid-tier snack producers exhibit highest price sensitivity, while Swiss nutraceutical manufacturers accept premium positioning for certified organic traceability.
Supply Chain Analysis
Strategic stockpiling of botanical feedstocks prevails over just-in-time approaches due to climate-induced harvest volatility. Supply concentrates in Madagascar for vanilla, India for spice oleoresins, and France for lavender and aromatic herbs. Maltodextrin and gum arabic feed from corn belt regions and Sudanese acacia stands respectively. Single-source vulnerability in equatorial growing belts threatens continuity. Distribution runs through direct procurement relationships with multinational food manufacturers, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dry powder flavors market exhibits cyclical recovery characteristics as reformulation waves triggered by regulatory disclosure deadlines create successive procurement surges across processed food corridors.
For Market Incumbents: Consolidate backward integration into botanical extraction assets to defend against biotechnology-derived molecule disruptors. Lock in maltodextrin and gum arabic supply agreements to secure carrier substrate continuity. Prioritize regulatory affairs team expansion to maintain EU Flavouring Regulation compliance velocity. For New Entrants and Emerging Players: Technical service gaps in small-batch nutraceutical formulation support represent underexploited territory. Target North American protein fortification applications where masking expertise commands premium positioning. Pursue FSSAI certification pathways to access India's processed food expansion corridor. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional blenders lacking encapsulation technology capabilities. Five-to-ten year viability hinges on biotechnology adaptation rather than traditional extraction scale. Monitor EFSA novel molecule approval timelines as inflection signal for natural flavor commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Reduces agricultural feedstock dependence while preserving EU natural labeling status. |
| Encapsulation Technology Acquisition | Captures heat-stable volatile oil loading capabilities for bakery application expansion. |
| Regulatory Affairs Infrastructure Build | Accelerates EFSA safety evaluation navigation and GRAS self-affirmation throughput. |
| Direct Procurement Portal Launch | Displaces distributor intermediaries serving small-batch craft food manufacturers. |
| Botanical Traceability Certification | Meets Swiss and French organic nutraceutical sourcing documentation requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with flavor house procurement directors, bakery and snack manufacturer category managers, nutraceutical formulation scientists, regulatory affairs specialists, and extraction facility operations heads. Secondary validation drew from EU Flavouring Regulation implementation guidance, EFSA safety evaluation databases, FDA GRAS notification records, FSSAI flavor additive standards, customs trade flow data, and SEC filings from publicly traded flavor houses. Bottom-up volume modeling triangulated against top-down market sizing across product type, end-use vertical, application format, and distribution channel dimensions.
Across the analysis window, projections integrated historical procurement pattern analysis, regulatory compliance timeline modeling, and technology adoption curve assessment. Segmentation dimensions spanned natural versus synthetic versus organic certification tiers, food and beverage versus nutraceutical versus pharmaceutical end-uses, baking versus seasoning versus dairy versus snack food applications, and distributor versus direct versus online retail channels. CAGRs derived from volume-weighted average growth across these intersecting segments, with protein fortification penetration rates and encapsulation technology diffusion curves as key demand-side inputs.
Underlying assumptions cover sustained EU Flavouring Regulation enforcement intensity, stable botanical feedstock harvest yields, and continued protein fortification trend acceleration, with deviation risk concentrated in climate-induced supply disruptions and EFSA evaluation timeline extensions. Revision becomes warranted when biotechnology-derived molecule cost parity thresholds cross below conventional extraction economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
Citrus Flavonoid Complexes from Mediterranean Peels Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Natural Flavors and Fragrances Market
Flavorings and Food Additives
Naringin Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Global Chicory Market
Flavorings and Food Additives
Coconut Syrup Market
Flavorings and Food Additives
Food Colorants Market
Flavorings and Food Additives
Food Aroma Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
Orange Extract Market
Flavorings and Food Additives
Citrus Aromatic Fractions for Mood Support Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Beverage Flavoring Agent Market
Flavorings and Food Additives
Flavor and Flavor Enhancers Market