
 Middle East and Africa Food Anti Caking Agents Market | 2026-2036
Middle East and Africa Food Anti Caking Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Food Anti Caking Agents Market Foresight
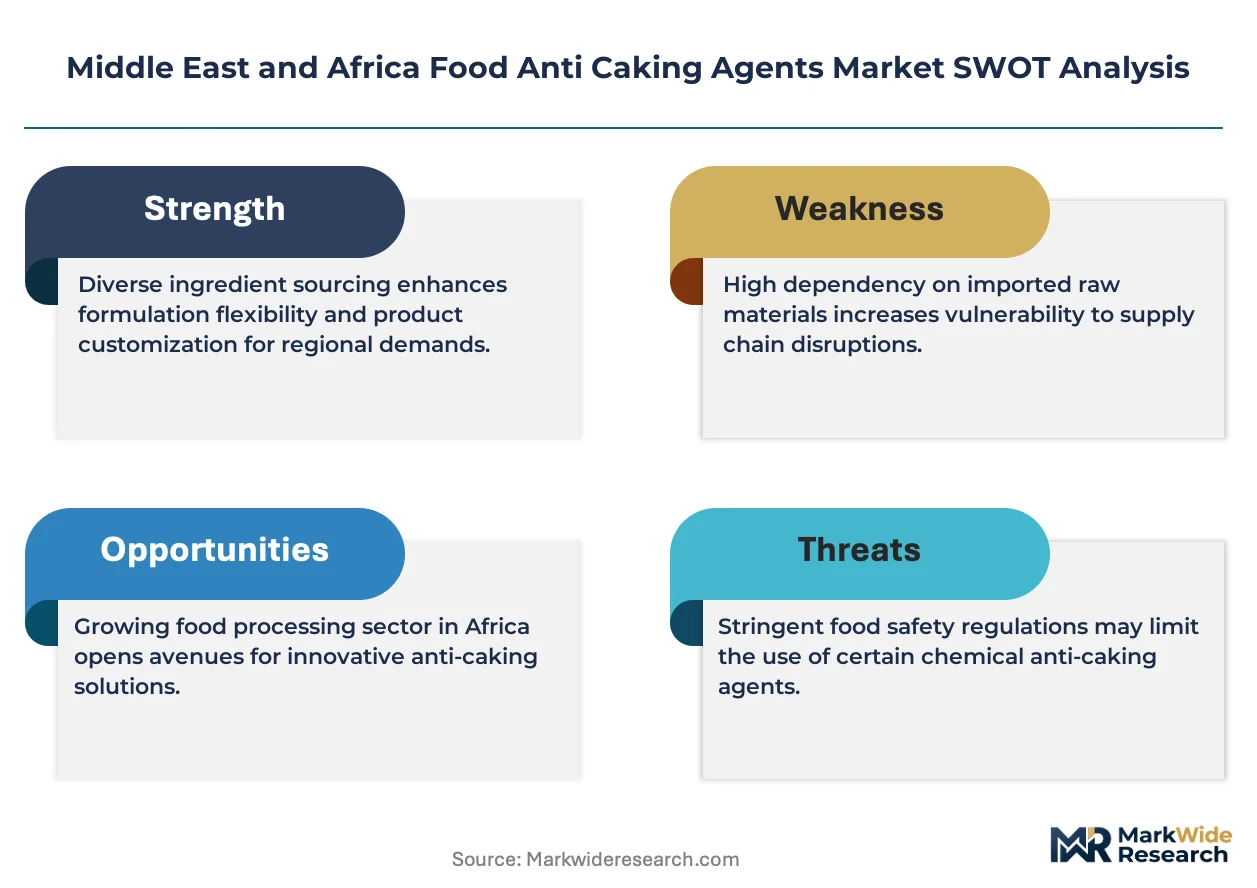
Technical advisory and formulation support services is decoupling pure ingredient sales from value capture in the Middle East and Africa Food Anti Caking Agents Market. Cargill Incorporated leverages its regional grain handling infrastructure to bundle anti-caking solutions with broader food ingredient portfolios. BASF SE anchors its position through R&D intensity in synthetic silica chemistry tailored to local humidity conditions. Evonik Industries AG differentiates via specialty precipitated silicates engineered for high-temperature processing environments prevalent in North African dairy operations.
Food anti-caking agents are powdered or granulated additives, typically composed of calcium silicate, magnesium carbonate, or phosphate salts, that absorb moisture and coat particles to prevent agglomeration during storage and transport. These agents maintain critical flow properties in hygroscopic food matrices where ambient humidity exceeds product-specific equilibrium thresholds. Calcium silicate and tricalcium phosphate dominate product type demand due to their dual functionality as both anti-caking aids and mineral fortifiers in bakery and dairy applications across the region. Sauces and seasonings represent the fastest-growing application segment as West African and Levantine food processors expand dry mix production for export markets.
Saudi Food and Drug Authority standards, Gulf Standardization Organization technical regulations, and South African Department of Health food additive controls collectively govern permissible anti-caking agent categories and maximum inclusion rates across the region. Compliance with these overlapping frameworks shapes formulation choices, particularly for multinational suppliers serving both GCC and Sub-Saharan markets from single production hubs. Stakeholders must monitor divergence between Gulf harmonized standards and national enforcement capacities as Nigeria and Kenya develop independent food additive registries.
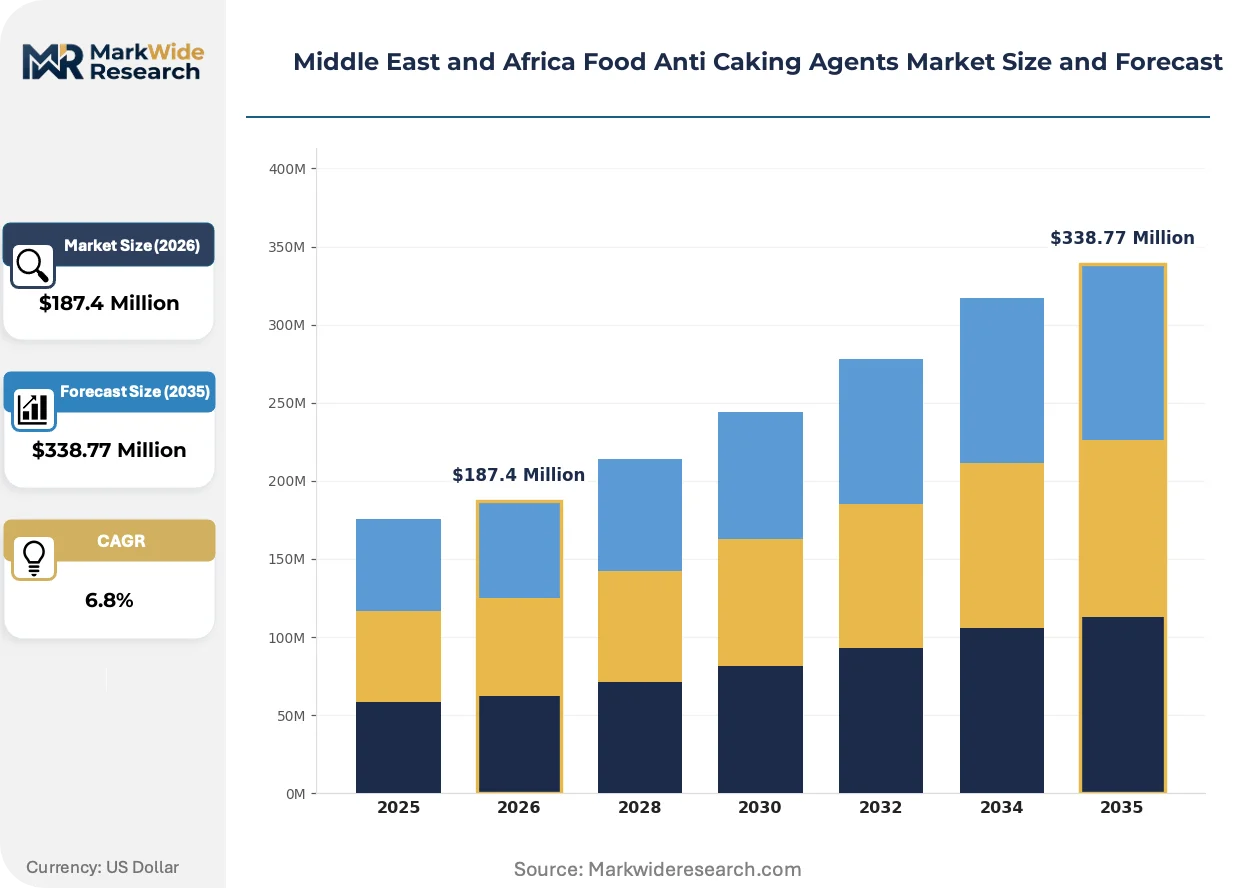
Market Dynamics
Reformulation pressure from Gulf Cooperation Council food safety standards is forcing suppliers to revalidate anti-caking agent portfolios across dual halal and mineral fortification requirements, compressing product development cycles.
Growth Catalysts
- Saudi Food and Drug Authority additive disclosure mandates:Processed dairy producers in the kingdom are accelerating procurement of phosphate-based agents to meet tightened labeling protocols ahead of enforcement deadlines.
- West African dry mix export expansion:Seasonings manufacturers in Nigeria and Ghana are scaling silicate-treated formulations to maintain powder integrity through humid port logistics and extended shelf-life requirements.
- Silica chemistry R&D localization:Specialty precipitated silicates engineered for North African dairy processing temperatures are reducing dependency on European imports.
Market Restraints
- Phosphate raw material volatility:Feedstock price swings for tricalcium phosphate are compressing margin buffers for bakery ingredient blenders serving price-sensitive North African markets.
- Single-hub supply concentration:Multinational suppliers serving both GCC and Sub-Saharan markets from centralized European production face freight cost exposure and customs clearance friction at Red Sea ports.
- Natural anti-caking substitute encroachment:Rice hull ash and cellulose derivatives are gaining trial volume in South African organic certification channels, displacing synthetic silicates in premium segments.
Strategic Opportunities
- Kenya independent additive registry development:Early engagement with Nairobi's emerging food safety framework positions suppliers to shape maximum inclusion rate standards before formal adoption.
- High-temperature dairy processing convergence:Integration of spray-drying optimization with anti-caking formulation design creates bundled service revenue streams in Egyptian and Algerian milk powder operations.
- Direct-to-processor digital channels:B2B platform procurement of anti-caking agents is bypassing traditional ingredient distributors in UAE food manufacturing zones, collapsing margin capture layers.
Industry Challenges
- Dual certification timeline compression:Simultaneous Gulf Standardization Organization technical regulation compliance and South African Department of Health additive registration is stretching regulatory affairs capacity at regional headquarters.
- Humidity-specific formulation talent scarcity:Food chemists capable of calibrating calcium silicate absorption kinetics to Red Sea coastal conditions command premium compensation, constraining technical service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Food Anti Caking Agents Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Silicate, Magnesium Carbonate, Sodium Aluminum Phosphate, Tricalcium Phosphate Application: Dairy Products, Bakery Products, Sauces, Seasonings End User: Food Manufacturers, Retailers, Food Service Providers, Household Consumers Form: Powder, Granule, Liquid, Emulsion |
| Companies Covered | Cargill Incorporated, BASF SE, Evonik Industries AG, Tate & Lyle PLC, Solvay SA, Cabot Corporation, Agropur Ingredients, PPG Industries Inc., Archer Daniels Midland Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Food Anti Caking Agents Market Shifts & Advancements
Moisture-activated coating systems are displacing static powder blends across the Middle East and Africa Food Anti Caking Agents Market, enabling responsive performance that adjusts to ambient humidity fluctuations during regional distribution.
Encapsulated nano-silica delivery systems is automating the precision dosing of anti-caking agents in high-throughput bakery lines across Saudi Arabia's processed food corridor. Large-scale flatbread producers are retrofitting continuous mixers with sensor-integrated feed systems at pace. This automation is compressing the technical service intensity traditionally required for formulation troubleshooting.
Gulf Standardization Organization harmonized additive categories are converging with evolving halal certification protocols to create unified compliance pathways for multinational suppliers. Industrial consequence includes reduced formulation variant proliferation across GCC markets. Dairy and seasonings segments are consolidating SKUs to serve Saudi Arabia, UAE, and Kuwait from single product registrations.
Buyer consolidation among West African dry mix exporters is concentrating procurement leverage in the hands of Lagos- and Accra-based food processors with integrated seasoning blending capabilities. Traditional ingredient distributors are losing volume to direct technical partnerships between anti-caking suppliers and export-oriented manufacturers. This channel compression is most visible in Nigerian chili powder and soup mix operations targeting European diaspora markets.
Middle East and Africa Food Anti Caking Agents Market Segmentation
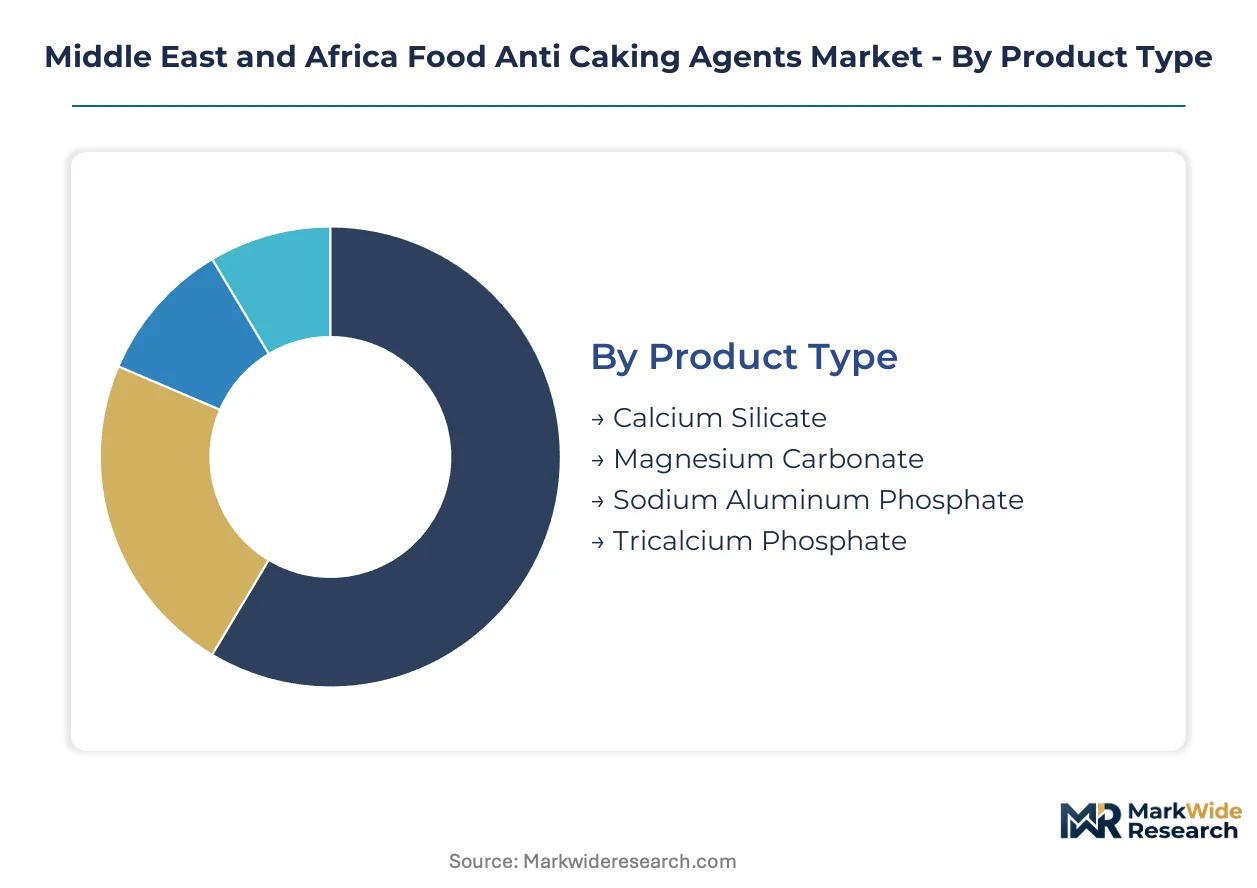
Formulation choices across the Middle East and Africa Food Anti Caking Agents Market hinge on humidity exposure, processing temperatures, and dual halal-fortification requirements. Procurement patterns diverge sharply between Gulf dairy processors seeking phosphate-based mineral enrichment and West African seasonings exporters prioritizing moisture absorption through silicate chemistry.
Product Type:
Cost tier determines procurement priority, with mineral fortification value and raw material volatility shaping buyer trade-offs between synthetic and naturally-derived agents.
- Calcium Silicate:A porous, highly absorbent synthetic silicate that binds surface moisture on hygroscopic powders. Saudi Arabia's flatbread and milk powder producers favor this agent for its dual functionality as a mineral fortifier and flow aid in high-humidity Red Sea logistics. Tricalcium Phosphate dominates bakery and dairy applications where calcium enrichment aligns with Gulf Standardization Organization disclosure mandates and consumer nutrition labeling preferences.
- Tricalcium Phosphate:A calcium salt with moderate moisture absorption and significant mineral payload, widely specified in processed cheese and infant formula. Egyptian and Algerian dairy operations specify this phosphate for spray-drying compatibility and halal certification simplicity.
- Magnesium Carbonate:A lightweight, alkaline agent with rapid moisture uptake, deployed in cocoa powder and spice blends where pH stability matters.
- Sodium Aluminum Phosphate:An acidic leavening adjunct with secondary anti-caking properties, constrained by aluminum content scrutiny in South African health-conscious segments.
Tricalcium Phosphate leads on scale through dairy fortification volume; Calcium Silicate leads on momentum as humidity-responsive formulations expand across GCC processing corridors.
Application:
Volume concentration tracks export-oriented manufacturing scale, with dry mix production for diaspora markets driving procurement intensity.
- Sauces:Dry soup and sauce mixes require agents that maintain dispersibility through humid port storage and extended shelf life. Nigerian and Ghanaian exporters specify silicate-treated formulations to survive container transit to European markets without caking.
- Seasonings:Chili powders, curry blends, and spice mixes demand aggressive moisture management given raw material hygroscopicity. Lagos-based processors are integrating anti-caking agents directly into blending lines rather than relying on distributor-added treatments.
- Dairy Products:Milk powders, processed cheeses, and infant formulas specify phosphate agents for nutritional fortification compliance.
- Bakery Products:Flour blends and dry mixes favor calcium silicate where mineral content adds label value.
Seasonings leads on scale through West African export volume; Sauces climbs the fastest as Levantine and North African processors build dry mix capacity for Middle Eastern retail chains.
End User:
Customer type dictates technical service intensity, with integrated manufacturers bypassing traditional distribution layers.
- Food Manufacturers:Large-scale processors with in-house blending capabilities specify anti-caking agents through direct technical partnerships. Saudi dairy cooperatives and Nigerian seasonings exporters negotiate formulation support bundled with ingredient supply.
- Food Service Providers:Central kitchens and institutional caterers procure pre-treated dry mixes rather than standalone anti-caking agents.
- Retailers:Private-label dry goods suppliers specify agent inclusion rates through contract manufacturers.
- Household Consumers:Minimal direct engagement; anti-caking functionality embedded in finished packaged foods.
Food Manufacturers leads on scale through integrated procurement volume; Food Service Providers gains share fastest as Gulf hospitality sector consolidation drives centralized ingredient specification.
Form:
Supply concentration favors powder formats, though processing automation is shifting demand toward engineered physical forms.
- Powder:The standard physical state for calcium silicate and phosphate agents, offering maximum surface area for moisture absorption. Egyptian and Saudi spray-drying operations feed powder agents through pneumatic conveying systems.
- Granule:Larger particle size reduces dusting and improves flow in high-speed bakery lines.
- Liquid:Suspension formats for specialized coating applications in premium confectionery.
- Emulsion:Oil-dispersed systems for fat-based matrices where water-activated agents prove incompatible.
Powder leads on scale through established handling infrastructure; Granule shows steepest expansion trajectory as Saudi flatbread automation retrofits specify low-dust feed systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Gulf Standardization Organization harmonized standards and national enforcement gaps is redirecting anti-caking agent formulation investments toward jurisdictions with clearer additive registration pathways. Production facilities cluster where compliance costs predictably align with export market access.
Saudi Arabia
Saudi Food and Drug Authority disclosure mandates are accelerating phosphate-based agent procurement across the kingdom's processed dairy corridor. SFDA labeling protocols compress product development cycles for infant formula and milk powder exporters. Jeddah's Red Sea logistics hub concentrates spray-drying operations where humidity-responsive calcium silicate formulations dominate procurement specifications.
United Arab Emirates
MOHAP food additive controls and Dubai's re-export positioning attract multinational suppliers establishing GCC distribution headquarters. Halal certification convergence with GSO technical regulations simplifies formulation standardization across Emirati dairy and bakery operations. Dubai Industrial City clusters contract manufacturers serving Saudi and Kuwaiti markets from single production lines.
South Africa
Department of Health additive registration requirements and organic certification channel growth are fragmenting procurement between synthetic silicates and natural substitutes. National food safety framework evolution creates compliance timeline uncertainty for phosphate-based agents. Gauteng's seasoning blending corridor concentrates dry mix production for European diaspora export markets.
Nigeria
Emerging national food additive registry development and humid port logistics drive silicate-treated formulation demand among Lagos-based seasonings exporters. Pre-registration engagement opportunities attract technical advisory investment ahead of formal Nairobi-aligned standards adoption. Apapa port zone dry mix operations specify aggressive moisture absorption for container transit to European markets.
Egypt
Spray-drying optimization convergence with anti-caking formulation design creates bundled service demand in Egyptian milk powder operations. National standards alignment with Gulf harmonized categories simplifies phosphate agent registration for dairy exporters targeting GCC retail chains. Alexandria's dairy processing corridor concentrates high-temperature processing environments where precipitated silicate engineering reduces European import dependency.
Middle East and Africa Food Anti Caking Agents Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated food processors bypassing traditional distribution layers in favor of direct technical partnerships. The supplier base concentrates around three strategic archetypes: diversified chemical conglomerates with regional grain handling infrastructure, specialty silicate chemists with humidity-specific R&D capabilities, and ingredient blenders bundling anti-caking functionality with broader fortification portfolios. Competitive moves center on formulation support service integration and regional production hub establishment to compress freight exposure at Red Sea ports.
Within the diversified chemical tier, Cargill Incorporated and BASF SE exemplify multinational suppliers leveraging existing regional infrastructure to bundle anti-caking solutions with adjacent ingredient portfolios. Evonik Industries AG occupies a position among specialty precipitated silicate producers engineering for North African dairy processing temperatures. These three entities represent distinct competitive vectors: grain-handling-integrated distribution, synthetic silica chemistry R&D intensity, and high-temperature environment formulation specialization respectively.
| Leading Market Players |
|---|
| Cargill Incorporated |
| BASF SE |
| Evonik Industries AG |
| Tate & Lyle PLC |
| Solvay SA |
| Cabot Corporation |
| Agropur Ingredients |
| PPG Industries Inc. |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Tricalcium phosphate feedstock indices cascading from Moroccan phosphate rock benchmarks stratify procurement costs across three distinct pricing tiers for Middle East and Africa Food Anti Caking Agents Market buyers. Mineral fortification premiums compress margin buffers for Egyptian dairy blenders while silicate chemistry alternatives attract West African seasonings exporters facing humid logistics exposure.
Pricing Analysis
Distributor margin capture layers differentiate contract-based long-term offtake agreements from spot procurement in Lagos and Jeddah processing corridors. Three-tier pricing structure across premium, standard, and economy levels tracks halal certification grade and volume scale, with Saudi dairy cooperatives least price-sensitive given bundled technical service requirements. Cost compression in standard-grade phosphate agents intensifies because feedstock volatility transmits directly from OCP Group supply contracts. Nigerian chili powder exporters represent the most price-sensitive segment, prioritizing moisture absorption performance over mineral fortification label claims.
Supply Chain Analysis
Return flows of expired or moisture-compromised anti-caking treated powders remain minimal given food-grade disposal protocols, though Egyptian dairy operations increasingly audit supplier batch traceability for recall readiness. Manufacturing concentration centers on Germany, Belgium, and Saudi Arabia for synthetic silicate production, with phosphate agent synthesis anchored in Morocco and Tunisia. Raw material dependencies rest on phosphate rock concentrates, sodium carbonate, and precipitated silica feedstocks. Single-source vulnerability from Red Sea logistics chokepoints elevates freight cost exposure for European-imported agents. Distribution runs through integrated food manufacturer direct procurement channels bypassing traditional ingredient distributors in UAE and Saudi Arabia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by Gulf dairy processors shifting procurement specifications toward humidity-responsive calcium silicate formulations with dual mineral fortification credentials.
For Market Incumbents: Cement formulation support service bundling as the primary defensive perimeter against direct-to-processor digital channel encroachment. Expand captive supply of precipitated silicate feedstocks through backward integration into Tunisian or Egyptian mineral processing assets. Deepen technical advisory capacity for Red Sea coastal humidity calibration to neutralize talent scarcity premiums eroding service margins. For New Entrants and Emerging Players: Regional grain handling cooperatives represent the most accessible channel partner type for bypassing established distributor relationships. Target Kenya's emerging additive registry development ahead of formal Nairobi standards adoption, where early technical engagement shapes maximum inclusion rate specifications. Penetrate Nigerian seasonings export operations through Apapa port zone direct sales teams offering container transit moisture survival guarantees. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty precipitated silicate chemists possessing North African dairy processing temperature engineering capabilities. Long-term viability over the projection horizon favors acquisition targets with localized R&D infrastructure and existing Gulf Standardization Organization registration portfolios. Monitor divergence between SFDA enforcement timelines and Nigerian national registry development pace as inflection indicator for regional formulation standardization versus fragmentation outcomes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Feedstock | Moroccan rock concentrate sourcing secures margin buffers against OCP Group pricing volatility for Egyptian blenders. |
| Regional R&D Localization | Tunisian precipitated silicate engineering reduces European import dependency for North African dairy spray-drying operations. |
| Direct-to-Processor Digital Channel Launch | B2B platform procurement collapses distributor margin layers in UAE food manufacturing zones. |
| Halal Certification Convergence Investment | Unified GSO technical regulation compliance simplifies SKU consolidation across Saudi, UAE, and Kuwaiti markets. |
| Technical Advisory Service Expansion | Humidity-specific formulation support commands premium positioning against commodity anti-caking agent suppliers. |
Research Methodology
Coverage spans the Gulf Cooperation Council, North Africa, and West Africa, with primary inputs from each region combined with secondary validation. Primary interviews engaged food ingredient procurement managers at Saudi dairy cooperatives, Egyptian spray-drying operations technical directors, Nigerian seasonings export executives, and UAE-based contract manufacturing plant managers. Secondary sources incorporated Gulf Standardization Organization technical regulations, Saudi Food and Drug Authority additive disclosure mandates, South African Department of Health registration guidelines, customs trade data for phosphate and silicate imports, and SEC filings from diversified chemical conglomerates with regional grain handling infrastructure. Bottom-up demand modeling triangulated against top-down market sizing from production capacity assessments.
Rate-of-change decomposition separated volume growth from price mix effects across the analysis window. Segmentation dimensions modeled include product type chemistry, application processing temperature requirements, end-user integration level, and regional regulatory cluster alignment. CAGRs derived from fitted growth curves applied to baseline consumption estimates, cross-referenced against dairy processing capacity expansion announcements and West African dry mix export volume trajectories. Industry-specific forecast inputs incorporated Red Sea humidity exposure coefficients and halal certification protocol evolution timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Nigerian national additive registry development pace and potential phosphate raw material export restriction policies. Forecasts reflect documented assumptions regarding GSO-SFDA regulatory convergence continuity and Red Sea logistics corridor stability. Practitioners should monitor Kenya independent standards adoption triggers and South African organic certification channel growth rates for early signals of natural substitute displacement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Acetylated Distarch Adipate Market
Food Additives and Ingredients
Nisin for Food Market
Food Additives and Ingredients
Africa Food Additives Market
Food Additives and Ingredients
Nanoencapsulated Food Additives Market
Food Additives and Ingredients
Global Natamycin Market
Food Additives and Ingredients
Hydrocolloid Carrier Market
Food Additives and Ingredients
Starch-Based Texturizing Agents Market
Food Additives and Ingredients
Food Texturing Agents Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Gardenia Food Color Market
Food Additives and Ingredients
Germany Food Enzymes Market