
 Chicken Fat Market | 2026-2036
Chicken Fat Market Size, Share, and Industry Trends Forecast 2026-2036
Chicken Fat Market Analysis
Multi-source procurement toward vertically integrated rendering networks is realigning supply security for downstream fat buyers. Darling Ingredients Inc. leverages captive rendering capacity across North American poultry belts to secure volume commitments. Tyson Foods, Inc. anchors its position through in-house rendering tied to plant-level slaughter volumes. JBS S.A. dominates Brazilian supply, extending backward integration into fat collection from its own processing footprint.
Chicken fat comprises triglycerides extracted from poultry adipose tissue through wet or dry rendering at temperatures between 60°C and 120°C, yielding a yellow lipid with melting points near 20°C to 35°C used across food formulation, oleochemical feedstocks, and energy applications. Rendered fat leads product type volumes due to its cost efficiency in industrial frying and pet food palatant systems, while fat blends capture expanding margin pools as formulators seek customized fatty acid profiles. Biofuels application growth outpaces food industry expansion where renewable diesel mandates in multiple jurisdictions pull tallow-grade lipids into hydrotreatment pathways.
EPA biosolids and rendering effluent rules shape US processor compliance costs, while REACH and ECHA classifications govern EU oleochemical market access for imported fats. FDA food-contact and FSMA traceability requirements filter which rendering outputs qualify for human-grade versus feed-grade channels. Stakeholders must monitor evolving renewable fuel standard pathways and rendering carbon intensity scoring as these frameworks determine which fat streams command premium offtake versus commodity pricing.
Market Dynamics
Renewable diesel mandates in California, Oregon, and British Columbia are pulling tallow-grade lipids into hydrotreatment pathways, restructuring offtake priorities for poultry fat renderers who previously served food and feed channels exclusively.
Growth Catalysts
- EU Green Deal carbon intensity scoring:Renderers achieving low-carbon certification access premium biofuel offtake contracts that bypass commodity pricing tiers.
- Pet food premiumization:Palatant specification upgrades in North American and European premium kibble formulations drive demand for rendered fat with controlled fatty acid profiles.
- Brazilian integrated processing:JBS S.A. and BRF S.A. anchor supply security through captive rendering networks tied to plant-level slaughter volumes.
Market Restraints
- Feedstock cost volatility:Poultry slaughter volumes fluctuate with avian influenza cycles and seasonal processing schedules, compressing renderer margins during supply contractions.
- Supply concentration risk:Brazilian production clusters around São Paulo and Paraná states, exposing buyers to localized logistics disruptions and port congestion.
- Regulatory friction:REACH and ECHA substance classifications impose documentation burdens on EU oleochemical importers that commodity traders struggle to satisfy.
Strategic Opportunities
- Underpenetrated Southeast Asian feed markets:Vietnamese and Indonesian aquaculture operations seek cost-effective lipid sources as fishmeal prices escalate.
- Renewable diesel tax credits:US Inflation Reduction Act clean fuel production credits reward renderers who verify lifecycle carbon intensity below 50g CO2e/MJ.
- Enzymatic interesterification:Convergence of lipase biocatalysis with continuous processing enables custom fat blend production at smaller scale than chemical interesterification permits.
Industry Challenges
- FSMA traceability compliance:FDA food safety modernization rules require lot-level tracking from renderer to end-use, forcing IT system upgrades across mid-tier processors.
- Capex intensity for carbon capture:EU F-Gas Regulation and national climate targets pressure renderers to install thermal oxidizer upgrades and biogas recovery infrastructure.
- Specialized technician scarcity:Wet rendering operations require operators trained in high-temperature lipid chemistry and effluent management, a skill set concentrated among aging workforces in traditional rendering belts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chicken Fat Market |
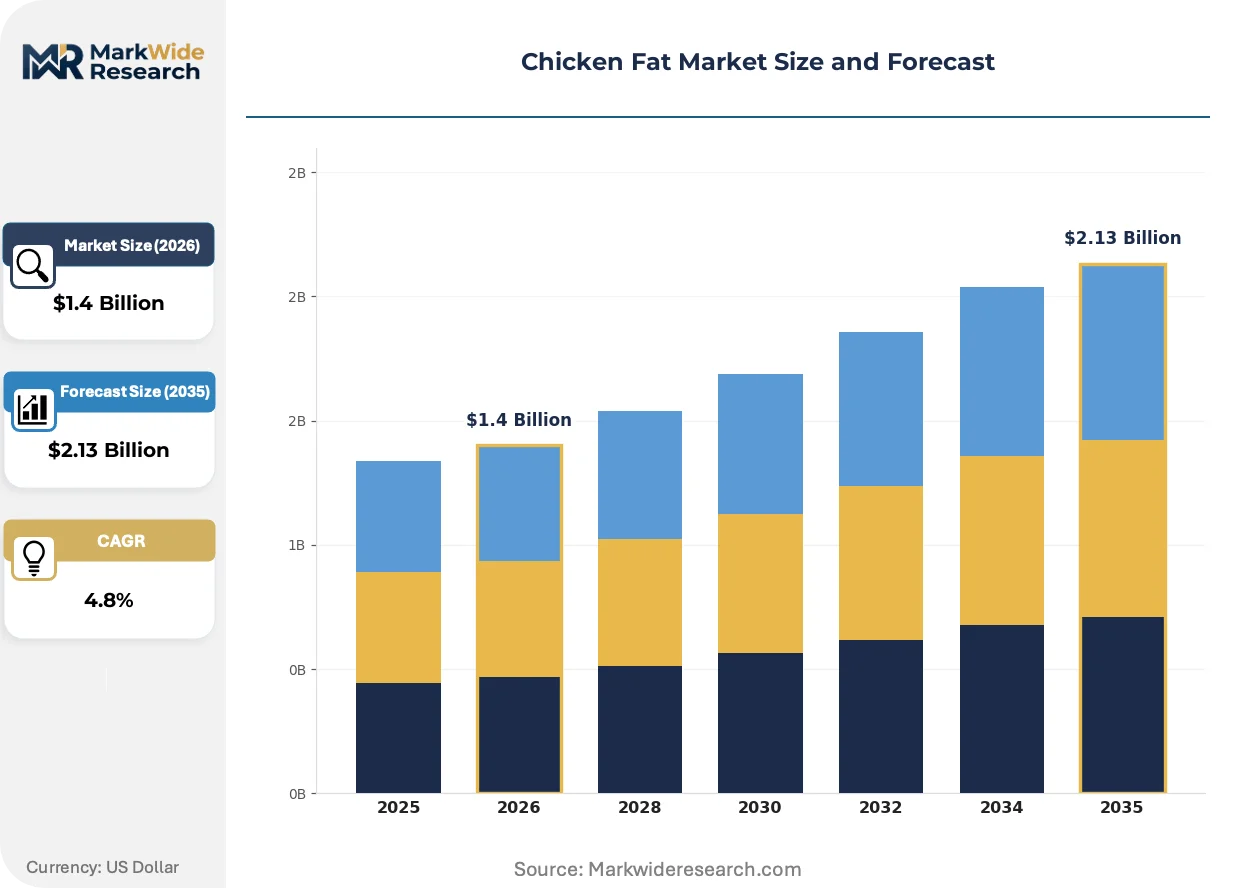
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rendered Fat, Pure Fat, Chicken Tallow, Fat Blends Application: Food Industry, Pet Food, Biofuels, Cosmetics Packaging Type: Bulk Containers, Sachets, Cans, Tubs End User: Food Manufacturers, Restaurants, Home Cooks, Pet Suppliers |
| Companies Covered | Essex Food Ingredients, H. J. Baker & Bro., LLC, STARA FOODS B.V., Valley Proteins, Inc., JBS S.A., Piermen B.V., Darling Ingredients Inc., Sanimax, Tyson Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chicken Fat Market Emerging Trajectories
Processing technology and regulatory carbon accounting are converging to reward renderers who can document supply chain provenance and emissions intensity, while buyer procurement models favor long-term volume commitments over spot-market flexibility.
Enzymatic rendering using lipase biocatalysts operates at lower temperatures than thermal wet rendering, preserving heat-sensitive fatty acids for high-value oleochemical applications. Specialty chemical formulators in Germany and the Netherlands are adopting these processes to meet ECHA sustainability disclosure requirements under CSRD scope 3 rules. The technology is expanding into mid-scale rendering operations that previously lacked capital for continuous thermal systems.
California's Low Carbon Fuel Standard and Oregon's Clean Fuels Program now assign carbon intensity scores to individual fat streams based on rendering energy inputs and transportation distances. Renderers with access to renewable natural gas or solar-powered facilities achieve sub-40g CI scores that command price premiums in West Coast renewable diesel offtake. This regulatory framework most affects integrated processors with plant-level energy control, disadvantaging merchant renderers dependent on grid electricity.
Long-term offtake agreements with renewable diesel producers are displacing traditional commodity trading relationships for tallow-grade poultry fats. Integrated oil companies in Texas and Louisiana now contract directly with renderers for five-to-ten year supply commitments, bypassing historical merchant broker networks. This pattern is most visible in the US Gulf Coast corridor, where hydrotreatment capacity expansions outpace domestic tallow and poultry fat supply growth.
Chicken Fat Market Segmentation
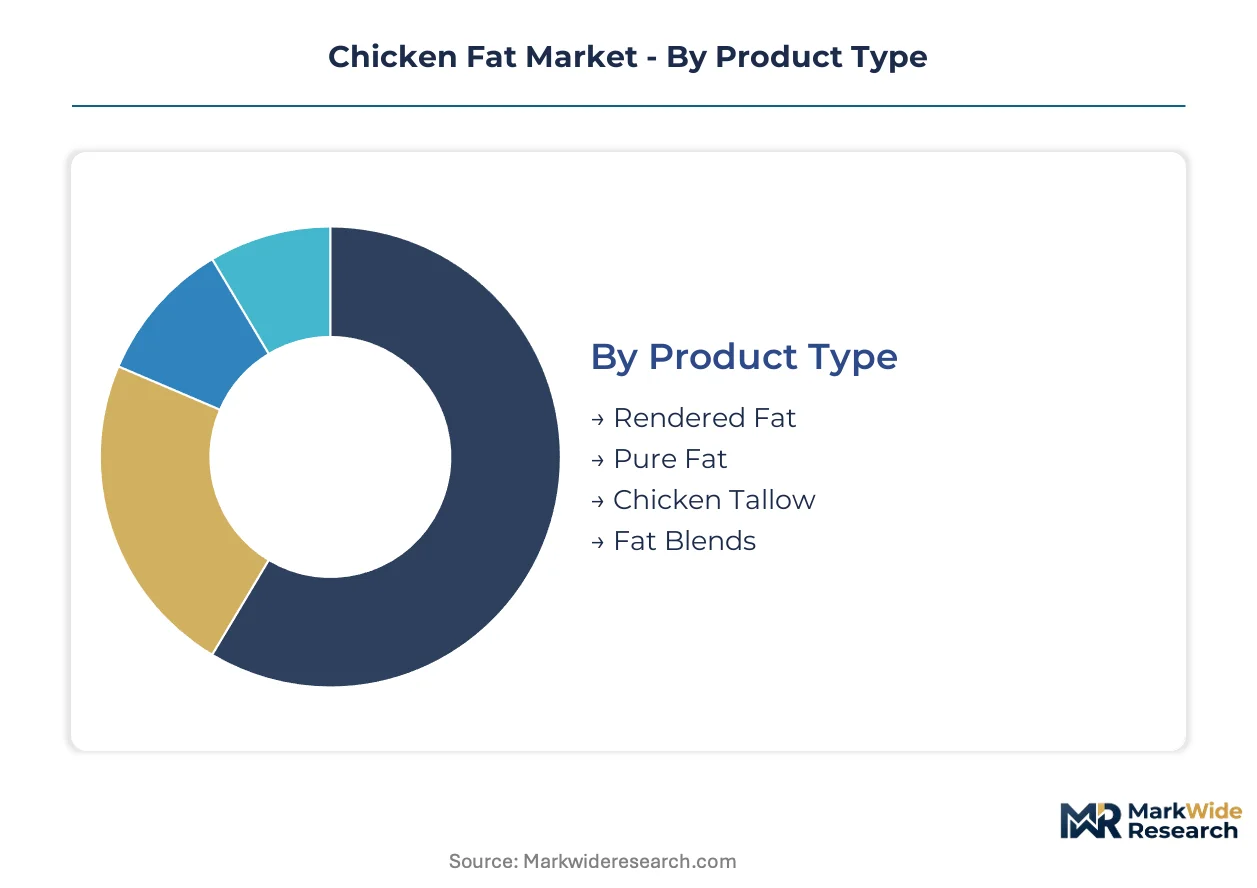
Chicken fat segmentation reveals how specification tiers map to divergent margin pools across food-grade, feed-grade, and fuel-grade channels. Buyers sort procurement by fatty acid profile requirements, carbon intensity scoring eligibility, and traceability documentation depth.
Product Type:
Temperature control during extraction and post-render processing separates commodity streams from specialty grades capable of biofuel offtake or cosmetic certification.
- Rendered Fat:Wet or dry thermal extraction at 60°C to 120°C yields a yellow lipid with melting points between 20°C and 35°C. Industrial frying and pet food palatant systems in North America and Europe absorb volume, though California LCFS carbon intensity scoring now pulls supply into renewable diesel channels when documentation permits.
- Fat Blends:Custom fatty acid profiles achieved through enzymatic or chemical interesterification command expanding margin pools. German and Dutch specialty chemical formulators specify these for ECHA sustainability disclosure compliance under CSRD scope 3 rules.
- Pure Fat:Refined triglyceride streams meeting FDA food-contact specifications serve human-grade formulation with lot-level FSMA traceability.
- Chicken Tallow:Higher melting point fraction separated through controlled cooling finds oleochemical feedstock applications.
Mature deployment sits with Rendered Fat. Newer deployment is concentrated in Fat Blends.
Application:
End-use channel selection determines regulatory pathway eligibility and pricing tier access for renderer output streams.
- Pet Food:Palatant specification upgrades in premium kibble formulations drive specification for rendered fat with controlled fatty acid profiles. North American and European buyers now require documentation of rendering energy inputs to satisfy scope 3 disclosure demands.
- Biofuels:Hydrotreatment pathways in Texas and Louisiana pull tallow-grade lipids into renewable diesel production. US Inflation Reduction Act clean fuel production credits reward verified lifecycle carbon intensity below 50g CO2e/MJ.
- Food Industry:Industrial frying and baking applications prioritize cost efficiency over fatty acid customization.
- Cosmetics:Refined grades meeting REACH registration requirements serve emollient applications in EU personal care formulation.
Volume concentration remains in Pet Food. Steepest expansion trajectory belongs to Biofuels.
Packaging Type:
Logistics configuration aligns with buyer scale and shelf-life requirements across industrial, foodservice, and retail channels.
- Bulk Containers:Tanker and tote delivery dominates renewable diesel offtake contracts requiring five-to-ten year volume commitments from integrated oil companies.
- Tubs:Retail-format packaging serves home cook and small restaurant segments with shorter rotation cycles.
- Sachets:Portion-controlled units target foodservice sampling and specialty pet food trial formats.
- Cans:Traditional retail preservation format maintains position in conventional grocery distribution.
Industrial procurement concentrates in Bulk Containers. Emerging format development centers on Sachets.
End User:
Buyer sophistication tiers separate commodity spot purchasers from strategic partners capable of long-term offtake agreements.
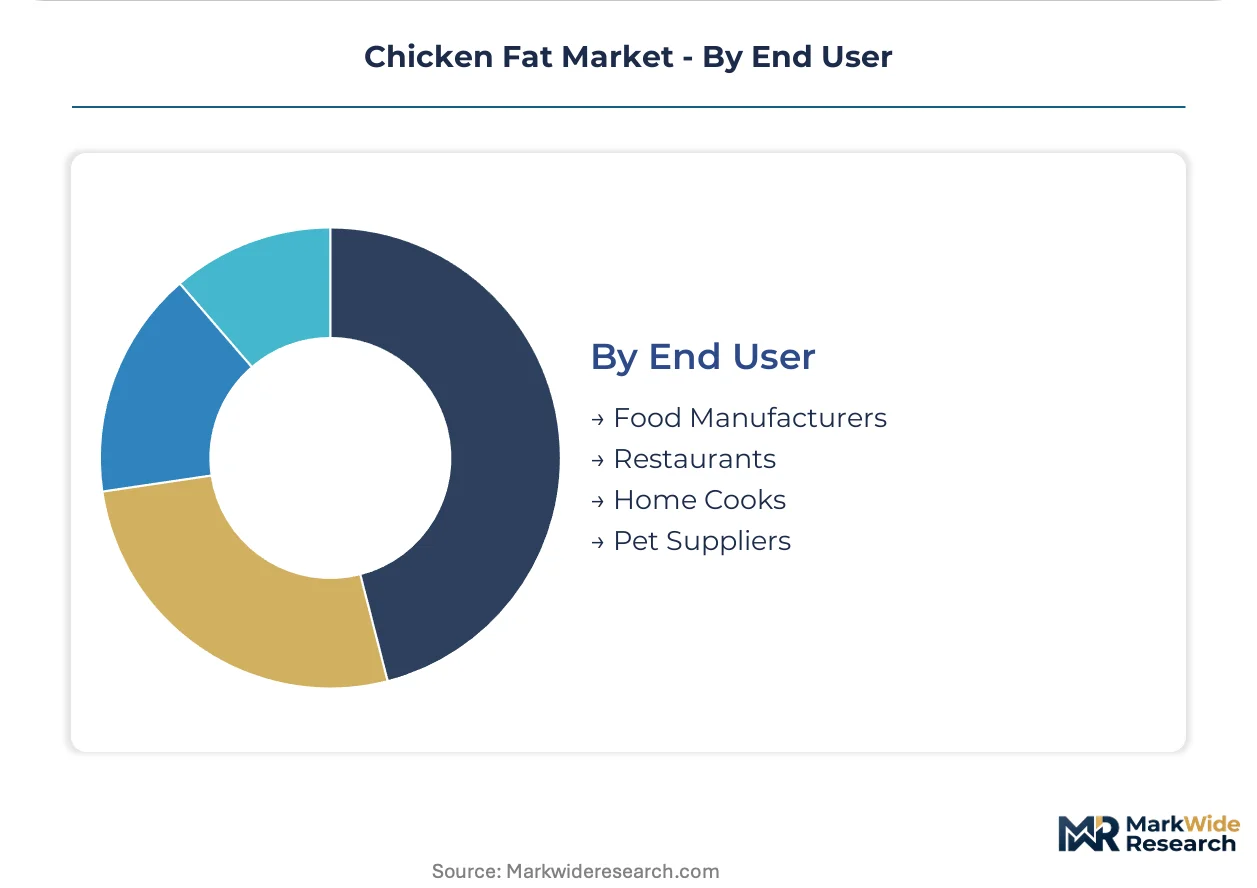
- Food Manufacturers:Large-scale frying and baking operations negotiate annual contracts with integrated processors possessing captive rendering capacity.
- Pet Suppliers:Premium kibble formulators specify fatty acid profiles and carbon intensity documentation to meet retailer sustainability requirements.
- Restaurants:Foodservice operators prioritize price stability over specification customization in procurement decisions.
- Home Cooks:Retail channel buyers respond to packaging convenience and shelf stability claims.
Contract depth is greatest with Food Manufacturers. Procurement flexibility is highest among Home Cooks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poultry slaughter belts in Brazil, the United States, and Germany anchor feedstock availability for rendering operations. National regulatory frameworks and biofuel mandates reshape where processed fat commands premium offtake versus commodity pricing.
Brazil
JBS S.A. and BRF S.A. operate captive rendering networks tied to São Paulo and Paraná slaughter complexes. ANVISA feed-grade certification requirements govern export eligibility to Southeast Asian aquaculture markets. Port congestion at Santos periodically disrupts bulk container shipments to European oleochemical buyers.
United States
Integrated processors in the Southeast and Midwest leverage plant-level rendering capacity to secure renewable diesel offtake contracts. EPA biosolids rules and California LCFS carbon intensity scoring filter which fat streams qualify for biofuel premiums. Darling Ingredients and Tyson Foods anchor supply security through backward integration into poultry processing footprints.
Germany
Specialty chemical formulators in the Cologne-Ruhr cluster specify enzymatically processed fat blends for ECHA sustainability disclosure compliance. REACH substance classifications impose documentation burdens on imported rendered fat that commodity traders struggle to satisfy. CSRD scope 3 rules drive demand for lot-level traceability from renderer to end-use.
Netherlands
Rotterdam serves as the primary EU entry point for Brazilian poultry fat destined for oleochemical and biofuel channels. ECHA classifications and EU Green Deal carbon intensity benchmarks determine which import batches access premium pricing tiers. Dutch specialty chemical firms specify custom fatty acid profiles for personal care emollient applications.
Canada
British Columbia's Clean Fuels Program assigns carbon intensity scores to individual fat streams based on rendering energy inputs and transportation distances. Health Canada and PMRA regulations govern feed-grade channel eligibility for domestic pet food manufacturers. Prairie poultry processing clusters supply renderers serving West Coast renewable diesel producers.
Chicken Fat Market Vendor Landscape
Global majors compete with regional champions across rendering capacity and biofuel offtake contracting. The vendor base separates into integrated processors with captive slaughter supply, merchant renderers dependent on third-party feedstock, and specialty blenders serving cosmetic and pharmaceutical channels. Two dominant competitive moves are reshaping positioning: long-term offtake agreements with renewable diesel producers displacing spot-market relationships, and enzymatic processing technology licensing to access ECHA-compliant sustainability tiers.
Within the integrated processor archetype, JBS S.A. and Tyson Foods, Inc. exemplify backward integration strategies that secure volume commitments from biofuel producers. Darling Ingredients Inc. occupies a position spanning both merchant rendering and specialty blend production. These three entities represent contrasting approaches to carbon intensity documentation and regulatory compliance across multiple jurisdictions.
| Leading Market Players |
|---|
| Essex Food Ingredients |
| H. J. Baker & Bro., LLC |
| STARA FOODS B.V. |
| Valley Proteins, Inc. |
| JBS S.A. |
| Piermen B.V. |
| Darling Ingredients Inc. |
| Sanimax |
| Tyson Foods, Inc. |
| Others |
Supply Flow & Price Mechanics
Poultry slaughter volume indices in Brazil and the United States cascade through rendering economics into three-tier pricing structures across premium, standard, and economy levels. California LCFS carbon intensity scoring and EU ECHA sustainability disclosure requirements stratify fat streams into premium biofuel offtake versus commodity feed-grade channels.
Pricing Analysis
Service bundling separates carbon-certified fat streams with verified lifecycle documentation from unbundled commodity grades lacking traceability infrastructure. Long-term offtake contracts with renewable diesel producers command price premiums over spot-market transactions, while pet food manufacturers exhibit highest price sensitivity due to formulation cost constraints. Price differentiation hinges on certification tier and volume scale. Cost compression in standard-grade rendered fat intensifies because merchant renderers lack captive energy assets to achieve sub-40g CI scores.
Supply Chain Analysis
Direct-to-biofuel-producer channels handle integrated processor volumes, bypassing historical merchant broker networks. Feedstock supply concentrates in Brazil, the United States, and Germany, drawing from poultry adipose tissue, slaughterhouse trimmings, and rendering plant effluent streams. Supply chain risk centers on single-source vulnerability in São Paulo and Paraná states, where port congestion at Santos periodically disrupts bulk container shipments to European oleochemical buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as California LCFS and EU Green Deal carbon intensity scoring force merchant renderers without documentation infrastructure toward acquisition or exit.
For Market Incumbents: Anchor supply security through backward integration into captive rendering capacity tied to plant-level slaughter volumes. Invest in thermal oxidizer upgrades and biogas recovery infrastructure to achieve sub-40g CI scores that access premium renewable diesel offtake. Defend against integrated oil company long-term contracting by locking five-to-ten year volume commitments before hydrotreatment capacity expansions outpace domestic fat supply. For New Entrants and Emerging Players: Specialty chemical distributors in Germany and the Netherlands represent the most accessible channel partners for enzymatic fat blend production at smaller scale. Target Vietnamese and Indonesian aquaculture operations seeking cost-effective lipid sources as fishmeal prices escalate. Pursue white-space in ECHA-compliant custom fatty acid profiles for personal care emollient applications. For Investors and Strategic Acquirers: Distressed-cycle entries favor merchant renderers with stranded thermal assets in the US Southeast and Midwest. Long-term viability hinges on carbon intensity documentation capability and renewable natural gas access. Watch for inflection when California LCFS credit prices compress margins for grid-dependent renderers unable to achieve sub-50g CO2e/MJ lifecycle scores.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Rendering | JBS S.A. and Tyson Foods secure volume commitments through plant-level slaughter control. |
| Carbon Intensity Certification Program | Renderers achieving EU Green Deal benchmarks access premium biofuel offtake contracts. |
| Enzymatic Processing Technology Licensing | German specialty chemical formulators adopt lipase biocatalysis for ECHA CSRD compliance. |
| Long-term Supply Agreement with Renewable Diesel Producers | Integrated oil companies in Texas and Louisiana contract directly for five-to-ten year commitments. |
| Geographic Expansion into Southeast Asian Feed Markets | Vietnamese aquaculture operations seek alternative lipid sources amid fishmeal price escalation. |
Methodological Framework
Document review covered customs and trade data, SEC filings, EPA biosolids compliance records, and ECHA substance classifications, complemented by interviews with rendering plant managers, pet food procurement leads, renewable diesel offtake specialists, and specialty chemical formulators. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Cross-referencing historical slaughter volume patterns with expert panel input on regulatory trajectory shaped the analytical framework. Segmentation dimensions included product type, application channel, packaging format, and carbon intensity tier. CAGRs were derived from trend extrapolation adjusted for policy-driven demand shifts in biofuel mandates and pet food premiumization.
Several conditions sit outside the modeled scope, including avian influenza severity cycles, port congestion duration at Santos, and LCFS credit price volatility. Forecasts reflect assumptions about regulatory stability and rendering technology adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Organic Lamb Market
Meat Products
Chicken Buckets Market
Meat Products
Middle East Poultry Meat Market
Meat Products
South Africa Processed Meat Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
Beef Tallow Market
Meat Products
Emulsified Meat Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
Global Beef Market
Meat Products
Beef Bouillon Market
Meat Products
North America Red Meat Market
Meat Products
Brazil Meat Products Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Beef Bone Broth Market
Meat Products
Global Edible Meat Market
Meat Products
Saudi Arabia Goat Meat and Cheese Market