
 Global Sterols Market | 2026-2036
Global Sterols Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sterols Market Foresight
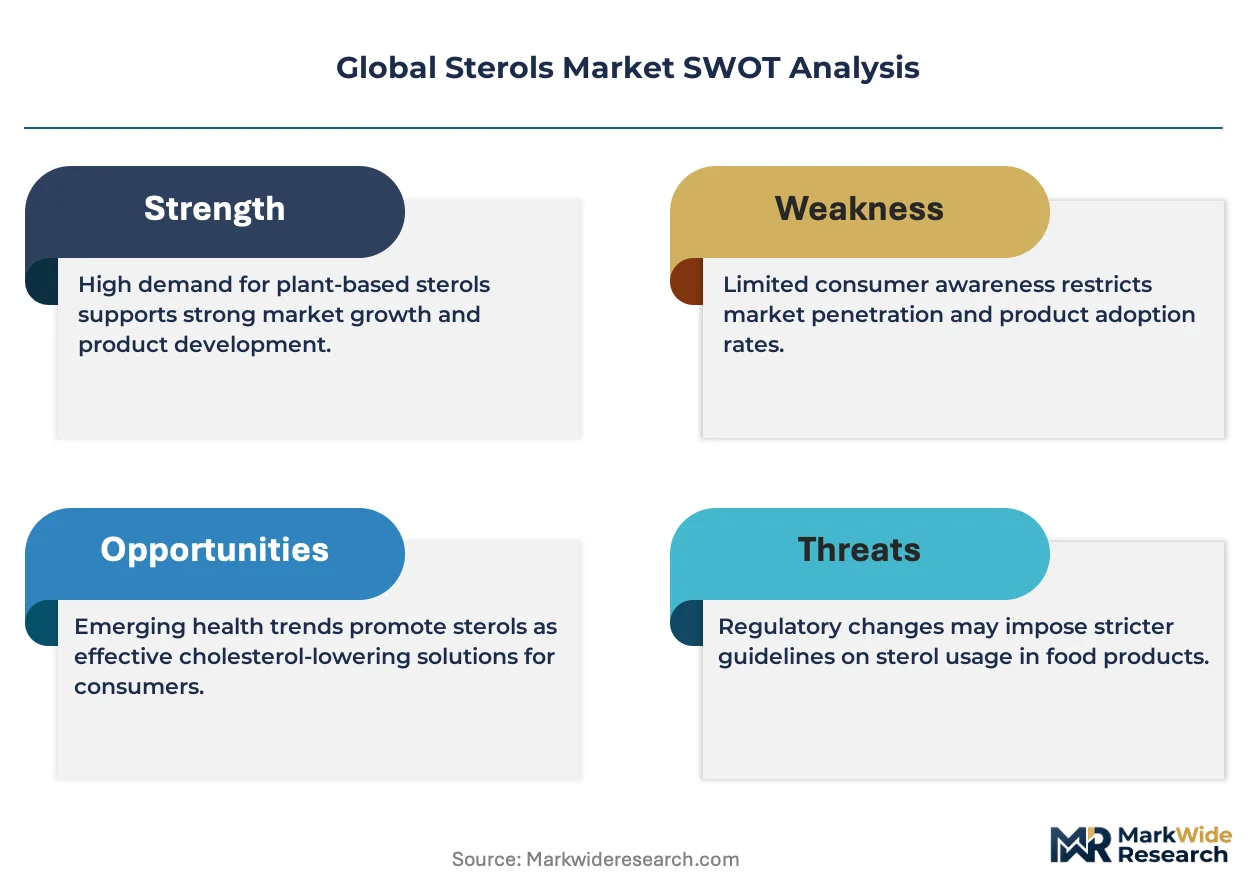
Pharmaceutical-grade sterol specifications is reorganizing competitive dynamics across the supply base. BASF SE leverages its integrated biotechnology platform to sustain high-purity output for drug applications. Cargill, Incorporated anchors North American supply through backward integration into vegetable oil refining. Arboris specializes in pine-derived sterol extraction, occupying a defensible niche in European sourcing.
Sterols comprise a class of steroid alcohols structurally characterized by a tetracyclic cyclopentanoperhydrophenanthrene backbone with an eight-to-ten carbon side chain and a hydroxyl group at the C-3 position, typically isolated from vegetable oils via solvent extraction or crystallization processes for use as cholesterol-lowering agents and emulsion stabilizers. Beta-sitosterol dominates volume flows due to its abundance in soybean and corn feedstocks, while campesterol commands premium positioning in pharmaceutical formulations requiring tighter purity bands. Functional foods represents the fastest-expanding application segment as CPG manufacturers reformulate portfolios around heart-health positioning.
FDA dietary supplement regulations, EFSA health claim protocols, and FSSAI functional food standards collectively elevate barrier costs for new sterol suppliers seeking multi-regional market access. REACH compliance in Europe and evolving EPA biosafety assessments for novel extraction methods further complicate qualification timelines. Stakeholders must monitor regulatory divergence between jurisdictions to optimize formulation investments and avoid stranded product registrations.
Market Dynamics
Pharmaceutical-grade purity specifications are bifurcating the sterols supply base into drug-validated and food-grade tiers, forcing capital reallocation toward GMP-certified extraction infrastructure.
Growth Catalysts
- FDA Dietary Supplement Labeling Requirements:Updated qualification pathways for heart-health claims are accelerating sterol incorporation into fortified foods and nutraceuticals across US retail channels.
- Functional Food Manufacturers:CPG reformulation around cholesterol management positioning is driving bulk procurement contracts for plant-derived sterol esters.
- Solvent Extraction Advancement:Supercritical CO2 methods are improving beta-sitosterol yield rates from corn and soybean feedstocks, tightening cost structures for high-volume suppliers.
Market Restraints
- Vegetable Oil Feedstock Volatility:Soybean and corn oil price swings transmit directly to sterol production economics, compressing margin predictability for non-integrated processors.
- REACH Compliance Burden:European chemical registration protocols impose multi-year timelines and six-figure documentation costs on novel extraction method entrants.
- Synthetic Cholesterol Substitutes:Biotechnologically produced cholesterol analogs for pharmaceutical applications threaten displacement of natural sterol sources in select drug formulations.
Strategic Opportunities
- India Functional Food Standards:FSSAI health claim protocols are opening formal pathways for sterol-fortified edible oils in a market with rising cardiovascular disease prevalence.
- Pine-Derived Sterol Niche:Tall oil feedstock extraction from European and North American pulp mills offers defensible sourcing outside commodity oilseed channels.
- EPA Biosafety Assessment Alignment:Streamlined approval frameworks for enzymatic extraction methods are reducing qualification friction for US-based biotech entrants.
Industry Challenges
- Analytical Chemist Scarcity:Sterol stereochemistry verification and impurity profiling require specialized chromatography expertise that outpaces current training pipeline output.
- GMP Facility Capex Requirements:Pharmaceutical-grade sterol production demands cleanroom infrastructure and validated quality systems that strain mid-capitalization processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sterols Market |
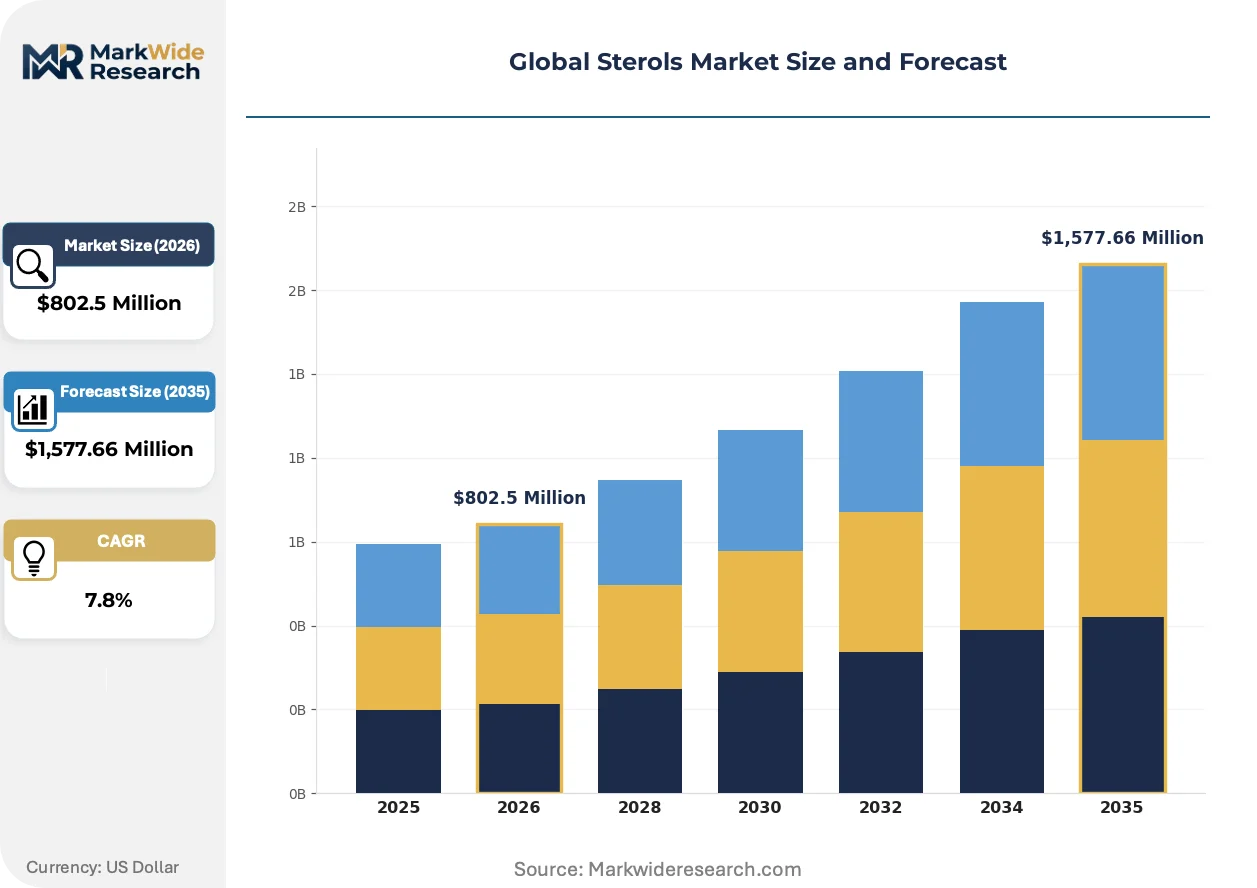
| Market Size in 2026 | $802.5 Million |
| Market Size in 2035 | $1,577.66 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta-Sitosterol, Campesterol, Stigmasterol, Brassicasterol Application: Dietary Supplements, Pharmaceuticals, Cosmetics, Functional Foods, Animal Nutrition Source: Vegetable Oils, Soybean, Corn, Pine Tree, Others End User: Food & Beverage Manufacturers, Pharmaceutical Companies, Personal Care Producers, Feed Manufacturers |
| Companies Covered | BASF SE, Cargill, Incorporated, Archer Daniels Midland Company, DuPont de Nemours, Inc., The Lubrizol Corporation, Arboris, Raisio Oyj, Bunge Limited, Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sterols Market Shifts & Advancements
Extraction technology convergence with synthetic biology is dissolving traditional boundaries between natural sourcing and biomanufacturing, while regulatory fragmentation between jurisdictions is forcing multi-track qualification strategies.
Supercritical CO2 extraction is decomposing the historical dominance of hexane-based solvent methods in vegetable oil sterol recovery. European and North American processors are adopting these systems to meet residual solvent limits in pharmaceutical applications. The shift is compressing equipment supplier margins while elevating capital barriers for new market entrants.
EFSA health claim protocols are tightening evidentiary standards for cholesterol reduction claims on sterol-fortified products. Manufacturers must now submit human intervention studies rather than relying on compositional equivalence. Functional food brands targeting European retail are reformulating around validated dosage thresholds or withdrawing heart-health positioning entirely.
CPG procurement teams are consolidating supplier relationships around vertically integrated vegetable oil refiners capable of certifying sterol provenance from crop to finished ingredient. Long-term offtake agreements with volume commitments are displacing spot market purchasing for major functional food brands. This concentration is most visible in US Midwest manufacturing corridors where soybean processing clusters enable integrated supply chains.
Global Sterols Market Segmentation
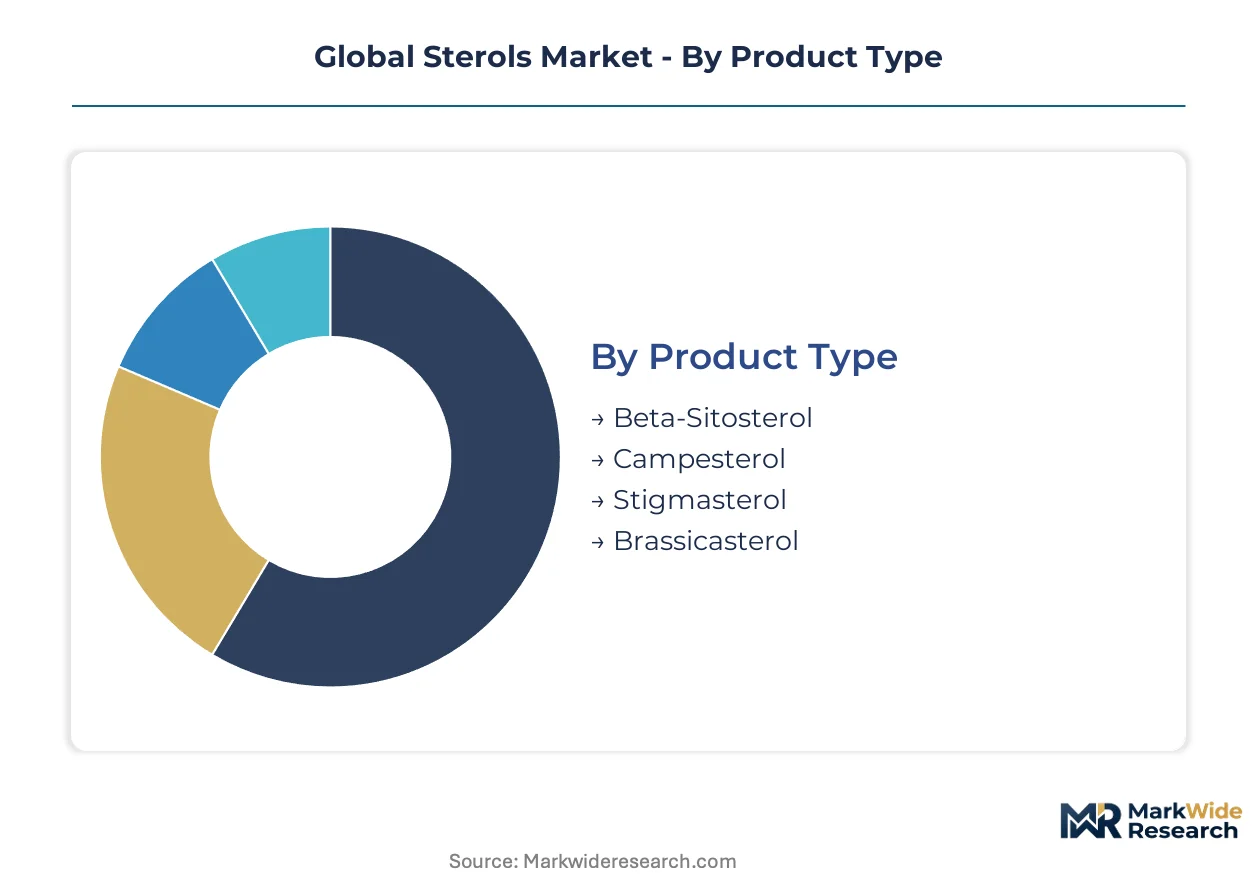
Sterol suppliers configure product portfolios around divergent purity specifications and regional regulatory pathways. Segmentation reveals where commodity scale competes against pharmaceutical-grade premiums.
Product Type:
Domestic consumption dominates beta-sitosterol and campesterol volumes in North American and European markets, while stigmasterol and brassicasterol flow disproportionately toward export-oriented pharmaceutical manufacturers in Asia-Pacific.
- Beta-Sitosterol:The most abundant plant sterol structurally characterized by a 24-ethyl substituent on the steroid backbone. Demand concentrates in US Midwest functional food corridors where CPG manufacturers procure bulk quantities for cholesterol-lowering positioned products.
- Campesterol:A 24-methyl sterol isomer requiring tighter purity bands for drug applications. Pharmaceutical compounders in Germany and Switzerland drive premium procurement for cardiovascular therapeutic formulations.
- Stigmasterol:A C-22 desaturated analog serving as a key intermediate for semi-synthetic hormone production. Indian and Chinese API manufacturers represent the primary export destination.
- Brassicasterol:A C-28 sterol distinctive to rapeseed and mustard oil feedstocks. European tall oil refiners capture this niche for specialized cosmetic emollient applications.
Beta-sitosterol holds the largest share; momentum sits with campesterol as pharmaceutical purity requirements tighten.
Application:
Cost tiers separate commodity-grade animal nutrition from pharmaceutical and cosmetic segments commanding fivefold price multiples for identical base molecules.
- Functional Foods:The steepest expansion trajectory as CPG brands reformulate around FDA-permitted heart-health claims. US retail channels now stock over 150 sterol-fortified SKU variants across spreads, yogurts, and beverages.
- Pharmaceuticals:Cholesterol management therapies and prodrug synthesis drive specification intensity. EMA validation requirements filter supplier pools to GMP-certified European and North American processors.
- Dietary Supplements:Softgel and tablet formulations targeting lipid profile optimization. Amazon and direct-to-consumer channels are displacing traditional pharmacy distribution for this segment.
- Cosmetics:Emulsion stabilizers and anti-inflammatory actives in dermocosmetic lines. South Korean and French formulators lead incorporation rates.
- Animal Nutrition:Feed additives for poultry and swine growth promotion. This segment operates on thin margins with procurement consolidated among integrated oilseed crushers.
Functional foods command the fastest volume gains; pharmaceuticals retain the highest value concentration per kilogram.
Source:
Volume scale concentrates in row-crop feedstocks while pine-derived extraction offers defensible margin protection against commodity oilseed volatility.
- Vegetable Oils:Refined soybean and corn oil distillates constitute the dominant commercial pathway. US and Brazilian crushers leverage backward integration to capture sterol streams from existing refining infrastructure.
- Soybean:Dedicated sterol concentration from deodorizer distillate fractions. Argentine processors export bulk volumes to European compounders under long-term offtake structures.
- Corn:Ethanol co-product recovery yields competitive cost positioning. Iowa and Illinois processing clusters anchor North American supply.
- Pine Tree:Tall oil pitch extraction from kraft pulp mills sidesteps oilseed price transmission. Finnish and Swedish suppliers dominate this feedstock category.
- Others:Rice bran, wheat germ, and algae-derived sterols occupying emerging niche positions.
Vegetable oils aggregate the largest volume; pine-derived sourcing gains favor among margin-defensive European suppliers.
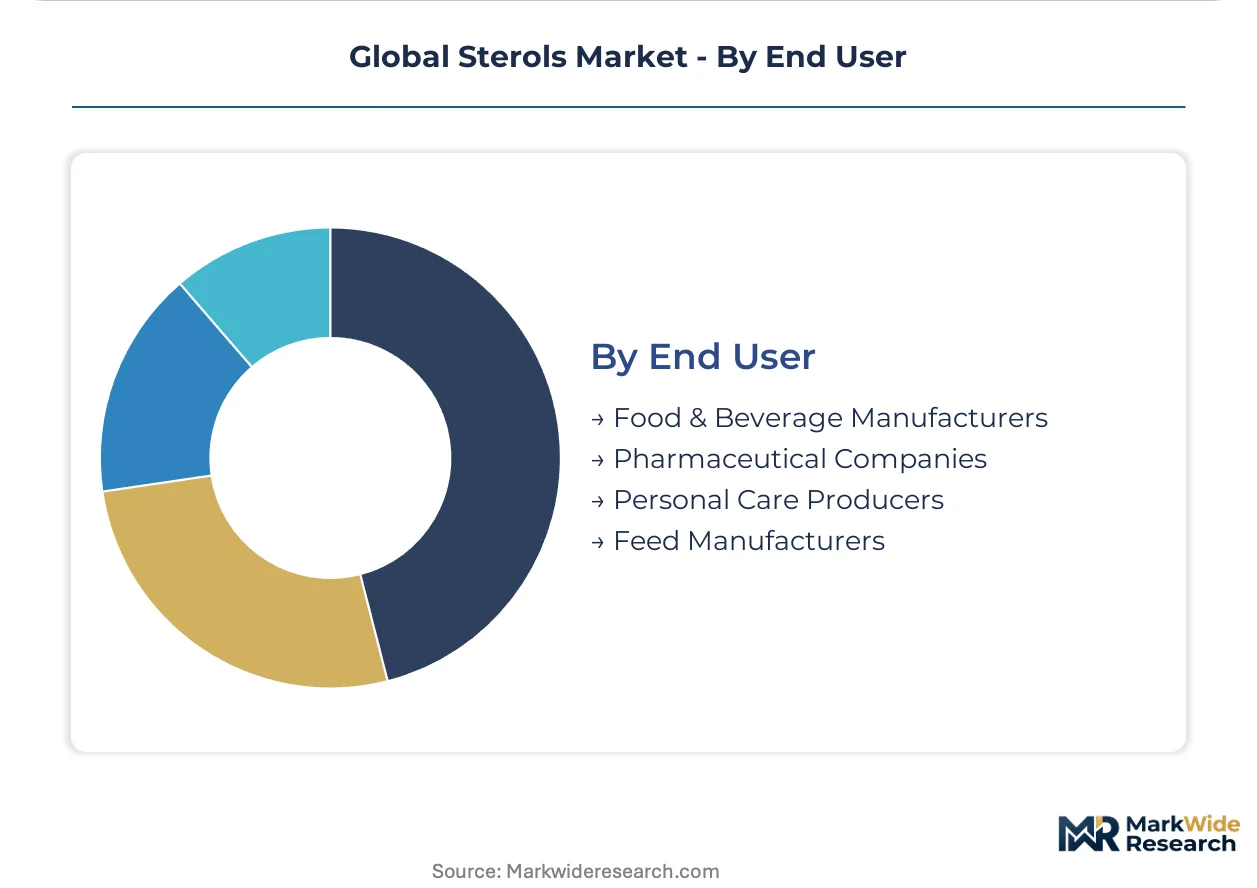
End User:
Customer type determines specification stringency, with pharmaceutical companies imposing analytical protocols that food manufacturers rarely replicate.
- Food & Beverage Manufacturers:CPG procurement teams consolidate supplier relationships around vertically integrated refiners capable of certifying sterol provenance from crop to finished ingredient.
- Pharmaceutical Companies:Drug-validated sterol requirements bifurcate supply tiers, forcing capital allocation toward cleanroom infrastructure and validated quality systems.
- Personal Care Producers:Cosmetic formulators prioritize odor profile and color specification over purity metrics, opening supply to broader processor pools.
- Feed Manufacturers:Animal nutrition buyers operate on spot-market purchasing with minimal qualification burden, compressing supplier margins.
Food and beverage manufacturers represent the largest procurement volume; pharmaceutical companies drive the fastest specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are reshaping sterol trade corridors. The United States maintains a structural deficit in pharmaceutical-grade material, while Germany and India anchor opposite ends of the value chain as specialized exporters.
United States
Functional food manufacturers in the Midwest drive bulk procurement of plant-derived sterols. FDA dietary supplement labeling requirements are accelerating reformulation timelines for heart-health positioned products. Chicago and Minneapolis processing corridors concentrate deodorizer distillate refining capacity for domestic beta-sitosterol supply.
Germany
Pharmaceutical compounders in Baden-Württemberg command premium positioning for campesterol in cardiovascular therapeutic formulations. EMA validation requirements filter supplier pools to GMP-certified processors. Frankfurt and Ludwigshafen chemical clusters host sterol esterification infrastructure serving European drug manufacturers.
India
API manufacturers in Gujarat and Maharashtra import stigmasterol intermediates for semi-synthetic hormone production. FSSAI functional food standards are opening formal pathways for sterol-fortified edible oils in domestic retail channels. Mumbai and Ahmedabad refining hubs are expanding tall oil fractionation capacity for brassicasterol extraction.
China
Soybean processors in Shandong and Heilongjiang provinces export bulk sterol distillates to European compounders. NMPA pharmaceutical registration protocols are tightening impurity profiling requirements for imported drug-grade material. Qingdao and Dalian port infrastructure handles concentrated flows of corn-derived phytosterols bound for Japanese nutraceutical manufacturers.
Finland
Pulp mill integration in the Lakeland region sustains tall oil sterol extraction outside commodity oilseed channels. EFSA health claim protocols are elevating evidentiary burdens for cholesterol reduction positioning in Nordic retail. Kotka and Rauma port terminals ship pine-derived beta-sitosterol to German cosmetic formulators.
Global Sterols Market Competitive Landscape
Concentration sits with diversified chemical conglomerates and integrated agricultural processors. The supply base bifurcates between pharmaceutical-validated and food-grade tiers, with qualification stringency determining competitive access. Strategic archetypes include backward-integrated oilseed refiners, specialty tall oil extractors, and biotechnology-platform operators. Capacity expansion and GMP certification acquisition constitute the dominant competitive moves.
Within the integrated processor tier, BASF SE and Cargill, Incorporated exemplify divergent sourcing strategies. Arboris occupies a defensible position as a tall oil specialist outside commodity oilseed volatility. These three anchors illustrate how competitive positioning depends on feedstock control and regulatory qualification depth rather than scale alone.
| Leading Market Players |
|---|
| BASF SE |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| DuPont de Nemours, Inc. |
| The Lubrizol Corporation |
| Arboris |
| Raisio Oyj |
| Bunge Limited |
| Kerry Group plc |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day inventory cycles for pharmaceutical-grade sterols concentrate pricing power among GMP-certified processors in Germany and Switzerland, while spot-market beta-sitosterol flows through US Midwest soybean corridors on fifteen-day turns. This divergence between validated-drug and food-grade tiers lets integrated refiners capture margin premiums that non-integrated processors cannot access.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across pharmaceutical, food-grade, and feed-tier certification levels. Price differentiation hinges on GMP validation depth and volume scale, with pharmaceutical compounders showing lowest sensitivity due to regulatory switching costs. Cost compression in food-grade beta-sitosterol is intensifying because Argentine processors are expanding deodorizer distillate capacity. Feed manufacturers exhibit highest price sensitivity, procuring on spot markets with minimal qualification burden.
Supply Chain Analysis
The United States, Brazil, and Argentina anchor bulk beta-sitosterol production from soybean and corn oil refining, while Finland and Sweden sustain pine-derived sterol extraction through pulp mill integration. Feedstock supply draws from vegetable oil deodorizer distillates, tall oil pitch fractions, and ethanol co-product streams. Single-source vulnerability concentrates in pharmaceutical-grade campesterol, where Baden-Württemberg compounders rely on limited GMP-certified European suppliers. Distribution runs through long-term offtake agreements with CPG procurement teams displacing spot purchasing for functional food applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat because FDA and EMA validation protocols impose multi-year qualification timelines that insulate incumbent GMP-certified processors from price-based displacement.
For Market Incumbents: Compound certification depth in pharmaceutical-grade sterol production to defend against synthetic cholesterol substitutes threatening natural-source displacement. Prioritize capacity addition in US Midwest soybean corridors where CPG procurement consolidation favors integrated refiners with crop-to-ingredient provenance certification. For New Entrants and Emerging Players: Lead with enzymatic extraction methods qualifying under streamlined EPA biosafety frameworks to target white-space in US biotech-enabled sterol supply. The most penetrable segment sits in FSSAI-aligned sterol-fortified edible oils for Indian domestic retail, where cardiovascular disease prevalence drives health-claim reformulation without entrenched supplier relationships. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because regulatory qualification depth creates durable margin premiums unavailable in commodity feedstock processing. Target tall oil specialists with pulp mill integration outside oilseed price transmission. The signal to watch is REACH documentation burden escalation filtering novel extraction method entrants.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Acquisition | EMA and FDA validation protocols filter supplier pools to certified processors in Germany and Switzerland. |
| Backward Integration into Soybean Refining | US Midwest crushers capture sterol streams from existing deodorizer distillate infrastructure. |
| Enzymatic Extraction Scale-Up | EPA biosafety alignment reduces qualification friction for novel US-based biotech entrants. |
| Tall Oil Fractionation Expansion | Finnish and Swedish pulp mills sidestep commodity oilseed volatility through pine-derived sourcing. |
| Long-Term CPG Offtake Structuring | Volume commitments with functional food manufacturers displace spot market purchasing patterns. |
Research Methodology
A standing panel of pharmaceutical procurement directors, vegetable oil refinery plant managers, FSSAI regulatory affairs leads, and functional food brand managers provided ongoing calibration across primary interviews and secondary validation. Customs trade data, FDA dietary supplement filings, EFSA health claim registers, and SEC 10-K disclosures from integrated agricultural processors anchored bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling across product type, application, source feedstock, and end-user specification intensity. CAGRs were derived from demand-side uptake curves in functional food reformulation and supply-side capacity expansion in GMP-certified extraction infrastructure.
Forecasts assume regulatory continuity in FDA dietary supplement protocols, EMA pharmaceutical validation requirements, and REACH chemical registration regimes; material policy shifts would require re-modeling. Specific risks include synthetic cholesterol substitute approval acceleration and vegetable oil feedstock price volatility transmission. Recalibration cycles align with material shifts in regulatory evidentiary standards and CPG procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
China Food Flavor and Enhancer Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Soy Sauce Powder Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Natural and Organic Flavors Market
Flavorings and Food Additives
Food Texturizers Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Grapefruit Oil Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Annatto Extract Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Jujube Extracts Market
Flavorings and Food Additives
Flavoring Oil Market