
 Botanical Flavors Market | 2026-2036
Botanical Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Botanical Flavors Market Outlook
Subscription-based flavor customization services is realigning how botanical extracts reach mid-sized beverage and confectionery clients. Givaudan leverages its integrated extraction network across multiple continents to secure raw material consistency. International Flavors & Fragrances sustains competitive pressure through deep R&D investment in cold-press and CO2 extraction technologies. Symrise anchors its position in European markets with specialized supply agreements for organic-certified botanicals.
Botanical flavors comprise volatile and non-volatile compounds derived from plant tissues through steam distillation, solvent extraction, or enzymatic treatment, standardized to specific flavor potency measured in fold concentration or percentage of key aromatic markers. These formulations serve primarily to replace synthetic flavor chemicals in consumer products where ingredient transparency influences purchase decisions. Essential oils and natural flavorings command premium positioning within the product type matrix due to concentrated aromatic profiles and extended shelf stability. Within applications, beverages and confectionery absorb the majority of volume, while bakery products and sauces represent faster-growing niches as manufacturers reformulate legacy recipes.
The FDA's natural flavor definition under 21 CFR 101.22 and the EU's REACH framework govern extraction solvent allowances and labeling claims, directly constraining which botanical sources qualify for clean-label positioning in their respective jurisdictions. EFSA evaluations of novel botanical extracts create additional pre-market hurdles for suppliers seeking European distribution. Stakeholders must monitor pending regulatory revisions on natural versus nature-identical classifications to anticipate reformulation costs and sourcing adjustments.
Market Dynamics
Clean-label reformulation pressure from beverage and confectionery manufacturers is compressing procurement cycles for botanical extraction suppliers, forcing rapid scale-up of cold-press and CO2 extraction capacity to meet solvent-free certification requirements under FDA and REACH frameworks.
Growth Catalysts
- EU REACH solvent restrictions:Tightening extraction solvent allowances under ECHA guidelines are accelerating replacement of synthetic flavor chemicals with steam-distilled botanicals in German and French food processing facilities.
- Beverage clean-label mandates:Major soft drink and functional beverage producers are eliminating artificial additives, creating sustained pull for standardized essential oil formulations with documented fold concentrations.
- Hamburg-Frankfurt extraction cluster:Concentrated botanical processing infrastructure in Central Germany enables just-in-time delivery to European confectionery and sauce manufacturers.
Market Restraints
- Raw material volatility:Weather-sensitive cultivation of vanilla, citrus, and spice botanicals in Madagascar, India, and Indonesia generates supply instability and price spikes for natural flavor houses.
- EFSA novel extract evaluations:Pre-market safety assessments for new botanical sources create 18-24 month approval delays, freezing supplier innovation pipelines for European distribution.
- Enzymatic treatment capacity scarcity:Limited commercial-scale facilities for biocatalytic flavor extraction constrain output of premium natural flavorings relative to solvent-based alternatives.
Strategic Opportunities
- India FSSAI organic certification:India's food safety regulator is expanding recognition for organic-certified botanicals, opening procurement channels for Indian-grown turmeric, cardamom, and holy basil extracts.
- Bakery application expansion:Underpenetrated reformulation of legacy pastry and bread recipes presents volume growth potential as manufacturers replace artificial vanillin with natural vanilla and botanical butter flavors.
- Subscription flavor customization:Direct-to-manufacturer digital platforms for mid-sized beverage clients are disintermediating traditional distributor relationships and capturing margin previously lost to intermediaries.
Industry Challenges
- Analytical chemist shortage:Specialized expertise in gas chromatography-mass spectrometry for aromatic marker identification is scarce, delaying batch certification and release timelines.
- Dual jurisdiction compliance:Suppliers serving both FDA and REACH markets must maintain parallel documentation systems for extraction solvent residues and natural flavor definitions, multiplying administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botanical Flavors Market |
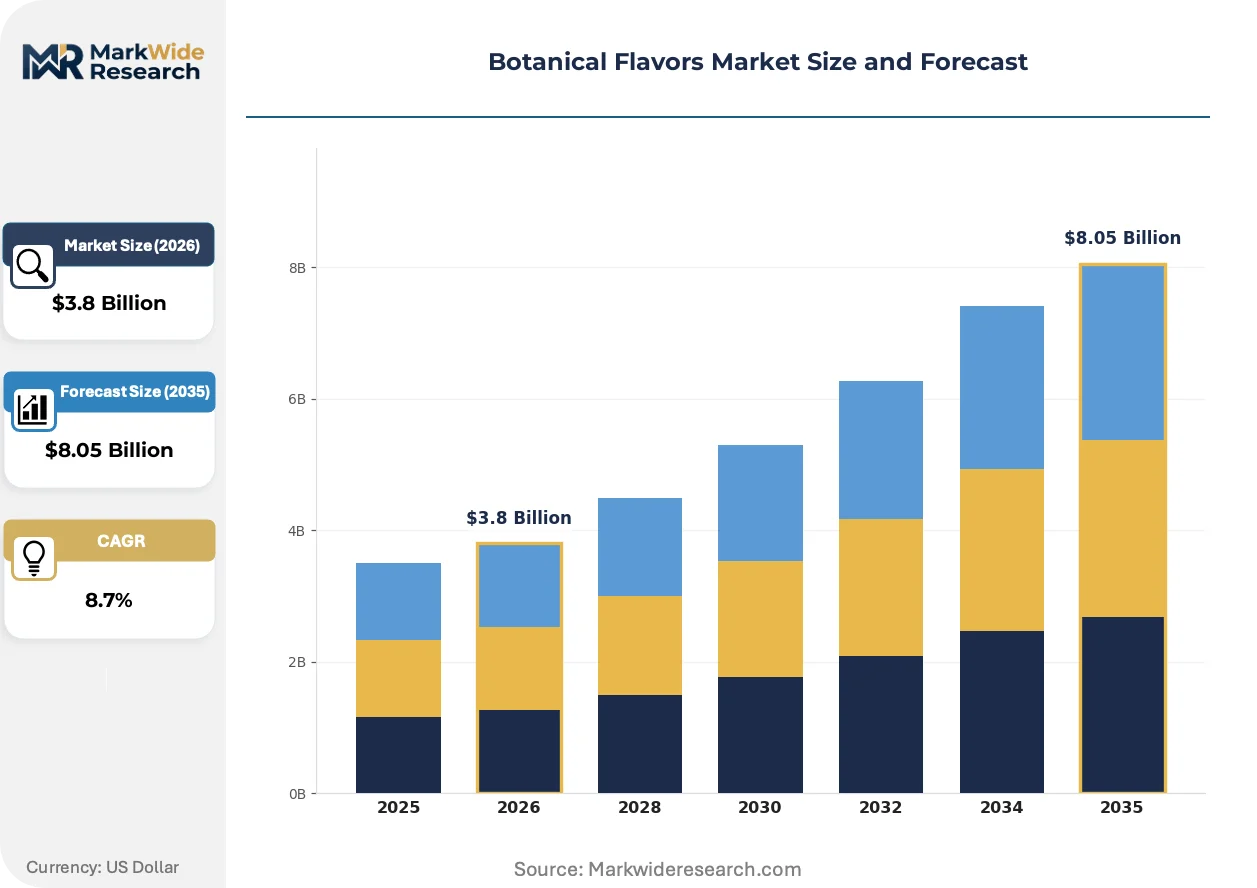
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Extracts, Essential Oils, Flavoring Agents, Natural Flavorings End User: Food & Beverage, Cosmetics, Pharmaceuticals, Nutraceuticals Application: Bakery Products, Beverages, Sauces & Dressings, Confectionery Grade: Food Grade, Cosmetic Grade, Pharmaceutical Grade, Industrial Grade |
| Companies Covered | Givaudan, International Flavors & Fragrances, Firmenich, Symrise, Archer Daniels Midland, Dohler GmbH, Synergy Flavors, Bell Flavors & Fragrances, kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botanical Flavors Market Strategic Shifts
Extraction technology automation and regulatory reclassification of natural flavor definitions are compressing supplier margins while opening new application categories for botanical formulations in functional beverages and savory sauces.
Supercritical CO2 extraction systems are automating the separation of volatile aromatic compounds from plant matrices without thermal degradation or solvent residues. Mid-sized flavor houses in Germany and California are retrofitting existing steam distillation facilities with modular CO2 units to serve organic-certified confectionery clients. This automation is compressing batch-to-batch variability and reducing reliance on skilled operator judgment for extraction endpoint determination.
EFSA's evolving guidance on botanical novel food status is reclassifying certain traditional herbal extracts as requiring pre-market authorization, forcing reformulation of existing European beverage and supplement products. Suppliers must now submit comprehensive toxicological dossiers for extracts derived from sources not consumed pre-1997, adding compliance costs that favor established players with dedicated regulatory affairs teams. Cold-pressed citrus and mint extracts face heightened scrutiny, driving some manufacturers toward grandfathered steam-distilled alternatives.
Direct sourcing partnerships between extraction facilities and agricultural cooperatives are displacing traditional commodity broker networks for vanilla, cocoa, and spice botanicals. Beverage manufacturers in North America are establishing captive supply relationships with Madagascan and Ugandan vanilla growers to secure traceability documentation required for clean-label claims. This disintermediation is most visible in premium functional drink segments where single-origin botanical provenance commands shelf price premiums.
Botanical Flavors Market Segmentation
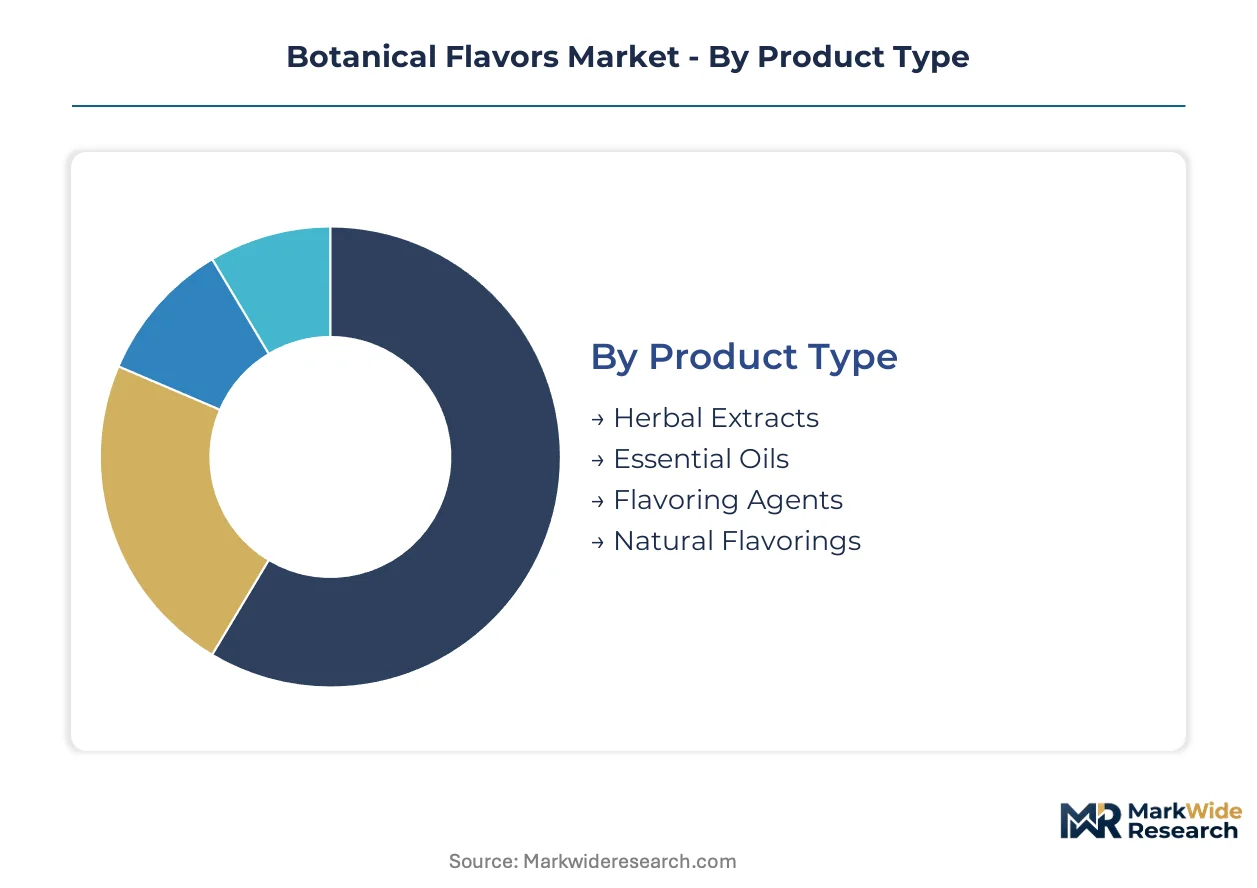
Botanical flavor suppliers face divergent technical specifications across end-use categories, forcing parallel production lines and certification systems. Segmentation clarity enables manufacturers to align extraction protocols with the precise regulatory thresholds governing each downstream application.
Product Type:
Purchase decisions hinge on concentration potency and solvent residue limits mandated by FDA and REACH frameworks for clean-label positioning.
- Essential Oils:Highly concentrated volatile aromatic compounds obtained through steam distillation or cold-pressing, standardized to fold concentration metrics. Beverage manufacturers in Germany and France prioritize these formulations for their solvent-free certification and extended shelf stability under ECHA guidelines.
- Natural Flavorings:Complex mixtures of volatile and non-volatile compounds extracted through enzymatic or CO2 methods, delivering standardized aromatic profiles. Demand concentrates in North American functional beverage producers eliminating artificial additives from ingredient declarations.
- Herbal Extracts:Water or ethanol-soluble botanical concentrates capturing polyphenolic and terpenoid compounds for flavor and functional applications.
- Flavoring Agents:Standardized aromatic preparations blended to specific taste profiles for industrial-scale food processing.
Volume sits with Essential Oils; growth tilts toward Natural Flavorings.
End User:
Regulatory jurisdiction determines extraction solvent allowances and toxicological documentation burdens.
- Food & Beverage:Clean-label reformulation across soft drinks, confectionery, and sauces drives procurement of steam-distilled and CO2-extracted botanicals with documented fold concentrations and traceability documentation.
- Pharmaceuticals:Botanical extracts meeting USP or EP monograph standards for tablet coatings and oral dosage flavor masking.
- Cosmetics:Fragrance-grade botanicals for personal care applications requiring IFRA compliance and dermal safety assessments.
- Nutraceuticals:Standardized herbal extracts combining flavor function with bioactive compound claims subject to novel food evaluations.
Food & Beverage commands current volume; Pharmaceuticals offers the steepest expansion trajectory as oral dosage flavoring requirements tighten.
Application:
Reformulation urgency varies by category based on artificial additive exposure and consumer label scrutiny.
- Beverages:Functional drinks and premium soft drinks lead botanical adoption, with manufacturers replacing synthetic flavor chemicals to meet clean-label mandates and secure shelf price premiums in competitive retail environments.
- Confectionery:Gummies, hard candies, and chocolate applications require heat-stable botanical formulations that retain aromatic integrity through high-temperature processing stages.
- Bakery Products:Underpenetrated segment where legacy artificial vanillin replacement with natural vanilla and botanical butter flavors presents volume growth potential.
- Sauces & Dressings:Savory botanical applications including herb-infused emulsions and spice extracts for condiment reformulation.
Beverages anchor current procurement; Bakery Products gains share fastest as pastry and bread manufacturers accelerate artificial additive elimination.
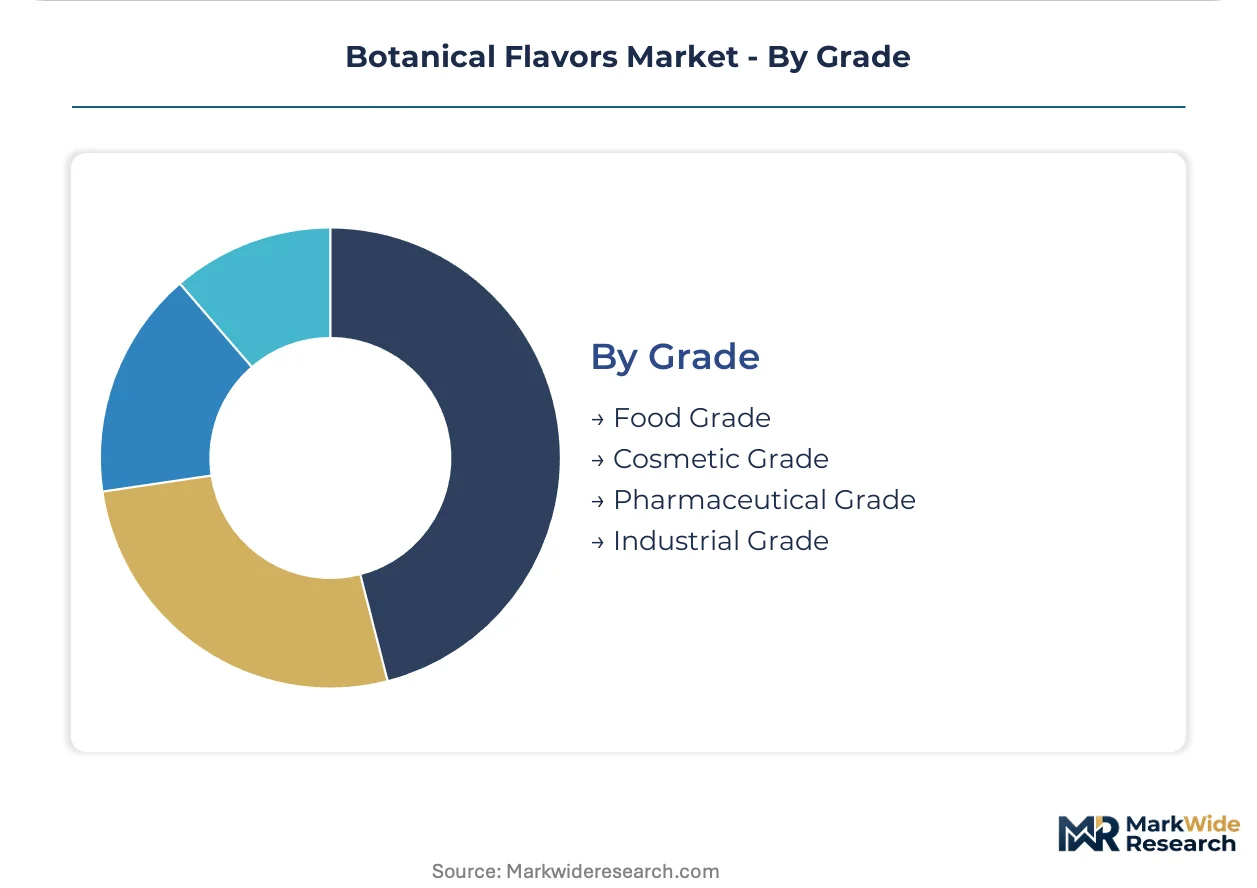
Grade:
Certification tier dictates extraction facility investment, analytical testing protocols, and documentation systems.
- Food Grade:Botanical extracts meeting FDA 21 CFR 101.22 and EU food additive specifications for direct human consumption, requiring gas chromatography-mass spectrometry verification of aromatic markers and solvent residues.
- Pharmaceutical Grade:USP or EP-compliant extracts with validated manufacturing processes and stability data for drug product integration.
- Cosmetic Grade:IFRA-conforming botanicals with dermal safety assessments for topical application.
- Industrial Grade:Non-food botanical preparations for technical applications with reduced purity specifications.
Food Grade dominates procurement volume; Pharmaceutical Grade expands most quickly as oral dosage flavoring standards converge with botanical extract capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hamburg-Frankfurt corridor anchors European botanical extraction capacity, with concentrated processing infrastructure serving Central European food manufacturers demanding rapid turnaround on clean-label flavor formulations.
Germany
Functional beverage manufacturers in Bavaria and North Rhine-Westphalia are eliminating synthetic additives from ingredient declarations. ECHA's REACH solvent restrictions mandate documented residue testing for all imported botanical extracts. The Hamburg-Frankfurt extraction cluster enables just-in-time delivery to confectionery processors reformulating legacy recipes.
United States
Soft drink producers in California and Texas are establishing captive supply relationships with Madagascan vanilla growers for traceability documentation. FDA guidance under 21 CFR 101.22 constrains which extraction methods qualify for natural flavor labeling. Midwest beverage facilities are retrofitting steam distillation lines with modular CO2 extraction units.
France
Sauce and condiment manufacturers in Île-de-France are accelerating procurement of herb-infused emulsions for clean-label reformulation. ANSM enforces dermal safety assessments for botanicals crossing into cosmetic applications. The Provence-Alpes-Côte d'Azur region concentrates lavender and herb distillation capacity serving premium fragrance and flavor houses.
India
Domestic turmeric and cardamom extract demand is rising as FSSAI expands organic certification recognition for export-grade botanicals. The Spice Board of India coordinates quality standardization for cardamom, black pepper, and ginger extracts. Karnataka and Kerala processing facilities are scaling enzymatic extraction capacity for natural flavoring production.
Japan
Functional drink manufacturers in the Kanto region are integrating yuzu and matcha extracts into premium positioning strategies. METI's guidance on novel food ingredients creates pre-market documentation requirements for traditional botanicals in new applications. Osaka-area flavor houses specialize in heat-stable formulations for confectionery applications.
Botanical Flavors Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the botanical flavor value chain. Integrated extraction networks with captive agricultural sourcing dominate premium-tier supply, while specialized flavor houses without cultivation assets compete on formulation agility and regulatory dossier expertise. Three archetypes define competitive positioning: vertically integrated agricultural processors, technology-focused extraction specialists, and formulation-centric flavor houses. Consolidation pressure is accelerating through strategic partnerships between extraction facilities and agricultural cooperatives, alongside capacity expansion in CO2 and enzymatic processing.
Among Swiss-headquartered integrated players, Givaudan and Firmenich occupy positions spanning agricultural sourcing through finished flavor formulation. International Flavors & Fragrances exemplifies the technology-driven archetype with substantial R&D infrastructure in advanced extraction methodologies. Symrise represents the European-market specialist model with concentrated supply agreements for organic-certified botanicals. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Givaudan |
| International Flavors & Fragrances |
| Firmenich |
| Symrise |
| Archer Daniels Midland |
| Dohler GmbH |
| Synergy Flavors |
| Bell Flavors & Fragrances |
| Kerry Group |
| Others |
Value Chain & Pricing Dynamics
Vanilla bean futures and citrus peel spot indices cascade through botanical flavor supply chains into stratified pricing tiers, with Madagascar-origin vanilla commanding premiums over Indonesian alternatives and cold-pressed citrus extracts pricing at multiples above solvent-based equivalents. REACH-compliant CO2 extraction capacity scarcity in Germany and California reinforces tier separation as beverage manufacturers absorb certification-driven cost premiums for clean-label positioning.
Pricing Analysis
Margin tightening in mid-tier natural flavorings reflects enzymatic extraction capacity bottlenecks and analytical chemist scarcity delaying batch certification. Three-tier pricing structure across premium organic-certified, standard food-grade, and economy solvent-extracted levels separates buyers by documentation requirements and fold concentration specifications. Cost-down pressure on standard-tier formulations accelerates as mid-sized beverage clients migrate to subscription-based procurement platforms disintermediating traditional distributors. Private-label confectionery manufacturers exhibit highest price sensitivity; premium functional drink producers absorb organic certification premiums with minimal volume elasticity.
Supply Chain Analysis
Analytical chemist shortages in Hamburg and California extraction clusters constrain throughput expansion despite automated CO2 system deployments. Supply concentrates in Madagascar for vanilla, India for turmeric and cardamom, and Indonesia for spice botanicals, creating geographic dependency on tropical cultivation zones. Raw material pipelines draw from weather-sensitive agricultural cooperatives, with drought-induced crop failures generating 18-24 month supply disruptions. Single-source vulnerability for Bourbon vanilla and Sri Lankan cinnamon exposes processors to climate-driven price spikes. Distribution runs through regional flavor houses maintaining parallel FDA and REACH documentation systems for dual-jurisdiction clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Botanical flavor markets reward backward integration into captive agricultural sourcing, with traceability documentation emerging as the decisive competitive moat separating premium-tier suppliers from commodity competitors.
For Market Incumbents: Acquire enzymatic extraction facilities and organic-certified cultivation acreage to secure solvent-free certification capacity and raw material traceability documentation. Consolidate Hamburg-Frankfurt processing infrastructure through regional facility acquisitions to capture just-in-time delivery contracts from Central European confectionery reformulators. Cold-press technology specialists and FSSAI-recognized Indian agricultural cooperatives represent priority acquisition targets against emerging technology-driven entrants. For New Entrants and Emerging Players: The premium-to-economy price gap in bakery applications offers accessible entry volume as artificial vanillin replacement accelerates in pastry and bread manufacturing. Target underpenetrated sauce and dressing reformulation in France and Germany where herb-infused emulsion demand outpaces specialized supplier capacity. Deploy direct-to-manufacturer digital platforms with subscription flavor customization to bypass entrenched distributor relationships capturing mid-sized beverage client margins. For Investors and Strategic Acquirers: The window for entry favors technology-focused extraction specialists with modular CO2 automation and established EFSA regulatory dossier capabilities. Long-term viability hinges on dual-jurisdiction compliance infrastructure serving both FDA and REACH markets with parallel documentation systems. Watch for EFSA novel extract evaluation backlog resolution as inflection indicator for innovation pipeline velocity and premium formulation pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Cooperatives | Madagascan and Ugandan vanilla grower partnerships secure traceability documentation for clean-label claims. |
| Modular CO2 Extraction Capacity Expansion | California and German facility retrofits serve organic-certified confectionery clients with solvent-free certification. |
| Direct-to-Manufacturer Digital Platform Launch | Subscription flavor customization disintermediates distributors and captures mid-sized beverage client margins. |
| EFSA Regulatory Dossier Investment | Novel extract pre-market authorization capabilities accelerate European distribution access for innovation pipelines. |
| Enzymatic Treatment Facility Acquisition | Biocatalytic extraction capacity scarcity creates premium positioning for natural flavoring output expansion. |
Study Parameters
Trade databases, EFSA safety evaluation registers, and FSSAI organic certification records formed the secondary backbone, cross-referenced with customs data on vanilla, citrus, and spice botanical imports. Primary interviews with extraction facility technical directors, beverage manufacturer procurement leads, confectionery reformulation specialists, and regulatory affairs managers at flavor houses validated capacity utilization rates and certification timelines. Bottom-up and top-down triangulation reconciled facility-level production data with end-use consumption patterns across beverage, confectionery, and bakery applications.
Bottom-up modeling anchored projections in named extraction facility capacity expansions and agricultural cooperative yield estimates, while top-down analysis cross-checked against clean-label reformulation mandates at major soft drink and functional beverage producers. Segmentation dimensions spanned extraction methodology, certification grade, application heat-stability requirements, and regulatory jurisdiction cluster. CAGRs derived from facility investment pipelines and EFSA evaluation queue resolution timelines, with vanilla bean price volatility and enzymatic capacity buildout rates as key sensitivity inputs across the projection horizon.
Inputs from EFSA evaluation registers and FSSAI certification databases were available through the study window; gaps in proprietary extraction yield data and confidential supply contract terms introduce uncertainty bands around capacity expansion timelines. Forecasts reflect assumptions on REACH solvent restriction enforcement continuity and FDA natural flavor definition stability. Material deviation in EFSA novel extract evaluation velocity or Madagascar vanilla crop yields warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
All-Natural Flavors System Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Ginkgo Biloba Extract Market
Flavorings and Food Additives
Beverage Flavoring Agent Market
Flavorings and Food Additives
Japan Food Flavor and Enhancer Market
Flavorings and Food Additives
Egypt Food Colorants Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
Rose Water Market
Flavorings and Food Additives
South America Food Flavor and Enhancer Market
Flavorings and Food Additives
Natural Flavors Market
Flavorings and Food Additives
Global Sterols Market
Flavorings and Food Additives
China Food Flavor and Enhancer Market
Flavorings and Food Additives
Canola Lecithin Market