
 Camelina Oil Market | 2026-2036
Camelina Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Camelina Oil Market Analysis
Modular packaging formats across bottles, cans, and totes is hardening as the dominant configuration logic, letting buyers match order size to application volume without committing to bulk drum contracts. Sustainable Oils leverages its integrated seed-to-oil pipeline to control supply consistency for biofuel clients. Henry Lamotte Services GmbH anchors European distribution through its refined-oil specialization for cosmetic and pharmaceutical formulators. Smart Earth Camelina Corp. competes on varietal development, breeding high-oil cultivars tailored to cold-climate cultivation.
Camelina oil is a cold-pressed triglyceride oil extracted from Camelina sativa seeds, containing approximately 35-40% alpha-linolenic acid and notable levels of vitamin E, with a smoke point around 245°C that suits both food and industrial applications. Refined oil commands the largest value share due to its neutral flavor profile and extended shelf stability demanded by food manufacturers and personal care brands. Unrefined oil retains higher antioxidant content and captures premium positioning within health stores and direct-to-consumer channels. Biofuels represent the fastest-expanding end use industry as renewable diesel producers seek non-food oilseeds with favorable carbon intensity scores under compliance programs.
The EPA's Renewable Fuel Standard and California Air Resources Board's LCFS pathway certifications shape feedstock demand by assigning carbon scores that determine credit generation. REACH registration requirements in Europe and FDA food-contact substance notifications in the United States govern product standards and cross-border market access for refined and unrefined grades. Stakeholders must monitor evolving low-carbon fuel regulations and oilseed sustainability certifications to secure offtake contracts and protect margin structures.
Market Dynamics
Biofuel refiners are locking in multi-year offtake agreements for camelina-derived renewable diesel, creating supply-side pull that is reshaping acreage allocation decisions across North American farming regions.
Growth Catalysts
- California LCFS pathway certifications:The state's Low Carbon Fuel Standard assigns favorable carbon intensity scores to camelina oil, generating compliance credits that refiners monetize.
- Renewable diesel capacity expansion:Biofuel producers are commissioning new hydrotreating units designed specifically for non-food oilseeds with low carbon footprints.
- EU Renewable Energy Directive feedstock qualification:European refiners are advancing camelina through sustainability certification pathways to meet renewable transport fuel mandates.
Market Restraints
- Crush capacity concentration:North American oilseed processing infrastructure remains concentrated among legacy soybean and canola facilities with limited camelina retrofit flexibility.
- Input cost volatility:Farmgate camelina seed prices fluctuate with competing crop economics, particularly spring wheat and canola rotation decisions.
- Substitution threat from used cooking oil:Renewable diesel producers are simultaneously qualifying lower-cost waste feedstocks that compete for the same LCFS credits.
Strategic Opportunities
- Underpenetrated Canadian Prairie provinces:Saskatchewan and Alberta hold expansion-ready farmland with climate conditions suited to camelina's cold-weather hardiness.
- Aviation fuel offtake contracts:Airlines are negotiating sustainable aviation fuel supply agreements that specify camelina oil as a certified feedstock under CORSIA.
- Cosmetic formulator channel development:Direct relationships with clean beauty brands are bypassing traditional distributor markups for cold-pressed unrefined grades.
Industry Challenges
- Seed multiplication timeline:Certified seed stock for high-oil cultivars requires three to four growing seasons to scale commercially.
- IP licensing complexity:Trait stacks for herbicide tolerance and oil profile modification involve overlapping patent estates across multiple germplasm developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camelina Oil Market |
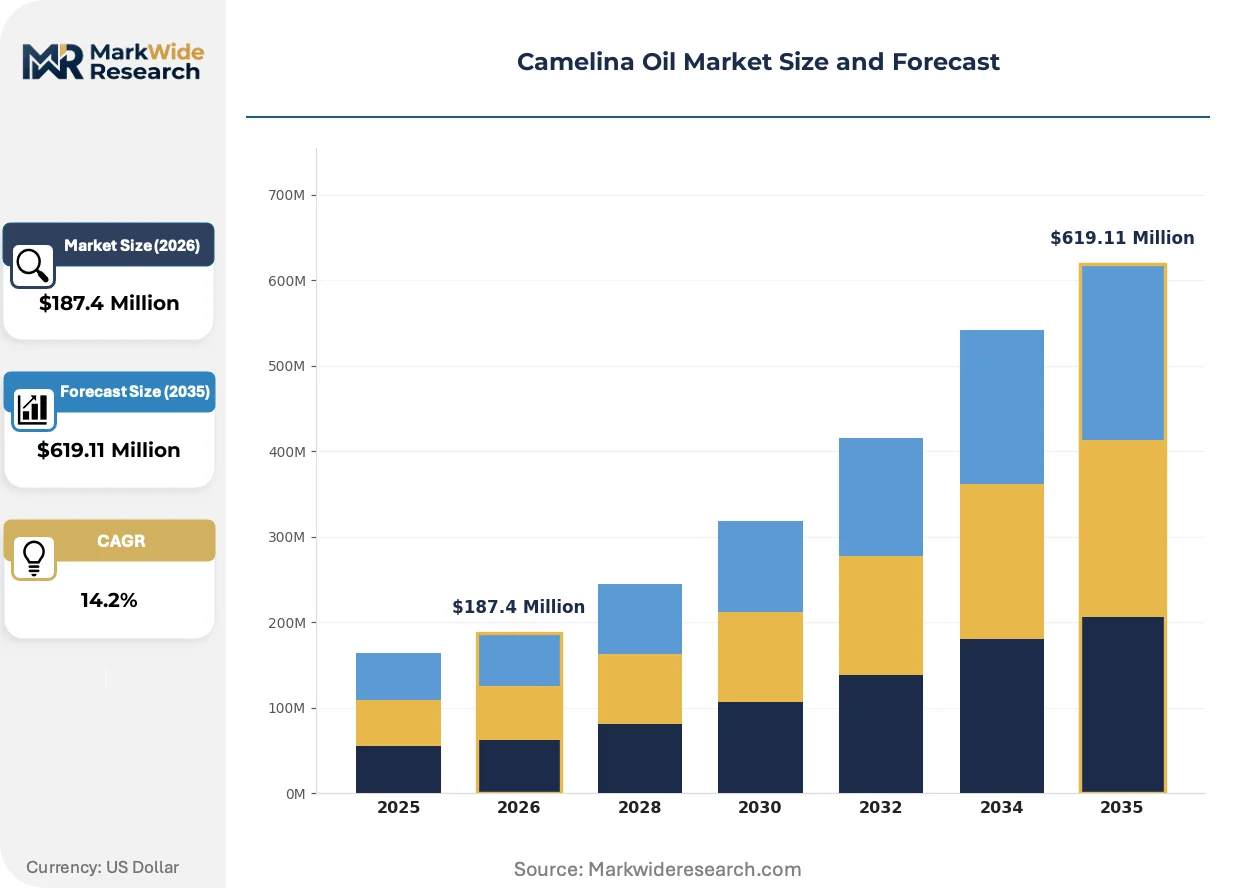
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Unrefined Oil, Crude Oil, Essential Oil End Use Industry: Food Industry, Personal Care, Pharmaceuticals, Biofuels Packaging Type: Bottles, Cans, Drums, Totes Distribution Channel: Online Retail, Supermarkets, Health Stores, Distributors |
| Companies Covered | H and B Oils Center Co., Global Clean Energy Holdings, Fitoben Srl, Australian Wholesale Oils, Henry Lamotte Services GmbH, Jedwards International Inc., Sustainable Oils, Smart Earth Camelina Corp., Making Cosmetics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camelina Oil Market Emerging Trajectories
Mechanical pressing and solvent extraction configurations are being retooled for camelina's unique hull structure, while breeding programs accelerate trait development for industrial end-uses.
Supercritical CO2 extraction is expanding into camelina oil production for cosmetic and nutraceutical applications where residual solvent standards are tightening. European personal care formulators are adopting this technology to meet REACH registration requirements for novel extraction methods. The process is expanding into mid-scale production facilities that previously relied on cold-pressing alone, compressing the quality premium between artisanal and industrial grades.
EPA Renewable Fuel Standard pathway approvals are creating compliance-grade feedstock categories that differentiate camelina oil from uncertified alternatives. Refiners must document chain-of-custody from seed to fuel to generate RINs, forcing supply chain reconfiguration. Biofuel producers with integrated crushing operations are capturing margin that previously flowed to third-party oilseed processors.
Direct contracting between crush facilities and biofuel refiners is displacing spot market purchases for compliance-grade feedstocks. Large renewable diesel producers are negotiating five to seven-year supply agreements with fixed pricing indexed to LCFS credit values. This pattern is most visible in California and Oregon, where state-level clean fuel programs have created predictable offtake economics.
Camelina Oil Market Segmentation
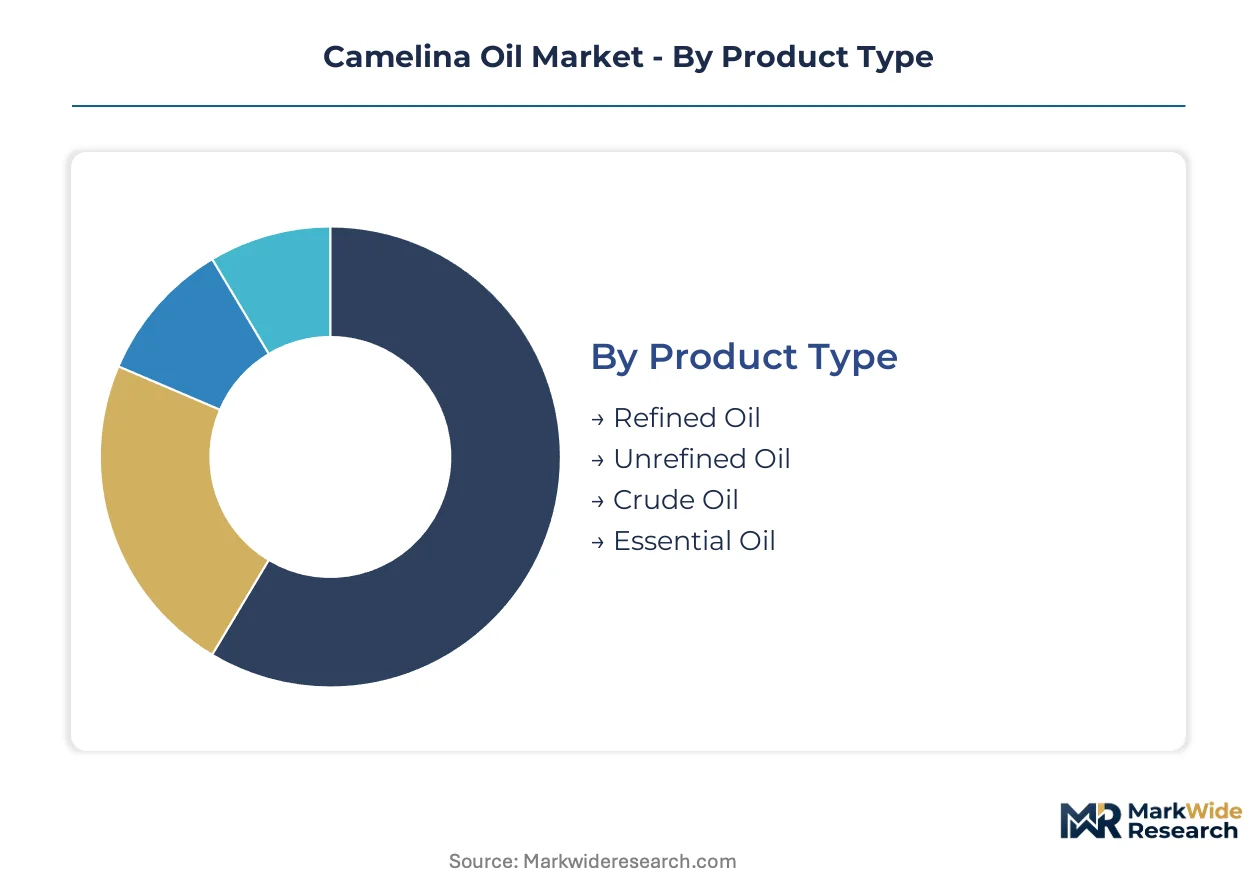
Camelina oil segmentation reflects divergent purity requirements across food, fuel, and cosmetic applications. Buyers select grades based on smoke point thresholds, carbon intensity scoring, and antioxidant retention needs.
Product Type:
Customization intensity spans from commodity crude to precision-refined specifications, with processing depth determining end-use eligibility and margin capture.
- Refined Oil:Neutralized and deodorized to remove free fatty acids and phospholipids, achieving extended shelf stability. Food manufacturers in the United States specify this grade for frying applications above 230°C. Refined oil dominates volume contracts with renewable diesel producers seeking consistent feedstock specifications.
- Unrefined Oil:Cold-pressed and filtered without chemical treatment, retaining vitamin E and polyphenol content. Health stores and direct-to-consumer channels in Germany and France command premium positioning for this grade. Cosmetic formulators specify unrefined oil for antioxidant-rich serum applications.
- Crude Oil:Solvent-extracted or expeller-pressed base material requiring downstream refining. Biofuel refiners purchase crude oil for in-house hydrotreating to renewable diesel specifications.
- Essential Oil:Steam-distilled volatile fraction capturing camelina's characteristic nutty aroma. Niche aromatherapy and natural fragrance applications in Switzerland and Austria utilize this grade.
Most installed capacity flows through Refined Oil. Expansion is steepest in Unrefined Oil.
End Use Industry:
Application-driven segmentation separates compliance-grade fuel feedstocks from formulation-sensitive cosmetic and food grades.
- Biofuels:Hydrotreated renewable diesel and sustainable aviation fuel production represent the steepest demand trajectory. California LCFS pathway certification and EPA RIN eligibility create premium pricing tiers for certified camelina oil. Refiners in Oregon and Washington State are commissioning dedicated camelina processing trains.
- Food Industry:Salad oils, cooking sprays, and nutritional supplements utilize refined grades for oxidative stability. European food manufacturers specify camelina oil for omega-3 fortification in bakery and dairy applications.
- Personal Care:Cold-pressed unrefined oil serves clean beauty formulations requiring cold-process emulsification. French and Italian cosmetic houses specify camelina for hair conditioning and skin barrier repair products.
- Pharmaceuticals:Excipient applications and soft-gel capsule formulations demand ultra-low peroxide specifications. Swiss and German pharmaceutical contract manufacturers qualify camelina oil for lipid-based drug delivery systems.
Procurement concentration centers on Biofuels. Volume gains are climbing fastest in Pharmaceuticals.
Packaging Type:
Container economics align with order frequency and contamination risk across food-grade and industrial handling requirements.
- Bottles:Amber glass and PET formats for retail shelf presence and light protection. Health stores and specialty grocers in the United States and Canada stock 250ml to 1L configurations.
- Cans:Aerosol and screw-cap metal containers for cooking spray applications. Food service distributors specify 5L to 20L cans for commercial kitchen replenishment.
- Drums:200-liter steel and HDPE drums for food manufacturing and cosmetic compounding. Midwestern US food processors receive drum deliveries on scheduled replenishment contracts.
- Totes:Intermediate bulk containers for biofuel refinery feedstock delivery. Crush facilities in Saskatchewan and Alberta load totes for rail shipment to California renewable diesel plants.
Drum shipments handle the largest tonnage. Tote utilization is expanding most quickly.
Distribution Channel:
Channel selection reflects buyer sophistication, with industrial procurement bypassing retail markup while consumer segments demand physical inspection.
- Distributors:Industrial oil brokers and ingredient houses manage bulk logistics for food and cosmetic manufacturers. Henry Lamotte Services GmbH anchors European refined-oil distribution through Hamburg and Rotterdam port facilities.
- Supermarkets:Mass-market retail placement for cooking oil and supplement positioning. US grocery chains in the Pacific Northwest feature camelina oil in natural foods sections.
- Health Stores:Specialty retail with staff consultation for omega-3 and cold-pressed positioning. Independent retailers in Colorado and Oregon emphasize local sourcing narratives.
- Online Retail:Direct-to-consumer subscription models and marketplace fulfillment. Amazon and specialized nutraceutical platforms handle unrefined oil shipments with temperature-controlled packaging.
Distributor networks command the highest throughput. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Camelina sativa cultivation originated in Central Europe and the Mediterranean basin, where Bronze Age farmers first domesticated the oilseed for lamp fuel and cooking. Modern industrial scaling began in the North American Great Plains during the early 2000s, when biofuel researchers identified its cold-climate hardiness and favorable carbon intensity profile.
United States
California's Low Carbon Fuel Standard drives renewable diesel demand, with EPA RIN eligibility creating premium pricing tiers for certified feedstock. The state's Air Resources Board maintains strict chain-of-custody documentation requirements. Pacific Northwest crush facilities in Oregon and Washington State are commissioning dedicated camelina processing trains for West Coast refiners.
Canada
Saskatchewan and Alberta hold expansion-ready farmland suited to camelina's frost tolerance, with Prairie grain handlers building oilseed storage infrastructure. Health Canada and PMRA regulate novel feedstock approval for food and fuel pathways. Crush capacity in Regina and Saskatoon is scaling to supply California renewable diesel plants via rail shipment.
Germany
European food manufacturers specify camelina oil for omega-3 fortification in bakery and dairy applications, with EFSA novel food approvals governing ingredient eligibility. REACH registration requirements shape extraction method standards for cosmetic grades. Hamburg and Rotterdam port facilities anchor continental distribution through refined-oil specialization.
France
French cosmetic houses formulate camelina oil into hair conditioning and skin barrier repair products, leveraging cold-pressed unrefined grades for clean beauty positioning. ANSM regulates cosmetic ingredient safety under EU Cosmetics Regulation. Provence and Occitanie host artisanal pressing operations serving Paris-based luxury formulators.
Switzerland
Swiss pharmaceutical contract manufacturers qualify camelina oil for lipid-based drug delivery systems, with Swissmedic overseeing excipient quality standards. Geneva and Basel clusters demand ultra-low peroxide specifications for soft-gel capsule formulations. Supercritical CO2 extraction facilities in the Alpine region serve premium nutraceutical applications.
Camelina Oil Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and supply chain control. The vendor base organizes into three tiers: integrated seed-to-oil operators with captive crushing, specialized refiners serving cosmetic and pharmaceutical channels, and regional distributors managing bulk logistics. Strategic moves concentrate on multi-year offtake contracting and varietal development licensing.
Within the integrated operator tier, Sustainable Oils and Smart Earth Camelina Corp. exemplify upstream control strategies. Henry Lamotte Services GmbH anchors European refined-oil distribution. These three entities represent distinct archetypes: seed genetics control, crush capacity ownership, and continental logistics specialization.
| Leading Market Players |
|---|
| H and B Oils Center Co. |
| Global Clean Energy Holdings |
| Fitoben Srl |
| Australian Wholesale Oils |
| Henry Lamotte Services GmbH |
| Jedwards International Inc. |
| Sustainable Oils |
| Smart Earth Camelina Corp. |
| Making Cosmetics Inc. |
| Others |
Supply Flow & Price Mechanics
Farmgate camelina seed indices in Saskatchewan and Alberta cascade through crush margins into three distinct oil pricing tiers, with California LCFS credit values indexing long-term offtake premiums and spot crude sales tracking competing canola economics.
Pricing Analysis
Long-term contract pricing indexed to carbon credit values dominates biofuel procurement, separating certified renewable diesel feedstock from uncertified alternatives. Price differentiation rests on EPA RIN eligibility and LCFS pathway certification, with food-grade refined oil commanding stability premiums and crude biofuel grades absorbing farmgate volatility. Cost compression in unrefined cosmetic grades intensifies as supercritical CO2 extraction scales. Biofuel refiners show lowest price sensitivity due to compliance credit monetization, while health retailers face acute margin pressure from substitute omega-3 sources.
Supply Chain Analysis
Rail freight rates from Prairie Canada to California refineries constitute the dominant logistics cost component, compressing crush margins on cross-border movements. Supply concentrates in Saskatchewan, Alberta, and Montana, with seed stock multiplication timelines tethered to varietal licensing complexity. The chain draws from certified seed developers, contract farming networks, and regional crush facilities. Single-source vulnerability sits with limited high-oil cultivar germplasm controlled by overlapping patent estates. Distribution runs through integrated seed-to-oil operators, industrial distributors, and direct refinery contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratchets, with California's LCFS credit price floors and EPA RFS volume mandates creating demand visibility that outpaces conventional agricultural commodities.
For Market Incumbents: To counter substitution pressure from used cooking oil and waste feedstocks, secure multi-year offtake agreements with renewable diesel producers indexed to LCFS credit values, and expand crush capacity in Saskatchewan to capture rail logistics arbitrage against West Coast refiners. For New Entrants and Emerging Players: Begin with varietal development licensing for cold-climate high-oil cultivars, targeting underpenetrated Canadian Prairie acreage and direct cosmetic formulator channels in France and Switzerland that bypass distributor markups for cold-pressed grades. For Investors and Strategic Acquirers: Consolidation pressure builds where seed genetics IP overlaps with crush capacity scarcity, favoring acquisition of integrated operators with EPA pathway certifications and captive Prairie farmland relationships. Watch sustainable aviation fuel offtake negotiations under CORSIA as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Five to seven-year offtake contracts with California refiners lock in LCFS credit exposure and crush margin visibility. |
| Backward Integration | Captive seed breeding programs reduce germplasm licensing costs and accelerate cultivar adaptation to regional frost patterns. |
| Green Certification Program | EPA RIN pathway approval and EU RED feedstock qualification open premium pricing tiers in compliance markets. |
| Capacity Expansion | Dedicated camelina processing trains in Oregon and Washington State capture West Coast renewable diesel demand growth. |
| Joint Venture | Airline partnerships for sustainable aviation fuel offtake secure CORSIA-eligible feedstock premiums ahead of mandate phase-in. |
Methodological Framework
Multiple input streams — primary interviews with crush facility operators, biofuel refinery procurement heads, and cosmetic formulator R&D directors, plus secondary validation through EPA RFS pathway filings, California LCFS certification databases, and EFSA novel food registers — were reconciled through bottom-up acreage and crush capacity modeling against top-down fuel mandate demand projections.
Historical crush margins and seed yield data were cross-referenced against expert panel inputs on varietal development timelines and LCFS credit price trajectories across the projection horizon. Segmentation dimensions modeled include product type, end-use industry, packaging format, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating biofuel capacity buildout schedules and crop rotation economics.
Caveats apply where EPA pathway approval delays, germplasm IP litigation, or LCFS credit price volatility could materially shift the outlook. Forecasts reflect documented assumptions on seed multiplication rates and crush facility commissioning timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
France Soy Protein Market
Ingredients
Coconut Flour Market
Ingredients
Brazil Corn Syrup Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Europe Malt Ingredient Market
Ingredients
Shortening Fats Market
Ingredients
Agave Inulin Market
Ingredients
Pea Flour Market
Ingredients
Bean Ingredients Market
Ingredients
Blackcurrant Concentrate Market
Ingredients
Ground-Nut Oil Market
Ingredients
Cold-Pressed Citrus Seed Oil Ingredients Market
Ingredients
Agarwood Oil Market
Ingredients
Specialty Fats and Oils Market
Ingredients
Mirepoix Market
Ingredients
Wheat Protein Concentrates Market