
 Native Starch Market | 2026-2036
Native Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Native Starch Market Intelligence
REACH compliance is decoupling small-scale extractors from mainstream European supply chains. Cargill, Incorporated leverages backward integration into corn wet milling across the American Midwest. Roquette Frères sustains product specialization in pea and potato starch variants for pharmaceutical-grade applications. Ingredion Incorporated anchors its competitive position through granular form technology leadership in clean-label food systems.
Native starch denotes the unmodified carbohydrate polymer extracted directly from botanical sources such as maize, potato, tapioca, or waxy cereals, retaining original amylose-amylopectin ratios without chemical, physical, or enzymatic alteration beyond standard purification and drying. Its primary industrial purpose centers on providing viscosity, gelation, and binding functionality across food processing, pharmaceutical tableting, paper surface sizing, and textile warp sizing applications. Maize starch occupies the dominant volume position due to abundant feedstock availability and established wet-milling infrastructure, while tapioca starch represents the fastest-expanding category driven by Southeast Asian supply base expansion and rising gluten-free formulation requirements. Food grade quality standards command the deepest margin pools as clean-label and organic certification premiums widen price spreads against technical and industrial grades.
The EPA regulates effluent discharge from corn wet milling facilities under Clean Water Act provisions, while the FDA governs food-grade starch identity standards and GRAS self-affirmation pathways. EFSA and EMA jointly influence pharmaceutical-grade starch monograph requirements across European compendial applications. Stakeholders must monitor evolving carbon border adjustment mechanisms and renewable fuel mandates that threaten to redirect corn feedstock toward ethanol production, tightening native starch raw material availability.
Market Dynamics
Clean-label formulation mandates from major food retailers are compressing ingredient approval timelines and forcing native starch suppliers to certify non-GMO and organic supply chains ahead of regulatory deadlines.
Growth Catalysts
- EU Green Deal implementation:The EU Green Deal and F-Gas Regulation are mandating lower-carbon extraction processes, creating compliant sourcing premiums for European wet-milling facilities that retrofit energy recovery systems.
- India PLI scheme incentives:Production-linked incentive schemes for food processing infrastructure are accelerating domestic maize and tapioca starch capacity buildout across Gujarat and Maharashtra processing corridors.
- Gluten-free bakery expansion:Tapioca starch demand from North American and European gluten-free formulation manufacturers is pulling Southeast Asian supply base expansion into dedicated export-grade drying facilities.
Market Restraints
- Maize feedstock competition:Renewable fuel mandates in the United States and Brazil are redirecting corn supply toward ethanol production, tightening native starch raw material availability during harvest shortfalls.
- REACH compliance concentration:European Chemicals Agency registration requirements are decoupling small-scale extractors from mainstream supply chains, consolidating procurement options for pharmaceutical-grade buyers.
- Modified starch substitution:Cross-linked and acetylated starch variants offer superior freeze-thaw stability in prepared foods, displacing native grades in cost-sensitive industrial applications.
Strategic Opportunities
- BIS certification acceleration:Bureau of Indian Standards food-grade certification requirements are creating first-mover advantages for domestic processors that achieve pharmaceutical-grade monograph alignment ahead of import substitution deadlines.
- Pea starch pharmaceutical pivot:Roquette Frères and specialized processors are expanding pea and potato starch capacity for tablet disintegration and excipient applications, capturing premium margins from EMA compendial standards.
- Carbon border positioning:Early adoption of renewable energy in extraction facilities allows European suppliers to document embedded carbon intensity ahead of EU carbon border adjustment mechanism implementation.
Industry Challenges
- Wet-milling process engineering talent:Specialized knowledge in corn and tuber starch extraction, protein separation, and effluent treatment is concentrating at legacy facilities, constraining new plant commissioning timelines.
- Organic certification traceability:Maintaining identity-preserved supply chains from farm to dried powder requires blockchain or equivalent tracking infrastructure that mid-scale processors lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Native Starch Market |
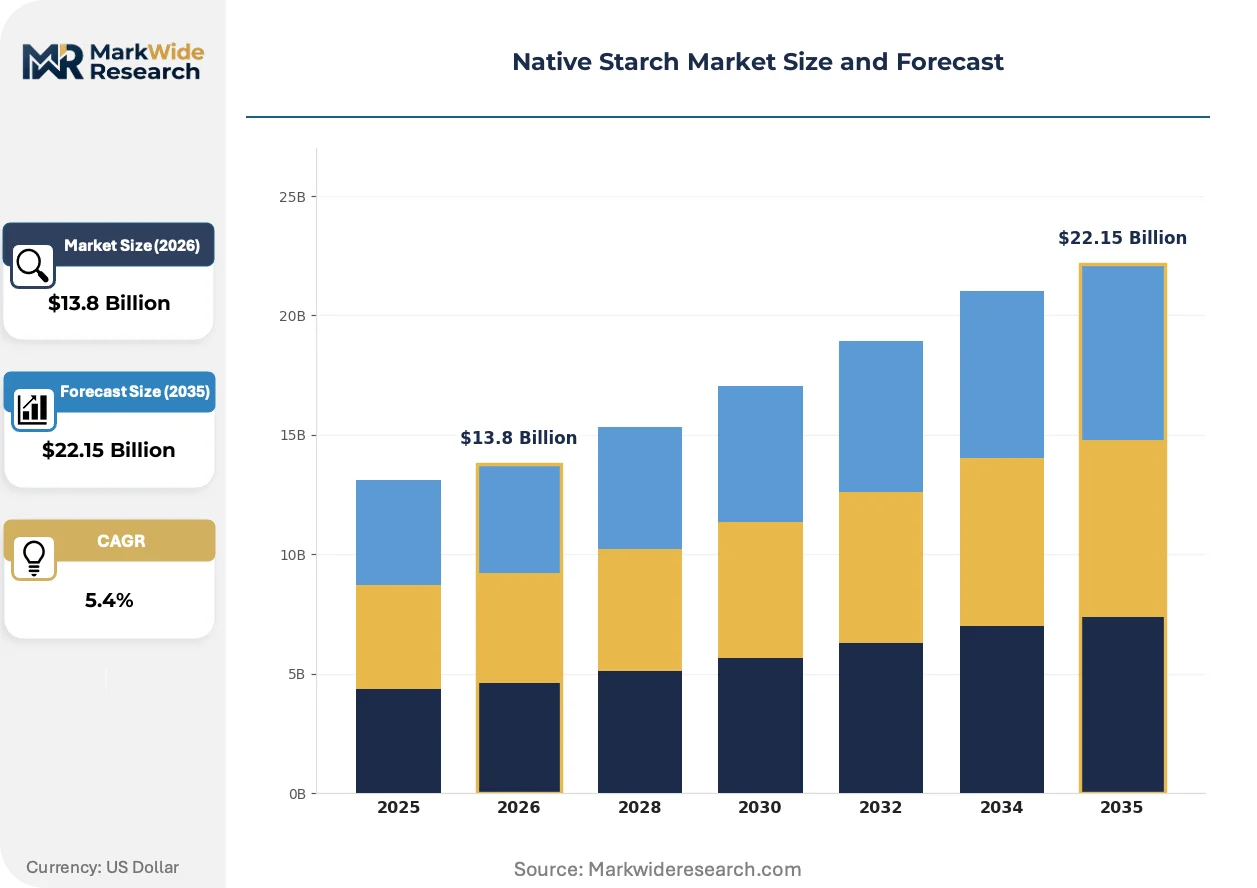
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waxy Starch, Maize Starch, Potato Starch, Tapioca Starch End Use Industry: Food & Beverage, Pharmaceuticals, Paper & Packaging, Textile Form: Granular, Powder, Liquid, Gel Quality Grade: Food Grade, Technical Grade, Industrial Grade, Pharmaceutical Grade |
| Companies Covered | Tate & Lyle PLC, Tereos Starch & Sweeteners, Archer Daniels Midland Company, Royal Avebe U.A., AGRANA Beteiligungs-AG, Cargill, Incorporated, Roquette Frères, Emsland-Stärke GmbH, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Native Starch Market Strategic Shifts & Innovations
Physical modification techniques are displacing chemical derivatization as the primary pathway for clean-label viscosity enhancement, reshaping equipment investment priorities across extraction facilities.
Pre-gelatinized native starch is absorbing demand from instant soup and sauce manufacturers seeking cold-water dispersibility without E-number labeling. Food service distributors in Germany and the Netherlands are specifying pre-gelatinized grades for reduced-hydration prepared meal systems. The technology is absorbing volume that previously flowed toward chemically modified instant starches, compressing the premium spread between native and modified categories.
REACH authorization timelines for legacy wet-milling chemicals are forcing European facilities to validate enzymatic purification alternatives ahead of 2026 sunset dates. The substitution pressure is accelerating capital deployment into membrane filtration and chromatographic separation systems. Pharmaceutical-grade maize starch monographs are tightening as EMA and national competent authorities harmonize heavy metal and microbial specification limits.
Direct-procurement relationships between clean-label food brands and identity-preserved starch processors are shortening traditional ingredient distribution channels. North American natural product retailers are requiring lot-level traceability documentation that commodity brokers cannot provide. This disintermediation is most visible in organic tapioca starch sourcing, where Thai and Vietnamese processors are building direct sales offices in California and New York metro areas.
Native Starch Market Segmentation
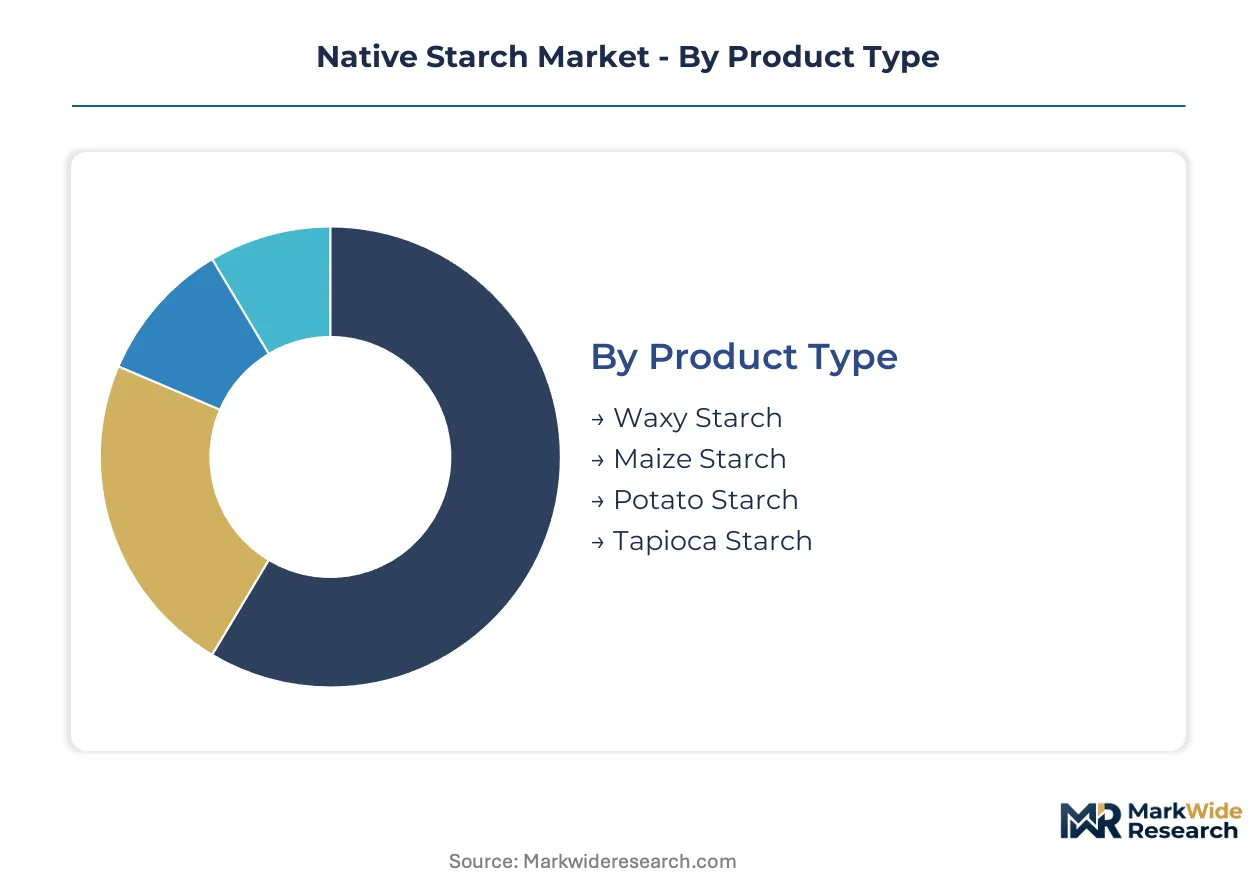
Native starch suppliers configure production assets around amylose-amylopectin ratios and purification thresholds that map directly to end-use performance requirements. Segmentation discipline separates commodity volume plays from premium-grade specialization strategies.
Product Type:
Customization intensity rises with amylopectin concentration and tuber-specific extraction complexity across this spectrum.
- Maize Starch:Standard dent corn wet-milling yields 25-28% amylose content suitable for general thickening and binding. Demand concentrates in North American prepared foods manufacturing where clean-label reformulation is displacing modified starches.
- Tapioca Starch:Cassava root extraction produces near-pure amylopectin with exceptional freeze-thaw stability and neutral flavor profiles. Southeast Asian supply corridors in Thailand and Vietnam are expanding dedicated export-grade drying capacity to serve European and North American gluten-free bakery demand.
- Waxy Starch:Specialized waxy maize varieties deliver >99% amylopectin for high-shear processing environments.
- Potato Starch:Tuber extraction yields large granule size with superior swelling power for meat analog applications.
Most installed capacity flows through Maize Starch. Expansion is steepest in Tapioca Starch.
End Use Industry:
Application-specific purity requirements create divergent margin architectures across customer verticals.
- Food & Beverage:Clean-label formulation mandates from major retailers are compressing ingredient approval timelines and forcing certification of non-GMO and organic supply chains. European and North American manufacturers are specifying identity-preserved starches with lot-level traceability documentation.
- Pharmaceuticals:Tablet disintegration and excipient applications demand compendial-grade monograph compliance with tight heavy metal and microbial specification limits. EMA harmonization efforts are tightening standards across European manufacturing.
- Paper & Packaging:Surface sizing and coating applications prioritize cost-efficient viscosity control over certification premiums.
- Textile:Warp sizing operations in India and Bangladesh consume technical-grade starches for yarn strength during weaving.
Volume concentration sits with Food & Beverage. Margin expansion is most pronounced in Pharmaceuticals.
Form:
Processing convenience and hydration kinetics determine form selection across manufacturing environments.
- Granular:Standard dried starch retains native crystalline structure for controlled gelatinization during heating. Food manufacturers in Germany and the Netherlands specify granular grades for reduced-hydration prepared meal systems requiring precise viscosity development.
- Powder:Fine-milled particle distribution accelerates dispersion in high-speed mixing equipment.
- Liquid:Suspension starches eliminate dust handling and pre-hydration steps in continuous processing lines.
- Gel:Pre-gelatinized preparations enable cold-water dispersibility for instant soup and sauce applications without E-number labeling.
Granular form dominates current throughput. Pre-gelatinized Gel formats are gaining share fastest in convenience food segments.
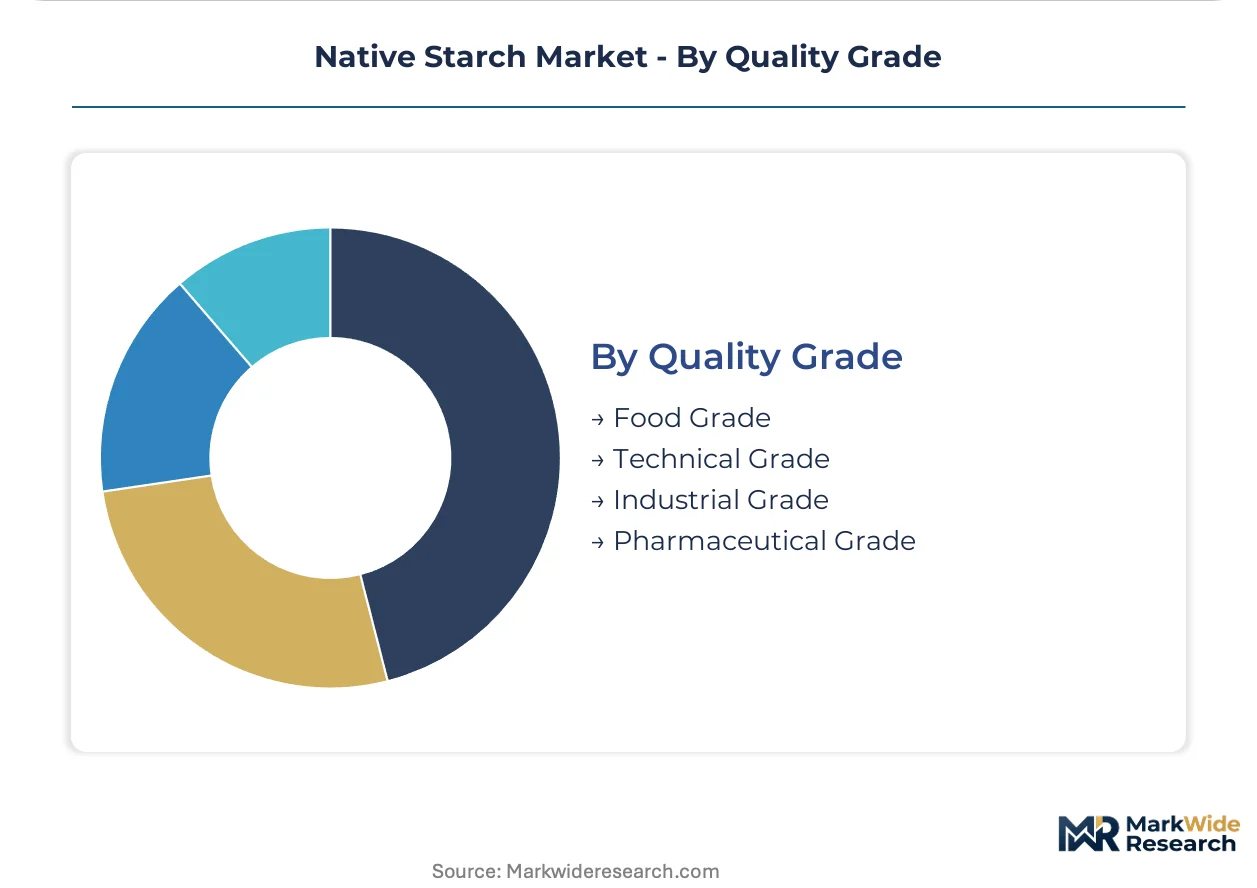
Quality Grade:
Certification tier directly governs permissible applications and achievable price realization.
- Food Grade:BIS certification requirements in India and FDA identity standards in the United States establish baseline safety and purity thresholds. Organic and non-GMO premiums are widening price spreads against conventional grades as clean-label requirements harden.
- Pharmaceutical Grade:EMA and national competent authority monographs dictate heavy metal limits, microbial specifications, and excipient functionality testing. REACH authorization timelines for legacy wet-milling chemicals are forcing validation of enzymatic purification alternatives.
- Technical Grade:Industrial applications accept broader specification ranges in exchange for volume pricing.
- Industrial Grade:Paper and textile processing utilizes basic purity starches without food-contact compliance overhead.
Food Grade commands the largest volume position. Pharmaceutical Grade delivers the steepest margin trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The native starch industry traces its modern scale to nineteenth-century European wet-milling operations along the Rhine and Maas river systems. Commercial extraction migrated to the American Midwest during the early twentieth century as hybrid corn yields transformed supply economics. Processing technology now concentrates across four major national production bases.
United States
Ethanol mandates under the Renewable Fuel Standard divert corn feedstock from starch extraction during harvest shortfalls. EPA effluent regulations under the Clean Water Act govern discharge from wet-milling facilities across Illinois and Iowa. The Corn Belt processing corridor from Decatur to Cedar Rapids anchors capacity concentration for food-grade and industrial applications.
Germany
Pharmaceutical-grade potato starch demand from EMA-compliant tablet manufacturers sustains premium pricing in Baden-Württemberg and Lower Saxony. REACH authorization timelines for legacy wet-milling chemicals force validation of enzymatic purification alternatives. The Emsland region maintains specialized extraction infrastructure for compendial-grade monograph production.
India
PLI scheme incentives accelerate domestic maize and tapioca starch capacity buildout across Gujarat and Maharashtra processing corridors. BIS certification requirements for food-grade standards create first-mover advantages for processors achieving pharmaceutical-grade alignment. The Ahmedabad-Vadodara industrial belt concentrates new drying facility investment for export-grade production.
Thailand
Gluten-free bakery expansion in North America and Europe pulls cassava root supply toward dedicated export-grade drying facilities. Thai processors build direct sales offices in California and New York metro areas to serve clean-label brand procurement. The Central Plains region from Nakhon Sawan to Kanchanaburi anchors tapioca starch extraction infrastructure.
Brazil
Renewable fuel mandates redirect corn supply toward ethanol production, tightening native starch raw material availability during seasonal constraints. ANVISA governs food-contact starch identity standards for domestic formulation manufacturers. The São Paulo state processing cluster maintains technical-grade capacity for paper and textile sizing applications.
Native Starch Market Key Industry Players
The competitive structure tilts toward integrated agribusiness conglomerates with captive feedstock supply. Wet-milling economics favor scale concentration above threshold volumes where protein separation and co-product recovery justify capital intensity. Three archetypes dominate: multinational grain processors with backward integration into corn supply, European tuber specialists with pharmaceutical-grade certification, and Asian tapioca processors with export-oriented drying infrastructure. Capacity expansion and direct-procurement channel development represent the dominant competitive vectors as clean-label brands disintermediate traditional distribution.
Among North American grain processors, Cargill, Incorporated and Archer Daniels Midland Company exemplify the integrated agribusiness archetype with Midwest wet-milling concentration. Ingredion Incorporated occupies a position within the specialty formulation tier, while Roquette Frères represents the European tuber-specialist model with pea and potato starch focus. Tate & Lyle PLC and AGRANA Beteiligungs-AG sit within the diversified ingredient portfolio segment serving multiple industrial verticals.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Tereos Starch & Sweeteners |
| Archer Daniels Midland Company |
| Royal Avebe U.A. |
| AGRANA Beteiligungs-AG |
| Cargill, Incorporated |
| Roquette Frères |
| Emsland-Stärke GmbH |
| Ingredion Incorporated |
| Others |
Cost & Logistics Intelligence
Specialized wet-milling process engineers in the American Midwest command wage premiums that compress margin spreads between pharmaceutical-grade and technical-grade native starch tiers. Labor-cost differentials between legacy Corn Belt facilities and emerging Gujarat processing corridors widen pricing arbitrage windows for food-grade buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs native starch transactions. Price differentiation rests on certification grade—organic and non-GMO premiums widen spreads against conventional grades—and volume scale with contract duration. Cost compression in technical-grade maize starch is intensifying because renewable fuel mandates redirect corn feedstock toward ethanol production. Industrial paper and textile buyers exhibit the highest price sensitivity, while pharmaceutical tablet manufacturers absorb premium spreads for EMA-compendial monograph compliance.
Supply Chain Analysis
India's PLI scheme domestic-content requirements are reshaping sourcing patterns for food-grade starch procurement. Supply concentrates in the United States, India, and Thailand, with corn wet-milling anchored in the Corn Belt and tapioca extraction clustering in Southeast Asian supply corridors. Raw material flows draw from hybrid maize seedstock, cassava root cultivation, and specialized waxy cereal varieties. Single-source vulnerability runs through Thai tapioca processors serving North American gluten-free bakery demand. Distribution runs through direct-procurement relationships that disintermediate traditional ingredient brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The native starch market represents a late-cycle quality story as clean-label formulation mandates from European and North American retailers harden specifications toward identity-preserved, lot-traceable supply chains.
For Market Incumbents: Deploy backward integration into captive corn feedstock supply to defend against ethanol mandate-driven raw material competition. Cargill and Archer Daniels Midland should accelerate pharmaceutical-grade monograph alignment ahead of EMA harmonization deadlines. Channel control through direct sales office buildout in California and New York metro areas counters disintermediation pressure from clean-label brands. For New Entrants and Emerging Players: Membrane filtration and enzymatic purification technology offers entry pathways around REACH-authorized chemical sunset constraints. White-space targets include BIS-certified pharmaceutical-grade capacity in Gujarat and Maharashtra corridors, and organic tapioca starch identity-preserved supply chains for European gluten-free manufacturers. Go-to-market positioning should emphasize blockchain-enabled lot traceability that commodity brokers cannot replicate. For Investors and Strategic Acquirers: Integrated food-ingredient conglomerates are the most active acquirers in this space, seeking tuber-specialist capabilities for pharmaceutical-grade diversification. Long-term viability hinges on carbon-border-adjustment positioning and renewable energy adoption in extraction facilities. Acquisition targets should display pharmaceutical-grade monograph alignment and direct-procurement channel development. The signal to watch is EU carbon border adjustment mechanism implementation timelines affecting embedded carbon intensity documentation requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Monograph Alignment | EMA harmonization efforts tighten heavy metal and microbial specifications for tablet excipient applications. |
| Direct-Procurement Channel Development | Thai and Vietnamese processors build California sales offices to serve clean-label brand sourcing requirements. |
| Renewable Energy Adoption in Extraction | European facilities document embedded carbon intensity ahead of EU carbon border adjustment mechanism implementation. |
| Identity-Preserved Supply Chain Infrastructure | Blockchain-enabled lot traceability meets North American natural product retailer documentation mandates. |
| Enzymatic Purification Technology Deployment | REACH authorization timelines for legacy wet-milling chemicals force membrane filtration capital deployment. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Wet-milling plant managers, procurement leads at food and pharmaceutical manufacturers, distribution channel partners, and technical R&D directors provided operational perspectives. Secondary sources include customs and trade data, SEC filings from publicly traded processors, EMA and FDA regulatory submissions, and BIS certification records. Bottom-up capacity and utilization estimates triangulate against top-down demand segmentation across end-use industries.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon. The analytical framework models product type, quality grade, end-use industry, and form dimensions alongside regional production hub clustering. CAGRs derive from segment-level demand elasticity analysis and capacity expansion timelines. Forecast inputs incorporate corn feedstock competition from renewable fuel mandates and gluten-free bakery demand pull from North American and European formulation manufacturers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU carbon border adjustment implementation, ethanol mandate revisions, and REACH authorization timeline shifts. Forecasts reflect documented assumptions around feedstock availability, regulatory compliance costs, and clean-label certification premium sustainability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Fats and Oils Market
Ingredients
Karaya Gum Market
Ingredients
Diastatic Malt Market
Ingredients
Cocoa Derivatives Market
Ingredients
Cooking Oils and Fats Market
Ingredients
Coconut Flour Market
Ingredients
Glucosylglycerol Market
Ingredients
Europe Plant Protein Ingredients Market
Ingredients
Red Orange Anthocyanin Extract Ingredients Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Sunflower Meal Market
Ingredients
Calendula Oil Market
Ingredients
Carotenoids Market
Ingredients
Asia-Pacific Gelatin Market
Ingredients
Fruit Pectin Market
Ingredients
Tuberose Extract Market