
 Dehydrated Beets Market | 2026-2036
Dehydrated Beets Market Size, Share, and Industry Trends Forecast 2026-2036
Dehydrated Beets Market Analytics
Specialized dehydration technician availability is collapsing across beet processing hubs, forcing manufacturers to automate or relocate. BATA FOOD leverages its Turkish sourcing network to sustain year-round raw material flows. Silva International anchors North American supply through controlled-atmosphere drying infrastructure. Paradise Fruits Solutions Gmbh differentiates via precision-cut flake geometries for premium bakery accounts.
Dehydrated beets are root vegetables processed through hot-air, freeze, or drum drying to moisture levels below 10 percent, preserving betalain pigments, dietary fiber, and natural sugars for shelf-stable food and nutraceutical applications. Powder formats dominate volume due to solubility advantages in beverage and supplement matrices, while flake and chip segments capture margin pools from artisan snack and garnish channels. Food processing end-use leads absolute consumption, though pharmaceutical-grade specifications for nitrate extraction are tightening and redirecting some premium powder supply.
FDA color additive regulations and EFSA novel food assessments shape formulation compliance costs on both sides of the Atlantic, while India's FSSAI is tightening contaminant thresholds for imported dehydrated vegetable ingredients. USDA organic certification and EU organic regulation create parallel qualification tracks that segment supplier tiers. Stakeholders must monitor how diverging nitrate-level standards between pharmaceutical and food-grade specifications reshape contract manufacturing priorities.
Market Dynamics
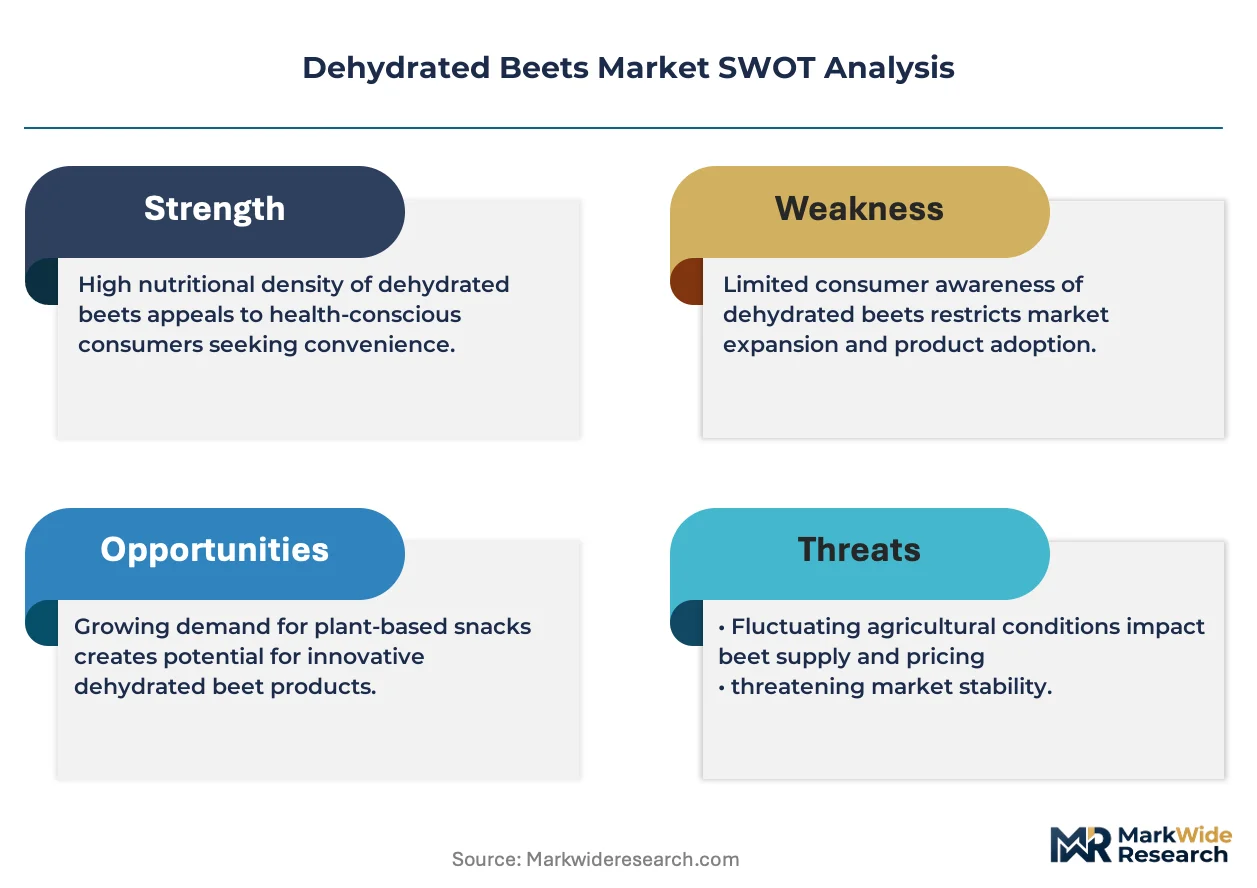
Dehydrated beet processing is bifurcating between pharmaceutical-grade nitrate extraction and clean-label food colorant applications, with FDA's updated color additive guidance forcing manufacturers to retool quality systems or exit food-grade supply entirely.
Growth Catalysts
- Plant-based meat formulation:Food processors are absorbing beet powder volumes as natural binders replace synthetic hydrocolloids in burger and sausage analogues.
- EU organic regulation:Parallel qualification tracks for EU organic certification are segmenting supplier tiers and creating premium price pools for compliant Central European processors.
- Freeze-drying infrastructure:Controlled-atmosphere drying technology is preserving betalain pigment integrity for nutraceutical applications demanding pharmaceutical-grade specifications.
Market Restraints
- Specialized technician scarcity:Dehydration operator availability is collapsing across beet processing hubs, forcing automation capital deployment or geographic relocation.
- Turkish raw material concentration:Year-round beet supply depends on Turkish sourcing networks, exposing processors to regional climate volatility and currency fluctuation.
- Pharmaceutical-food grade divergence:Tightening nitrate-level standards between pharmaceutical extraction and food-grade specifications are redirecting premium powder supply and compressing food-grade margins.
Strategic Opportunities
- Indian FSSAI threshold alignment:Tightening contaminant standards for imported dehydrated vegetables are creating first-mover advantage for processors investing in HACCP-plus certification.
- Precision-cut flake geometries:Bakery and artisan snack channels are absorbing premium flake formats with defined particle size distributions for visual garnish applications.
- Solubility-optimized powder grades:Beverage and supplement matrices are demanding ultra-fine beet powder with enhanced dispersibility, commanding formulation service premiums.
Industry Challenges
- Dehydration automation capex intensity:Technician scarcity is forcing processor investment in continuous belt dryers and optical sorting systems requiring seven-figure capital commitments.
- Dual certification timeline compression:USDA organic and EU organic parallel qualification tracks are extending product launch cycles by 8-14 months for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehydrated Beets Market |
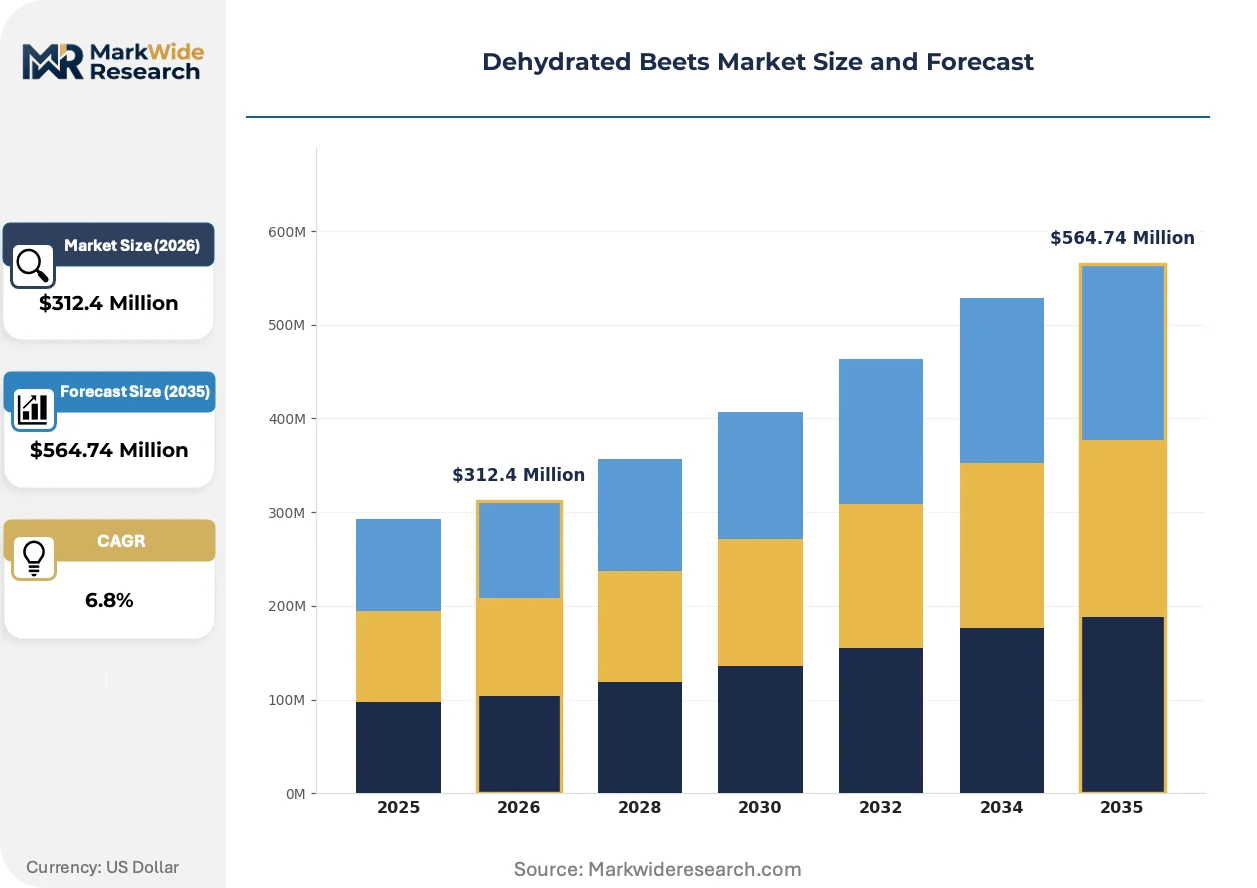
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diced, Powder, Flakes, Chips End Use Industry: Food Processing, Cosmetics, Pharmaceuticals, Agriculture Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales Packaging Type: Bags, Bottles, Jars, Bulk Containers |
| Companies Covered | BATA FOOD, Silva International, Paradise Fruits Solutions Gmbh, DMH Ingredients, NutraDry, Cultivator Natural Products, Inspired Ingredients, Herbafood Ingredients Gmbh, Saipro Biotech Private Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehydrated Beets Market Evolving Landscape
Dehydrated beet processing is experiencing technology-driven quality stratification, with precision drying methods separating pharmaceutical-grade from commodity food-grade supply and reshaping competitive positioning across extraction and colorant end-uses.
Controlled-atmosphere freeze drying is decomposing the traditional hot-air drying monopoly in premium beet powder production. Nutraceutical extractors are adopting lyophilization infrastructure to preserve nitrate bioavailability for cardiovascular supplement formulations. This technology shift is compressing commodity processor margins while enabling pharmaceutical-grade price premiums.
EFSA novel food assessments are tightening documentation requirements for beet-derived ingredients entering European supplement channels. Manufacturers must now submit comprehensive toxicology dossiers for betalain concentrates exceeding standardized use levels. German and Dutch processors are responding by vertically integrating clinical trial capabilities to accelerate regulatory clearance timelines.
Direct-procurement contracts between beet processors and plant-based meat formulators are displacing traditional ingredient distributor channels. Large-scale meat analogue manufacturers are establishing annual volume commitments with specified pigment stability metrics. This channel consolidation is most visible in North American and German markets where clean-label formulation mandates are strictest.
Dehydrated Beets Market Segmentation
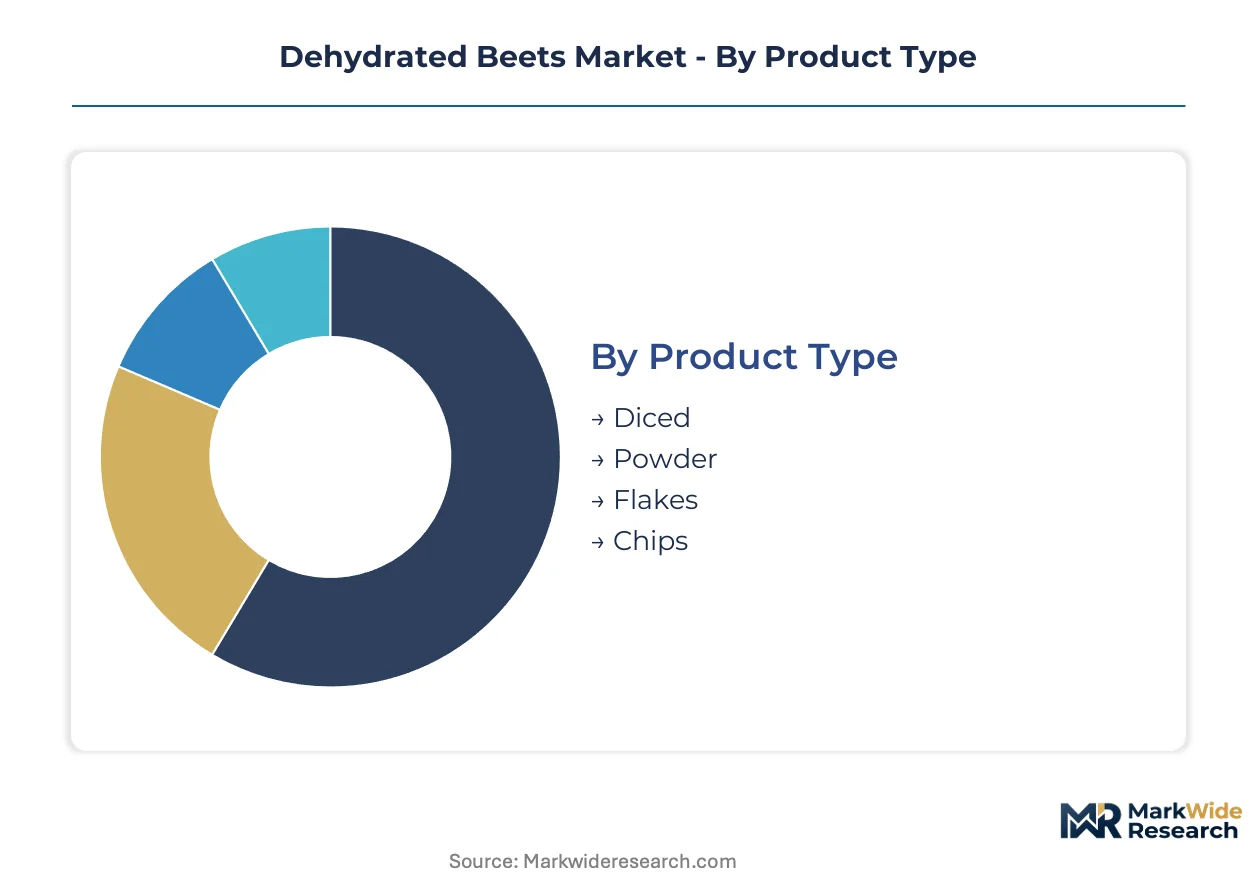
Channel dynamics in dehydrated beets vary sharply by physical format and end-use specification. Powder and flake segments flow through divergent distribution pathways, while pharmaceutical-grade requirements impose distinct packaging and handling protocols that reshape supplier economics.
Product Type:
Powder and flake formats dominate commercial volume through separate channel structures, with powder concentrating in ingredient supply chains and flakes capturing premium retail placement.
- Powder:Ultra-fine particle distribution below 100 microns enables complete solubility in beverage and supplement matrices. Plant-based meat formulators in Germany and the United States absorb the largest powder volumes as FDA color additive guidance tightens synthetic hydrocolloid replacement timelines.
- Flakes:Precision-cut geometries with defined thickness tolerances serve artisan bakery and premium garnish applications. Paradise Fruits Solutions Gmbh anchors Central European flake supply through controlled cutting infrastructure that preserves betalain visual integrity.
- Diced:Intermediate particle size for rehydration-dependent foodservice applications, flowing primarily through direct sales channels to institutional kitchens.
- Chips:Whole-root cross-sections positioned in health-oriented retail, packaged in nitrogen-flushed bags to prevent pigment oxidation during shelf storage.
By volume, Powder leads. By margin expansion, Flakes is gaining share fastest.
End Use Industry:
Application concentration determines specification tiers, with pharmaceutical extraction demanding nitrate-content certification that food-grade processors cannot economically match.
- Food Processing:Natural colorant and binder absorption in plant-based meat analogues drives absolute consumption. Clean-label mandates from major North American and German formulators are redirecting synthetic dye volumes toward beet-derived alternatives.
- Pharmaceuticals:Nitrate extraction for cardiovascular supplement formulations requires lyophilization infrastructure and EFSA novel food dossier compliance. Freeze-dried pharmaceutical-grade supply commands price multiples over commodity food-grade powder.
- Cosmetics:Betalain pigment incorporation into natural color cosmetics, primarily through direct procurement from certified organic processors.
- Agriculture:Soil amendment and animal feed applications absorbing lower-grade material with relaxed contaminant thresholds.
Food Processing generates the largest absolute revenue. Pharmaceuticals delivers the steepest expansion trajectory.
Distribution Channel:
Channel selection correlates directly with buyer scale and specification complexity, fragmenting supplier relationships across divergent service requirements.
- Direct Sales:Annual volume commitments with specified pigment stability metrics dominate plant-based meat and pharmaceutical extraction procurement. Large-scale manufacturers bypass distributor markups through captive supply agreements.
- Online Retail:Solubility-optimized powder grades and premium flake formats reach supplement consumers and artisan bakers through specialized ingredient platforms.
- Supermarkets:Pre-packaged chips and standard powder SKUs compete on shelf placement and nitrogen-flush packaging visibility.
- Health Stores:Organic-certified products with USDA or EU organic logos command placement premiums in specialized retail.
Direct Sales captures the highest volume throughput. Online Retail shows the most rapid channel expansion.
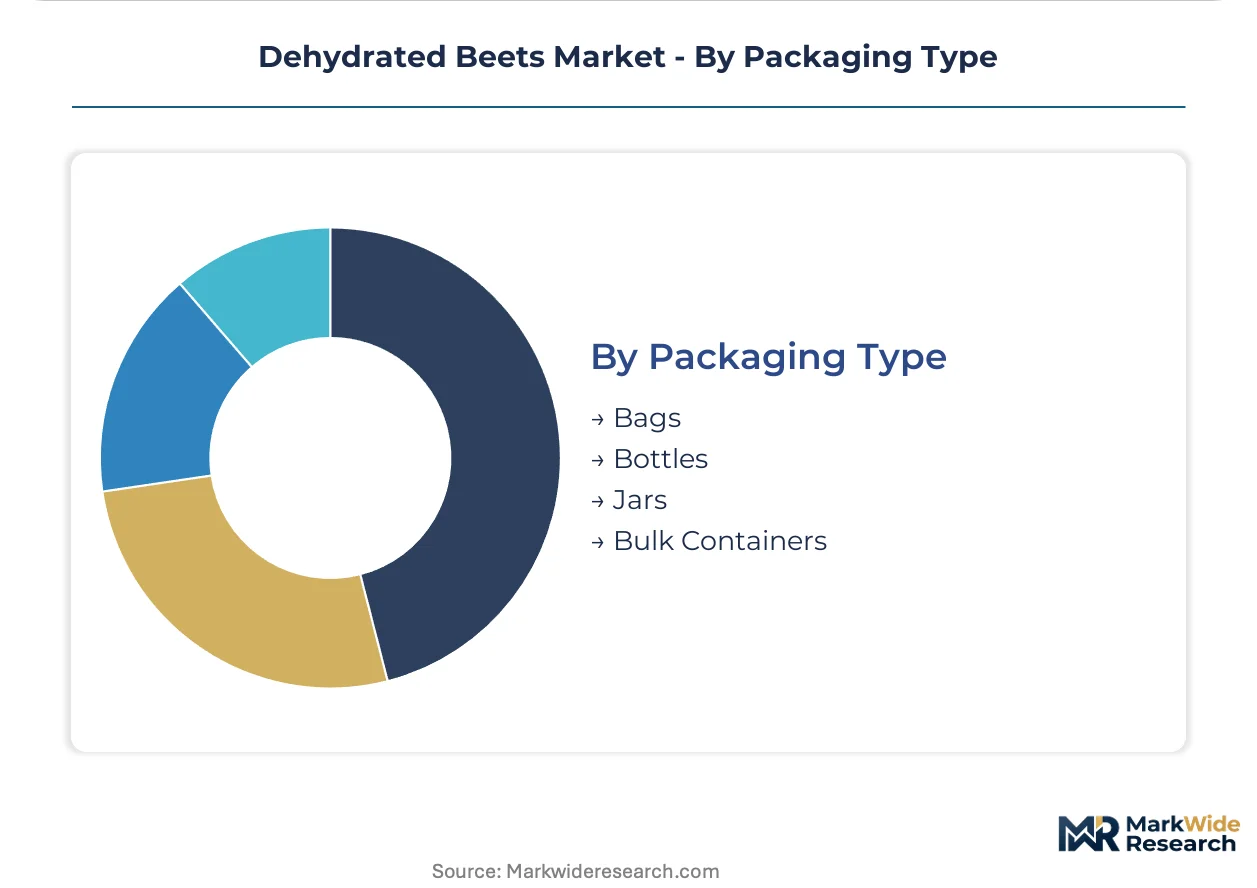
Packaging Type:
Packaging configuration protects betalain integrity across divergent shelf-life requirements, with pharmaceutical and export applications demanding oxygen-barrier specifications that inflate unit economics.
- Bulk Containers:Foodservice and industrial ingredient supply flows through lined fiber drums with nitrogen backflushing, minimizing per-kilogram packaging cost for high-volume buyers.
- Bags:Multi-layer laminate structures with oxygen scavengers protect retail flake and chip formats through 18-month shelf targets.
- Bottles:Supplement-grade powder distribution favors HDPE containers with desiccant inserts for moisture control in humid climates.
- Jars:Premium cosmetic and gift-oriented SKUs utilize glass with UV-blocking tint to prevent betalain photodegradation.
Bulk Containers move the greatest tonnage. Bags deliver the widest SKU proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA color additive guidance anchors United States regulatory pressure, while EFSA novel food assessments and India's FSSAI contaminant thresholds create parallel compliance tracks across three distinct jurisdictions.
United States
Plant-based meat formulators in Chicago and Los Angeles absorb beet powder volumes as synthetic hydrocolloid replacement accelerates. FDA's updated clean-label color additive guidance forces manufacturers to retool quality systems or exit food-grade supply entirely. Silva International anchors North American supply through controlled-atmosphere drying infrastructure in the Midwest.
Germany
EU organic regulation creates premium price pools for compliant Central European processors serving bakery and nutraceutical channels. EFSA novel food dossier requirements tighten documentation for betalain concentrates entering supplement markets. Paradise Fruits Solutions Gmbh and Herbafood Ingredients Gmbh concentrate precision-cut flake production in Baden-Württemberg and Bavaria.
India
FSSAI tightening of contaminant thresholds for imported dehydrated vegetables redirects procurement toward HACCP-plus certified domestic processors. Pharmaceutical-grade nitrate extraction for cardiovascular supplements drives lyophilization investment in Maharashtra and Gujarat. Cultivator Natural Products and Saipro Biotech Private Ltd. occupy positions within the domestic supplier tier.
Turkey
Year-round raw material flows depend on Turkish sourcing networks, exposing processors to regional climate volatility and currency fluctuation. BATA FOOD leverages its Anatolian beet cultivation contracts to sustain continuous supply for European and Middle Eastern buyers. Izmir and Konya processing clusters specialize in hot-air drying for commodity food-grade powder.
Netherlands
Rotterdam and Eindhoven logistics hubs facilitate re-export of pharmaceutical-grade beet powder to Nordic and British supplement manufacturers. REACH compliance infrastructure supports EFSA-aligned toxicology dossier preparation for novel food clearance. Dutch traders occupy intermediary positions between Turkish raw material sources and German precision-processing specialists.
Dehydrated Beets Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the dehydrated beets supply base. The market structure fragments across three tiers: pharmaceutical-grade lyophilization specialists, clean-label food-grade precision processors, and commodity hot-air drying operators. Strategic archetypes include freeze-drying technology licensors, organic-certified Central European processors, and Turkish-integrated raw material aggregators. Dominant competitive moves center on backward integration into beet cultivation contracts and geographic relocation to escape technician scarcity in traditional processing hubs.
Among Turkey-integrated aggregators, BATA FOOD exemplifies raw material security through captive Anatolian sourcing. German precision processors Paradise Fruits Solutions Gmbh and Herbafood Ingredients Gmbh occupy positions within the EU organic certification tier, representing the premium-standard segment where flake geometry and pigment stability command formulation service premiums.
| Leading Market Players |
|---|
| BATA FOOD |
| Silva International |
| Paradise Fruits Solutions Gmbh |
| DMH Ingredients |
| NutraDry |
| Cultivator Natural Products |
| Inspired Ingredients |
| Herbafood Ingredients Gmbh |
| Saipro Biotech Private Ltd. |
| Others |
Value Network & Pricing Analysis
EU organic regulation gates both supplier qualification and price differentiation simultaneously, segmenting Central European processors into premium certification tiers while Turkish commodity operators compete on raw material cost. Pharmaceutical-grade lyophilization commands multiples over hot-air dried food-grade powder as FDA color additive guidance tightens formulation compliance thresholds.
Pricing Analysis
German flake premiums exceed Turkish commodity powder by substantial spreads as Paradise Fruits Solutions Gmbh and Herbafood Ingredients Gmbh capture formulation service premiums through precision-cut geometries. Three-tier pricing structure across pharmaceutical-grade, EU organic-certified, and conventional commodity levels segments buyer budgets by application stringency. Cost compression in conventional hot-air dried tiers intensifies because Turkish currency volatility and climate exposure inflate raw material uncertainty. Plant-based meat formulators show least price sensitivity due to clean-label mandates, while foodservice distributors absorb conventional powder with tight procurement controls.
Supply Chain Analysis
Inventory cycles stretch 8-14 months for dual USDA-EU organic certification as parallel qualification tracks extend product launch timelines. Raw material flows draw from Turkish Anatolian cultivation contracts, German precision-processing clusters, and Indian lyophilization investments in Maharashtra and Gujarat. Betalain pigment stability, nitrate-content certification, and optical sorting equipment constitute critical input dependencies. Single-source vulnerability concentrates in Turkish year-round supply exposure to regional drought and lira fluctuation. Distribution runs through direct procurement contracts between processors and plant-based meat manufacturers, displacing traditional ingredient distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dehydrated beet processing fragments across pharmaceutical extraction, clean-label food colorant, and commodity agriculture applications, with plant-based meat formulation mandates creating premium niches for certified organic supply.
For Market Incumbents: Fortify lyophilization infrastructure against pharmaceutical-grade margin compression as EFSA novel food dossier requirements extend clearance timelines. Deepen backward integration into Anatolian beet cultivation contracts to escape Turkish raw material concentration risk. Lock annual volume commitments with North American plant-based meat formulators before second-tier processors achieve USDA organic certification. For New Entrants and Emerging Players: Lead with HACCP-plus certification alignment to capture Indian FSSAI tightening of import contaminant thresholds before established European suppliers redirect capacity. Target Maharashtra and Gujarat processing clusters where domestic pharmaceutical-grade nitrate extraction demand outpaces lyophilization capacity. Deploy solubility-optimized powder grades through specialized ingredient platforms serving supplement formulators. For Investors and Strategic Acquirers: FDA's updated color additive guidance reshapes the acquisition landscape by forcing food-grade quality system retooling that smaller commodity processors cannot finance. Five-to-ten year viability favors freeze-drying technology licensors and EU organic-certified precision processors over hot-air drying operators facing automation capex intensity. Monitor German-Dutch clinical trial integration capabilities as signal for EFSA novel food clearance velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Contracts | BATA FOOD's Anatolian sourcing network secures year-round raw material continuity against climate volatility. |
| Freeze-Drying Infrastructure Deployment | Silva International's controlled-atmosphere drying preserves betalain integrity for pharmaceutical-grade nitrate extraction. |
| Dual Organic Certification Investment | Paradise Fruits Solutions Gmbh's EU organic qualification opens premium bakery and nutraceutical price pools. |
| Precision-Cut Flake Geometry Development | Herbafood Ingredients Gmbh's defined thickness tolerances command formulation service premiums from artisan channels. |
| HACCP-Plus Certification Alignment | Cultivator Natural Products' domestic Indian processing captures FSSAI import threshold tightening advantage. |
Research Methodology
Initial hypotheses were tested against primary input from dehydration plant managers, plant-based meat formulators, regulatory affairs specialists at EFSA and FDA, and pharmaceutical extraction procurement leads, then refined through secondary validation against customs trade data, USDA organic certification databases, SEC filings of listed ingredient processors, and EFSA novel food assessment registers. Bottom-up volume modeling triangulated against top-down market sizing across powder, flake, diced, and chip formats.
Variance decomposition across product type, end-use specification tier, distribution channel structure, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating lyophilization capacity expansion timelines, plant-based meat analogue adoption curves, and pharmaceutical nitrate extraction demand elasticity. Forecast inputs included Turkish beet cultivation yield volatility and EFSA novel food dossier approval velocity.
The analysis sits within stated boundaries; outcomes outside sustained clean-label mandate enforcement or Turkish supply continuity would require recalibration. Forecasts reflect documented assumptions about regulatory timeline compression and automation capital deployment rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Maqui Berries Market
Fruits and Vegetables
Gold Kiwifruit Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Colombia Fruits and Vegetables Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Canned Fruits and Vegetables Market
Fruits and Vegetables
Fava Beans Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Global Pickle Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market
Fruits and Vegetables
Peaches and Nectarines Market
Fruits and Vegetables
Coconut Products Market
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
Mango Puree Market