
 Insect-Based Ingredients Market | 2026-2036
Insect-Based Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Insect-Based Ingredients Market Foresight
Pet food manufacturers is rebalancing toward insect protein inclusion as conventional fishmeal costs fluctuate and sustainability commitments harden. Innovafeed leverages vertical integration from larvae cultivation to oil extraction, sustaining cost advantages across its French operations. Protix anchors European supply through its Netherlands-based industrial bioconversion facility, the largest of its kind on the continent. Ynsect competes on species diversification, specializing in mealworm-derived proteins for high-value aquaculture and companion animal segments.
Insect-based ingredients comprise processed derivatives—protein powders, lipids, and chitin—extracted through controlled rearing, mechanical separation, drying, and milling of farmed insect biomass, serving primarily as alternative protein and functional inputs for feed, food, and agricultural applications. Protein powders dominate current output volumes, though oils command premium pricing in aquaculture and cosmetics due to their fatty acid profile. Animal feed absorbs the majority of present tonnage, while human food and nutraceutical applications accelerate fastest where Novel Food authorizations have cleared. Mealworms and black soldier fly larvae occupy distinct supply tiers, with the former penetrating higher-margin food-grade channels and the latter scaling efficiently for bulk feed.
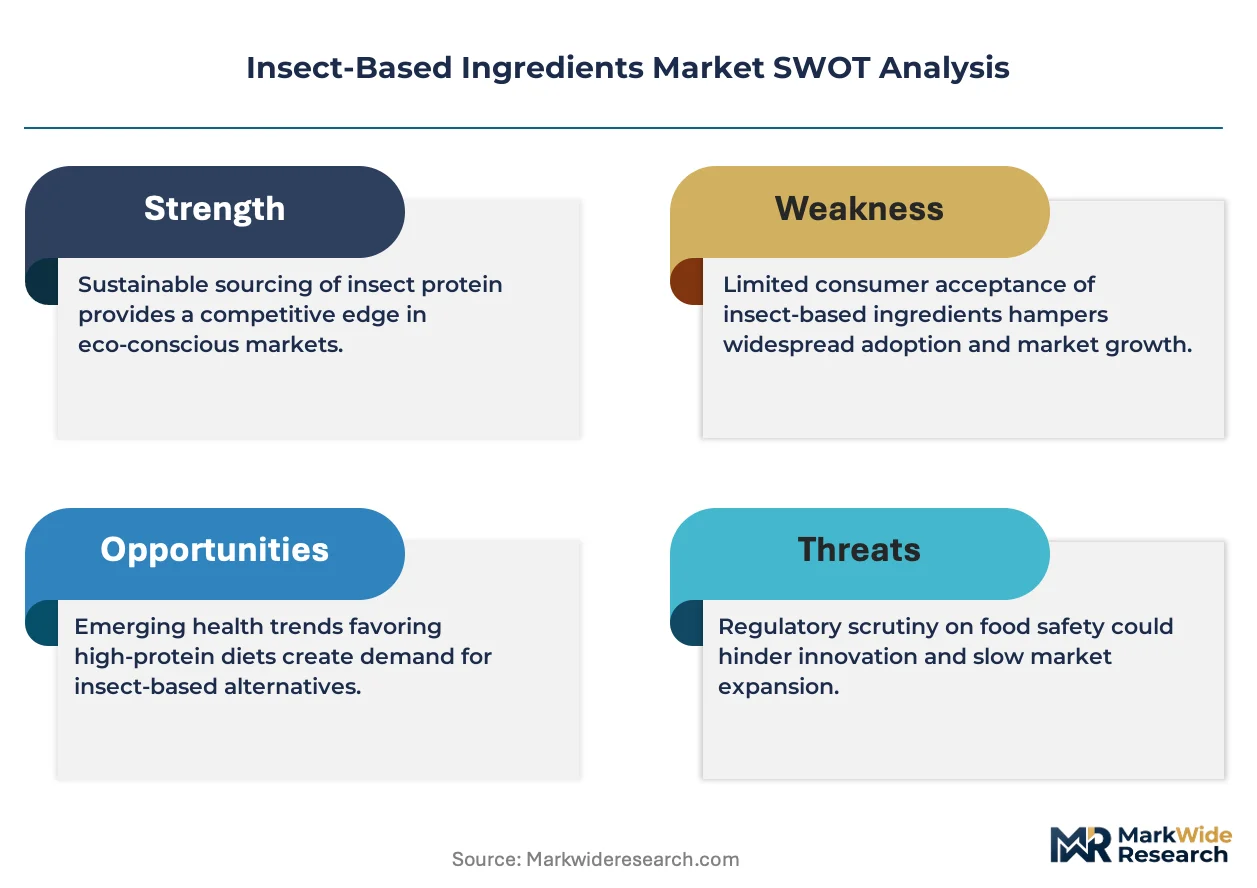
The European Food Safety Authority evaluates species-specific dossiers under the EU Novel Food framework, while the FDA exercises enforcement discretion over insect ingredients marketed in the United States, creating divergent compliance burdens that fragment market access timelines. BIS in India and other national regulators are developing safety standards for insect farming that will determine which exporters qualify for emerging import markets. Stakeholders must track regulatory synchronization between feed-grade and food-grade approval pathways, as the gap between these designations determines where margin pools materialize first.
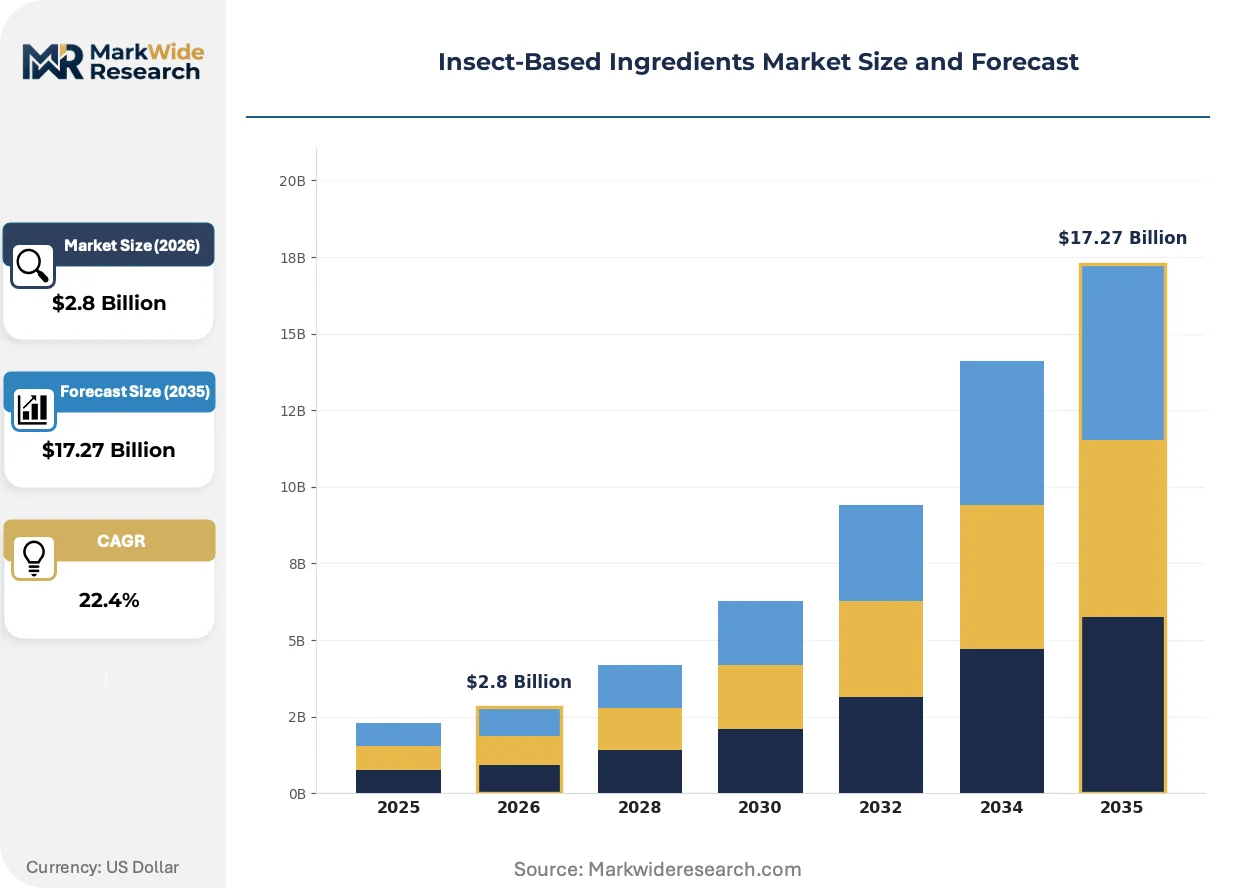
Market Dynamics
The EU Novel Food Regulation is compressing approval timelines for human-grade insect proteins while feed-grade channels absorb current capacity, creating a bifurcated expansion pattern across production networks.
Growth Catalysts
- ESG-linked procurement mandates:European aquafeed buyers now require deforestation-free protein certification, accelerating black soldier fly inclusion in salmon and trout formulations.
- France's national protein sovereignty plan:Public funding for domestic insect farming infrastructure is expanding larval rearing capacity near existing oilseed processing clusters.
- Mechanical separation advances:Continuous centrifugation systems are reducing protein recovery costs by half, enabling price parity with soy concentrate in select feed applications.
Market Restraints
- Input cost volatility:Organic waste substrate prices fluctuate with agricultural commodity cycles, squeezing margin predictability for larvae cultivators.
- Regulatory friction:The EU Novel Food framework requires 18-24 month dossier reviews per species, delaying human-food market entry beyond feed-grade revenue timelines.
- Substitution threat:Precision-fermented single-cell proteins from companies like Perfect Day and Motif FoodWorks are capturing premium positioning in companion animal nutrition.
Strategic Opportunities
- Underpenetrated geography:Germany's federal states lack production density despite housing Europe's largest pet food manufacturing base, creating procurement localization potential.
- Regulatory tailwind:The EU Green Deal's protein diversification targets are channeling CAP subsidies toward insect farm establishment in former livestock regions.
- Technology convergence:AI-driven climate control and computer-vision sorting are unifying precision agriculture methods with bioconversion operations, reducing labor intensity.
Industry Challenges
- Talent scarcity in entomology operations:Industrial-scale larvae management requires specialized expertise absent from conventional agriculture training programs.
- Capex intensity of bioconversion facilities:Climate-controlled rearing halls and automated harvesting equipment demand upfront investment exceeding comparable aquaculture infrastructure.
- Certification timeline compression:Dual-track approvals for feed-grade and food-grade outputs force parallel compliance investments before revenue diversification materializes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insect-Based Ingredients Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $17.27 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Oils, Snacks, Feed Ingredients Application: Animal Feed, Human Food, Nutraceuticals, Fertilizers Insect Species: Mealworms, Crickets, Black Soldier Fly, Grasshoppers Form: Whole, Dried, Powdered, Extracts |
| Companies Covered | Innovafeed, Protix, EnviroFlight, Ynsect, Sentara Group, Entobel, Aspire Food Group, Nutrition Technologies, AgriProtein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insect-Based Ingredients Market Shifts & Advancements
Automation and regulatory clarity are converging to transform insect farming from artisanal operations into industrial biomanufacturing, with implications spanning protein extraction efficiency and market access velocity.
Continuous-flow larvae rearing systems are unifying climate control, feeding automation, and harvest timing into single-process platforms. Dutch engineering firms are deploying these integrated units across Belgium and the Netherlands. The technology is compressing capital requirements per ton of protein output while standardizing quality metrics for downstream buyers.
EFSA's species-by-species safety evaluations under the EU Novel Food framework are creating segmented approval pathways. Mealworm and cricket dossiers have cleared human consumption, while lesser mealworm and housefly applications remain under review. Food manufacturers in France and Belgium are reformulating with authorized species while awaiting portfolio expansion.
Direct contracting between insect protein suppliers and premium pet food brands is displacing spot-market purchasing. Mars Petcare and Nestlé Purina are negotiating multi-year offtake agreements with French and Dutch producers. This pattern concentrates procurement power with vertically integrated cultivators possessing certified food-grade capacity.
Insect-Based Ingredients Market Segmentation
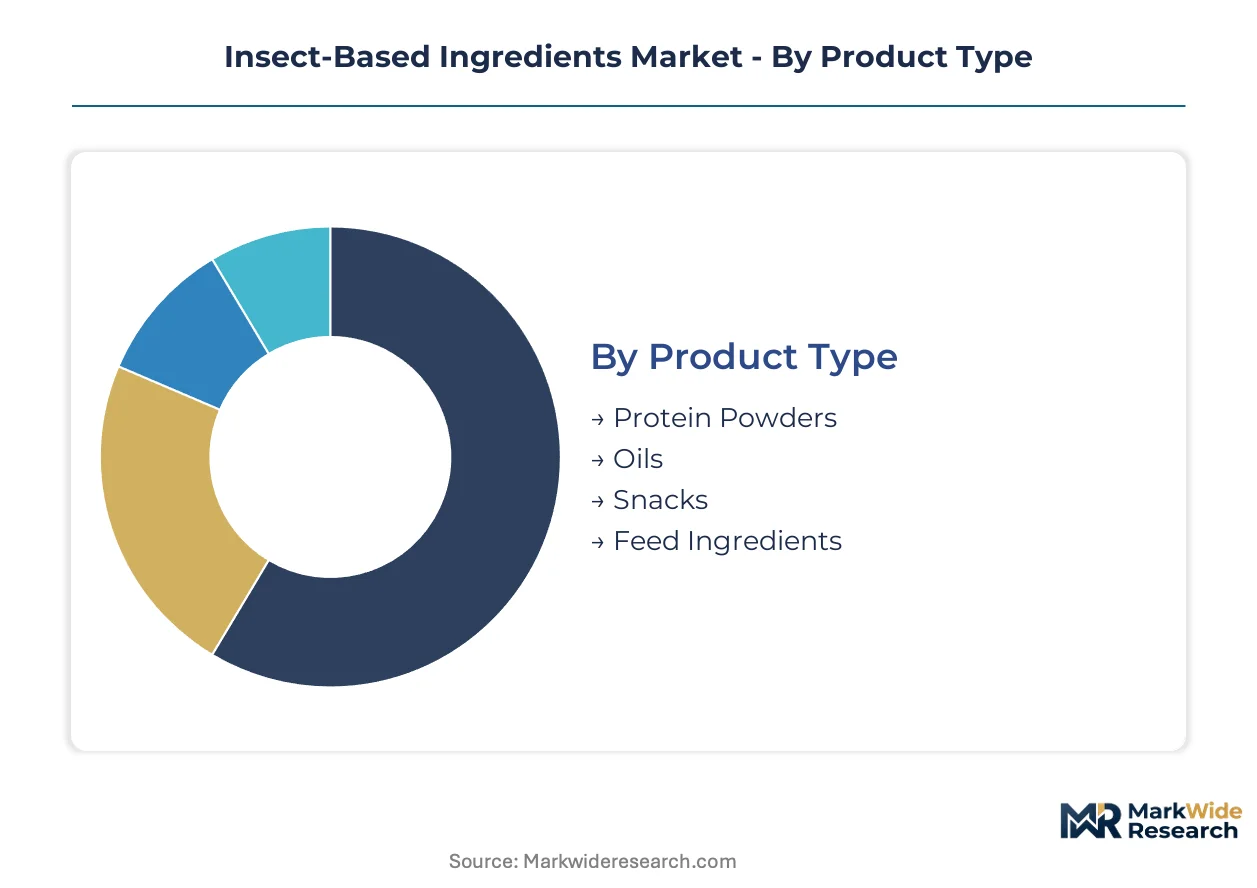
Segmentation in insect-based ingredients reflects divergent margin structures across feed-grade and food-grade channels, with regulatory approval status determining which product categories absorb capital investment first. Manufacturers configure production lines around species-specific bioconversion parameters and end-use certification requirements.
Product Type:
Upgrade cycles in insect ingredient processing follow regulatory clearance sequencing, with food-grade authorizations triggering capital redeployment from feed-only output toward higher-margin human consumption formats.
- Protein Powders:Concentrated protein isolates achieve 60-80% protein content through mechanical separation and drying of larvae biomass. Aquafeed manufacturers in Norway and Scotland specify these powders for salmonid diets to meet marine ingredient reduction targets. EFSA authorization for mealworm and cricket powders has unlocked human-grade procurement from sports nutrition brands.
- Oils:Lipid fractions extracted via solvent or mechanical pressing contain lauric acid concentrations exceeding 40% in black soldier fly derivatives. Cosmetics formulators in France and pet food manufacturers in Germany compete for limited food-grade oil volumes, with fatty acid profile specificity driving contract premiums.
- Snacks:Whole roasted or extruded consumer products require Novel Food dossier clearance per species. Belgian and Dutch retailers stock authorized formats while awaiting portfolio expansion from pending EFSA reviews.
- Feed Ingredients:Unfractionated dried larvae meals serve bulk aquaculture and poultry operations. Dutch producers supply tonnage to European shrimp and trout farms under deforestation-free procurement mandates.
Feed Ingredients sits at the top of the volume ranking, with Oils climbing the fastest.
Application:
Cost tier stratification separates commodity feed absorption from premium food and nutraceutical positioning, with certification overhead creating margin cliffs between adjacent categories.
- Animal Feed:Aquaculture and poultry operations consume the majority of current insect protein output, with salmon feed manufacturers in Norway and trout producers in Denmark specifying black soldier fly meal at 10-30% inclusion rates. ESG-linked procurement mandates from European retailers are hardening volume commitments.
- Human Food:Novel Food authorization under EU Regulation 2015/2283 gates market access, with mealworm and cricket powders cleared for bakery, pasta, and sports nutrition applications. French food manufacturers lead reformulation activity.
- Nutraceuticals:Chitin-derived glucosamine and antimicrobial peptides target dietary supplement channels. Premium positioning depends on organic certification and species-specific bioactive documentation.
- Fertilizers:Frass and exuviae from larvae rearing operations provide nitrogen-rich soil amendments. Dutch greenhouse operators integrate these outputs into circular production models.
Animal Feed commands the dominant share of current tonnage, while Human Food applications are expanding most quickly where regulatory clearance has preceded.
Insect Species:
Volume concentration and margin potential split across species lines, with rearing efficiency and regulatory approval status determining commercial deployment sequencing.
- Black Soldier Fly:Hermetia illucens larvae convert organic waste biomass with feed conversion ratios superior to conventional livestock. Industrial facilities in the Netherlands and France achieve tonnage scale for aquafeed and pet food commodity supply.
- Mealworms:Tenebrio molitor rearing operates at lower density but yields food-grade protein with favorable amino acid completeness. EFSA clearance has positioned this species for human consumption leadership in European markets.
- Crickets:Acheta domesticus and Gryllodes sigillatus species carry Novel Food authorization for powdered and whole formats. Asian supply chains and European indoor farming operations compete on organic certification and carbon footprint metrics.
- Grasshoppers:Locusta migratoria and related species await EFSA safety evaluation completion. Traditional consumption in African and Asian markets informs dossier preparation for European authorization.
Black Soldier Fly dominates current production volumes, with Mealworms gaining share fastest in food-grade channels.
Form:
Processing intensity and shelf stability requirements segment the market across preservation methods, with downstream customer specifications determining optimal format selection.
- Powdered:Milled and sieved fractions below 500 micron particle size integrate into extruded feeds and baked goods. Protein concentration and flowability specifications vary by end-use.
- Extracts:Purified protein, lipid, or chitin fractions require additional separation and refining steps. Premium positioning in cosmetics and pharmaceuticals justifies processing overhead.
- Dried:Whole or fragmented larvae preserved through microwave or freeze-drying retain structural integrity for visual presentation in pet treats and culinary applications.
- Whole:Unprocessed adult or larval insects serve niche culinary and educational markets. Limited shelf stability constrains distribution reach.
Powdered formats lead current output volumes, with Extracts showing the steepest expansion trajectory in high-margin applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands anchors insect ingredient production through its dense cluster of industrial bioconversion facilities near the Belgian border. France and Belgium follow with vertically integrated operations serving premium pet food and aquafeed channels. Germany and the United Kingdom represent underpenetrated procurement markets where demand outstrips domestic supply.
Netherlands
Dutch aquafeed manufacturers specify black soldier fly meal for salmon and trout diets under ESG-linked procurement mandates from European retailers. The EU Green Deal channels Common Agricultural Policy subsidies toward insect farm establishment in former livestock regions. Protix operates the continent's largest industrial bioconversion facility near Dongen, supplying tonnage to Norwegian salmon feed producers.
France
French pet food brands negotiate multi-year offtake agreements for mealworm-derived proteins as conventional fishmeal costs fluctuate. The national protein sovereignty plan directs public funding toward larval rearing capacity near existing oilseed processing clusters in northern France. Innovafeed leverages vertical integration from larvae cultivation to oil extraction across its French operations.
Belgium
Belgian retailers stock authorized mealworm and cricket formats for human consumption while awaiting portfolio expansion from pending EFSA reviews. EFSA's species-by-species safety evaluations under the EU Novel Food framework create segmented approval pathways for food manufacturers. Continuous-flow larvae rearing systems from Dutch engineering firms deploy across Belgian facilities near the Flemish-Dutch border.
Germany
German pet food manufacturers represent Europe's largest manufacturing base yet lack proximate insect protein production density. The country's federal states compete for CAP subsidies to establish insect farming infrastructure in former agricultural regions. Mars Petcare and Nestlé Purina source certified food-grade capacity from French and Dutch suppliers pending domestic scale-up.
United Kingdom
British aquaculture operations import black soldier fly meal from Dutch producers under post-Brexit trade arrangements. The Food Standards Agency evaluates novel food applications separately from EFSA timelines, creating regulatory asynchrony with continental suppliers. Scottish salmon feed manufacturers specify insect protein inclusion to meet marine ingredient reduction targets from UK retailers.
Insect-Based Ingredients Market Competitive Landscape
Capacity expansion dominates the current landscape as cultivators race to secure multi-year offtake agreements with premium pet food and aquafeed buyers. The vendor base stratifies across three tiers: vertically integrated industrial bioconverters achieving tonnage scale, mid-cap specialists focused on food-grade species diversification, and regional substrate-to-protein operators serving local feed markets. Strategic archetypes include the full-stack cultivator controlling rearing through extraction, the species specialist optimizing mealworm or cricket formats for human consumption, and the waste-to-protein aggregator securing municipal organic waste contracts. Dominant competitive moves encompass geographic expansion into underpenetrated procurement markets and technology licensing of continuous-flow rearing systems.
Among French and Dutch industrial bioconverters, Innovafeed, Protix, and Ynsect occupy positions exemplifying distinct strategic archetypes. Innovafeed represents the vertically integrated model spanning larvae cultivation through downstream oil extraction. Protix anchors European supply volume through industrial-scale black soldier fly operations. Ynsect sits within the species-specialist tier, concentrating on mealworm-derived proteins for higher-margin applications. EnviroFlight and Aspire Food Group represent North American entrants pursuing regulatory clearance pathways distinct from EFSA sequencing. Entobel and Nutrition Technologies exemplify regional substrate-secured operators building captive supply relationships with local waste generators.
| Leading Market Players |
|---|
| Innovafeed |
| Protix |
| EnviroFlight |
| Ynsect |
| Sentara Group |
| Entobel |
| Aspire Food Group |
| Nutrition Technologies |
| AgriProtein |
| Others |
Supply & Pricing Matrix
Entomology workforce scarcity in the Netherlands and northern France widens pricing spreads between food-grade and feed-grade insect protein tiers, as labor-cost differentials compound certification overhead for human-consumption channels.
Pricing Analysis
Input-cost pass-through from organic waste substrate volatility compresses margins for black soldier fly cultivators serving commodity aquafeed contracts. Contract-based long-term offtake agreements dominate premium channels, with price differentiation driven by EFSA Novel Food certification status and vertical integration depth. Pricing pressure stems from precision-fermented protein substitutes capturing companion animal nutrition share. Feed-grade buyers exhibit highest price sensitivity, while cosmetics formulators and sports nutrition brands tolerate premium positioning for lauric acid specificity.
Supply Chain Analysis
Direct-to-aquafeed-manufacturer channels handle volume demand from Norwegian salmon feed producers, while pet food brands source through multi-year offtake agreements with French and Dutch cultivators. Supply concentrates in the Netherlands, France, and Belgium, with German and British buyers dependent on cross-border procurement. The chain draws from organic waste substrates, climate-controlled rearing infrastructure, and mechanical separation equipment. Single-source vulnerability runs through concentrated larvae rearing capacity near the Dutch-Belgian border.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where ESG-linked procurement mandates from European retailers are hardening demand specifications toward deforestation-free, marine-ingredient-reduced feed formulations.
For Market Incumbents: Deploy continuous-flow rearing technology licensing to defend position against precision-fermented protein substitutes entering companion animal nutrition. Secure multi-year offtake agreements with Mars Petcare and Nestlé Purina before capacity expansion saturates premium pet food channels. Add food-grade certification capacity in Germany's underpenetrated federal states to capture localization subsidies. For New Entrants and Emerging Players: Begin with substrate-secured operations in former livestock regions of eastern Germany, where CAP subsidies offset capex intensity and proximate demand from Europe's largest pet food manufacturing base outstrips supply. Target aquafeed commodity supply to Norwegian salmon producers as the most penetrable volume segment, leveraging deforestation-free procurement mandates as entry wedge. For Investors and Strategic Acquirers: Pet food manufacturers are the most active acquirer in this space, pursuing captive supply of certified food-grade insect protein. The analysis frames long-term viability around regulatory synchronization between feed-grade and food-grade approval pathways, with acquisition focus on vertically integrated cultivators possessing EFSA-cleared species portfolios. Monitor EFSA dossier clearance timelines for lesser mealworm and housefly as inflection signal for human-food market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Novel Food Dossier Expansion | EFSA clearance for additional species unlocks human-consumption revenue diversification beyond feed-grade channels. |
| Backward Integration into Substrate Supply | Municipal organic waste contracts reduce input cost volatility and margin unpredictability for larvae cultivators. |
| Continuous-Flow Rearing System Deployment | Dutch engineering firms standardize quality metrics while compressing capital requirements per ton of protein output. |
| Multi-Year Offtake Agreement Negotiation | Premium pet food brands concentrate procurement power with certified food-grade capacity holders. |
| Geographic Expansion into Germany | Federal states compete for CAP subsidies to establish production density near Europe's largest pet food manufacturing base. |
Research Methodology
Direct dialogue with insect farm operations managers, EFSA regulatory affairs specialists, aquafeed procurement directors, and pet food brand supply chain heads grounded qualitative findings, cross-referenced with EFSA Novel Food register entries, EU CAP subsidy disbursement records, Dutch customs trade data, and Norwegian salmon feed formulation disclosures. Bottom-up protein output estimates from identified cultivation facilities triangulated against top-down demand absorption from end-use sector procurement mandates.
Segment-level value and volume trajectories across the analysis window reflect modeled interactions between regulatory clearance sequencing, species-specific rearing efficiency parameters, and buyer procurement localization incentives. CAGRs derived from fitted growth curves incorporating EFSA dossier approval probability weightings, mechanical separation technology diffusion rates, and ESG-linked procurement mandate adoption curves in European retail and aquaculture sectors.
Several conditions sit outside the modeled scope, including potential EFSA safety evaluation timeline extensions, precision-fermented protein cost parity achievement, and Brexit-related trade friction modifications affecting British import arrangements. Forecasts reflect assumptions about regulatory synchronization and technology adoption that warrant periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Mung Bean Starch Market
Ingredients
Textured Soy Flour Market
Ingredients
Thinned Starch Market
Ingredients
Mirepoix Market
Ingredients
Food Ingredients Market
Ingredients
Marine Hyaluronic Ingredients Market
Ingredients
North America Gluten Free Flour Market
Ingredients
North America Plant Protein Ingredients Market
Ingredients
Food Grade Cassia Gum Powder Market
Ingredients
Pulses Ingredients Market
Ingredients
Bouillon Market
Ingredients
Vital Wheat Gluten Market
Ingredients
Specialty Yeast Market
Ingredients
Soybean Oil Market
Ingredients
Jasmine Extract Market
Ingredients
Resistant Starch Market