
 Cold Water-Soluble Creamer Market | 2026-2036
Cold Water-Soluble Creamer Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Water-Soluble Creamer Market Analysis
ISO 22000 certification is bifurcating the competitive landscape into qualified suppliers and second-tier entrants. Royal FrieslandCampina leverages its dairy protein expertise to anchor premium cold water-soluble formulations. Mokate S.A. sustains Central European production scale with specialized spray-drying infrastructure. Fujian Jumbo Grand Food Co., Ltd. dominates Greater China distribution through deep channel control in food service.
Cold water-soluble creamer denotes a lipid-protein matrix engineered for instantaneous dispersion below 25°C, typically manufactured through high-pressure spray-drying of emulsified fat-in-water systems with modified starches or hydrocolloids. The ingredient type dimension reveals plant-based formulations capturing the fastest growth as oat and coconut lipid replacements displace hydrogenated palm fractions in beverage applications. Powder formats retain volume leadership due to superior shelf stability and freight economics, though liquid creamer pods are expanding in automated vending and capsule systems where single-serve precision matters.
Food safety frameworks from the FDA, EFSA, and China's SAMR govern emulsifier allowances, hydrogenated fat restrictions, and labeling thresholds that directly shape formulation choices and export eligibility. The EU F-Gas Regulation indirectly pressures manufacturers by restricting refrigerants used in cold-chain logistics for liquid creamer variants. Stakeholders must monitor evolving plant protein allergen labeling requirements across multiple jurisdictions to preempt reformulation cycles and secure shelf placement.
Market Dynamics
The EU Green Deal's hydrogenated fat restrictions are forcing wholesale lipid system reformulation across cold water-soluble creamer manufacturing, compressing legacy palm oil dependencies while accelerating oat and coconut oil adoption timelines.
Growth Catalysts
- RTD Beverage Proliferation:Southeast Asian instant coffee providers are expanding cold water-soluble procurement as ready-to-drink lines multiply across Vietnam and Indonesia.
- ISO 22000 Certification:Food safety framework adoption is creating supplier qualification tiers that concentrate procurement among certified manufacturers.
- Spray-Drying Infrastructure:Specialized high-pressure atomization technology deployment is enabling instantaneous sub-25°C dispersion performance in ambient-temperature markets.
Market Restraints
- Plant Lipid Input Volatility:Oat and coconut oil supply fluctuations create formulation cost instability versus legacy hydrogenated palm fractions.
- Refrigerant Restrictions:The EU F-Gas Regulation constrains cold-chain logistics capacity for liquid creamer variants, compressing distribution range.
- Allergen Labeling Complexity:Evolving plant protein disclosure requirements across multiple jurisdictions extend reformulation cycles and delay shelf placement.
Strategic Opportunities
- Automated Vending Penetration:Liquid creamer pod formats are capturing precision-dispensing channels in Japan and South Korea's unmanned beverage infrastructure.
- Food Service Channel Control:Deep distribution partnerships in Greater China's commercial beverage operations offer volume anchoring independent of retail competition.
- Plant-Based Mandate Tailwinds:EU Green Deal hydrogenated fat prohibitions are creating regulatory-driven demand acceleration for reformulated lipid-protein matrices.
Industry Challenges
- Emulsifier Compliance Timelines:FDA, EFSA, and SAMR allowance variations across jurisdictions force parallel formulation tracks and extend certification durations.
- Spray-Drying Capex Intensity:High-pressure atomization equipment and specialized drying tower infrastructure demand substantial capital deployment for quality-tier entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Water-Soluble Creamer Market |
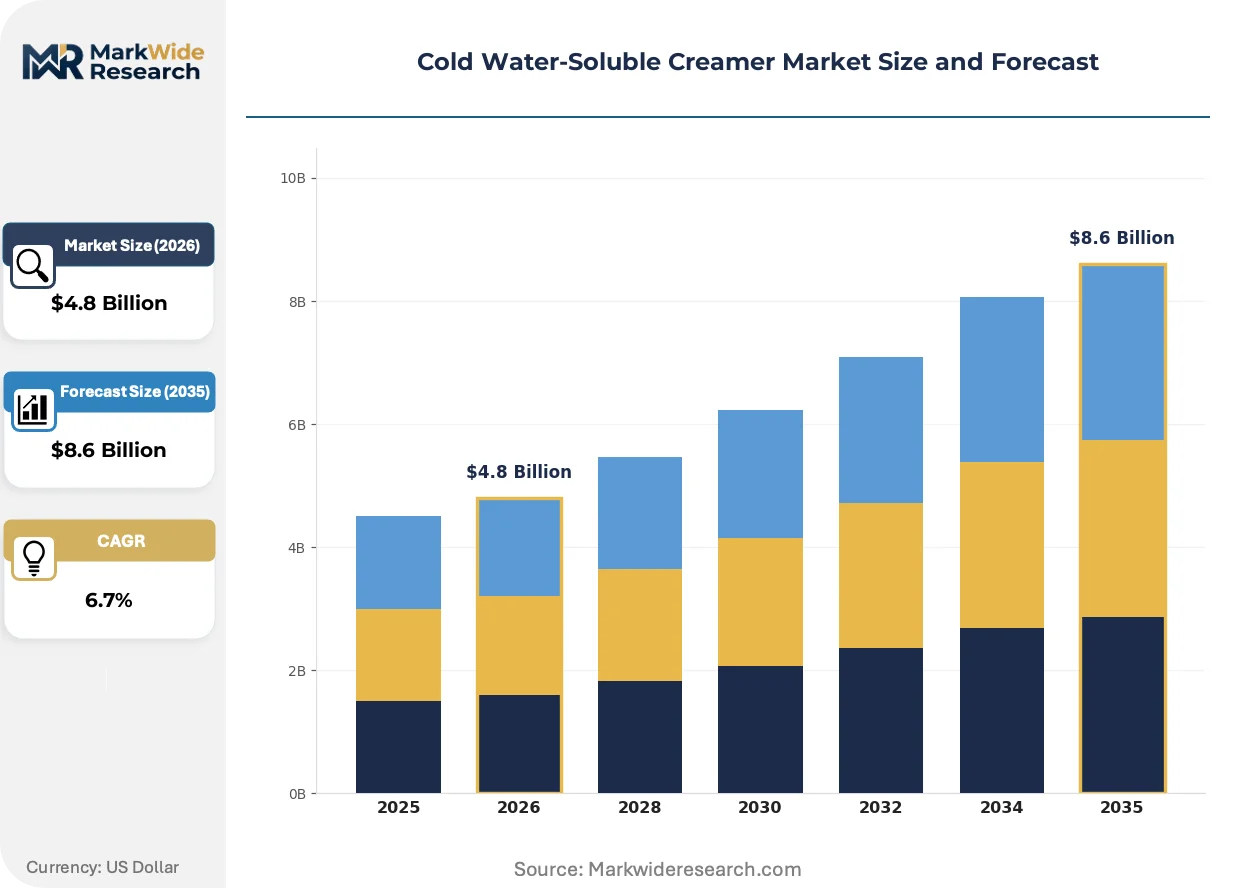
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creamer Powder, Liquid Creamer, Creamer Pods, Creamer Sachets End User: Food Service, Retail, Beverage Manufacturers, Instant Coffee Providers Ingredient Type: Dairy, Non-Dairy, Plant-Based, Sugar-Free Application: Beverages, Baking, Confectionery, Other Food Products |
| Companies Covered | Super Group Ltd., Almer Malaysia Sdn Bhd, Mokate S.A., Guangdong Wenhui Food, Shandong Tianjiao Biotech, Royal FrieslandCampina, Ingredion, Fujian Jumbo Grand Food Co., Ltd., Balchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Water-Soluble Creamer Market Emerging Trajectories
Formulation chemistry and dispersion technology are converging to redefine performance benchmarks for cold water-soluble creamers, with plant lipid integration and automated dispensing systems driving parallel innovation tracks.
Modified starch and hydrocolloid stabilization systems are bifurcating the performance spectrum between economy and premium cold water-soluble tiers. Beverage manufacturers in Vietnam and Indonesia are adopting these systems at accelerated rates to achieve sub-25°C dispersion without hydrogenated fat content. This technological divergence is compressing mid-tier positioning while enabling clear quality stratification based on instantaneous solubility metrics.
REACH chemical registration requirements and the EU F-Gas Regulation are tightening emulsifier approval pathways and cold-chain logistics constraints simultaneously. Industrial consequence manifests in reformulation bottlenecks for manufacturers dependent on legacy refrigerant-dependent liquid distribution. Liquid creamer variants face compressed geographic reach, while powder formats gain relative advantage in ambient-temperature supply chains.
Single-serve precision requirements are restructuring procurement patterns across automated beverage channels. Capsule and pod systems in Japan's vending infrastructure are displacing bulk powder contracts in commercial settings. This behavioral shift concentrates most visibly in metropolitan clusters where unmanned beverage stations dominate out-of-home consumption.
Cold Water-Soluble Creamer Market Segmentation
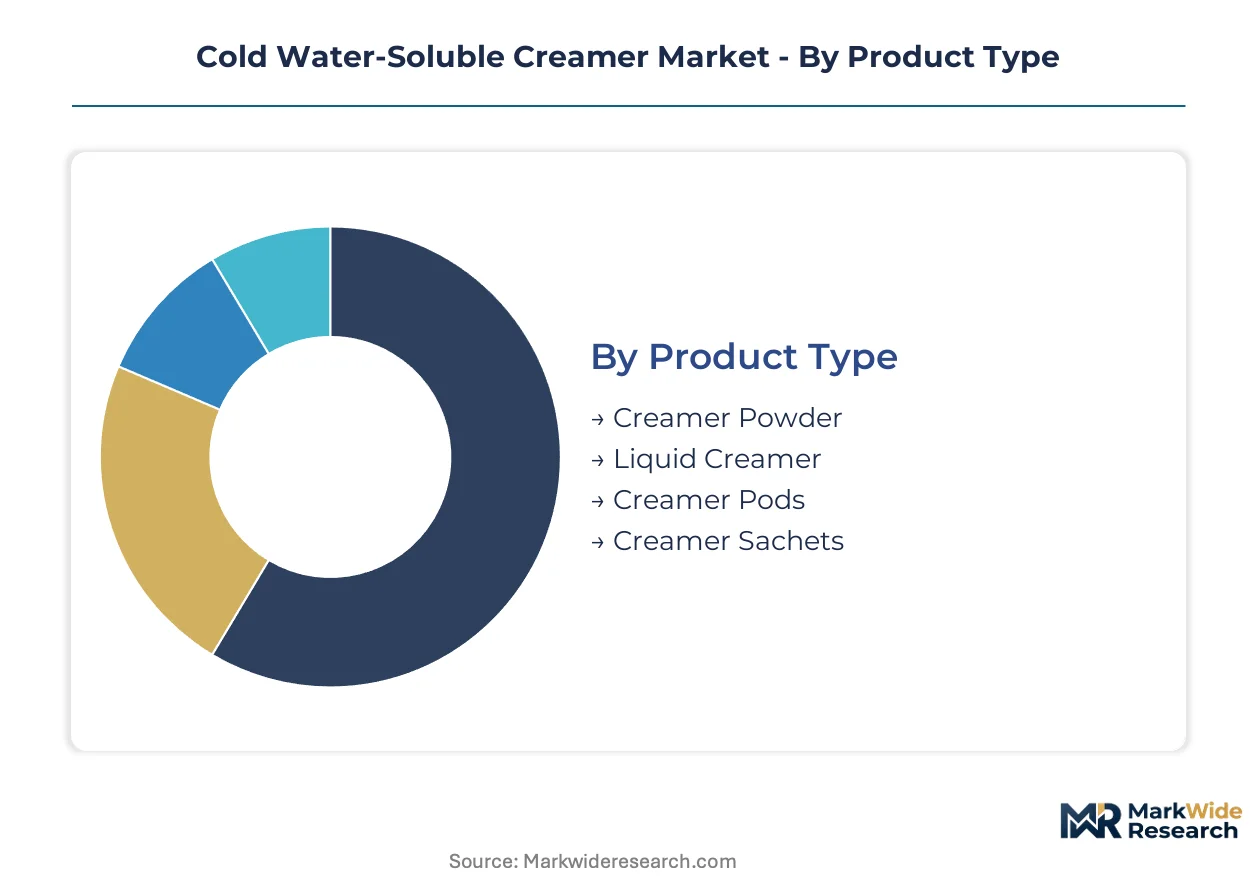
Cold water-soluble creamer segmentation reflects divergent technical requirements across ambient-temperature supply chains and automated dispensing infrastructure. Regulatory frameworks governing hydrogenated fat content and emulsifier allowances directly shape viable formulation pathways within each category.
Product Type:
FDA, EFSA, and SAMR emulsifier allowances create divergent compliance pathways that favor powder formats in multi-jurisdictional distribution while constraining liquid variants through refrigerant-dependent logistics regulations.
- Creamer Powder:Spray-dried lipid-protein matrices with modified starch or hydrocolloid carriers achieve instantaneous sub-25°C dispersion without cold-chain dependency. Vietnam and Indonesia's ambient-temperature beverage markets concentrate procurement here due to freight economics and shelf stability advantages under tropical storage conditions.
- Liquid Creamer:Emulsified fat-in-water systems requiring refrigerated distribution face compressed geographic reach under EU F-Gas Regulation constraints on refrigerant gases. Japan and South Korea's automated vending channels absorb volume despite logistics limitations, driven by single-serve precision requirements in unmanned infrastructure.
- Creamer Pods:Pre-portioned liquid formats for capsule systems integrate with precision-dispensing equipment in commercial settings. METI standards govern packaging integrity for Japan's vending machine integration.
- Creamer Sachets:Individual powder sachets serve food service and institutional channels where portion control and minimal equipment requirements dominate procurement criteria.
Creamer powder handles the majority of throughput; creamer pods are the fastest mover on share.
End User:
Cost tier differentiation separates high-volume commodity supply from specialized formulation services, with certification requirements creating distinct procurement qualification levels.
- Food Service:Commercial beverage operations in Greater China demand bulk powder supply with consistent dispersion performance across variable water temperatures. Channel control through deep distribution partnerships anchors volume independent of retail competition.
- Retail:Consumer packaged formats face shelf placement competition where ISO 22000 certification functions as a qualification gate. Supermarket and convenience store channels in Southeast Asia prioritize plant-based labeling compliance for EU export eligibility.
- Beverage Manufacturers:Industrial-scale procurement for RTD line integration requires customized lipid-protein matrices with specified viscosity and stability profiles. Reformulation timelines accelerate under EU Green Deal hydrogenated fat prohibitions.
- Instant Coffee Providers:Southeast Asian producers expanding cold water-soluble procurement drive demand concentration in Vietnam and Indonesia, where ambient-temperature consumption patterns dominate.
Food service handles the majority of throughput; beverage manufacturers are expanding most quickly on share.
Ingredient Type:
Application requirements for clean-label positioning and allergen disclosure complexity are restructuring procurement priorities across dairy, plant-derived, and modified formulations.
- Plant-Based:Oat and coconut lipid replacements displace hydrogenated palm fractions under EU Green Deal regulatory pressure. REACH registration requirements for novel emulsifier systems extend formulation development cycles while creating first-mover advantages for approved ingredient suppliers.
- Dairy:Milk protein concentrates and sodium caseinate matrices retain premium positioning through superior mouthfeel and whitening performance. Royal FrieslandCampina leverages dairy protein expertise to anchor high-end cold water-soluble formulations.
- Non-Dairy:Hydrogenated vegetable oil systems face declining procurement as regulatory prohibitions compress legacy formulation viability across European markets.
- Sugar-Free:Aspartame and sucralose-sweetened variants serve diabetic and reduced-calorie beverage segments with specialized stability requirements for high-intensity sweetener compatibility.
Dairy handles the majority of throughput; plant-based is climbing the fastest.
Application:
Volume concentration in beverage channels versus margin differentiation in specialized food manufacturing creates divergent formulation investment priorities.
- Beverages:Coffee, tea, and cocoa applications demand instantaneous dispersion below 25°C with stable emulsion performance across pH variations. Vietnam and Indonesia's RTD proliferation concentrates procurement scale in this channel.
- Baking:Powder creamers function as fat and milk solid replacers in industrial bakery operations, with spray-dried format compatibility supporting dry mix integration.
- Confectionery:Specialized lipid systems for chocolate compound and candy applications require modified melting profiles and bloom resistance distinct from beverage-grade specifications.
- Other Food Products:Soup, sauce, and savory applications utilize creamer matrices for creaminess and mouthfeel modification in processed food manufacturing.
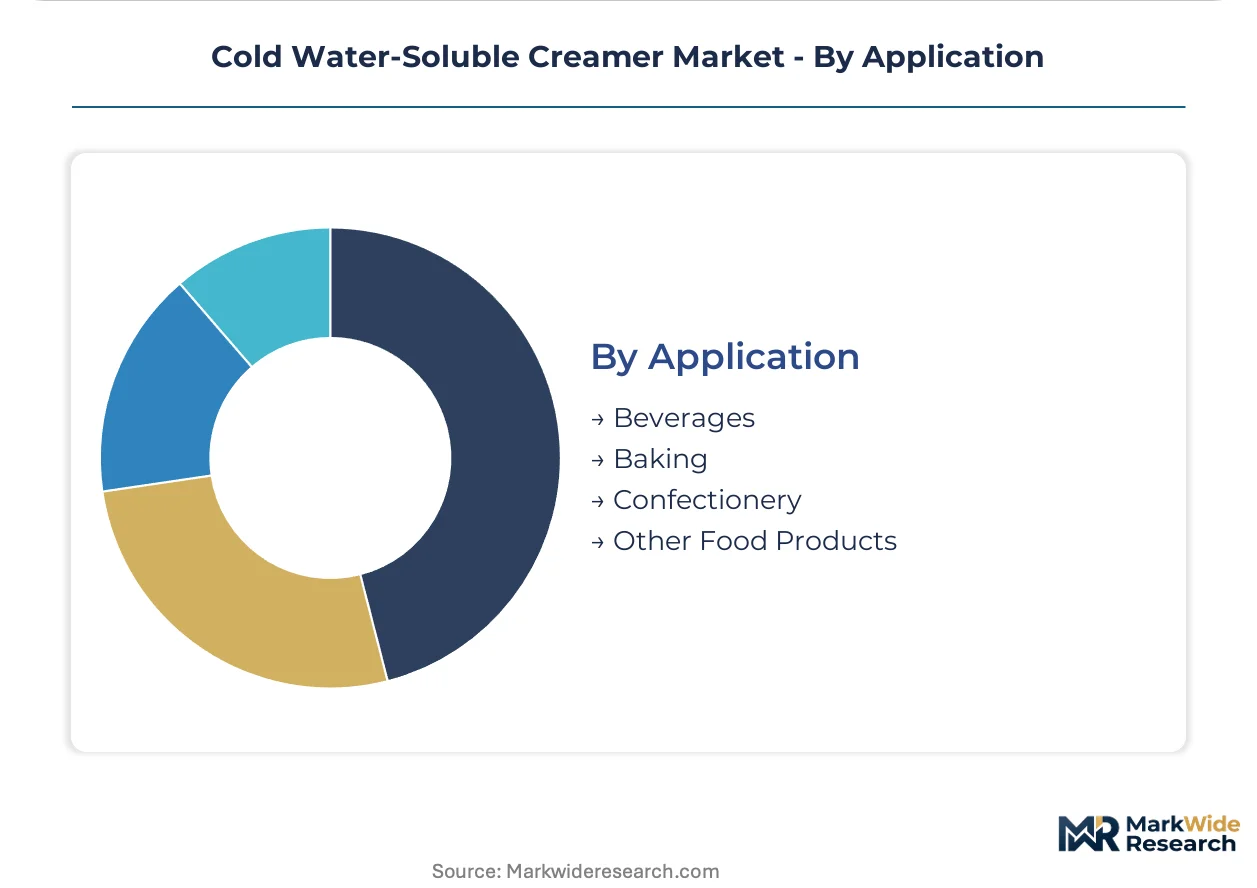
Beverages handles the majority of throughput; baking is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instant coffee manufacturers and RTD beverage producers drive procurement concentration across Southeast Asia, with EU regulatory pressure redirecting supply chains toward plant-based lipid systems. Vietnam and Indonesia anchor volume demand through ambient-temperature consumption patterns, while Greater China's food service channels and Japan's automated vending infrastructure create divergent growth vectors.
Vietnam
Ho Chi Minh City and Hanoi-based instant coffee producers expand cold water-soluble creamer procurement as RTD beverage lines multiply across domestic and export markets. The Ministry of Industry and Trade's food safety modernization program accelerates ISO 22000 adoption among ingredient suppliers. Binh Duong Province hosts spray-drying infrastructure clusters where manufacturers achieve sub-25°C dispersion specifications for tropical ambient distribution.
Indonesia
Jakarta and Surabaya beverage manufacturers concentrate demand for powder formats suited to archipelago logistics and inconsistent cold-chain coverage. The National Agency of Drug and Food Control (BPOM) enforces stricter emulsifier labeling requirements that compress reformulation timelines. East Java's Malang industrial corridor anchors production scale for domestic instant coffee and cocoa applications.
China
Guangdong and Fujian food service operators drive bulk powder procurement through deep commercial beverage channel partnerships independent of retail competition. SAMR's evolving plant protein allergen disclosure standards extend certification cycles for reformulated products. Xiamen's specialized ingredient manufacturing zone concentrates spray-drying capacity serving Greater China distribution networks.
Japan
Tokyo and Osaka metropolitan clusters absorb liquid creamer pod volume for precision-dispensing unmanned vending infrastructure. METI standards govern packaging integrity requirements for automated beverage machine integration. Nagoya's industrial corridor hosts formulation specialists adapting lipid-protein matrices to single-serve capsule specifications.
Germany
Ruhr Valley and Bavarian beverage ingredient distributors navigate EU Green Deal hydrogenated fat prohibitions that accelerate oat and coconut oil adoption timelines. EFSA emulsifier allowance variations force parallel formulation tracks for export-eligible products. Hamburg's port logistics infrastructure anchors cold-chain distribution capacity for liquid creamer variants serving Central European markets.
Cold Water-Soluble Creamer Market Vendor Landscape
Player mix skews toward specialized spray-drying operators and diversified dairy ingredient suppliers, with ISO 22000 certification creating visible supplier qualification tiers. The competitive structure concentrates procurement leverage among manufacturers with captive emulsification technology and high-pressure atomization infrastructure. Two strategic archetypes dominate: plant-based lipid system specialists and dairy protein matrix incumbents. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with regulatory-driven reformulation partnerships accelerating across EU-facing supply chains.
Within the dairy protein tier, Royal FrieslandCampina anchors premium formulation expertise, while Mokate S.A. exemplifies Central European production scale through specialized spray-drying infrastructure. Fujian Jumbo Grand Food Co., Ltd. represents Greater China channel control archetypes, with Guangdong Wenhui Food and Shandong Tianjiao Biotech occupying positions among Chinese domestic suppliers. Super Group Ltd. and Almer Malaysia Sdn Bhd sit within Southeast Asian procurement concentration zones serving Vietnam and Indonesia demand clusters. Ingredion and Balchem occupy ingredient technology supplier positions, with Balchem representing microencapsulation specialization relevant to dispersion performance specifications.
| Leading Market Players |
|---|
| Super Group Ltd. |
| Almer Malaysia Sdn Bhd |
| Mokate S.A. |
| Guangdong Wenhui Food |
| Shandong Tianjiao Biotech |
| Royal FrieslandCampina |
| Ingredion |
| Fujian Jumbo Grand Food Co., Ltd. |
| Balchem |
| Others |
Supply Flow & Price Mechanics
ISO 22000 certification gates both supplier qualification and price differentiation simultaneously, compressing uncertified manufacturers into commodity tiers while anchoring premium pricing power among accredited spray-drying operators with sub-25°C dispersion guarantees.
Pricing Analysis
Cost-plus contracts with palm oil and coconut oil indexation dominate procurement between Vietnamese instant coffee manufacturers and spray-drying facilities. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified suppliers from uncertified competitors and food-grade commodity traders. Pricing pressure stems from oat lipid input volatility as EU Green Deal prohibitions accelerate reformulation timelines. Beverage manufacturers exhibit highest price sensitivity, while automated vending operators in Japan absorb premiums for single-serve precision.
Supply Chain Analysis
Spray-drying tower capacity chokepoints in Vietnam's Binh Duong Province and Indonesia's East Java corridor concentrate upstream supply leverage. Manufacturing draws from hydrogenated palm oil, oat lipid fractions, and modified starch hydrocolloids as primary inputs. Single-source vulnerability runs through Southeast Asian emulsifier suppliers facing REACH registration bottlenecks. Distribution runs through ambient-temperature bulk powder logistics for food service channels, with liquid variants constrained by EU F-Gas refrigerant restrictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capsule system interoperability is restructuring procurement platforms, with METI-standard pod formats creating ecosystem lock-in that favors formulation specialists capable of precision-dispensing integration across Japan's unmanned beverage infrastructure.
For Market Incumbents: Consolidate spray-drying capacity in Vietnam and Indonesia through acquisition of second-tier facilities facing ISO 22000 compliance costs. Deepen captive emulsification technology to defend margin position against plant-based lipid volatility. Lock in multi-year offtake agreements with RTD beverage lines before EU Green Deal reformulation deadlines compress supplier switching costs. For New Entrants and Emerging Players: Anchor in Greater China's food service channel control gaps, where bulk powder procurement lacks certified alternatives to incumbent distributors. Target baking applications as the fastest-expanding segment with lower certification barriers than beverage-grade specifications. Pursue toll-manufacturing partnerships with underutilized spray-drying assets in Fujian and Shandong provinces. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across plant-based lipid system manufacturing as specialized drying tower infrastructure demands substantial deployment. Five-to-ten-year viability favors operators with backward integration into emulsifier supply and captive oat lipid sourcing. Monitor EU F-Gas Regulation enforcement intensity as signal for liquid creamer variant compression and powder format relative advantage.| Strategic Initiative | Industry Significance |
|---|---|
| Spray-Drying Capacity Expansion | Binh Duong Province infrastructure investments capture Vietnamese RTD beverage procurement concentration. |
| Plant Lipid Backward Integration | Captive oat and coconut oil sourcing insulates margins from commodity volatility under EU Green Deal timelines. |
| ISO 22000 Certification Investment | Food safety framework adoption gates procurement from Southeast Asian instant coffee manufacturers. |
| Automated Vending Partnership | METI-standard pod integration secures shelf placement in Japan's unmanned beverage infrastructure. |
| Food Service Channel Control | Deep distribution partnerships in Greater China anchor volume independent of retail competition intensity. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with spray-drying facility operators, procurement managers at Vietnamese instant coffee manufacturers, food service distributors in Greater China, and emulsifier technology specialists; alongside secondary validation through customs trade records, BPOM and SAMR regulatory filings, and industry association production surveys. Bottom-up capacity assessments triangulated against top-down demand modeling from RTD beverage line expansions.
Across the projection horizon, the analytical framework modeled segmentation by product type, ingredient category, end-user channel, and geographic production cluster. CAGRs derived from historical capacity utilization trends and announced facility expansions, with sensitivity analysis around EU Green Deal implementation pace and oat lipid supply elasticity.
Decision-makers should treat outputs as directional under assumptions of sustained EU hydrogenated fat prohibition timelines and stable Southeast Asian ambient-temperature consumption patterns; material deviation in regulatory enforcement or cold-chain infrastructure investment would warrant model refresh. Practitioners should keep alternative scenarios live as F-Gas Regulation scope expansion and plant protein allergen labeling harmonization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Bouillon Market
Ingredients
Egg Yolk Powder Market
Ingredients
Edible Fiber Market
Ingredients
North America Brewing Enzymes Market
Ingredients
South America Insoluble Dietary Fibers Market
Ingredients
Grape Seed Extracts Market
Ingredients
India Bakery Ingredients Market
Ingredients
North America Soybean Oil Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Encapsulated Ingredients Market
Ingredients
Europe Gelatin Market
Ingredients
Mexico Avocado Oil Market
Ingredients
Europe Insoluble Dietary Fibers Market
Ingredients
Meat Extract Market
Ingredients
Isoamyl Laurate Market
Ingredients
North America Alcohol Ingredients Market