
 Organic Cheese Powder Market | 2026-2036
Organic Cheese Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Cheese Powder Market Outlook
Specialty ingredient distribution is reshaping how organic cheese powder reaches food manufacturers. Kerry Group plc leverages its flavor systems portfolio to anchor supply relationships with clean-label snack producers across North America. Fonterra Co-operative Group Limited dominates organic dairy ingredient sourcing through its New Zealand farmer cooperative structure, while Glanbia plc specializes in nutritional and functional dairy powders for European food service channels.
Organic cheese powder consists of dehydrated organic cheese solids produced through spray-drying or roller-drying processes, typically containing 35-55% cheese solids with organic maltodextrin or whey as carriers, serving primarily as a flavoring and texturizing agent in processed foods. Cheddar variants occupy the largest share of product type demand due to their versatility across snack seasoning and sauce applications. The sauces application segment registers the fastest structural expansion as organic quick-service and retail-ready meal formats multiply. Food manufacturers represent the deepest margin pool among end users, commanding volume pricing and custom formulation services that retailers and households cannot replicate.
The USDA National Organic Program and EU Organic Regulation enforce strict livestock feed and processing standards that limit supplier eligibility and extend certification timelines for new market entrants. FDA food additive regulations and EFSA labeling requirements further constrain how organic cheese powder can be positioned in finished products. Stakeholders must monitor evolving organic certification reciprocity agreements between major producing regions, as fragmented standards threaten to fragment supply chain efficiency and inflate compliance costs for multinational ingredient buyers.
Market Dynamics
Clean-label certification requirements are compressing supplier eligibility timelines while concentrating procurement relationships among vertically integrated dairy processors capable of maintaining continuous organic compliance across feed sourcing, processing, and distribution stages.
Growth Catalysts
- EU Organic Regulation enforcement:Mandatory livestock feed standards and processing audits are locking in dedicated supply relationships between certified processors and snack manufacturers seeking label credibility.
- Spray-drying technology advancement:Improved thermal efficiency and flavor retention in dehydration equipment is expanding application viability into heat-sensitive sauce formulations previously closed to cheese powders.
- German retail infrastructure:Dense organic supermarket networks and above-average consumer willingness-to-pay for certified dairy derivatives are anchoring regional demand concentration.
Market Restraints
- Organic feed input volatility:Weather-driven fluctuations in certified grain and forage availability inflate raw milk cost structures beyond conventional dairy benchmarks.
- New Zealand supply concentration:Fonterra's cooperative dominance over organic milk solids creates single-source dependency risk for multinational ingredient buyers.
- USDA certification timeline friction:Multi-year transition periods for conventional dairy operations block rapid capacity expansion in response to demand spikes.
Strategic Opportunities
- Quick-service sauce applications:Organic quick-service restaurant chains are adopting cheese powder-based sauce concentrates to standardize flavor profiles across franchise locations.
- EU-US organic reciprocity expansion:Streamlined mutual recognition protocols would reduce duplicative certification costs for suppliers serving transatlantic customer bases.
- E-commerce ingredient channels:Direct-to-manufacturer platforms are disintermediating traditional foodservice distributors for mid-volume clean-label snack producers.
Industry Challenges
- Organic dairy agronomy expertise scarcity:Qualified farm advisors capable of managing certified herd health and pasture rotation protocols command premium compensation.
- Spray-dryer capex intensity:Food-grade dehydration equipment with organic segregation capabilities requires substantial capital deployment.
- EFSA labeling compliance complexity:Evolving nutritional and origin disclosure requirements demand continuous reformulation and packaging adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Cheese Powder Market |
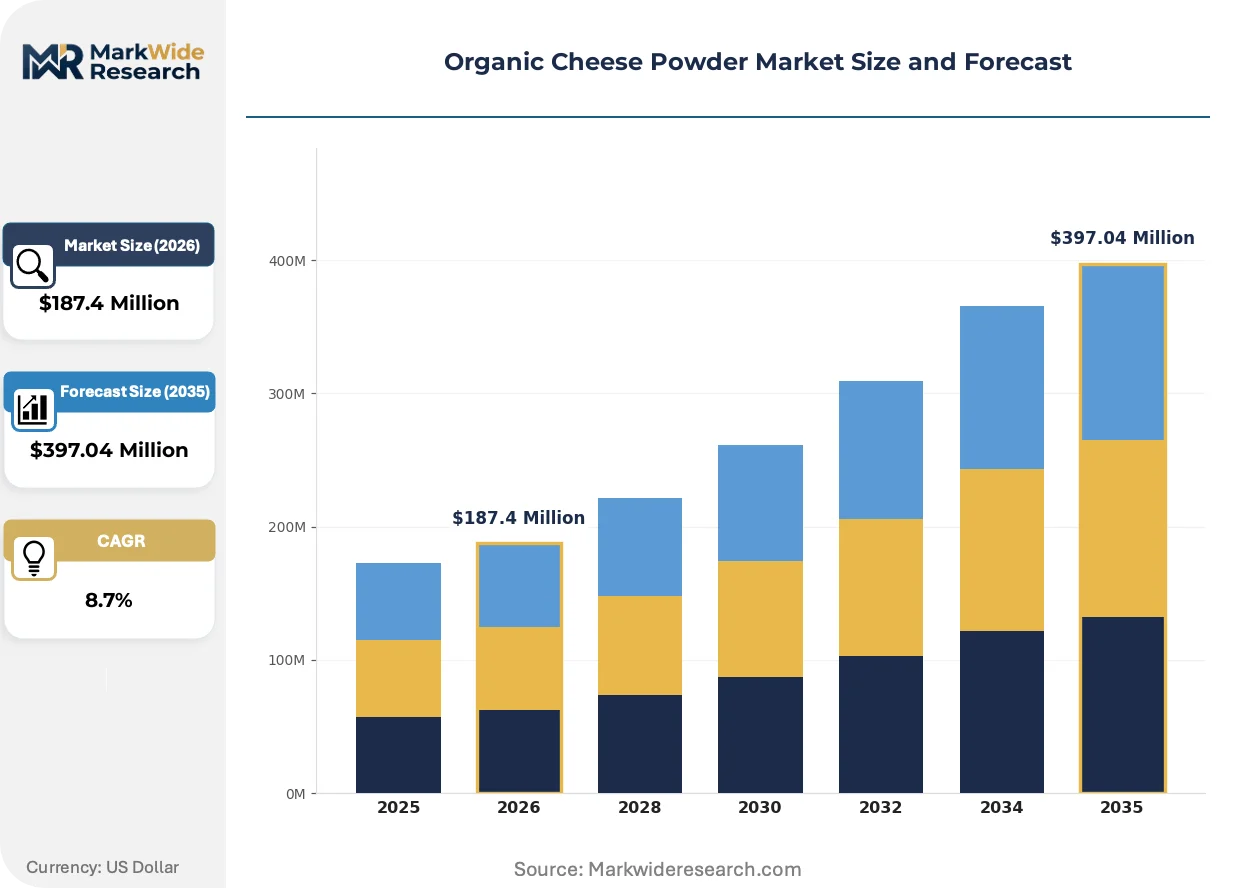
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Gouda, Parmesan, Mozzarella Application: Snacks, Sauces, Seasonings, Baked Goods End User: Food Manufacturers, Retailers, Food Service Providers, Households Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Arla Foods, Fonterra Co-operative Group Limited, Land O'Lakes, Inc., Bluegrass Ingredients, Inc., Dairy Farmers of America, Kerry Group plc, Glanbia plc, Frontier Co-op, Lactosan A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Cheese Powder Market Strategic Shifts
Processing technology convergence and certification protocol harmonization are compressing the gap between artisan dairy authenticity and industrial-scale powder production, reshaping competitive positioning across ingredient supply tiers.
Low-temperature vacuum dehydration is preserving volatile flavor compounds previously lost in conventional thermal processing. Clean-label sauce manufacturers in Germany and the Netherlands are adopting these systems to replicate aged cheddar depth in reduced-sodium formulations. Traditional high-heat roller drying is rendering obsolete for premium positioning segments where flavor fidelity commands price premiums.
REACH chemical safety registrations and EU Green Deal farm-to-fork traceability mandates are tightening documentation requirements across organic dairy supply chains. Processors must now maintain batch-level feed sourcing records and carbon footprint calculations. Cheddar powder exporters to the European Union are responding by integrating blockchain verification into supplier qualification protocols.
Direct procurement relationships between snack manufacturers and certified dairy cooperatives are displacing layered distributor networks. Mid-scale clean-label brands in North America now negotiate volume commitments directly with New Zealand and Irish organic milk suppliers. This channel restructuring is most visible among emerging plant-based snack companies seeking dairy powder co-manufacturing partnerships with established organic processors.
Organic Cheese Powder Market Segmentation
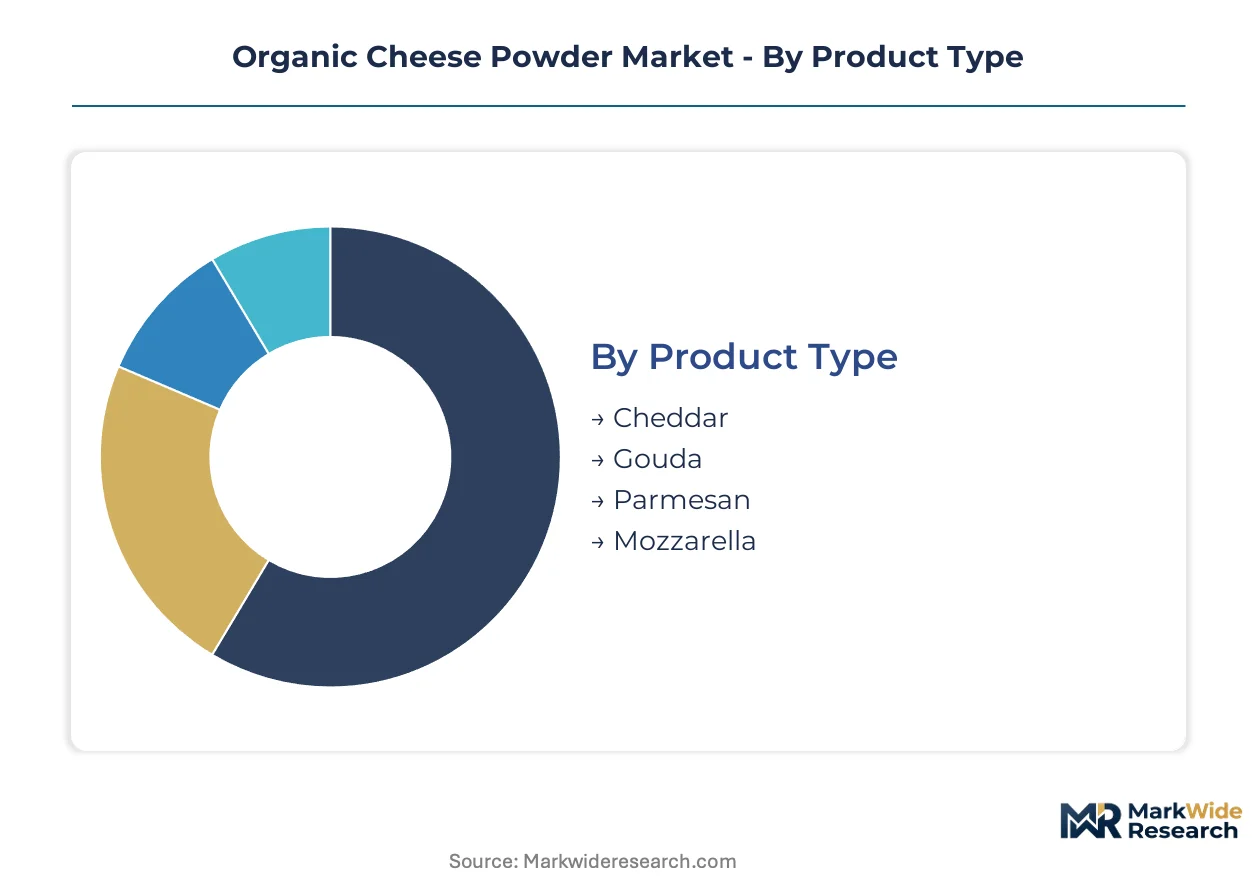
Segmentation in organic cheese powder markets reveals how certification requirements, formulation specifications, and channel access create distinct margin architectures. Each dimension carries implications for procurement complexity, regulatory compliance burden, and pricing power.
Product Type:
After-sales technical support intensity varies sharply across cheese varieties, with aged hard cheeses demanding more formulation troubleshooting than fresh varieties.
- Cheddar:Dehydrated organic cheddar solids deliver 35-55% cheese content with maltodextrin carriers, prized for meltability and sharp flavor profiles. German clean-label snack manufacturers anchor demand for aged cheddar powders in premium seasoning applications, though organic milk supply constraints limit capacity expansion.
- Gouda:Smoked and aged Gouda variants provide distinctive caramelized notes through Maillard-reactive compounds retained in low-temperature dehydration. Dutch organic dairy cooperatives dominate supply, with demand concentrating in European sauce applications seeking umami depth without artificial flavor enhancers.
- Parmesan:Hard-grating cheese powders with elevated protein content serve as finishing ingredients.
- Mozzarella:Low-moisture part-skim variants target pizza and baked goods applications.
Cheddar holds the largest share; momentum sits with Gouda as sauce formulators seek differentiated flavor signatures.
Application:
Cost tier stratification separates commodity seasoning applications from premium sauce concentrates with bespoke formulation services.
- Snacks:Organic cheese powders function as topical seasonings for extruded and puffed products, requiring adhesion systems and anti-caking agents that meet USDA organic standards. North American clean-label snack startups drive procurement volume, though EFSA labeling requirements complicate European market entry for seasoned products.
- Sauces:Concentrated cheese powder bases enable standardized flavor replication across quick-service franchise networks. German and Dutch organic restaurant chains are expanding most quickly, adopting these systems to reduce kitchen labor and ingredient waste.
- Seasonings:Retail tabletop and cooking blends represent mid-tier volume.
- Baked Goods:Crackers, savory pastries, and bread applications utilize cheese powders for flavor distribution.
Snacks command the deepest volume; sauces are climbing the fastest as food service automation spreads.
End User:
Customer type determines pricing architecture, with food manufacturers extracting volume discounts unavailable to fragmented household purchasers.
- Food Manufacturers:Large-scale processors negotiate multi-year supply agreements with certified organic dairies, securing dedicated production runs and custom particle size specifications. Kerry Group plc and Glanbia plc anchor relationships across North American and European snack production networks, leveraging technical service teams for formulation optimization.
- Retailers:Private-label organic cheese powder lines require shorter lead times and flexible minimum order quantities.
- Food Service Providers:Institutional and restaurant distributors prioritize shelf-stable concentrates with reconstitution protocols.
- Households:Direct consumer sales through e-commerce channels remain limited by price sensitivity and usage rate.
Food Manufacturers generate the highest absolute margin contribution; Food Service Providers are gaining share fastest as organic quick-service formats multiply.
Distribution Channel:
Supply concentration in New Zealand and Ireland shapes channel viability, with direct procurement relationships displacing traditional wholesale intermediaries.
- Online Retail:Direct-to-manufacturer platforms enable mid-volume clean-label snack producers to bypass foodservice distributors, accessing Fonterra and Irish organic cooperative supply with reduced markup layers. E-commerce penetration is expanding most quickly among emerging plant-based snack companies seeking dairy powder co-manufacturing partnerships.
- Supermarkets:Mass retail chains stock organic cheese powder in specialty and international aisles.
- Specialty Stores:Independent organic grocers and cheese shops cater to enthusiast consumers.
- Wholesale:Traditional food ingredient distributors maintain relevance for smaller manufacturers lacking procurement scale.
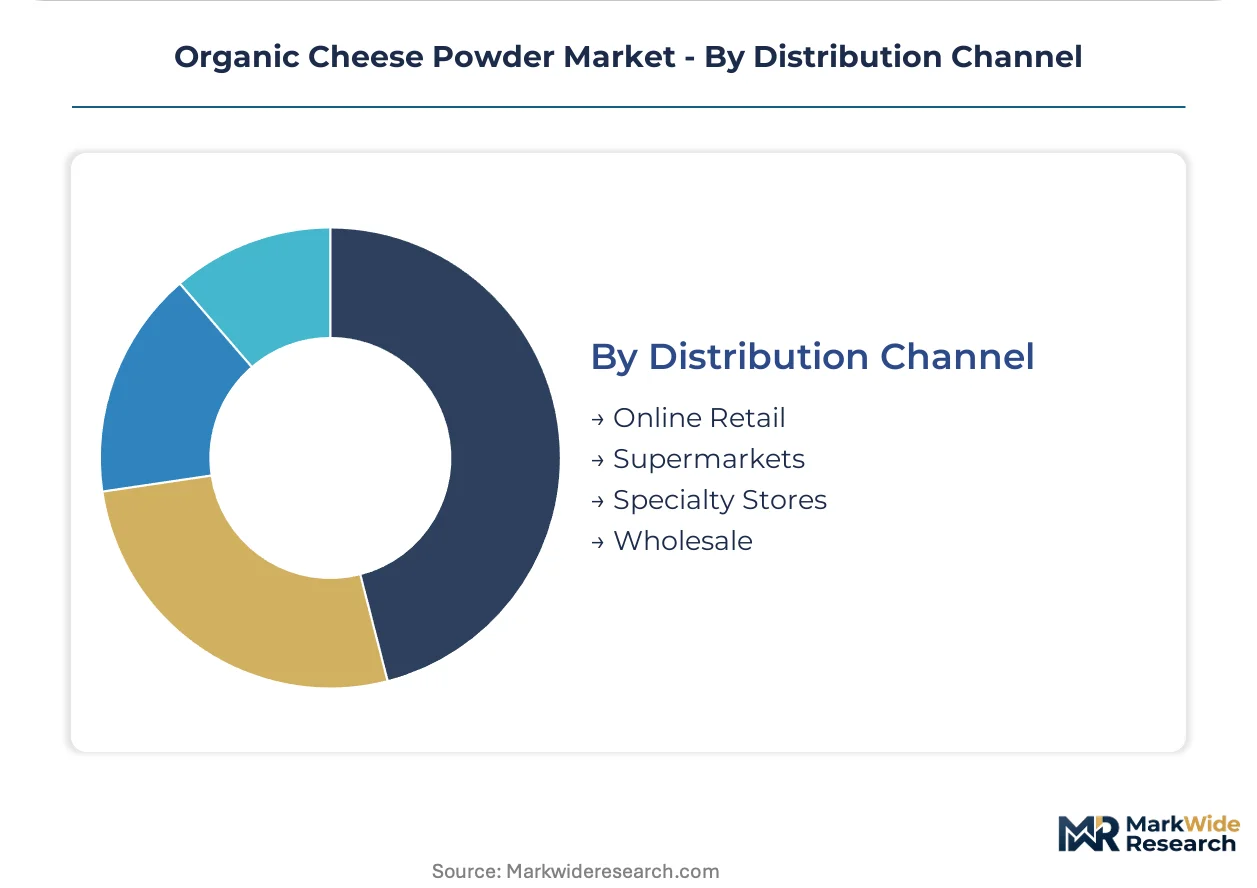
Supermarkets hold the largest share; Online Retail is expanding most quickly as platform infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain infrastructure underwrites Dutch organic dairy re-export capacity across northwestern Europe, anchoring continental distribution networks for spray-dried cheese ingredients.
Germany
Organic supermarket density in Berlin and Hamburg exceeds any European market, with REWE and EDEKA chains dedicating expanded shelf space to certified dairy derivatives. The EU Organic Regulation enforces livestock feed documentation standards that extend certification timelines for imported powders. Bavarian dairy cooperatives near Munich are installing blockchain traceability systems to satisfy farm-to-fork mandates.
United States
Clean-label snack startups in Austin and Brooklyn drive procurement volume for cheddar-based seasonings, though organic milk supply constraints limit rapid scaling. The USDA National Organic Program mandates three-year transition periods for conventional dairy operations seeking certification. Wisconsin's organic dairy belt around Madison is expanding spray-dryer capacity to serve domestic flavor houses.
Netherlands
Sauce formulators in Amsterdam and Utrecht adopt Gouda powders for umami depth without artificial enhancers, leveraging Maillard-reactive compounds from low-temperature dehydration. REACH chemical safety registrations impose documentation burdens on imported ingredients. The Eindhoven-Tilburg corridor hosts pilot facilities testing vacuum dehydration for premium flavor retention.
New Zealand
Fonterra's cooperative structure concentrates organic milk solids supply for multinational ingredient buyers across Asia-Pacific. The country's national dairy regulator enforces strict pasture-based livestock standards that limit production scalability. Canterbury region processing plants near Christchurch are expanding spray-drying lines with organic segregation capabilities.
France
Specialty cheese powder demand concentrates in Parisian food service channels seeking authentic regional flavor profiles for quick-service applications. ANSM and DGCCRF oversight of nutritional labeling creates compliance complexity for imported seasonings. The Brittany dairy cluster around Rennes is developing PDO-certified powder variants for premium export positioning.
Organic Cheese Powder Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ingredient supply. The organic cheese powder sector exhibits tiered consolidation, with multinational dairy processors controlling certified milk supply while mid-scale spray-drying operators compete on formulation flexibility. Three archetypes dominate: cooperative-backed dairy giants with captive organic herds, flavor-system integrators offering technical service bundles, and regional dehydration specialists with niche certification expertise. Competitive intensity centers on backward integration into organic feed sourcing and exclusive supply agreements with clean-label snack manufacturers.
Within the cooperative-backed tier, Fonterra Co-operative Group Limited and Arla Foods exemplify scale-driven supply concentration, leveraging farmer-ownership structures to secure continuous organic compliance across pasture-to-powder chains. Kerry Group plc occupies a distinct position as a flavor-system integrator, anchoring relationships through formulation optimization services rather than milk supply dominance. These three entities represent divergent strategic paths: captive agricultural control versus technical service differentiation.
| Leading Market Players |
|---|
| Arla Foods |
| Fonterra Co-operative Group Limited |
| Land O'Lakes, Inc. |
| Bluegrass Ingredients, Inc. |
| Dairy Farmers of America |
| Kerry Group plc |
| Glanbia plc |
| Frontier Co-op |
| Lactosan A/S |
| Others |
Value Chain & Pricing Dynamics
Spray-dryer undercapacity in the Canterbury region constrains Fonterra's organic powder output, forcing multi-year allocation commitments that inflate spot-market premiums and lock snack manufacturers into inflexible contract structures. This utilization squeeze cascades through procurement tiers, concentrating pricing power among cooperative-backed processors with captive pasture-to-powder infrastructure.
Pricing Analysis
Volume-discount tiering separates food manufacturers negotiating multi-year offtake agreements from mid-scale clean-label brands purchasing through e-commerce platforms. Premium-mid-economy pricing differentiation tracks organic certification depth, with EU Organic Regulation compliance commanding sustained premiums over USDA National Organic Program equivalents. Cost compression in the mid-tier intensifies as Irish and Dutch cooperatives expand spray-drying capacity. Household purchasers through specialty stores exhibit highest price sensitivity; quick-service restaurant chains demonstrate lowest sensitivity due to flavor-standardization requirements.
Supply Chain Analysis
Contract-manufacturing concentration rests with Fonterra's Canterbury facilities, Kerry Group's Wisconsin and Irish plants, and Glanbia's Dutch dehydration centers. Raw material flows draw from certified organic pastures in New Zealand, Ireland, and the Netherlands, with organic maltodextrin carriers sourced from European grain cooperatives. Single-source vulnerability around Fonterra's milk solids supply creates systemic risk for multinational buyers. Distribution runs through Rotterdam's cold-chain hub for European re-export, with direct procurement platforms disintermediating traditional wholesale tiers for North American snack startups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified farm advisors capable of managing certified herd health protocols command compensation premiums that outpace general dairy agronomist wages, constraining rapid supply expansion and favoring incumbents with established technical training pipelines.
For Market Incumbents: Entrench supply security through backward integration into organic feed sourcing, securing multi-year forage contracts ahead of weather-driven volatility. Expand spray-dryer capacity in Wisconsin and Canterbury to preempt competitor entry. Lock exclusive formulation partnerships with emerging plant-based snack brands seeking dairy powder co-manufacturing expertise before these buyers develop direct cooperative relationships. For New Entrants and Emerging Players: Build out white-space positioning in low-temperature vacuum dehydration systems, where flavor-retention capabilities differentiate against legacy roller-drying incumbents. Target German sauce formulators seeking aged Gouda depth in reduced-sodium applications. Pursue direct-to-manufacturer platform sales to bypass Kerry Group's flavor-system bundling and capture mid-volume clean-label procurement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cooperative-backed processors with multi-year organic certification maintenance obligations from farmer-members. Long-term viability across the analysis window favors targets with integrated pasture-to-powder traceability systems aligned with EU Green Deal farm-to-fork mandates. Monitor blockchain verification adoption rates among Bavarian cooperatives as inflection signal for supply-chain technology differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Feed | Captive forage supply insulates Fonterra and Arla from certified grain price spikes driven by weather volatility. |
| Low-Temperature Vacuum Dehydration Scale-Up | Dutch pilot facilities near Eindhoven preserve Maillard-reactive compounds for premium sauce applications. |
| Direct-to-Manufacturer Platform Launch | E-commerce channels disintermediate Kerry Group's technical service bundling for mid-volume snack producers. |
| Blockchain Traceability Implementation | Bavarian cooperatives satisfy EU Green Deal documentation mandates for German supermarket chains. |
| Quick-Service Sauce Concentrate Partnership | Standardized flavor replication reduces kitchen labor across Amsterdam and Utrecht organic restaurant franchises. |
Study Parameters
Cross-validation between USDA National Organic Program certification databases and EU Organic Regulation audit records anchors the qualitative findings on supplier eligibility constraints. Primary interviews with spray-dryer operations managers, clean-label snack procurement directors, organic dairy cooperative board members, and EFSA regulatory affairs specialists combined with secondary validation from customs trade data, SEC dairy processor filings, and EU farm-to-fork traceability disclosures. Bottom-up capacity assessments triangulate against top-down demand modeling from Nielsen retail audit data.
Calibration against historical organic dairy price spreads and spray-dryer capacity utilization rates refines the projection framework across the analysis window. Segmentation dimensions span cheese variety, application heat-sensitivity, end-user scale tier, and distribution channel digitization. CAGRs derive from fitted growth curves on certified organic milk production and clean-label snack launch velocity. Forecast inputs incorporate EU-US organic reciprocity negotiation status and low-temperature dehydration equipment deployment timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Irish cooperatives or rapid blockchain standardization by Dutch processors would shift outcomes. Cross-checking against Fonterra's seasonal milk solids auction results is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Latin America Cheese Market
Dairy Products
Organic Dairy Market
Dairy Products
Dairy Protein Market
Dairy Products
Recombined Milk Market
Dairy Products
Japan Dairy Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
Reconstituted Milk Market
Dairy Products
North America Casein Market
Dairy Products
Recombined Milk Products Market
Dairy Products
Cheese Color Market
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
Sweet Whey Market
Dairy Products
Emmental Cheese Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Europe Milk Protein Market
Dairy Products
United Kingdom Dairy Market