
 Baby Cereal-Based Complementary Food Market | 2026-2036
Baby Cereal-Based Complementary Food Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Cereal-Based Complementary Food Market Insights
Subscription-based replenishment services is realigning how parents purchase baby cereal, shifting from episodic supermarket trips to predictable auto-delivery models. Nestlé leverages its direct-to-consumer infrastructure to capture recurring revenue streams. Danone anchors its competitive stance through specialized organic formulations. HiPP differentiates via stringent ingredient sourcing protocols that appeal to quality-sensitive households.
Baby cereal-based complementary food comprises processed grain formulations designed for infants transitioning from exclusive milk feeding, typically manufactured through extrusion cooking or drum drying to achieve digestible textures with controlled particle sizes below two millimeters. The product serves as a calorie-dense bridge to solid foods while delivering iron, zinc, and B-vitamins critical to neurological development during the six-to-twenty-four-month window. Oatmeal and rice cereal categories dominate volume due to established palatability and lower allergenic profiles, though multi-grain blends represent the fastest-growing segment as parents seek diversified nutrient matrices. Organic and fortified ingredient quality tiers command disproportionate margin pools, reflecting parental willingness to pay for certified supply chains and micronutrient guarantees.
The FDA enforces strict limits on inorganic arsenic in rice-based infant cereals, compelling reformulation toward lower-arsenic grain alternatives. EFSA maximum residue levels for pesticides and heavy metals shape formulation choices for brands distributing across European retail channels. China's NMPA and national food safety standards impose additional registration requirements for imported complementary foods. Stakeholders must monitor evolving contaminant thresholds and certification harmonization between major markets to sustain product registrations and avoid supply disruptions.
Market Dynamics
Subscription-based replenishment services are compressing purchase cycles from episodic supermarket visits to predictable auto-delivery models, locking in recurring revenue streams and reshaping brand loyalty mechanics for millennial parents in urban centers.
Growth Catalysts
- Dual-income household density:Urban China and India record rising female labor participation rates, creating time-constrained parents who prioritize convenience-driven feeding solutions over traditional home-prepared alternatives.
- EFSA contaminant threshold tightening:Stricter maximum residue levels for pesticides and heavy metals in European infant foods are accelerating premium-tier demand as parents seek certified-clean supply chains.
- Iron-fortification mandates:WHO complementary feeding guidelines emphasizing micronutrient density are driving government procurement programs in low and middle-income countries toward fortified cereal formulations.
Market Restraints
- Input cost volatility:Organic oat and rice grain prices fluctuate with climate-induced harvest variability, compressing margin pools for brands committed to certified ingredient tiers.
- Supply concentration risk:Drum drying and extrusion cooking equipment manufacturing concentrates among German and Italian engineering specialists, creating capex bottlenecks for new market entrants.
- Substitution threat:Home-blended fruit and vegetable purees prepared in high-speed domestic processors capture price-sensitive households seeking perceived freshness advantages over packaged cereals.
Strategic Opportunities
- Underpenetrated rural India:Last-mile cold chain gaps historically excluded interior markets from branded complementary foods; ambient-stable cereal formats bypass infrastructure constraints.
- Regulatory tailwind:China's NMPA streamlined registration pathways for imported organic infant foods, reducing time-to-market for foreign brands with established supply chain documentation.
- Technology convergence:Blockchain-enabled provenance tracking combined with AI-driven personalized nutrition recommendations creates subscription stickiness through transparency and customization.
Industry Challenges
- Certification timeline compression:Simultaneous FDA inorganic arsenic testing, EFSA pesticide screening, and NMPA registration requirements create multi-jurisdictional compliance bottlenecks that delay product launches.
- Talent scarcity in pediatric nutrition science:Formulation expertise bridging grain processing technology with early-life metabolic requirements concentrates among a narrow cohort of academic and industry specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Cereal-Based Complementary Food Market |
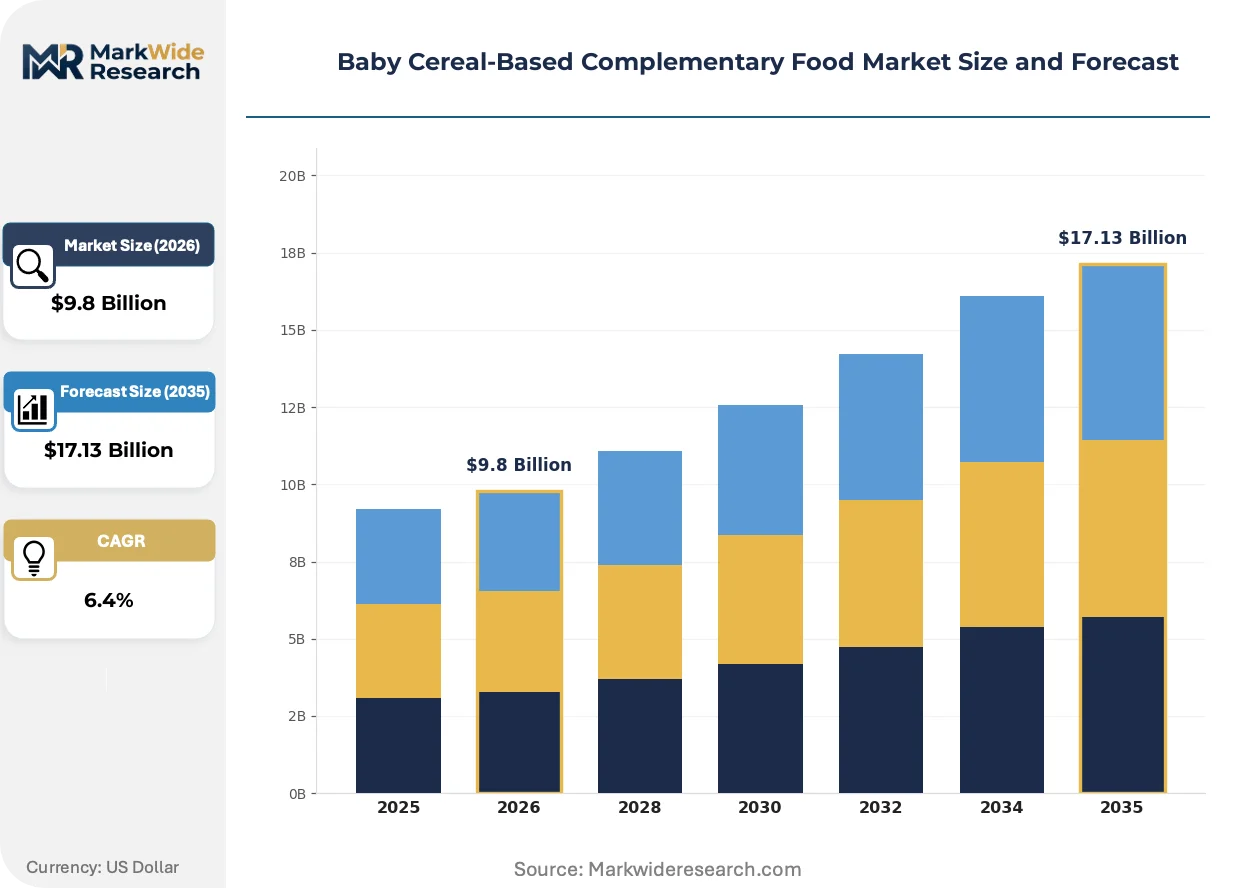
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oatmeal, Rice Cereal, Multi-Grain, Wheat Cereal Ingredient Quality: Organic, Non-GMO, Gluten-Free, Fortified Packaging Type: Boxes, Pouches, Jars, Tubs Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies |
| Companies Covered | Mead Johnson, Bellamy's Organic, Nestlé, Hero Group, Arla Foods, Danone, HiPP, Meiji, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Cereal-Based Complementary Food Market Trends and Innovations
Ingredient transparency technologies and direct-to-consumer channel architectures are converging to displace traditional retail dependency, while regulatory science advances reshape permissible formulation boundaries across major markets.
Blockchain-enabled supply chain verification is decentralizing quality assurance from centralized laboratory testing to distributed farm-to-fork documentation. Premium-tier parents in Shanghai, London, and San Francisco scan QR codes linking to soil composition data and harvest dates. This transparency architecture compresses information asymmetry between manufacturers and quality-sensitive households.
EFSA's evolving heavy metal maximum residue levels are forcing rice-cereal dominant portfolios toward multi-grain diversification. Manufacturers reformulate toward lower-arsenic alternatives like millet, sorghum, and amaranth. European retail channels now require third-party contaminant certification as a listing prerequisite, accelerating clean-label investment cycles.
Auto-replenishment algorithms embedded in parenting apps are displacing traditional grocery channel dependence. Subscription platforms capture consumption velocity data to predict reorder timing before household stock depletion. This behavioral shift concentrates most visibly among tech-sector employed parents in Seattle, Bangalore, and Shenzhen who integrate feeding logistics into broader household automation systems.
Baby Cereal-Based Complementary Food Market Segmentation
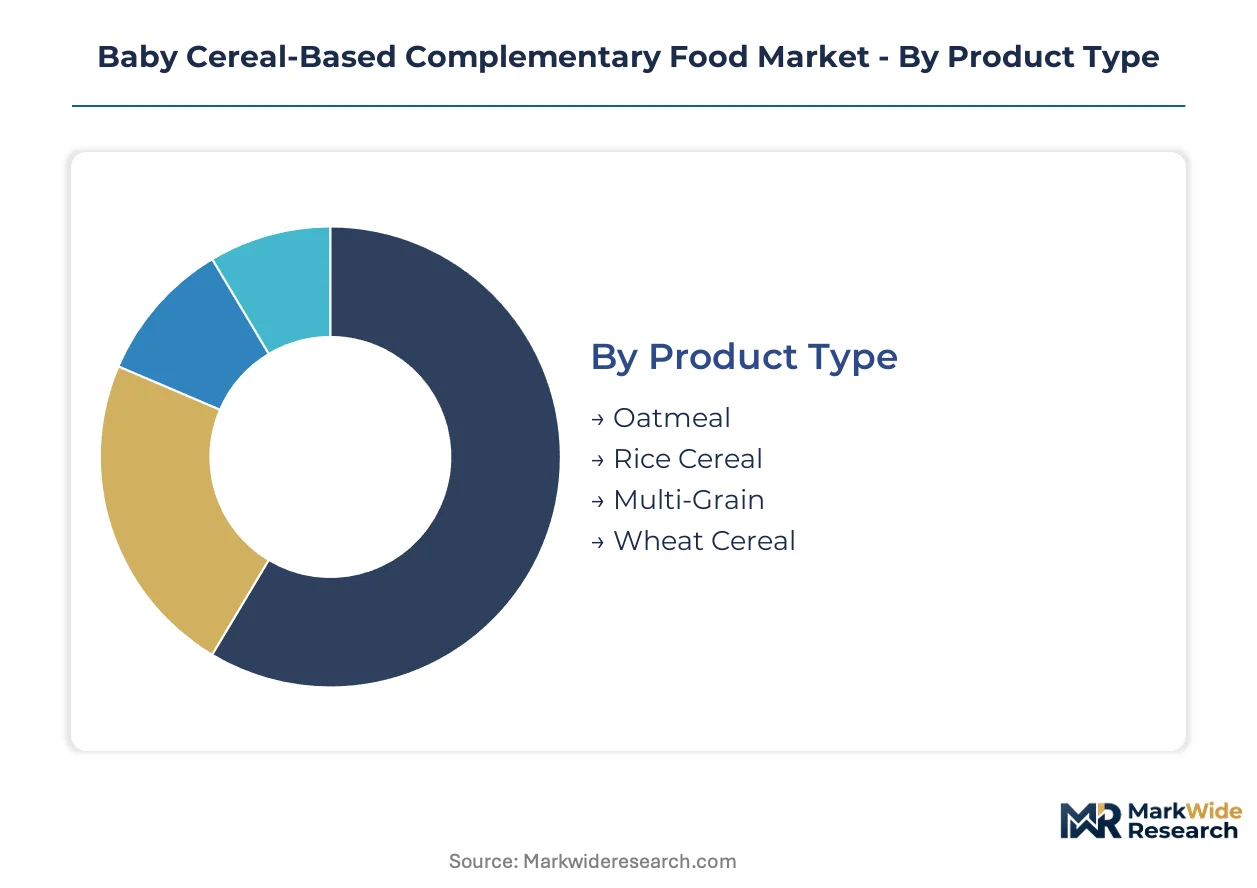
Parents cycle through cereal formats as infants develop chewing capacity and micronutrient needs intensify, creating natural upgrade pathways that manufacturers exploit through stage-gated product portfolios. Segmentation reveals where margin pools concentrate versus where volume scales, guiding resource allocation between premium innovation and mass-market penetration.
Product Type:
Texture progression from smooth purees to granular cereals drives the replacement cycle, with parents upgrading formats every four to six months as pediatric feeding guidelines recommend advancing consistency.
- Oatmeal:Rolled oat formulations processed through drum drying achieve particle sizes below two millimeters for six-month swallowing safety. Demand clusters in urban US households where pediatricians recommend oat fiber for digestive regularity, though EFSA arsenic monitoring has shifted some European parents toward alternative grains.
- Rice Cereal:Milled white rice subjected to extrusion cooking delivers hypoallergenic profiles with iron fortification at 15mg per 100g serving. Chinese parents in tier-one cities prioritize rice cereals for cultural palatability acceptance, yet FDA inorganic arsenic limits of 100 parts per billion are forcing portfolio dilution with lower-arsenic grain blends.
- Multi-Grain:Blended formulations incorporating quinoa, amaranth, and millet diversify amino acid matrices beyond single-grain limitations.
- Wheat Cereal:Semolina-based variants target Southern European markets with established durum wheat acceptance in infant diets.
Rice Cereal sits at the top of the volume ranking, with Multi-Grain climbing the fastest as contaminant-conscious parents seek diversified nutrient sources.
Ingredient Quality:
Cost tier stratification separates certification-heavy premium positioning from accessible fortified standards, with price multiples stretching from economy non-GMO bases to triple-certified organic offerings.
- Organic:USDA NOP or EU Organic certified supply chains mandate three-year soil transition periods and prohibited synthetic pesticide use. German and French parents demonstrate willingness-to-pay premiums exceeding 40% for certified organic cereals, with blockchain verification now standard for major retail listings.
- Non-GMO:Project Verified or equivalent third-party testing confirms absence of genetically modified organisms in grain sourcing. US demand concentrates in coastal metropolitan markets where retailer non-GMO shelf-set requirements create listing prerequisites independent of organic certification.
- Gluten-Free:Oat-based formulations processed on dedicated equipment prevent cross-contamination for celiac-risk infants.
- Fortified:Iron, zinc, and B-vitamin enrichment targets WHO complementary feeding guidelines for micronutrient density in low-resource settings.
Fortified commands the widest geographic footprint, while Organic captures the steepest margin expansion trajectory.
Packaging Type:
Volume-to-maturity dynamics favor single-serve convenience formats in premium urban channels against bulk economy packaging for price-sensitive household stockpiling.
- Boxes:Paperboard containers with inner plastic liners preserve shelf stability for 18-month ambient storage. Indian and Indonesian retail channels rely on box formats for last-mile ambient distribution where cold chain infrastructure remains underdeveloped.
- Pouches:Flexible laminate structures with spout closures enable single-serve portion control and reduced oxidation exposure. Subscription services in Seattle and London default to pouch formats for shipping efficiency and consumption velocity tracking.
- Jars:Glass containers with metal lug closures signal premium positioning for gifting occasions.
- Tubs:Polypropylene containers with resealable lids target multi-child households seeking bulk economy.
Boxes retain volume leadership across developing markets, though Pouches are gaining share fastest in direct-to-consumer channels.
Distribution Channel:
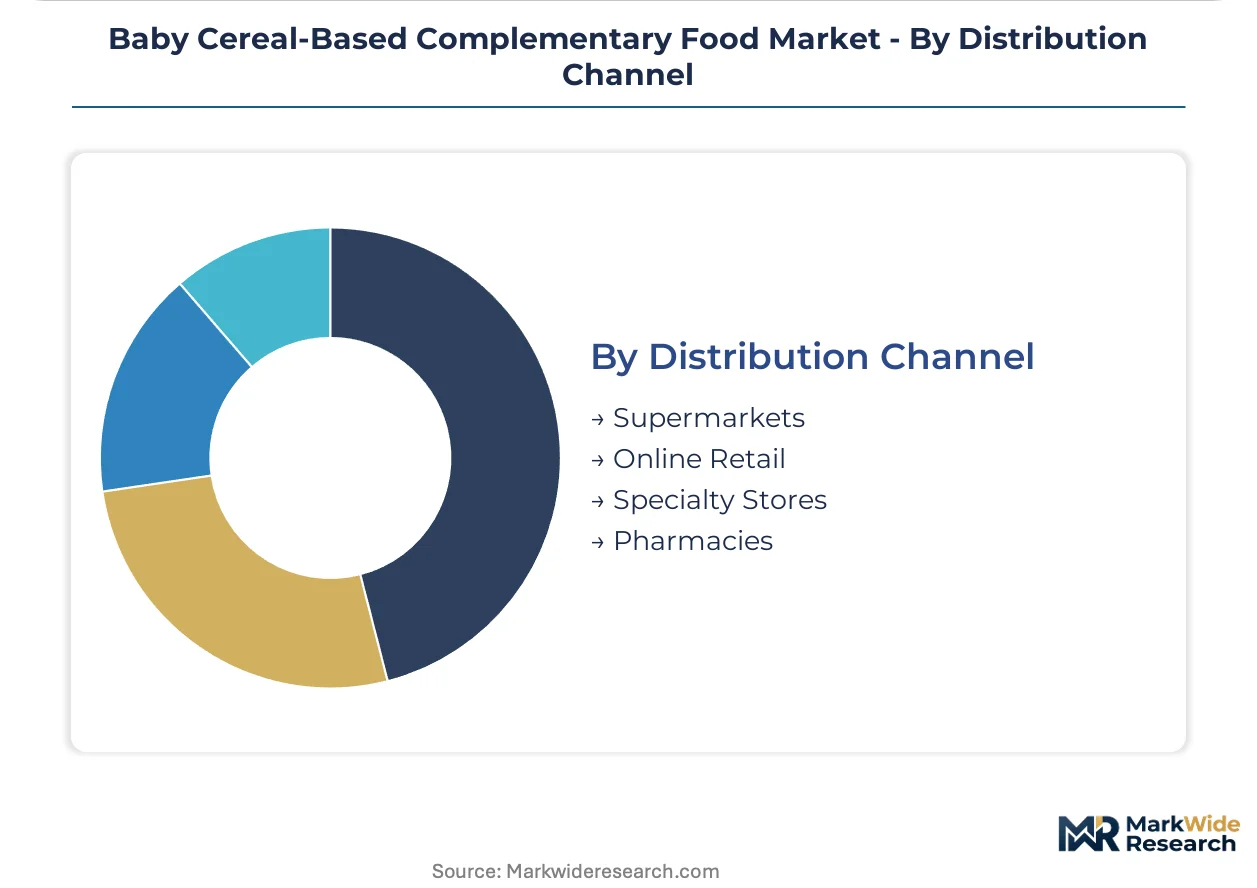
Customer-type concentration separates time-constrained dual-income households seeking replenishment automation from price-comparison shoppers prioritizing tactile evaluation.
- Supermarkets:Mass-market retail chains with dedicated baby food aisles provide shelf-space visibility and promotional velocity. Brazilian and Mexican parents rely on supermarket exclusivity for trusted brand access, with private-label penetration remaining below 15% due to safety sensitivity.
- Online Retail:Platform-based commerce with auto-replenishment algorithms captures subscription stickiness through predictive reorder timing. Chinese parents on Tmall and JD.com demonstrate highest online penetration rates globally, driven by urban logistics density and QR-code verification preferences.
- Specialty Stores:Premium baby boutiques with curated organic assortments serve quality-obsessed first-time parents.
- Pharmacies:Drugstore channels with pharmacist recommendation authority dominate Southern European and Latin American markets.
Supermarkets anchor volume in emerging economies, while Online Retail shows the most rapid channel shift acceleration in developed Asia-Pacific markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA registration pathways draw foreign brands faster than India's FSSAI compliance timelines, creating divergent market entry velocities across the two largest birth cohort nations.
China
Tier-one city parents on Tmall and JD.com drive online retail penetration for organic infant cereals, while NMPA streamlined registration reduces import documentation burdens. Shanghai and Beijing clusters concentrate demand for blockchain-verified supply chains among dual-income households.
United States
Pediatrician recommendations for oat fiber digestive benefits sustain oatmeal category dominance in urban households, though FDA inorganic arsenic limits of 100 parts per billion force rice-cereal reformulation. Seattle and San Francisco parents anchor subscription service adoption through parenting app integration.
India
Rising female labor participation in Maharashtra and Gujarat generates time-constrained parents seeking ambient-stable cereal formats that bypass cold chain gaps. FSSAI fortification standards align with government procurement programs targeting low-resource settings in interior states.
Germany
Parents demonstrate willingness-to-pay premiums exceeding 40% for EU Organic certified cereals with blockchain harvest documentation. EFSA maximum residue levels for pesticides shape formulation choices for brands distributing through Frankfurt and Munich retail channels.
Brazil
Supermarket exclusivity in São Paulo and Rio de Janeiro provides trusted brand access for safety-sensitive parents, with private-label penetration remaining below 15%. ANVISA registration requirements create compliance barriers that favor established multinational portfolios over new entrants.
Baby Cereal-Based Complementary Food Market Competitive Landscape
Top-tier vendors anchor premium organic and fortified segments, while mid-tier regional specialists compete on price-accessible formulations across emerging markets. The vendor base stratifies between multinational nutrition conglomerates with direct-to-consumer infrastructure and heritage organic brands with certified supply chain depth. Three archetypes dominate: science-backed pharmaceutical-origin nutrition companies, farm-to-fork organic purists with multi-generational brand equity, and private-label manufacturers serving retailer exclusivity arrangements. Competitive moves concentrate on portfolio diversification toward lower-arsenic grain blends and geographic expansion through regulatory harmonization strategies.
Within the pharmaceutical-origin nutrition tier, Abbott and Mead Johnson exemplify science-backed formulation credibility derived from pediatric research heritage. Nestlé anchors the multinational conglomerate archetype with direct-to-consumer infrastructure spanning subscription replenishment platforms. HiPP occupies a position within the certified organic purist tier, representing multi-generational European farm-to-fork sourcing protocols that command quality-sensitive household loyalty.
| Leading Market Players |
|---|
| Mead Johnson |
| Bellamy's Organic |
| Nestlé |
| Hero Group |
| Arla Foods |
| Danone |
| HiPP |
| Meiji |
| Abbott |
| Others |
Pricing and Supply Chain Analysis
Chicago Board of Trade oat futures volatility cascades through formulation costs into three-tier pricing structures across premium organic, certified non-GMO, and economy fortified tiers. Raw material swings compress margin pools for brands locked into long-term organic supply contracts while spot-market buyers absorb sharper cost pass-through.
Pricing Analysis
Capacity additions in Vietnam and Thailand are reshaping price floors for rice-cereal inputs as new milling capacity absorbs regional harvest variability. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and volume commitment. Cost compression in the organic tier is intensifying because climate-induced harvest variability in North American oat belts strains three-year soil transition commitments. Government procurement programs in low-resource settings exhibit highest price sensitivity, while blockchain-verified organic commands lowest elasticity among Shanghai and London dual-income households.
Supply Chain Analysis
EU Organic certification and FDA inorganic arsenic testing create dual gating requirements that filter supplier participation and concentrate procurement among documented grain cooperatives. Organic oat sourcing draws from Canada, Finland, and Sweden; rice milling concentrates in Vietnam, Thailand, and India. Supply chain risk centers on single-source vulnerability for drum drying equipment manufactured by German and Italian engineering specialists. Distribution runs through ambient-stable box formats for developing market retail penetration and flexible pouch structures for direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
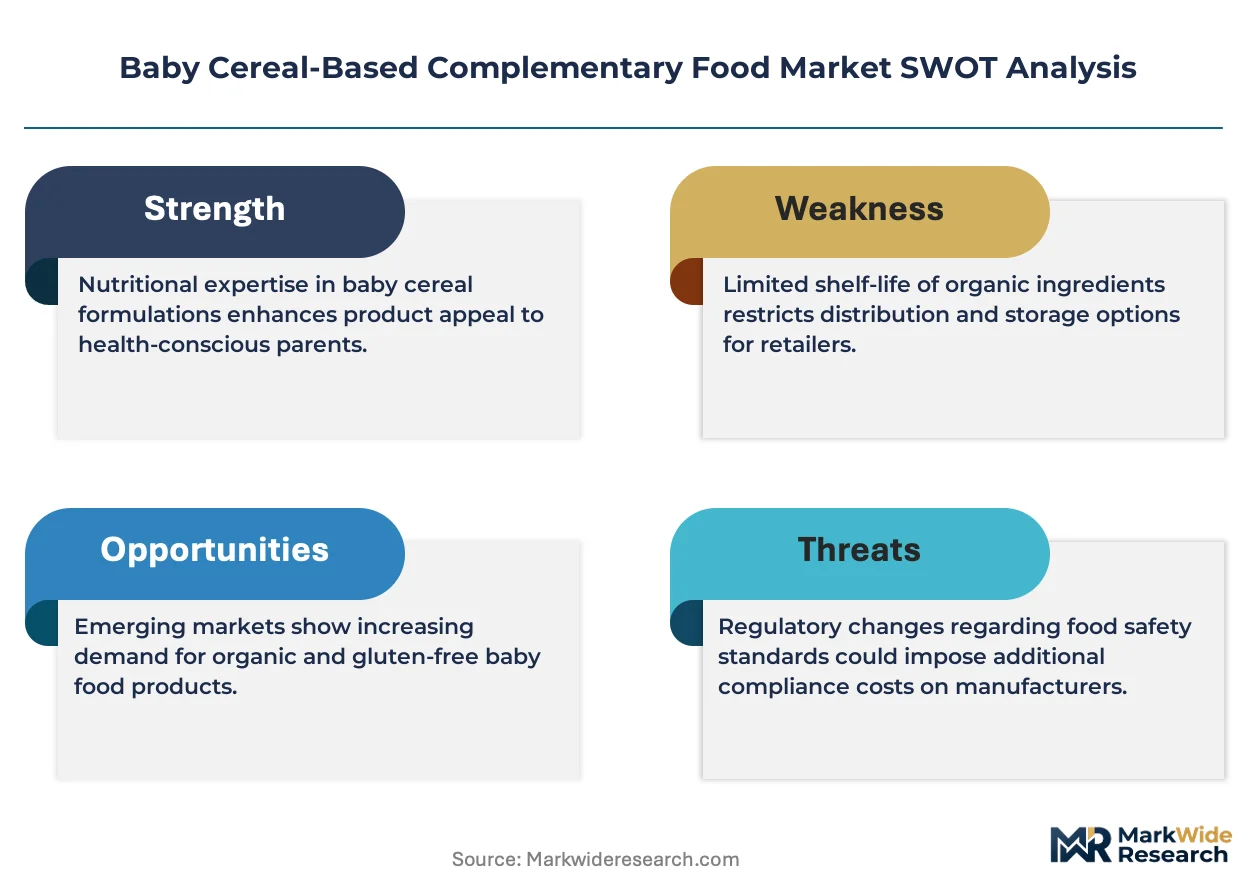
This market reads as a late-cycle quality story where parental willingness-to-pay premiums for contaminant-tested supply chains has shifted demand composition toward certified-clean tiers. The pivot from rice-dominant portfolios toward multi-grain diversification represents a structural demand reset.
For Market Incumbents: Extend portfolio diversification into lower-arsenic grain alternatives like millet, sorghum, and amaranth before FDA threshold tightening forces reactive reformulation. Deepen backward integration into certified organic acreage to defend margin position against input cost volatility. Lock in multi-year supply contracts with Scandinavian and Canadian oat cooperatives to preempt spot-market competition from emerging entrants. For New Entrants and Emerging Players: Capture underpenetrated rural Indian markets through ambient-stable box formats that bypass cold chain infrastructure gaps. Exploit streamlined NMPA registration pathways for imported organic infant foods by front-loading supply chain documentation investment. Lead with pharmacy channel partnerships in Southern European markets where clinician recommendation authority drives trial conversion. For Investors and Strategic Acquirers: Asymmetric upside sits with certified organic purists possessing multi-generational farm-to-fork sourcing protocols and established blockchain verification infrastructure. Long-term viability hinges on regulatory harmonization execution across FDA, EFSA, and NMPA jurisdictions. Watch for EFSA heavy metal threshold revisions as the signal to accelerate clean-label M&A before compliance costs escalate.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Grain Portfolio Diversification | Reduces FDA inorganic arsenic exposure while capturing contaminant-conscious parent demand in tier-one cities. |
| Direct-to-Consumer Subscription Launch | Locks recurring revenue through auto-replenishment algorithms embedded in parenting apps. |
| Blockchain Supply Chain Verification | Compresses information asymmetry for quality-sensitive households scanning QR codes in Shanghai and London. |
| Backward Integration into Organic Acreage | Captive supply of certified grain insulates margin pools from climate-induced harvest volatility. |
| Rural India Distribution Expansion | Ambient-stable formats bypass last-mile cold chain gaps that historically excluded interior markets. |
Research Methodology
Direct dialogue with pediatric nutrition formulators, grain procurement directors at complementary food manufacturers, regulatory affairs specialists navigating NMPA registration, and subscription platform operators grounded qualitative findings. Secondary validation drew from FDA enforcement reports, EFSA scientific opinions on infant food contaminants, NMPA import registration databases, and Nielsen retail audit data across urban Chinese and Indian markets. Bottom-up demand modeling and top-down category sizing were triangulated to cross-validate volume estimates.
Bottom-up segmentation analysis modeled product type progression from rice through multi-grain, ingredient quality tier stratification, packaging format channel alignment, and distribution channel shift dynamics across the projection horizon. CAGRs were derived from infant population cohort sizing, per-household consumption velocity assumptions, and price tier mix evolution. Forecast inputs included female labor participation trajectories in urban China and India, regulatory timeline assumptions for contaminant threshold revisions, and cold chain infrastructure development rates in target geographies.
Regulatory timeline acceleration, climate-induced organic harvest disruption, and subscription platform competitive entry are the dominant revision risks that could compress or extend growth trajectories. Forecasts reflect assumptions on birth rate stabilization patterns and certification harmonization progress across major markets. A model refresh is warranted upon material change in FDA inorganic arsenic enforcement posture or NMPA registration pathway modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
North America Organic Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Organic Follow Up Formula Market
Baby Food and Infant Formula
Infant Formula Market
Baby Food and Infant Formula
Organic Baby Food Market
Baby Food and Infant Formula
Cow Milk Infant Formula Market
Baby Food and Infant Formula
Goat Milk Formula Market
Baby Food and Infant Formula
Growing Up Milk Market
Baby Food and Infant Formula
Wet Cat Food Market
Baby Food and Infant Formula
Second Stage Organic Infant Formula Market
Baby Food and Infant Formula
Ready to Use Supplementary Food Market
Baby Food and Infant Formula
Middle East and Africa Organic Baby Food Market
Baby Food and Infant Formula
Infant Formula Milk Powder Market
Baby Food and Infant Formula
Organic Infant Formula Market
Baby Food and Infant Formula
Global Lactose-Free Infant Formula Market
Baby Food and Infant Formula
Russia Pet Food Market