
 Rye Bran Beta-Glucan Market | 2026-2036
Rye Bran Beta-Glucan Market Size, Share, and Industry Trends Forecast 2026-2036
Rye Bran Beta-Glucan Market Insights
Oat beta-glucan is consolidating share in the soluble fiber ingredient space, yet rye bran beta-glucan is carving distinct positioning through superior viscosity profiles and arabinoxylan co-fractionation economics. GoodMills Innovation leverages Central European milling infrastructure to secure raw material access at scale. GreenField Natural Ingredients anchors North American supply through dedicated rye bran extraction partnerships. Tate & Lyle competes with multi-cereal beta-glucan portfolios that span oat, barley, and rye sources.
Rye bran beta-glucan comprises a mixed-linkage (1,3)(1,4)-β-D-glucan polysaccharide extracted from the outer aleurone and pericarp layers of rye grain, typically yielding 8-15% beta-glucan content depending on cultivar and milling severity, with molecular weights ranging from 100 to 500 kDa that govern viscosity-building and gelation performance in food matrices. Its primary commercial purpose centers on cholesterol reduction and glycemic control claims in human nutrition, plus immunomodulatory applications in animal feed. Powder formats dominate current volume given ease of incorporation into bakery and beverage applications, while extract and concentrate grades capture disproportionate margin pools due to standardized beta-glucan content and cleaner label positioning. Functional foods and nutraceuticals represent the structurally fastest-growing application cluster, whereas animal feed maintains volume depth through poultry and swine gut health programs.
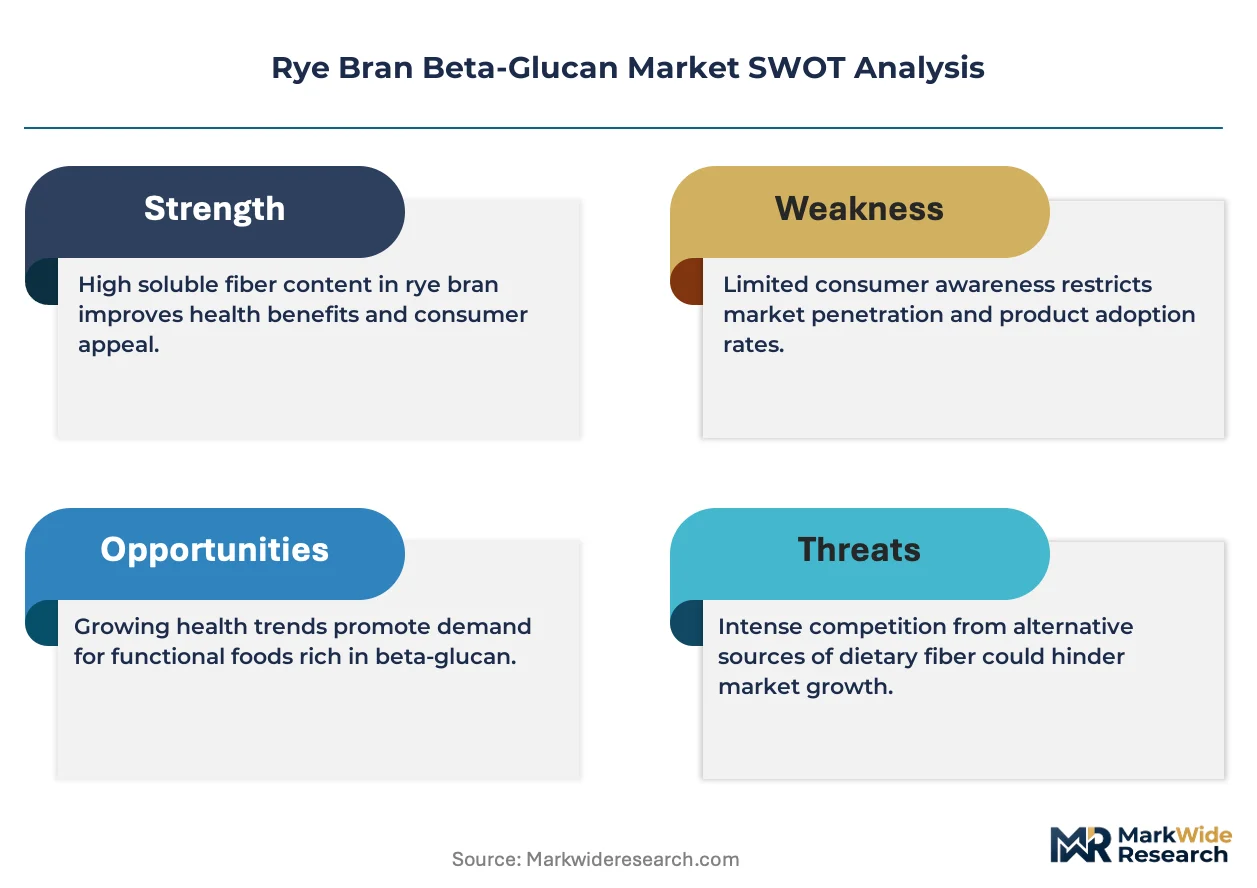
EFSA nutrition and health claims regulation shapes substantiation pathways for cholesterol-related marketing in Europe, while FDA GRAS notifications govern U.S. market access for novel rye bran extraction processes. REACH compliance and EU Green Deal bioeconomy targets are redirecting investment toward sustainable bran valorization technologies rather than commodity disposal. Stakeholders must monitor evolving glycemic health claim frameworks and decide whether to prioritize single-species purity or multi-cereal beta-glucan blending strategies.
Market Dynamics
EFSA substantiation requirements for cholesterol health claims are compressing formulation flexibility for rye bran beta-glucan suppliers, forcing investments in clinical validation infrastructure that smaller extractors cannot absorb.
Growth Catalysts
- Nordic biorefinery corridors:Swedish milling clusters near Malmö are consolidating extraction capacity, creating feedstock security for functional food manufacturers targeting glycemic control positioning.
- EU Green Deal bioeconomy targets:REACH-compliant bran valorization technologies are redirecting capital from commodity disposal toward soluble fiber ingredient production.
- Cholesterol-management formulations:German functional food manufacturers are accelerating procurement of viscosity-standardized rye bran beta-glucan for cardiovascular health product lines.
Market Restraints
- Arabinoxylan co-extraction economics:Variable yields from rye bran aleurone layers create input cost volatility that squeezes margin predictability for standardized concentrate grades.
- Oat beta-glucan substitution pressure:Established oat sourcing infrastructure and GRAS recognition in the US displace rye-derived alternatives in price-sensitive bakery applications.
- EFSA claim substantiation timelines:Extended clinical validation periods for novel molecular weight fractions delay market entry for upgraded extraction processes.
Strategic Opportunities
- Immunomodulatory animal feed:Poultry and swine gut health programs in Denmark and the Netherlands are expanding beta-glucan inclusion rates beyond current penetration levels.
- Clean-label beverage integration:Powder format standardization is enabling incorporation into ready-to-drink cholesterol management products without viscosity destabilization.
- Multi-cereal beta-glucan blending:Hybrid formulations combining rye, oat, and barley sources are opening positioning space outside single-species purity constraints.
Industry Challenges
- Clinical validation talent scarcity:Qualified biostatisticians familiar with EFSA health claim dossier requirements command premium compensation that strains mid-cap extractor budgets.
- Extraction equipment capex cycles:Continuous-flow processing systems for molecular weight fractionation require capital commitments that extend payback periods beyond typical financing horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rye Bran Beta-Glucan Market |
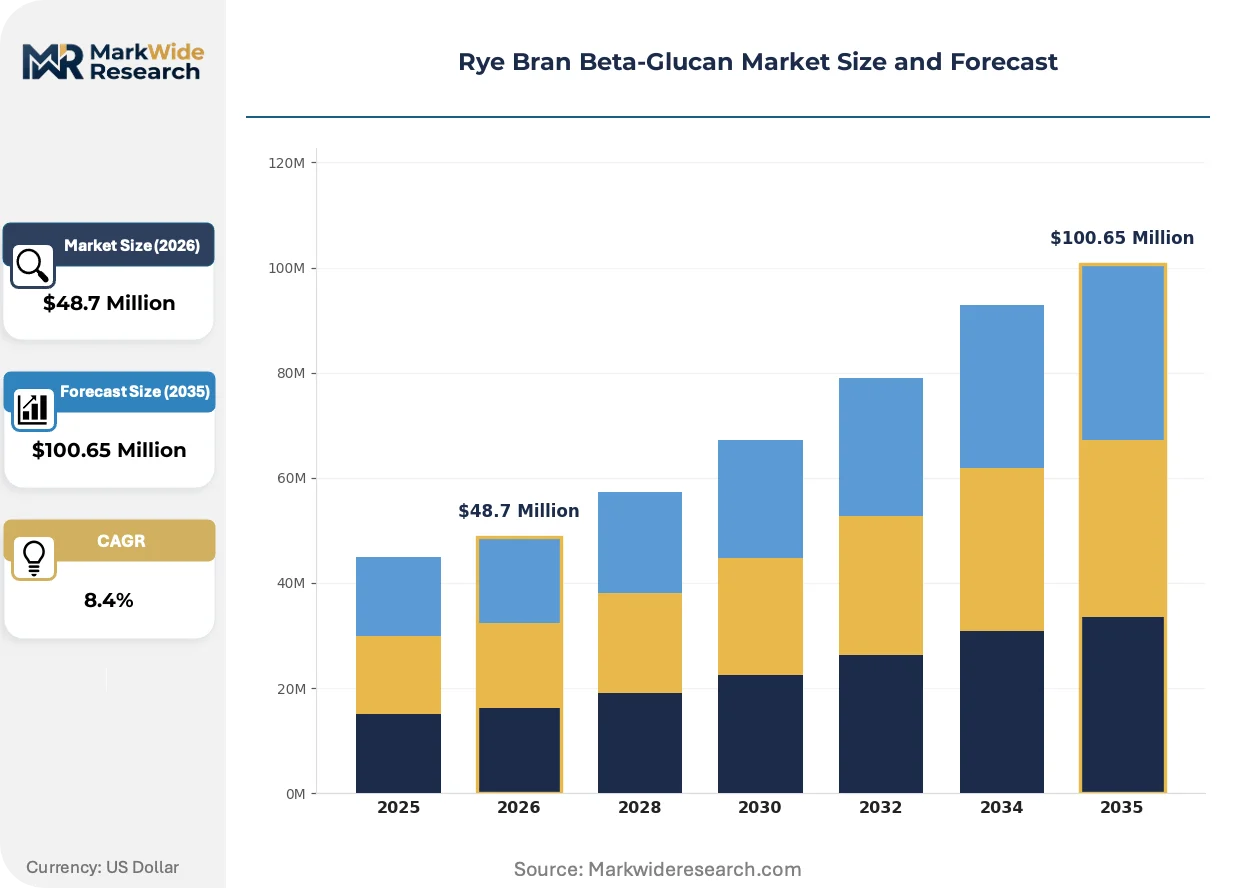
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $100.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Extract, Concentrate, Granules, Capsules Application: Functional Foods, Nutraceuticals, Dietary Supplements, Animal Feed, Cosmetics End Use Industry: Food Processing, Pharmaceutical, Personal Care, Animal Nutrition Packaging Type: Bags, Drums, Bottles, Pouches, Bulk Containers |
| Companies Covered | GoodMills Innovation, GreenField Natural Ingredients, Ceresal GmbH, Greenrize, Tate & Lyle, BENEO, Grain Millers, Lantmännen Biorefineries, Angel Yeast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rye Bran Beta-Glucan Market Trends and Innovations
Enzymatic extraction protocols and molecular weight fractionation technologies are actively compressing the performance gap between commodity bran and pharmaceutical-grade beta-glucan concentrates.
Subcritical water extraction technology is rewriting the economics of arabinoxylan co-fractionation from rye bran pericarp layers. Scandinavian biorefinery operators are retrofitting existing oat processing lines to handle rye feedstocks at commercial scale. This convergence is enabling dual-product revenue streams that improve unit economics for extraction facilities previously dependent on single-commodity output.
REACH authorization requirements for novel processing aids are tightening purity specifications for solvent residues in beta-glucan concentrates. ECHA registration deadlines are forcing extractors to document supply chain transparency for enzymatic catalysts used in molecular weight reduction steps. German functional food manufacturers are prioritizing suppliers with completed substance dossiers to avoid formulation disruption.
Long-term offtake agreements are displacing spot purchasing for standardized beta-glucan grades. Nordic milling conglomerates are locking in volume commitments from nutraceutical formulators seeking multi-year price stability. This shift is most visible in Swedish and Danish supply corridors where integrated biorefinery operators can guarantee cultivar-specific molecular weight profiles across contract durations.
Rye Bran Beta-Glucan Market Segmentation
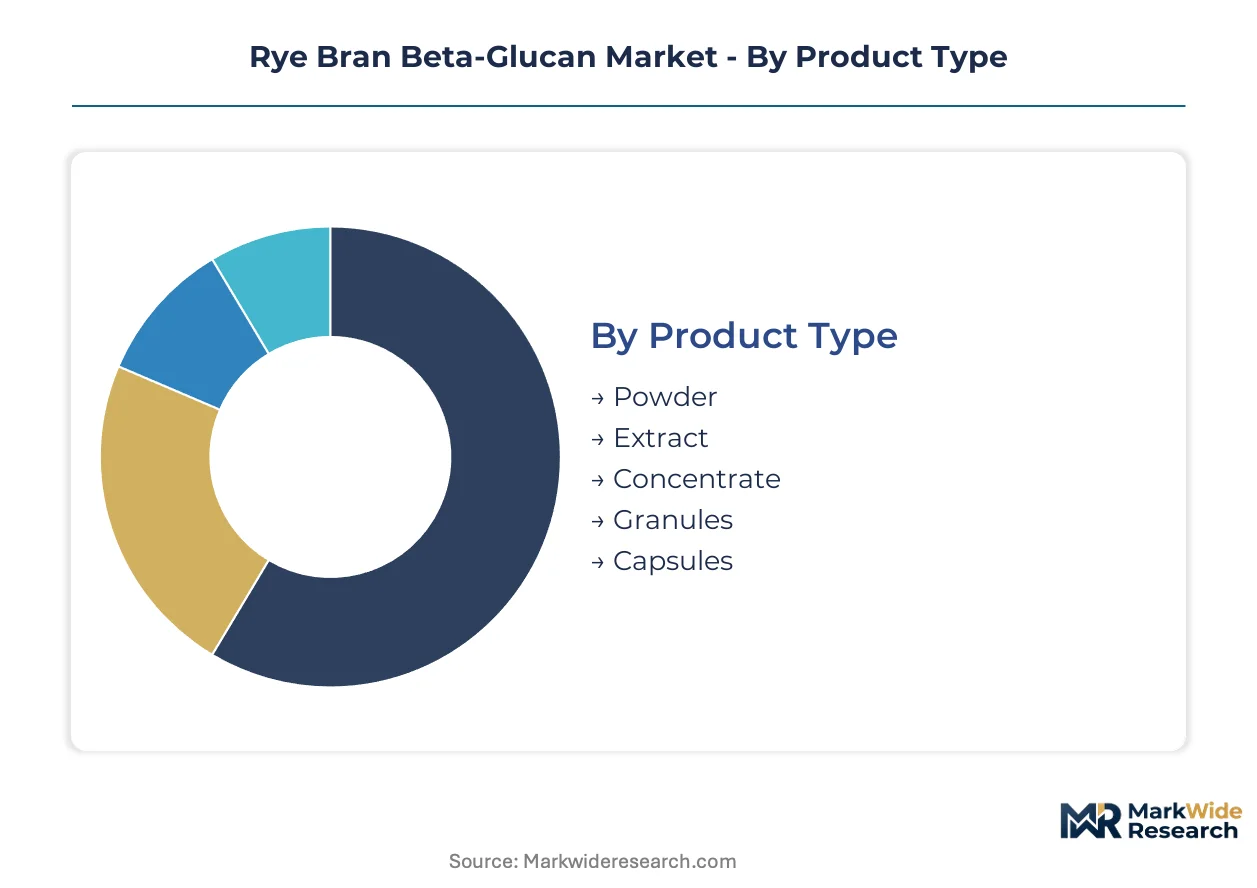
Rye bran beta-glucan suppliers must align product specifications with end-use viscosity requirements and regulatory claim pathways. Each segment category carries distinct margin profiles and technical barriers that determine competitive positioning.
Product Type:
Upgrade cycles from commodity bran to standardized concentrates are accelerating as German functional food manufacturers demand molecular weight documentation for EFSA cholesterol claims.
- Powder:Standardized particle sizes between 80-200 mesh enable uniform hydration in bakery and beverage matrices without lump formation. Bakery manufacturers in Sweden prefer this format for sourdough fiber enrichment where viscosity modulation is critical.
- Extract:Solvent-free aqueous extraction yields beta-glucan contents of 30-50% with retained molecular weight integrity for glycemic control positioning. Danish nutraceutical formulators are driving procurement of this grade for clean-label capsule applications.
- Concentrate:High-purity grades standardized to 70%+ beta-glucan content command premium positioning in pharmaceutical-adjacent nutrition.
- Granules:Agglomerated formats improve flowability for high-speed tableting operations in dietary supplement manufacturing.
- Capsules:Pre-filled dosage forms bypass powder handling complexity for direct-to-consumer cholesterol management products.
Powder sits at the top of the volume ranking, with Extract climbing the fastest.
Application:
Cost tier stratification separates clinical-grade formulations from commodity feed additives, with mid-tier nutraceutical applications capturing disproportionate margin expansion.
- Functional Foods:Cholesterol-reduction positioning in fermented dairy and baked goods requires viscosity-stable beta-glucan fractions that withstand shear processing. German dairy cooperatives near Hamburg are integrating these ingredients into drinkable yogurt formats.
- Nutraceuticals:Standardized molecular weight fractions enable precise dosing for cardiovascular health supplements with EFSA-compliant label claims. Swedish biorefinery corridors are securing long-term offtake agreements with capsule manufacturers targeting this segment.
- Dietary Supplements:Direct-to-consumer formats prioritize convenience and compliance over technical performance metrics.
- Animal Feed:Poultry and swine gut health programs in Denmark utilize lower-concentration grades where immunomodulatory effects outweigh purity requirements.
- Cosmetics:Film-forming properties of high-molecular-weight fractions support topical hydration claims in Nordic personal care formulations.
Animal Feed dominates current volume throughput, while Nutraceuticals gains share fastest on margin expansion.
End Use Industry:
Customer type concentration varies sharply across industries, with pharmaceutical-grade buyers demanding batch-level analytical documentation that food processors rarely require.
- Food Processing:Industrial bakeries and dairy manufacturers prioritize cost-stable supply contracts over molecular weight specificity for general fiber fortification.
- Pharmaceutical:cGMP-compliant manufacturing and validated analytical methods for beta-glucan content and purity are non-negotiable entry requirements.
- Personal Care:Cosmetic formulators seek film-forming and moisture-retention functionality from high-molecular-weight rye bran fractions.
- Animal Nutrition:Feed compounders in the Netherlands are expanding beta-glucan inclusion rates beyond current penetration in broiler gut health programs.
Food Processing anchors volume demand, with Animal Nutrition expanding most quickly on gut health science validation.
Packaging Type:
Supply concentration in Nordic milling clusters favors bulk formats for integrated biorefinery operators, while downstream formulators require unitized packaging for manufacturing flexibility.
- Bags:Multi-wall paper and woven polypropylene formats dominate intra-European ingredient distribution for mid-scale food manufacturers.
- Drums:Steel and fiber drums with nitrogen flushing protect hygroscopic concentrates during extended storage for pharmaceutical and nutraceutical customers.
- Bottles:PET and HDPE containers serve retail-ready dietary supplement and cosmetic ingredient positioning.
- Pouches:Flexible formats reduce shipping cube for e-commerce direct-to-consumer supplement brands.
- Bulk Containers:Tote bins and tanker deliveries minimize handling costs for integrated food processing facilities with dedicated intake systems.
Bulk Containers lead volume ranking, with Pouches gaining share fastest on e-commerce supplement channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish biorefinery corridors near Malmö anchor the industry's geographic concentration, with Nordic milling clusters driving feedstock security for cholesterol-management formulations. German functional food manufacturers accelerate procurement of viscosity-standardized grades. Danish and Dutch animal nutrition programs expand beta-glucan inclusion rates.
Germany
Functional food manufacturers near Hamburg integrate rye bran beta-glucan into drinkable yogurt formats for cardiovascular health positioning. EFSA nutrition and health claims regulation tightens substantiation requirements for soluble fiber ingredients, forcing investments in clinical validation infrastructure. The North Rhine-Westphalia milling belt secures long-term supply contracts with standardized molecular weight documentation.
Sweden
Nordic biorefinery operators retrofit existing oat processing lines to handle rye feedstocks at commercial scale. EU Green Deal bioeconomy targets redirect capital from commodity bran disposal toward soluble fiber ingredient production. The Malmö corridor consolidates extraction capacity, creating dual-product revenue streams through arabinoxylan co-fractionation economics.
Denmark
Poultry and swine gut health programs expand beta-glucan inclusion rates beyond current penetration levels in broiler operations. REACH compliance requirements for novel processing aids tighten purity specifications for solvent residues in concentrates. Copenhagen-area feed compounders lock in multi-year offtake agreements with integrated biorefinery operators.
Netherlands
Animal nutrition formulators in the Dutch feed belt prioritize immunomodulatory grades where efficacy outweighs purity requirements. ECHA registration deadlines force extractors to document supply chain transparency for enzymatic catalysts. Rotterdam-adjacent distribution hubs enable just-in-time delivery to compounders serving Benelux livestock operations.
United States
North American supply chains anchor through dedicated rye bran extraction partnerships serving beverage and bakery applications. FDA GRAS notifications govern market access for novel extraction processes with molecular weight fractionation steps. Midwest grain handling infrastructure supports toll processing arrangements for standardized concentrate grades.
Rye Bran Beta-Glucan Market Competitive Landscape
Global majors compete with regional champions across multi-cereal beta-glucan portfolios versus single-species purity positioning. The vendor base stratifies into three tiers: integrated milling conglomerates with captive raw material access, specialized extraction houses focusing on molecular weight standardization, and toll processors serving geographic niche markets. Dominant competitive moves include backward integration into Nordic biorefinery corridors and technology licensing agreements for subcritical water extraction protocols.
Among Central European milling-based operators, GoodMills Innovation exemplifies the integrated conglomerate archetype with scale advantages in raw material procurement. GreenField Natural Ingredients occupies a position as the North American supply anchor through dedicated extraction partnerships. Tate & Lyle represents the diversified global major competing across oat, barley, and rye beta-glucan sources rather than single-species concentration. These three entities collectively illustrate the strategic tension between geographic feedstock control and multi-cereal portfolio breadth.
| Leading Market Players |
|---|
| GoodMills Innovation |
| GreenField Natural Ingredients |
| Ceresal GmbH |
| Greenrize |
| Tate & Lyle |
| BENEO |
| Grain Millers |
| Lantmännen Biorefineries |
| Angel Yeast |
| Others |
Pricing and Supply Chain Analysis
Concentrate-grade premiumization against commodity powder volumes creates a bifurcated margin architecture that simultaneously rewards molecular weight documentation in German nutraceutical procurement and punishes undifferentiated bran disposal in Baltic milling operations. This tier divergence manifests in long-term offtake premiums for EFSA-substantiated cholesterol claims while spot markets for feed-grade material absorb arabinoxylan co-extraction volatility.
Pricing Analysis
Input-cost pass-through from rye cultivar availability and enzymatic catalyst pricing governs contract structures across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade concentrates with batch-level analytical documentation from industrial bakery powders and animal feed dilutions. Pricing pressure stems from oat beta-glucan substitution in US GRAS-recognized applications where established sourcing infrastructure undercuts rye-derived alternatives. Food processors exhibit highest price sensitivity due to volume procurement and viscosity-threshold flexibility, while pharmaceutical buyers accept premium positioning for cGMP compliance and validated purity metrics.
Supply Chain Analysis
Dual-sourcing requirements from German functional food manufacturers mandate multi-supplier qualification across Swedish biorefinery corridors and North Rhine-Westphalia milling belts. Geographic supply concentration centers on Sweden, Germany, and Denmark where integrated operators control cultivar-specific molecular weight profiles. Raw material dependencies draw from Nordic rye cultivation, aqueous extraction solvents, and enzymatic catalysts subject to ECHA registration timelines. Single-source vulnerability concentrates in Malmö-adjacent extraction capacity where arabinoxylan co-fractionation economics hinge on continuous-flow processing uptime. Distribution runs through Rotterdam-adjacent hubs for Benelux compounders and Hamburg-area dairy cooperatives for drinkable yogurt integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on enzymatic extraction cost-down curves and concentrate-grade penetration into pharmaceutical-adjacent nutrition where documentation premiums offset commodity powder compression.
For Market Incumbents: Lock in cultivar-specific supply contracts across Nordic biorefinery corridors before EFSA substantiation timelines harden qualification barriers for smaller extractors. Prioritize backward integration into Malmö-area milling infrastructure to secure feedstock security against oat beta-glucan displacement in price-sensitive bakery applications. Defensive patent positioning around subcritical water extraction protocols preserves technology licensing revenue streams. For New Entrants and Emerging Players: Enter via toll processing arrangements with Midwest US grain handlers where FDA GRAS notification pathways for novel molecular weight fractions remain less congested than EFSA dossier requirements. White-space concentration sits with immunomodulatory animal feed grades in Dutch poultry operations where efficacy thresholds permit lower-purity positioning and faster penetration. Direct-to-consumer capsule formats bypass formulation complexity and channel conflict with established nutraceutical incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized extraction houses possessing completed REACH substance dossiers and validated clinical validation infrastructure for cholesterol health claims. Long-term viability through the projection horizon favors operators with dual-product revenue streams from arabinoxylan co-fractionation that improve unit economics beyond single-commodity dependence. Signal to monitor: EFSA glycemic health claim framework expansion that would unlock additional label positioning space for viscosity-standardized fractions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nordic Milling | Captive rye bran supply secures molecular weight consistency for EFSA cholesterol claims. |
| Subcritical Water Extraction Licensing | Technology transfer agreements monetize proprietary arabinoxylan co-fractionation protocols. |
| Long-term Offtake Agreements | Multi-year contracts with German dairy cooperatives reduce spot market exposure. |
| Clinical Validation Infrastructure Investment | In-house biostatistics capabilities compress EFSA dossier preparation timelines. |
| Multi-cereal Beta-glucan Blending | Hybrid formulations combine rye, oat, and barley sources outside single-species constraints. |
Research Methodology
Bottom-up functional food and nutraceutical modeling reconciled against top-down extraction capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Nordic biorefinery operators, procurement leads at German dairy cooperatives, regulatory affairs specialists familiar with EFSA health claim pathways, and feed compounders in Dutch poultry operations were validated against secondary sources including EFSA published opinions, ECHA registration databases, EU customs trade data, and SEC filings from diversified ingredient majors. Triangulation across supply-side installation counts and demand-side formulation penetration ensures cross-validation of volume estimates.
Historical trendline analysis of soluble fiber ingredient adoption patterns informs the projection framework across the analysis window. Segmentation dimensions modeled include product type hierarchy, application tier stratification, end-use industry concentration, and packaging format evolution. CAGRs derive from regression analysis of documented capacity expansions and procurement contract disclosures. Industry-specific forecast inputs incorporate EFSA substantiation pipeline status and REACH authorization timelines for novel enzymatic processing aids.
Inputs from EFSA opinion databases and Nordic milling consortium disclosures were available through the study window; gaps in private-label contract pricing introduce uncertainty bands around concentrate-grade margin estimates. Forecasts reflect documented assumptions regarding clinical validation completion rates and regulatory pathway timelines. Deviation in EFSA glycemic health claim authorization timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Phytogenic Market
Ingredients
Corn-Based Ingredients Market
Ingredients
Pig Protein Concentrate Market
Ingredients
Soybean Meal Market
Ingredients
Fonio Flour Market
Ingredients
Wheat Gluten Market
Ingredients
Egg Yolk Lecithin Market
Ingredients
Marine Ingredients Market
Ingredients
South America Agar Market
Ingredients
Cocoa Butter Market
Ingredients
Omega 6 Market
Ingredients
Omega 3 Ingredients Market
Ingredients
North America Dairy Protein Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
Pea Flour Market
Ingredients
Resistant Starch Market