
 North America Algae Omega-3 Ingredients Market | 2026-2036
North America Algae Omega-3 Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Algae Omega-3 Ingredients Market Analytics
Infant formula is consolidating as the fastest-growing end-use vertical for algae-derived omega-3, displacing traditional fish oil sourcing across North American pediatric nutrition portfolios. DSM-Firmenich leverages its fermentation technology leadership to supply pharmaceutical-grade DHA to formula manufacturers across the United States and Canada. Cargill anchors its position through backward integration into strain development and controlled-environment cultivation facilities. Corbion N.V. differentiates via specialized lipid fractionation capabilities that yield customized EPA-to-DHA ratios for premium applications.
Algae omega-3 ingredients comprise polyunsaturated fatty acids—principally docosahexaenoic acid (DHA), eicosapentaenoic acid (EPA), and alpha-linolenic acid (ALA)—extracted from phototrophic or heterotrophic microalgae through cold-press or supercritical CO2 extraction processes achieving purity thresholds above 40% total omega-3 content; these lipids serve as vegan alternatives to marine fish oils in applications requiring precise fatty acid profiles and freedom from ocean-borne contaminants. DHA-rich algal oil dominates current revenue pools due to its non-negotiable inclusion in infant formula formulations, while EPA-rich oil represents the fastest-expanding category as sports nutrition brands reformulate recovery products around plant-based anti-inflammatory positioning. Softgel form factors command premium shelf positioning in dietary supplements, though powder formats gain traction in functional foods where clean-label solubility requirements constrain oil-based incorporation.
FDA GRAS determinations and USDA organic certification requirements shape ingredient marketability and retail placement across the United States, while Health Canada's Natural and Non-prescription Health Products Directorate governs omega-3 potency claims and label substantiation north of the border. The EPA's biotechnology oversight under the Toxic Substances Control Act additionally constrains novel genetically engineered algal strains entering commercial production. Stakeholders must monitor pending FDA guidance on qualified health claims for algae-sourced EPA and DHA in cardiovascular applications, as this regulatory signal will determine whether ingredient premiums justify expanded cultivation capacity investments.
Market Dynamics
FDA GRAS notifications for algal DHA and EPA ingredients are consolidating supply contracts with infant formula manufacturers, compressing qualification timelines and locking in multi-year purchase agreements before novel strain technologies reach commercial scale.
Growth Catalysts
- Health Canada NNHPD potency claims:Regulatory clarity on omega-3 label substantiation accelerates product registration for Canadian dietary supplement brands seeking differentiation from US competitors.
- Heterotrophic fermentation:Closed-system cultivation technology eliminates seasonal biomass variability, enabling pharmaceutical-grade DHA production with contaminant profiles below fish oil baselines.
- California functional food cluster:Concentrated demand from plant-based beverage and dairy-alternative formulators creates captive offtake for algae-derived lipid emulsions.
Market Restraints
- Sugar feedstock cost volatility:Corn dextrose and glucose prices determine heterotrophic cultivation economics, with drought conditions in Midwest grain belts compressing margin structures.
- Great Lakes nutraceutical manufacturing concentration:Single-region dependency for extraction and encapsulation capacity exposes supply chains to winter logistics disruptions and labor tightness.
- EPA biotechnology oversight:Novel genetically engineered algal strains face Toxic Substances Control Act pre-manufacture notification requirements that extend development timelines by 18-24 months.
Strategic Opportunities
- Canadian prairie contract cultivation:Underutilized agricultural infrastructure in Alberta and Saskatchewan offers low-cost controlled-environment facilities for phototrophic strain production.
- Sports nutrition EPA positioning:Plant-based anti-inflammatory claims in recovery formulations represent untapped white space beyond infant formula's DHA dominance.
- USDA organic certification:Premium tier pricing for certified organic algal oil commands shelf placement in natural channel retail with limited supplier competition.
Industry Challenges
- Lipid fractionation specialist scarcity:Customized EPA-to-DHA ratio production requires expertise in supercritical CO2 extraction parameter optimization that outpaces current technical training pipelines.
- Dual jurisdiction compliance:Simultaneous FDA GRAS and Health Canada NNHPD dossier preparation strains regulatory affairs capacity for mid-scale ingredient suppliers.
- Legacy fish oil specification inertia:Infant formula manufacturers maintain entrenched analytical methods and release criteria that algae-derived alternatives must retrofit without process disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Algae Omega-3 Ingredients Market |
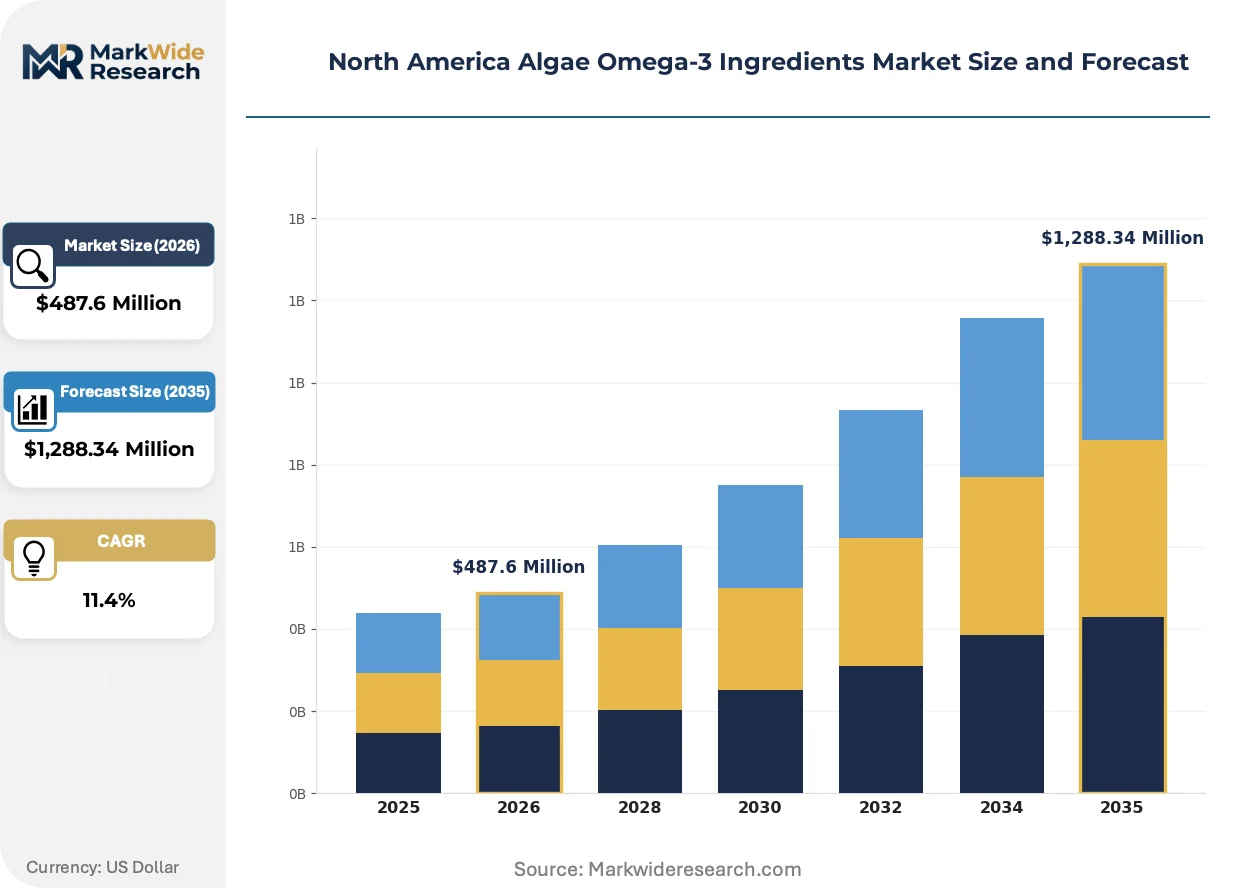
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Algal Oil, DHA Rich Oil, ALA Supplement, EPA Rich Oil End User: Food & Beverage, Nutraceuticals, Dietary Supplements, Cosmetics Form: Liquid, Powder, Capsule, Softgel Application: Functional Foods, Sports Nutrition, Infant Formula, Animal Nutrition |
| Companies Covered | Cargill, Archer Daniels Midland Company, Corbion N.V., DSM-Firmenich, BASF SE, Polaris Nutritional Lipids, Cyanotech Corporation, Neptune Wellness Solutions Inc., Algarithm Ingredients Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Algae Omega-3 Ingredients Market Evolving Landscape
Bioprocess engineering advances are collapsing the cost gap between algal and marine omega-3 sources, while regulatory harmonization efforts across US-Canada border jurisdictions reshape competitive positioning for cross-border suppliers.
Supercritical CO2 extraction technology is converging with continuous processing architectures to enable real-time lipid fractionation with purity thresholds exceeding 50% total omega-3 content. Infant formula manufacturers in Illinois and Ohio are piloting these systems to secure pharmaceutical-grade DHA supply chains independent of fish oil price volatility. The technology is converging with automated in-line analytics that compress batch release timelines from weeks to hours.
Health Canada's pending modernization of Natural Health Product regulations will streamline potency claim substantiation for algae-sourced EPA and DHA, reducing label amendment review periods. This regulatory revision forces US exporters to harmonize dossier formats for simultaneous FDA and NNHPD submission. Dietary supplement brands targeting dual-market distribution are pre-positioning compliant packaging ahead of implementation.
Clean-label solubility requirements in functional foods are displacing traditional softgel delivery formats with powder and emulsion technologies. Beverage manufacturers in California's plant-based cluster are adopting algae-derived lipid nanoemulsions for transparent fortification without sensory defects. Sports nutrition verticals in Colorado and Utah represent the most visible adoption geography, with recovery drink launches featuring EPA-rich algal oil positioning against turmeric and tart cherry extracts.
North America Algae Omega-3 Ingredients Market Segmentation
Segmentation in the North America algae omega-3 market reveals how ingredient specifications, delivery formats, and end-use requirements create distinct procurement patterns. Buyers prioritize different fatty acid profiles, regulatory certifications, and processing technologies depending on their target consumer base and channel positioning.
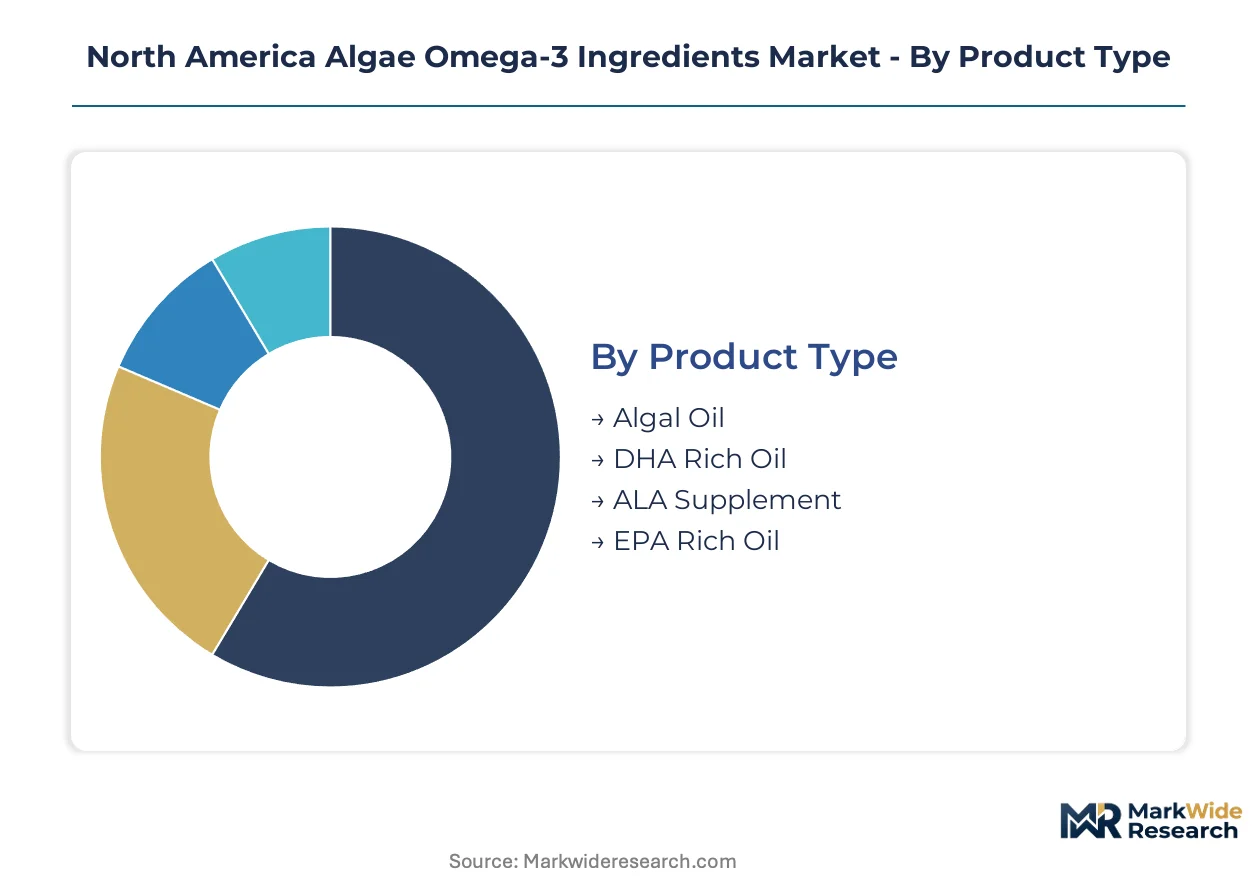
Product Type:
Buyers differentiate by EPA-to-DHA ratio requirements and whether applications demand single-fatty-acid purity or blended formulations.
- Algal Oil:Crude or refined whole-cell lipid extracts containing mixed omega-3 profiles serve cost-sensitive fortification applications in plant-based dairy alternatives. California beverage manufacturers source these emulsions for clean-label transparency without fish-derived allergen declarations.
- DHA Rich Oil:Concentrated docosahexaenoic acid formulations exceeding 40% purity by weight anchor infant formula supply contracts across Illinois and Ohio manufacturing facilities. FDA GRAS notifications for specific DHA algal strains lock in multi-year purchase agreements with pediatric nutrition brands seeking contaminant-free alternatives to marine fish oils.
- ALA Supplement:Alpha-linolenic acid derived from phototrophic cultivation provides vegan-sourced essential fatty acid for dietary supplement brands targeting plant-based positioning in natural channel retail.
- EPA Rich Oil:Eicosapentaenoic acid concentrates support anti-inflammatory claims in sports nutrition recovery formulations across Colorado and Utah.
DHA Rich Oil leads volumes today; EPA Rich Oil is gaining share fastest.
End User:
Channel selection determines regulatory pathway complexity and margin structure, with pharmaceutical-grade requirements commanding premium pricing over food-grade specifications.
- Food & Beverage:Plant-based dairy and functional beverage manufacturers in California's formulation cluster incorporate algal lipid nanoemulsions for transparent fortification without sensory defects or oxidation off-notes.
- Nutraceuticals:Health Canada NNHPD-registered products require potency claim substantiation that strains regulatory affairs capacity for cross-border suppliers serving Canadian pharmacy and practitioner channels.
- Dietary Supplements:Softgel and gummy delivery formats dominate US natural channel and mass retail placement, with FDA GRAS status enabling speed-to-market advantages over novel ingredient competitors.
- Cosmetics:Topical applications leverage algal omega-3 anti-inflammatory properties in prestige skincare formulations, though volumes remain constrained by formulation stability challenges and competing plant oil alternatives.
Dietary Supplements captures the largest revenue pool; Nutraceuticals climbs fastest on regulatory clarity.
Form:
Processing intensity and bioavailability engineering separate commodity-grade oils from value-added delivery systems.
- Liquid:Bulk oil formats serve food manufacturing and softgel encapsulation operations concentrated in the Great Lakes nutraceutical belt, with cold-chain logistics requirements limiting distribution radius.
- Powder:Microencapsulated and spray-dried lipid powders enable clean-label solubility in functional foods where oil-based incorporation creates sensory or stability defects; California's plant-based cluster drives adoption.
- Capsule:Two-piece hard-shell formats accommodate powder and oil fills for vegetarian-positioned supplement brands seeking alternatives to gelatin softgels in natural channel retail.
- Softgel:Gelatin and plant-based shell technologies command premium shelf positioning in dietary supplements, with enteric coating options expanding for EPA-rich formulations targeting sports nutrition.
Softgel maintains volume leadership; Powder expands most quickly on functional food demand.
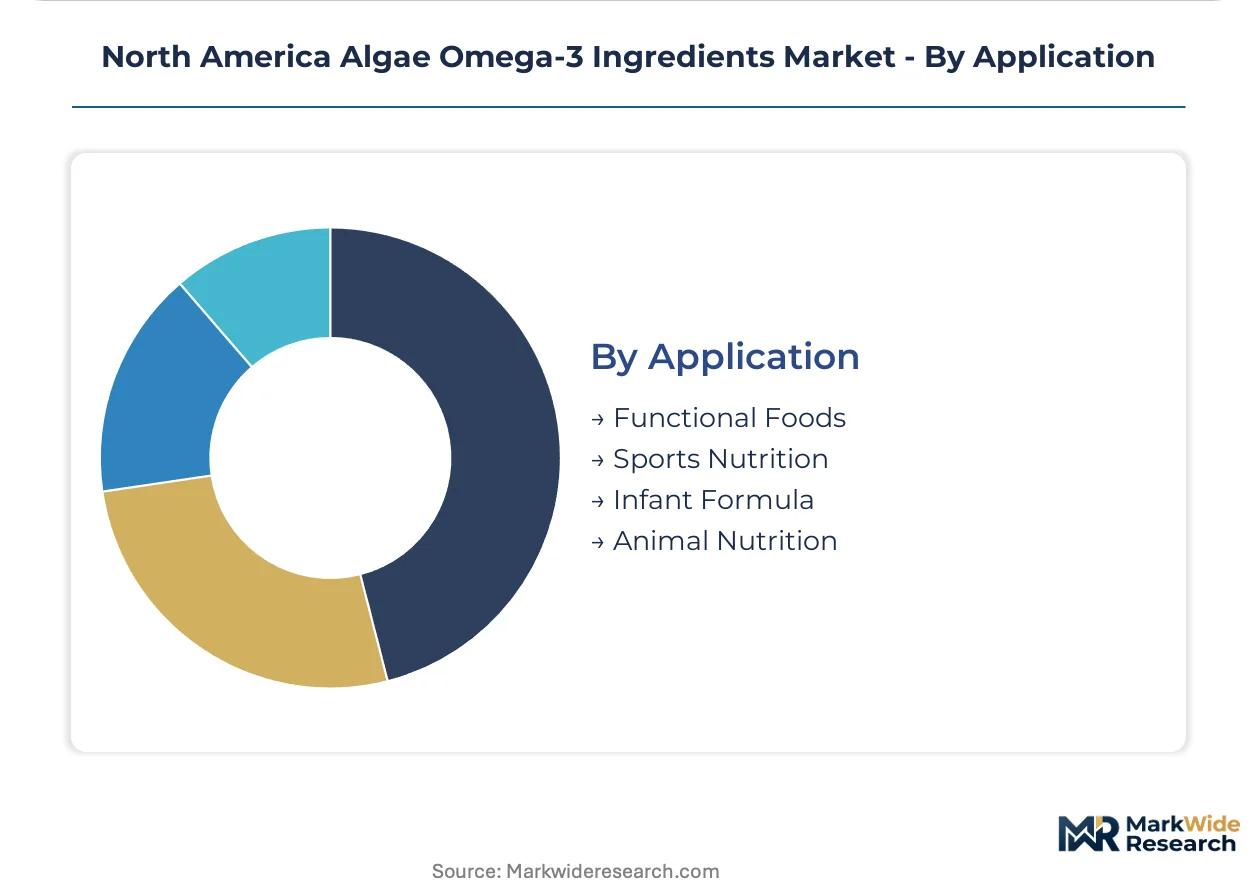
Application:
Regulatory scrutiny intensity and clinical substantiation requirements create tiered market access barriers across end-use verticals.
- Functional Foods:Beverage and dairy-alternative formulators in California adopt algae-derived lipid emulsions for transparent omega-3 fortification without fish-derived sensory markers or allergen labeling.
- Sports Nutrition:EPA-rich algal oil positions against turmeric and tart cherry extracts in recovery drink launches across Colorado and Utah, with plant-based anti-inflammatory claims capturing endurance athlete segments.
- Infant Formula:Pharmaceutical-grade DHA specifications dominate procurement criteria for Illinois and Ohio manufacturing facilities, with multi-year supply contracts locking in fermentation-derived alternatives to fish oil price volatility.
- Animal Nutrition:Pet food and aquaculture feed applications represent emerging offtake for algal omega-3 as sustainable alternatives to fish meal and fish oil in premium positioning strategies.
Infant Formula anchors current volumes; Sports Nutrition shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting fermentation capacity toward jurisdictions with streamlined biotechnology oversight and lower cost-of-compliance structures, while extraction and encapsulation operations concentrate near demand clusters to minimize cold-chain logistics exposure.
United States
FDA GRAS notifications for algal DHA and EPA strains anchor multi-year supply contracts with infant formula manufacturers in Illinois and Ohio. The EPA's Toxic Substances Control Act pre-manufacture notification requirements constrain novel genetically engineered strain commercialization timelines. California's functional food cluster in the San Francisco Bay Area and Los Angeles corridor drives demand for lipid nanoemulsions in plant-based beverages.
Canada
Health Canada's Natural and Non-prescription Health Products Directorate governs omega-3 potency claims and label substantiation, creating regulatory clarity that accelerates product registration for domestic dietary supplement brands. Prairie provinces Alberta and Saskatchewan offer underutilized agricultural infrastructure for controlled-environment phototrophic cultivation at lower facility costs than US coastal markets. The Great Lakes nutraceutical manufacturing belt extends into southern Ontario, concentrating extraction and softgel encapsulation capacity.
Mexico
Proximity to US Southwest distribution hubs positions northern border states as emerging contract cultivation sites for heterotrophic fermentation feedstock processing. Mexico's national health regulator COFEPRIS maintains aligned supplement registration pathways that facilitate cross-border product flows. Manufacturing investment in Nuevo León and Baja California targets duty-advantaged supply to California's plant-based food cluster.
North America Algae Omega-3 Ingredients Market Competitive Landscape
Backward integration into strain development and controlled-environment cultivation dominates the current landscape, with fermentation technology leadership separating pharmaceutical-grade suppliers from commodity-grade competitors. The vendor base stratifies across three tiers: integrated agribusiness conglomerates with captive biotechnology divisions, specialized lipid fractionation houses with supercritical CO2 extraction capabilities, and regional contract manufacturers serving private-label supplement brands. Capacity expansion in Canadian prairie provinces and strategic partnerships for nanoemulsion delivery technology represent the two prevailing competitive vectors.
Within the integrated agribusiness tier, Cargill and Archer Daniels Midland Company exemplify upstream control over heterotrophic cultivation feedstocks and fermentation infrastructure. DSM-Firmenich occupies a position representing pharmaceutical-grade DHA supply to pediatric nutrition portfolios, while Corbion N.V. anchors the specialized lipid fractionation segment with customized EPA-to-DHA ratio capabilities. These three entities collectively illustrate how technology ownership and regulatory dossier depth determine contract eligibility for premium infant formula and nutraceutical applications.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Corbion N.V. |
| DSM-Firmenich |
| BASF SE |
| Polaris Nutritional Lipids |
| Cyanotech Corporation |
| Neptune Wellness Solutions Inc. |
| Algarithm Ingredients Inc. |
| Others |
Value Network & Pricing Analysis
Infant formula manufacturers in Illinois and Ohio anchor procurement volumes through multi-year offtake contracts, locking in pharmaceutical-grade DHA pricing that stratifies across fermentation-derived premium tiers and commodity fish-oil alternatives. This buyer concentration compresses margin capture for mid-scale suppliers while rewarding integrated players with captive strain development capabilities.
Pricing Analysis
Distributor markups in the dietary supplement channel absorb 35-45 percent of final shelf price, creating pressure for direct-to-manufacturer contracting among high-volume nutraceutical brands. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates infant formula suppliers from functional food formulators. Pricing pressure stems from corn dextrose feedstock volatility in Midwest grain belts, squeezing heterotrophic cultivation economics. Dietary supplement brands exhibit highest price sensitivity, while pediatric nutrition portfolios tolerate premium positioning for contaminant-free DHA sourcing.
Supply Chain Analysis
USDA organic certification requirements and FDA GRAS dossier preparation costs are reshaping sourcing toward domestic fermentation capacity with established regulatory dossiers. Supply concentrates in the United States, Canada, and Mexico, with the Great Lakes belt anchoring extraction and encapsulation infrastructure. Raw material dependencies center on sugar feedstocks, specialized photobioreactor equipment, and supercritical CO2 extraction solvents. Single-region concentration in the Great Lakes exposes operations to winter logistics disruptions. Distribution runs through temperature-controlled bulk liquid tankers and cold-chain softgel shipments to nutraceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American algae omega-3 market functions as a geographic-arbitrage play between US fermentation technology leadership and Canadian prairie provinces' lower facility costs for controlled-environment cultivation. Health Canada's NNHPD regulatory clarity accelerates product registration timelines relative to FDA GRAS preparation, creating cross-border positioning advantages.
For Market Incumbents: Hedge against novel strain displacement by deepening backward integration into phototrophic cultivation assets in Alberta and Saskatchewan. Lock in multi-year supply contracts with infant formula manufacturers before heterotrophic fermentation cost curves flatten. Prioritize supercritical CO2 extraction capacity expansion to capture customized EPA-to-DHA ratio demand from sports nutrition brands.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in EPA-rich algal oil creates entry space for mid-tier suppliers targeting Colorado and Utah recovery drink launches. White space concentrates in USDA organic certified production, where limited supplier competition supports shelf placement premiums. Contract cultivation partnerships with Canadian prairie agricultural infrastructure lower capital barriers to phototrophic strain commercialization.
For Investors and Strategic Acquirers: Integrated agribusiness conglomerates with captive biotechnology divisions represent the most active acquirer category in this space, seeking fermentation technology ownership to secure pharmaceutical-grade supply contracts. Long-term viability hinges on regulatory harmonization across US-Canada jurisdictions enabling streamlined cross-border dossier submission. Monitor FDA guidance on qualified health claims for algae-sourced EPA and DHA as the inflection signal for expanded cultivation capacity investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Cargill and DSM-Firmenich secure captive DHA supply chains independent of third-party fermentation tolling. |
| Canadian Prairie Capacity Expansion | Alberta and Saskatchewan facilities exploit underutilized agricultural infrastructure for lower-cost phototrophic production. |
| Supercritical CO2 Extraction Scale-Up | Corbion N.V. and specialized lipid fractionation houses capture premium pricing for customized EPA-to-DHA ratios. |
| USDA Organic Certification Investment | Premium tier suppliers command natural channel shelf placement with limited certified organic competition. |
| Nanoemulsion Delivery Technology Partnership | California beverage manufacturers adopt transparent fortification solutions for plant-based dairy alternatives. |
Research Methodology
Multiple input streams — executive interviews with infant formula procurement directors, fermentation technology specialists, and Health Canada regulatory consultants — were reconciled against FDA GRAS notification databases, USDA organic certification records, and customs trade data for algal oil imports. Secondary validation drew from SEC 10-K filings of integrated agribusiness conglomerates, industry association technical reports, and patent filings for heterotrophic cultivation processes. Bottom-up volume estimates from individual facility capacities were triangulated against top-down market sizing from end-use demand aggregation.
Data-stream reconciliation across the projection horizon applied segmented growth modeling by product type, end-use vertical, and geographic regulatory cluster. The analytical framework incorporated EPA-to-DHA ratio specifications, certification tier premiums, and channel margin structures. CAGRs were derived from fitted growth curves calibrated to historical capacity expansion announcements and infant formula manufacturer procurement timelines. Forecast inputs included corn dextrose price volatility scenarios and pending FDA qualified health claim guidance timelines.
Caveats apply where biotechnology oversight delays under the EPA's Toxic Substances Control Act, Health Canada NNHPD regulation modernization, or feedstock price shocks could materially shift the outlook. Forecasts embed assumptions regarding regulatory harmonization progress and strain technology commercialization rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Indonesia Edible Oil Market
Ingredients
Global Egg White Peptide Market
Ingredients
South America Fermented Ingredients Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
Rooster Comb Extract Market
Ingredients
Yeast and Yeast Extract Market
Ingredients
Egg Albumin Protein Market
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Soy Protein Concentrate Market
Ingredients
Bangladesh Mustard Oil Market
Ingredients
Zea Mays Starch Market
Ingredients
Pumpkin Seed Protein Market
Ingredients
L-Arabinose Market
Ingredients
Cheese Cultures Market
Ingredients
India Olive Oil Market
Ingredients
Interesterified CBE Market