
 Olive Oil Market | 2026-2036
Olive Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Olive Oil Market Analysis
Market Context
Specialty store distribution is fragmenting as digital direct-to-consumer platforms and consolidated supermarket private labels pull volume in opposite directions. Deoleo leverages its Iberian bottling footprint to sustain shelf presence across European retail banners. Gallo Worldwide anchors Portuguese supply through controlled cooperatives in the Alentejo region. Sovena Group competes on refined oil scale in foodservice bulk contracts across North American institutional buyers.
Technical Definition and Segment Structure
Olive oil is the liquid fat extracted from Olea europaea fruit, with extra virgin grades requiring cold mechanical pressing below 27 degrees Celsius and free acidity below 0.8 percent for commercial classification. Its primary industrial purpose spans culinary formulation, cosmetic emollient bases, and pharmaceutical excipient applications where oxidative stability matters. Extra virgin commands the dominant margin pool in retail channels, while food manufacturing absorption of refined grades is expanding fastest in North African and Middle Eastern processing facilities. Glass bottle packaging retains premium positioning in gift and specialty segments, though plastic bottle and tetra pack formats are gaining share in mass-market household penetration.
Regulatory Framework
EU Green Deal carbon accounting rules and REACH chemical safety standards shape extraction facility investments and packaging material choices across European producer nations. The USDA organic seal and FDA food facility registration requirements govern US import access and label claim legitimacy. Stakeholders must monitor evolving EU Deforestation Regulation traceability mandates and California Olive Oil Commission grading enforcement to anticipate compliance cost shifts and origin verification technology adoption.
Market Dynamics
EU Green Deal carbon accounting rules are forcing extraction facilities to retrofit energy-intensive pressing operations, compressing margins for traditional mills while advantaging cooperatives with solar thermal integration.
Growth Catalysts
- EU Green Deal sustainability mandates:Carbon footprint disclosure requirements are pulling food manufacturers toward certified-origin suppliers with verified low-intensity extraction methods.
- Cosmetic formulation demand:Skincare brands are absorbing squalene-rich olive oil fractions for emollient bases, creating premium offtake channels outside commodity culinary markets.
- Alentejo cooperative consolidation:Portuguese producer associations are achieving scale efficiencies in organic certification and bulk export logistics.
Market Restraints
- Input cost volatility:Fertilizer and irrigation energy costs have doubled for Mediterranean growers since supply chain disruptions in input markets.
- Supply concentration risk:Andalusian processing capacity dominates EU extra virgin output, creating geographic vulnerability to drought-induced crop failures.
- Seed oil substitution:Sunflower and rapeseed oils are capturing price-sensitive food manufacturing volume in North African processing facilities.
Strategic Opportunities
- Direct-to-origin e-commerce:Producer-owned platforms are bypassing consolidated retail banners to capture full margin on traceable, small-batch shipments.
- EU Deforestation Regulation traceability mandates:Early compliance investments are creating competitive moats for cooperatives with geolocated orchard mapping and blockchain verification systems.
- Pharmaceutical excipient certification:USP-grade oxidative stability specifications are opening formulation contracts with generic drug manufacturers seeking natural lipid bases.
Industry Challenges
- Organic certification timeline compression:Three-year conversion periods for conventional orchards are straining grower cash flows during price troughs.
- Legacy mill equipment retrofit costs:Cold-pressing temperature monitoring systems and energy recovery units demand capital outlays that fragment producer competitiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Olive Oil Market |
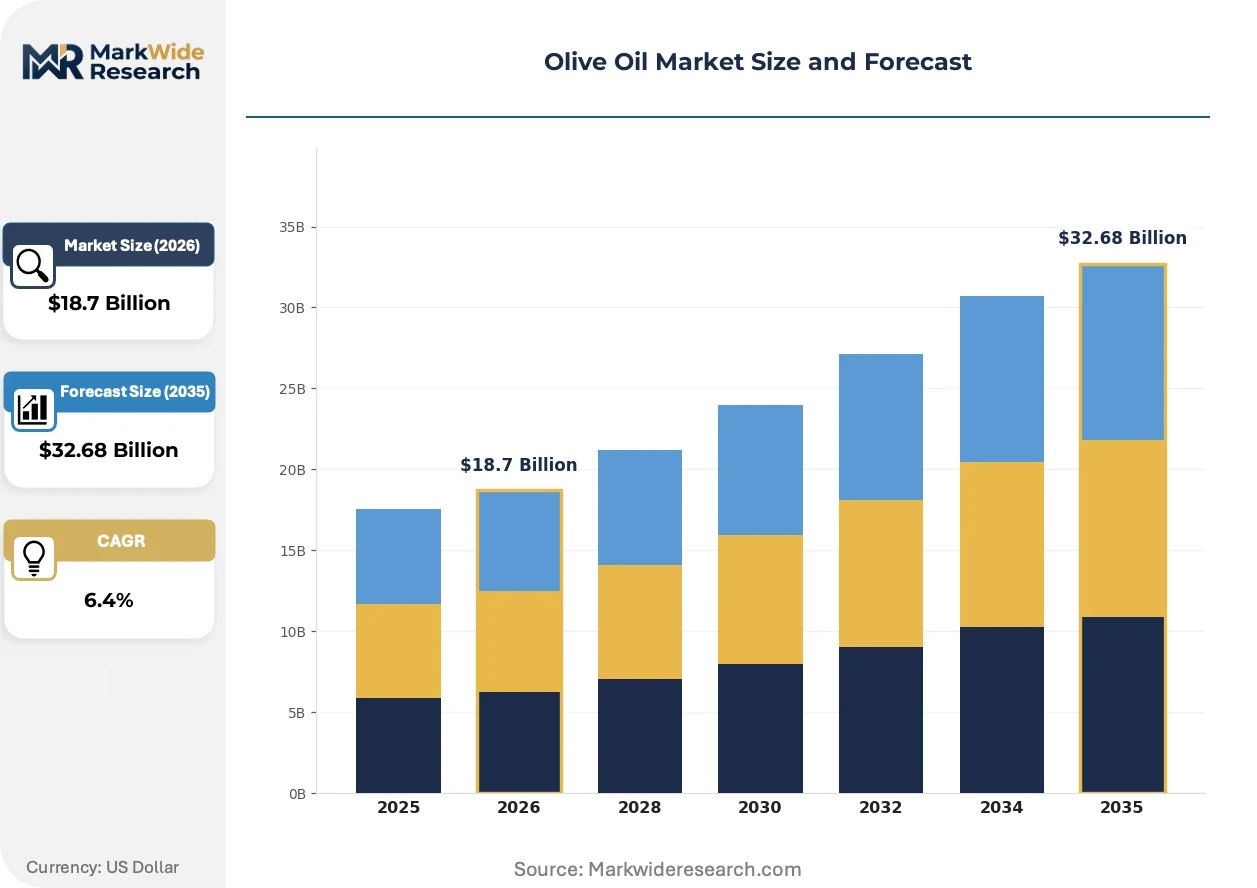
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extra Virgin, Pure, Light, Refined Packaging Type: Glass Bottle, Plastic Bottle, Tetra Pack, Can End User: Households, Restaurants, Food Manufacturing, Skincare Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Farmers Markets |
| Companies Covered | Gallo Worldwide, Salov, Deoleo, Monini, Colavita, Sovena Group, Borges International Group, Pompeian, Lamasia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Olive Oil Market Emerging Trajectories
Digital traceability infrastructure and extraction efficiency technologies are compressing traditional supply chain layers while regulatory compliance costs reshape competitive positioning among producer tiers.
Near-infrared spectroscopy paired with blockchain ledger systems is digitizing origin verification and chemical grading at mill intake points. Large cooperative federations in Spain and Italy are deploying these platforms to preempt EU Deforestation Regulation documentation requirements. The technology is digitizing compliance workflows that previously required manual paper trails and third-party laboratory testing, compressing certification timelines from weeks to hours.
REACH chemical safety standards are tightening packaging material specifications for olive oil contact surfaces, forcing migration from certain plastic additives toward glass and coated paperboard alternatives. Italian bottling facilities are absorbing the capital costs of line conversions ahead of enforcement deadlines. Foodservice bulk buyers in institutional channels are most affected, facing price step-ups as compliant packaging formats carry 15-20 percent material cost premiums.
Specialty store buyers are consolidating procurement around single-origin, harvest-dated SKUs with chemical assay transparency, displacing undifferentiated private label volume. Direct import relationships between US specialty distributors and Greek island cooperatives are replacing layered broker networks. This pattern is most visible in California and Northeast metropolitan markets where educated consumer segments command premium positioning for traceable, early-harvest extra virgin grades.
Olive Oil Market Segmentation
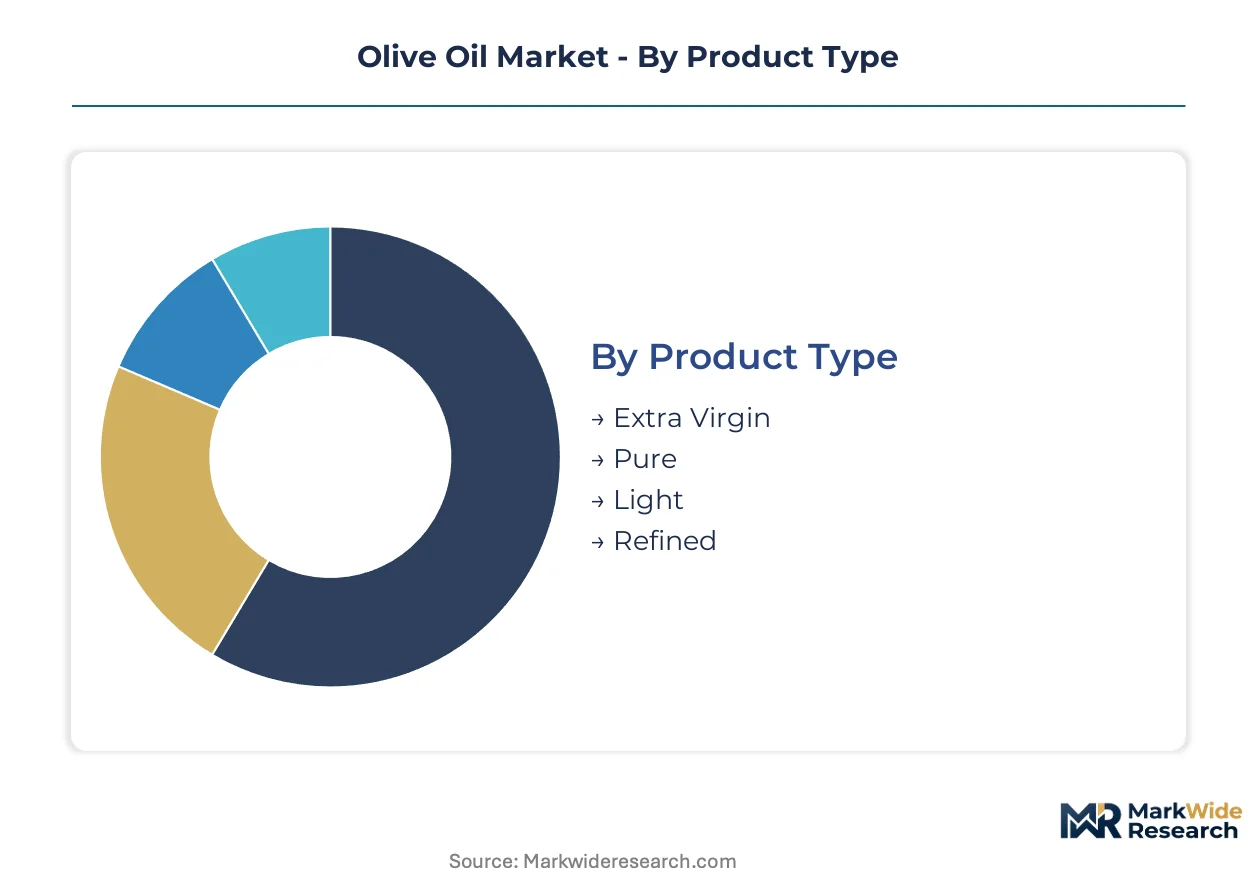
Olive oil segmentation reveals divergent margin structures across quality grades and channel economics. Product type and packaging format decisions determine whether producers capture premium retail multiples or compete on foodservice volume.
Product Type:
Culinary applications span a use-case spectrum from raw finishing to high-heat processing, with each grade commanding distinct price points and certification requirements.
- Extra Virgin:Cold mechanical extraction below 27°C preserves polyphenol content and maintains free acidity under 0.8%. Italian and Spanish specialty stores absorb the dominant share of certified-origin extra virgin, driven by EU Green Deal carbon disclosure mandates that favor verified low-intensity extraction methods.
- Refined:Chemically neutralized and deodorized to remove defects, achieving higher smoke points suitable for industrial frying. North African food manufacturing facilities in Morocco and Tunisia are expanding offtake fastest, as seed oil substitution pressures redirect volume toward cost-competitive refined olive grades.
- Pure:Blended composition combining refined and virgin oils for balanced flavor stability. Greek bottlers dominate private-label supply to European supermarket banners.
- Light:Refined oil with minimal color and flavor profile, marketed for subtle culinary applications. US mass-market retailers stock this grade for price-sensitive household penetration.
Established volume favors refined grades in food manufacturing; emerging adoption favors extra virgin in traceable direct-to-consumer channels.
Packaging Type:
Material selection tracks cost tier and shelf-life requirements across retail versus institutional segments.
- Glass Bottle:Inert barrier properties prevent oxidation and support premium positioning through tactile weight and visual clarity. Italian gift-market specialists and California specialty distributors specify dark-tinted glass for early-harvest extra virgin, as educated consumers in metropolitan markets pay margin premiums for harvest-dated transparency.
- Plastic Bottle:Lightweight logistics and shatter resistance enable mass-market household penetration. Portuguese cooperatives in Alentejo are scaling PET formats for North American supermarket private labels, though REACH chemical safety standards are forcing migration away from certain additive formulations.
- Tetra Pack:Aseptic carton technology extends shelf life without refrigeration for institutional foodservice. Greek bulk exporters favor this format for Middle Eastern hospitality sector contracts.
- Can:Metal barrier protection suits large-volume food manufacturing procurement. Spanish refining facilities package industrial quantities for North African processing plant intake.
Margin concentration sits with glass in premium retail; volume scaling sits with plastic and tetra pack in mass-market and institutional channels.
End User:
Customer type determines whether procurement emphasizes sensory certification or cost-per-unit processing economics.
- Households:Mediterranean consumer bases in Spain and Italy sustain per-capita consumption rates far above global averages, with specialty store and farmers market channels capturing educated segments seeking single-origin provenance.
- Restaurants:Foodservice operators balance ingredient cost against menu positioning, with fine-dining establishments in France and California specifying DOP-certified extra virgin for tableside finishing.
- Food Manufacturing:Industrial buyers prioritize oxidative stability and bulk logistics, with Moroccan and Turkish facilities absorbing refined grades for packaged food formulation.
- Skincare:Cosmetic formulators extract squalene-rich fractions for emollient bases, creating pharmaceutical-grade demand outside commodity culinary markets.
Procurement scale favors food manufacturing; margin expansion favors skincare and premium restaurant channels.
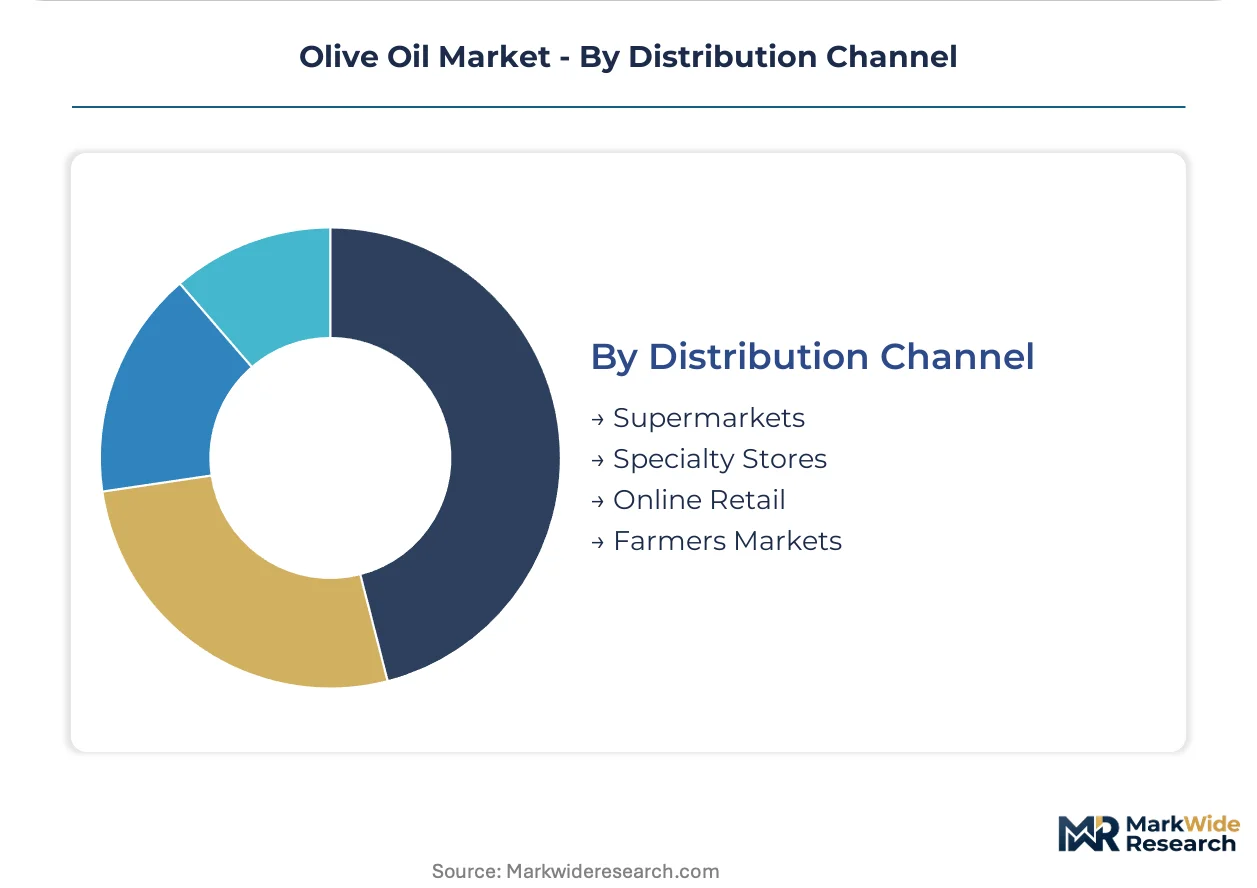
Distribution Channel:
Channel selection determines origin verification depth and price realization for producer tiers.
- Supermarkets:Consolidated retail banners in Germany and the UK drive private-label volume through centralized procurement, compressing supplier margins while demanding consistent quality documentation.
- Specialty Stores:Curated assortments in California and Northeast US metropolitan markets emphasize harvest dates, chemical assays, and cooperative provenance, displacing undifferentiated volume through educated consumer loyalty.
- Online Retail:Direct-to-origin platforms operated by Greek island cooperatives and Portuguese producer associations bypass layered broker networks, capturing full margin on traceable small-batch shipments.
- Farmers Markets:Localized exchange enables immediate quality verification and seasonal freshness claims, particularly active in Italian and Spanish production zones with strong tourism traffic.
Volume concentration remains with supermarkets; value capture is shifting fastest toward online retail and specialty store consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish extraction facilities command premium pricing power for certified-origin extra virgin grades, while North African refiners compete on cost-competitive refined volumes for food manufacturing absorption. This pricing asymmetry reflects divergent regulatory compliance burdens and carbon accounting transparency requirements across Mediterranean producer zones.
Spain
Andalusian cooperatives dominate EU extra virgin output, with Jaén province concentrating over half of national milling capacity. EU Green Deal carbon disclosure mandates are forcing energy-intensive facilities to retrofit with solar thermal integration, compressing margins for traditional mills. Seville-based bottling clusters are absorbing compliance costs ahead of REACH packaging enforcement deadlines.
Italy
Puglia and Calabria sustain specialty store demand through DOP-certified early-harvest grades, with chemical assay transparency commanding metropolitan premiums. EFSA chemical safety standards shape extraction facility investments across Apennine processing zones. Tuscan cooperative federations are deploying blockchain verification systems to preempt EU Deforestation Regulation documentation requirements.
Greece
Peloponnese and Crete supply chains are bypassing layered broker networks through direct-to-origin e-commerce platforms targeting US specialty distributors. The country's national food safety regulator enforces cold-pressing temperature monitoring for export-grade certification. Aegean island cooperatives are consolidating procurement around harvest-dated SKUs with geolocated orchard mapping.
United States
California's Central Valley anchors domestic extra virgin production, with Napa and Sonoma counties capturing premium positioning through early-harvest polyphenol retention. FDA food facility registration requirements govern import access and label claim legitimacy for Mediterranean suppliers. Los Angeles and San Francisco metropolitan markets absorb the dominant share of traceable, small-batch shipments through specialty retail channels.
Portugal
Alentejo cooperative associations are achieving scale efficiencies in organic certification and bulk export logistics for North American supermarket private labels. The country's agricultural ministry oversees conversion timelines for conventional orchard transitions. Lisbon bottling facilities are absorbing REACH-driven packaging line conversions for plastic additive compliance.
Olive Oil Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in extraction technology and cooperative supply aggregation. The vendor base organizes around three strategic archetypes: Iberian and Italian cooperative federations controlling origin-certified volume, multinational bottlers with private-label scale across retail banners, and specialty distributors curating single-provenance assortments for metropolitan markets. Competitive moves concentrate on backward integration into controlled cooperative supply and geographic expansion of DOP-certified origin portfolios.
Among Iberian-based platform integrators, Deoleo and Sovena Group exemplify the multinational bottling archetype with consolidated retail presence across European and North American channels. Gallo Worldwide anchors Portuguese supply positioning through Alentejo cooperative networks. These three entities represent divergent scale strategies: cooperative federation aggregation versus private-label volume penetration versus controlled-origin premium positioning.
| Leading Market Players |
|---|
| Gallo Worldwide |
| Salov |
| Deoleo |
| Monini |
| Colavita |
| Sovena Group |
| Borges International Group |
| Pompeian |
| Lamasia |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Andalusian milling facilities is compressing spot-market premiums for undifferentiated extra virgin grades while tightening margins for traditional producers, forcing supplier consolidation and selective channel withdrawal toward traceable direct-to-consumer platforms.
Pricing Analysis
The harvest-date-premium spread separates early-harvest polyphenol-rich grades from standard commercial lots. Pricing stratifies across premium, standard, and economy tiers based on certification grade and cooperative provenance. Cost compression in refined grades is intensifying because North African seed oil substitution pressures redirect food manufacturing volume. Foodservice bulk buyers exhibit highest price sensitivity; California specialty distributors and French fine-dining establishments show lowest sensitivity.
Supply Chain Analysis
Extended payment terms from German and UK supermarket banners are straining Portuguese and Greek cooperative cash flows, accelerating supply-chain finance facility adoption. Geographic concentration centers on Spain, Italy, and Greece for extra virgin output, with Morocco and Tunisia anchoring refined grade expansion. Raw material dependencies rest on fertilizer inputs, irrigation energy, and harvesting labor pools. Single-source vulnerability concentrates in Andalusian drought exposure. Distribution runs through cooperative federation aggregation into multinational bottler networks and direct-to-origin e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled traceability infrastructure is shifting competitive advantage toward platform-cooperative hybrids that can verify origin and chemical grade in real time, collapsing traditional broker layers.
For Market Incumbents: Entrench controlled cooperative supply through backward integration into Alentejo and Peloponnese producer associations. Preempt EU Deforestation Regulation compliance by deploying geolocated orchard mapping ahead of enforcement deadlines. Seed oil substitution in North African food manufacturing represents the pressing margin threat; certification investment in carbon-accounted extraction methods offers defensive differentiation.
For New Entrants and Emerging Players: US specialty distributors in California and Northeast metropolitan markets represent the most penetrable entry point for harvest-dated, chemical-assay-transparent SKUs. Direct-to-origin e-commerce platforms bypassing layered broker networks enable full margin capture on small-batch shipments. Lead with single-provenance storytelling and blockchain verification as the go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cooperatives with established organic certification and locked North American private-label contracts. Long-term viability hinges on traceability technology ownership and regulatory compliance moats. Acquisition targets should show deployed blockchain verification systems and DOP-certified origin portfolios. The signal to watch is EU Deforestation Regulation enforcement acceleration as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | EU Deforestation Regulation compliance compresses certification timelines from weeks to hours for cooperative federations. |
| Cooperative Federation Aggregation | Portuguese Alentejo associations achieve scale efficiencies in organic certification and bulk export logistics. |
| Direct-to-Consumer Platform Launch | Greek island cooperatives bypass broker networks to capture full margin on traceable small-batch shipments. |
| REACH Packaging Line Conversion | Italian bottling facilities absorb capital costs ahead of chemical safety enforcement deadlines. |
| Pharmaceutical Excipient Certification | USP-grade oxidative stability specifications open formulation contracts with generic drug manufacturers. |
Methodological Framework
Cross-validation between cooperative federation export data and EU customs records anchors the qualitative findings. Primary interviews with mill operations managers, specialty store buyers, foodservice procurement leads, and cosmetic formulators draw from structured protocols. Secondary validation sources include EFSA chemical safety filings, EU Green Deal carbon disclosure registries, and REACH packaging compliance databases. Bottom-up volume estimates from individual cooperative capacity triangulate against top-down category absorption figures.
Calibration against historical price series and trade flow patterns shapes the analytical framework across the projection horizon. Segmentation dimensions span product grade tier, packaging format, end-use application, and distribution channel. CAGRs derive from trend extrapolation moderated by regulatory inflection assumptions. Forecast inputs incorporate EU Deforestation Regulation timeline uncertainty and drought-induced crop failure probability.
Macroeconomic conditions sit as an overlay; deviation in energy input costs and currency exchange rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement pacing and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Organic Pastry Flour Market
Ingredients
Native Whey Protein Ingredients Market
Ingredients
Global Egg White Peptide Market
Ingredients
Waxy Maize Starch Market
Ingredients
Psyllium Husk Powder Market
Ingredients
Palm Mid-Fraction Market
Ingredients
Global Pea Protein Ingredients Market
Ingredients
Salad Oil Market
Ingredients
Global Dietary Fibers Market
Ingredients
Low Calorie Olive Oil Market
Ingredients
Biotech Ingredients Market
Ingredients
North America Alcohol Ingredients Market
Ingredients
Beef Concentrate Market
Ingredients
Drum to Hopper Blends Premix Market
Ingredients
Millet Protein Market
Ingredients
Asia Pacific Vegetable Oil Market