
 Global Apricot Oil Market | 2026-2036
Global Apricot Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Apricot Oil Market Foresight
Capital-intensity divergence between cold-press equipment owners and contract bottlers is unwinding competitive stability in apricot oil supply. NOW Foods leverages captive sourcing from Turkish orchards to sustain margin control across retail channels. Aura Cacia anchors North American distribution through co-op partnerships with Frontier Natural Products Co-op. Forest Essentials dominates premium Ayurvedic positioning in Indian domestic markets through specialized glass packaging and direct-store operations.
Apricot oil is a fixed oil expressed from Prunus armeniaca kernels, containing approximately 60-70% oleic acid and 20-30% linoleic acid with a light, non-greasy viscosity profile suited for topical absorption. Cold-pressed grades retain tocopherols and phytosterols that cosmetic formulators specify for antioxidant claims in facial serums and massage blends. Organic certification commands structural premium positioning as EU and North American buyers restrict pesticide residue thresholds. Pharmaceutical applications represent a concentrated margin pool where drug manufacturers specify refined grades for excipient use, though aromatherapy channels generate faster volume growth through wellness center procurement expansion.
FDA cosmetic labeling requirements, EU REACH substance registration, and USDA organic standards collectively govern market access and purity verification across major demand centers. EFSA novel food evaluations shape culinary application expansion timelines for European food processors seeking GRAS-equivalent status. Stakeholders must monitor kernel supply concentration in Turkey and Uzbekistan while evaluating backward integration into orchard assets to secure non-GMO and organic feedstock streams.
Market Dynamics
Kernel supply concentration in Turkey and Uzbekistan is tightening procurement leverage for European and North American cosmetic formulators, forcing downstream buyers to secure captive orchard relationships or accept volatile spot-market pricing for organic-certified feedstock.
Growth Catalysts
- EU REACH substance registration:Cosmetic-grade apricot oil suppliers achieving full dossier compliance gain preferential access to Parisian and German skincare houses seeking verified purity chains for facial serum formulations.
- Cold-press extraction technology:Equipment advances reducing tocopherol degradation during kernel processing enable antioxidant claims in premium emulsion products targeting wellness center distribution channels.
- Provence-based distiller cluster:French supply chain density around Grasse and surrounding regions provides integrated sourcing-to-formulation services that compress lead times for luxury cosmetics brands.
Market Restraints
- Kernel input cost volatility:Apricot kernel prices fluctuate with Turkish agricultural yields and competing demand from snack food processors, squeezing margin stability for non-integrated oil pressers.
- Single-origin supply risk:Over-reliance on Turkish and Uzbekistani orchards exposes buyers to regional climate shocks, political trade friction, and currency instability affecting contracted organic volumes.
- Refined grade technical limitations:Pharmaceutical excipient specifications require ultra-low peroxide values and complete allergen protein removal, constraining which pressers can serve drug manufacturers.
Strategic Opportunities
- Indian Ayurvedic premium channel:Specialized glass packaging and direct-store operations targeting domestic wellness consumers create margin pools above commodity cosmetic grades.
- USDA organic certification tailwind:North American buyers restricting pesticide residue thresholds generate structural premiums for certified suppliers able to document orchard-to-bottle traceability.
- Supercritical CO2 extraction convergence:Combination with conventional cold-pressing enables novel phytosterol concentrates for nutraceutical applications beyond standard cosmetic use.
Industry Challenges
- Organic certification timeline compression:Three-year conversion periods for conventional orchards limit rapid scaling of certified supply to match accelerating EU and North American buyer mandates.
- Cold-press equipment capex intensity:Stainless steel expeller systems with temperature-controlled jackets require substantial upfront investment, favoring established processors over new entrants.
- Cross-border phytosanitary compliance:Kernel and oil shipments face divergent national inspection protocols that delay customs clearance and increase working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Apricot Oil Market |
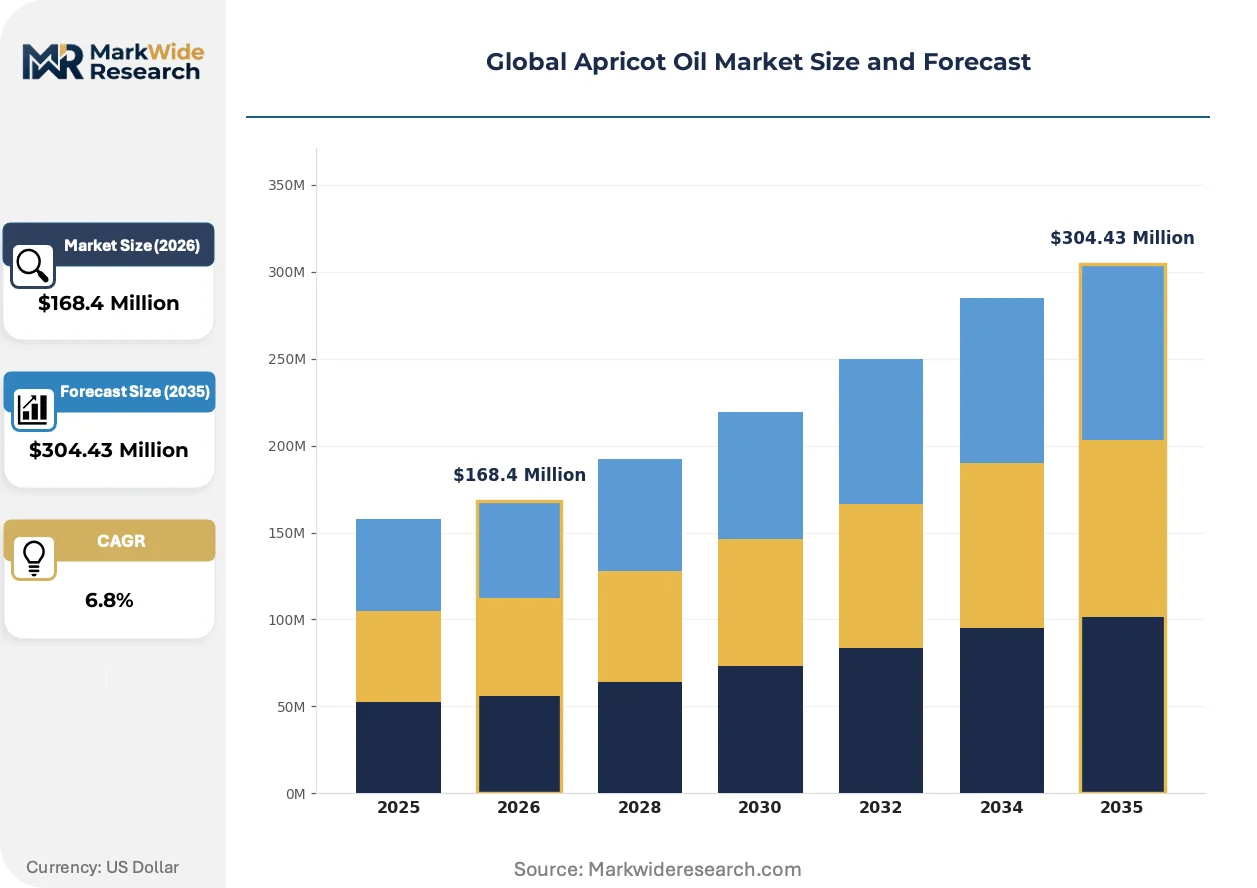
| Market Size in 2026 | $168.4 Million |
| Market Size in 2035 | $304.43 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold-Pressed, Refined, Organic, Virgin, Fractionated Application: Cosmetics, Culinary, Pharmaceuticals, Personal Care, Aromatherapy End User: Skincare Manufacturers, Food Processing, Drug Manufacturers, Wellness Centers, Spa Services Packaging Type: Glass Bottles, Plastic Bottles, Sachets, Aluminum Tubes, Jars |
| Companies Covered | NOW Foods, Aura Cacia, AMD Oil Sales LLC, Plantlife Natural Body Care, Frontier Natural Products Co-op, Greenwood Essencial, Forest Essentials, Starwest Botanicals, Life-Flo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Apricot Oil Market Shifts & Advancements
Extraction technology diversification and regulatory purity escalation are compressing traditional supplier tiers while opening specialized niches for traceability-verified and certification-differentiated product grades.
Supercritical CO2 extraction is fragmenting the conventional cold-press dominance in high-value cosmetic applications. German and Swiss skincare formulators are adopting CO2-derived oils for liposomal delivery systems requiring zero solvent residues. This technology is fragmenting the mid-tier supplier base by bifurcating winners with capital access from legacy mechanical pressers locked in commodity pricing.
EU REACH Annex XIV authorization requirements for cosmetic substances are tightening purity documentation obligations across the supply chain. French and German cosmetics houses now mandate full substance identity profiles from kernel suppliers. Small-scale Turkish pressers lacking regulatory affairs capabilities are losing shelf space to integrated Provence-based operators with in-house compliance teams.
Wellness center direct procurement is displacing traditional distributor intermediaries in North American aromatherapy channels. Spa operators in California and Colorado are contracting directly with Uzbekistani organic cooperatives for massage-grade volumes. This pattern concentrates most visibly in the Rocky Mountain region where vertically integrated wellness chains bypass conventional wholesale structures entirely.
Global Apricot Oil Market Segmentation
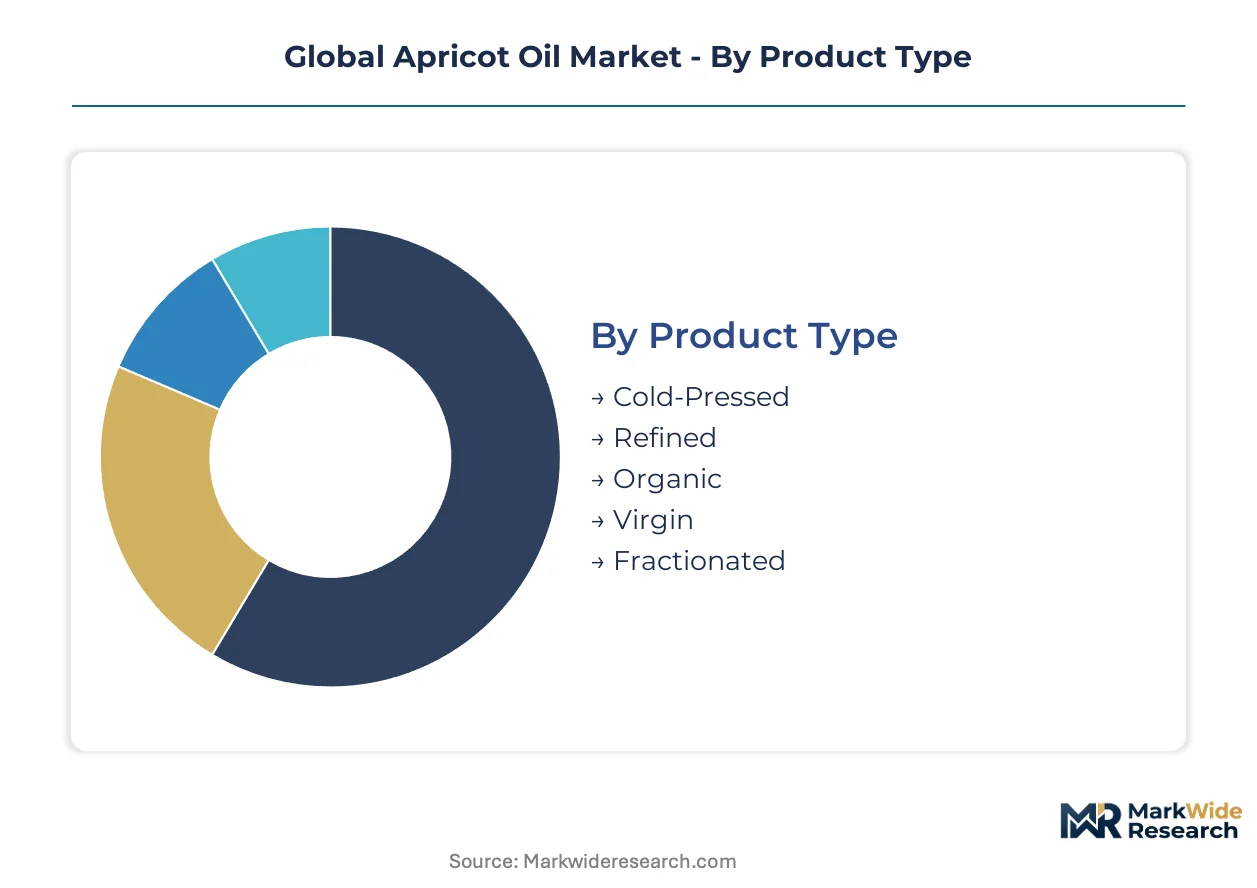
Apricot oil's commercial pathways diverge sharply across extraction methods and purity grades, with channel strategy determining which specifications reach cosmetics laboratories versus wellness retail shelves. Procurement patterns in Turkish orchards and French formulation houses reveal how segmentation governs margin capture and regulatory compliance burdens.
Product Type:
Cold-pressed and organic grades flow through premium cosmetics channels with full traceability documentation, while refined variants serve pharmaceutical compounders with stripped-down tocopherol profiles and ultra-low peroxide certification.
- Cold-Pressed:Mechanical extraction below 40°C preserves tocopherols and phytosterols for antioxidant claims in facial serums. Parisian cosmetics houses specify this grade for emulsion formulations targeting wellness center distribution. Kernel supply volatility from Turkish agricultural yields squeezes margin stability for non-integrated pressers.
- Organic:Three-year orchard conversion periods and pesticide residue documentation satisfy EU and North American buyer mandates. USDA certification generates structural premiums as buyers restrict threshold limits. Uzbekistani cooperatives are gaining direct procurement relationships with California spa operators.
- Refined:Bleaching and deodorization strips color and odor for pharmaceutical excipient specifications requiring complete allergen protein removal.
- Virgin:Single-press extraction without secondary processing retains maximum kernel lipids for massage-grade aromatherapy applications.
- Fractionated:Selective crystallization separates high-melting triglycerides for specialized cosmetic delivery systems.
By volume, refined grades lead through pharmaceutical and mass-market personal care channels. By growth pace, organic certification is climbing the fastest as EU REACH compliance tightens purity benchmarks.
Application:
Cost tier separation runs from pharmaceutical excipients commanding technical premiums down to culinary volumes competing with commodity edible oils on per-kilogram pricing.
- Cosmetics:Facial serums, emulsions, and premium skincare formulations specify cold-pressed grades with full tocopherol retention. Provence-based distillers supply major Parisian houses with integrated sourcing-to-formulation services. REACH Annex XIV authorization requirements are squeezing small-scale Turkish pressers from this channel.
- Pharmaceuticals:Drug manufacturers specify ultra-low peroxide values and complete protein removal for excipient use, constraining eligible suppliers to capital-intensive refiners. Forest Essentials in India captures margin pools above commodity grades through Ayurvedic positioning.
- Culinary:EFSA novel food evaluations shape European food processor expansion timelines for GRAS-equivalent status.
- Personal Care:Mass-market lotions and hair oils accept refined grades with reduced odor profiles.
- Aromatherapy:Wellness center direct procurement is displacing traditional distributors in California and Colorado.
Cosmetics generates the steepest margin expansion. Aromatherapy channels are gaining share fastest through spa operator vertical integration.
End User:
Customer type determines packaging specification and order granularity, from bulk tanker shipments to drug manufacturers down to single-origin glass bottles for premium retail.
- Skincare Manufacturers:French and German cosmetics houses mandate full substance identity profiles from kernel suppliers. Supercritical CO2 extraction is fragmenting the mid-tier supplier base as Swiss formulators adopt zero-residue oils for liposomal systems.
- Wellness Centers:Rocky Mountain spa operators contract directly with Uzbekistani organic cooperatives, bypassing wholesale intermediaries entirely. Aura Cacia anchors North American distribution through Frontier Natural Products Co-op partnerships.
- Food Processing:Culinary applications await regulatory clearance timelines in European markets.
- Drug Manufacturers:Excipient specifications require dedicated refining capacity with pharmaceutical-grade filtration systems.
- Spa Services:Massage-grade volumes prioritize light viscosity and rapid skin absorption characteristics.
Skincare manufacturers dominate current procurement volumes. Wellness centers are expanding most quickly through direct-to-origin contracting.
Packaging Type:
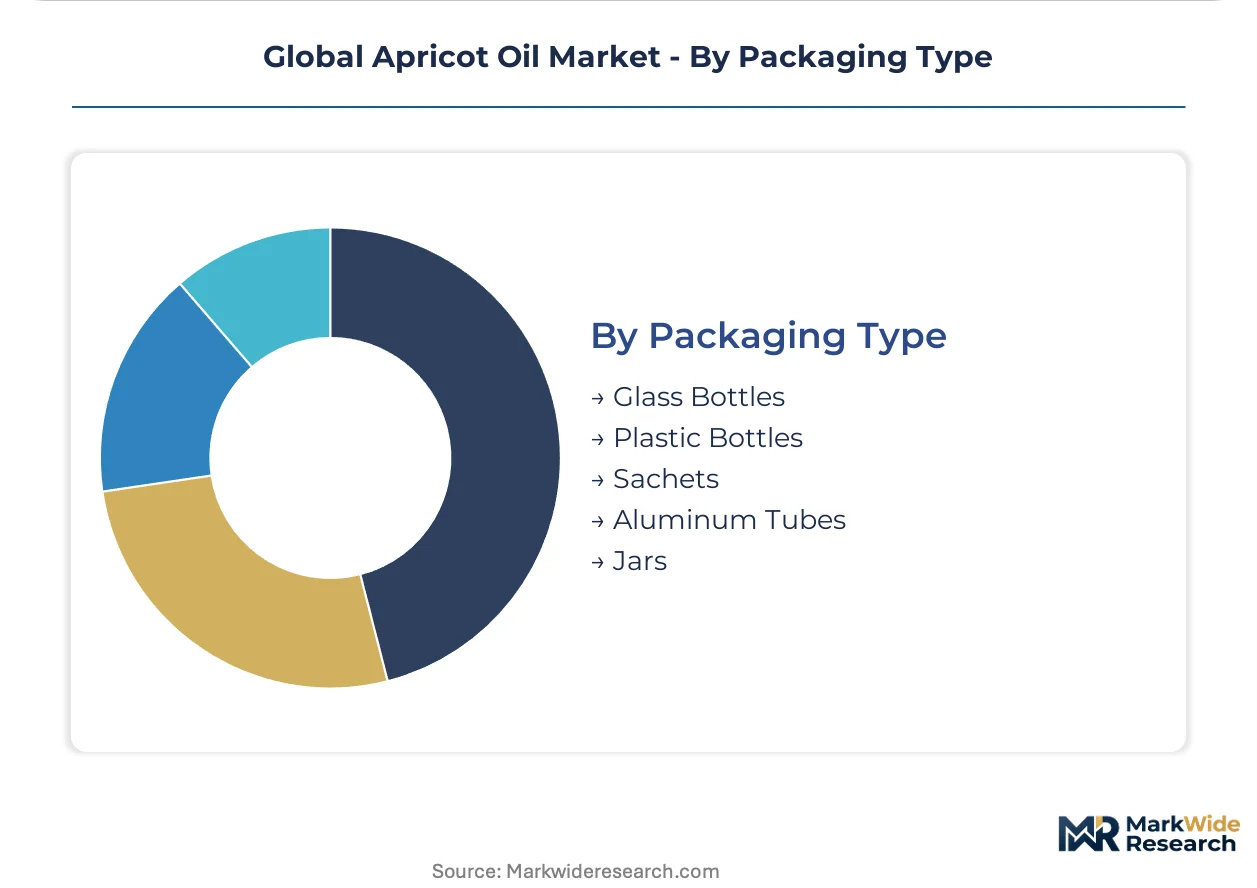
Supply concentration in glass and aluminum aligns with premium channel requirements, while plastic and sachet formats serve cost-sensitive personal care and sample distribution.
- Glass Bottles:Specialized packaging for Ayurvedic premium positioning in Indian domestic markets through direct-store operations. Forest Essentials leverages this format for margin capture above commodity grades.
- Plastic Bottles:High-density polyethylene serves mass-market personal care with reduced transportation costs.
- Sachets:Single-use samples support trial conversion in aromatherapy and hotel amenity channels.
- Aluminum Tubes:Collapsible metal packaging protects light-sensitive tocopherols in travel-size cosmetics.
- Jars:Wide-mouth containers accommodate balm and butter formulations with solid-phase carrier oils.
Plastic bottles lead by volume through mass personal care distribution. Glass bottles are gaining share fastest as organic certification drives premium positioning requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes apricot oil predominantly through luxury cosmetics channels, while the United States routes larger volumes through wellness center direct procurement and India channels supply into Ayurvedic premium retail. This consumption-mix differential shapes regulatory priorities and supply chain configurations across major demand centers.
France
Parisian cosmetics houses drive demand for cold-pressed grades with full tocopherol retention for facial serum formulations. REACH Annex XIV authorization requirements from ECHA tighten purity documentation obligations across kernel suppliers. The Grasse-Provence distiller cluster provides integrated sourcing-to-formulation services that compress lead times for luxury skincare brands.
United States
California and Colorado spa operators contract directly with overseas organic cooperatives for massage-grade volumes, bypassing traditional wholesale intermediaries. FDA cosmetic labeling requirements govern market access for topical applications, while USDA organic standards generate structural premiums for certified suppliers. The Rocky Mountain wellness corridor concentrates most visibly around vertically integrated spa chains.
Germany
Swiss and German formulators adopt supercritical CO2-derived oils for liposomal delivery systems requiring zero solvent residues. ECHA REACH substance registration governs cosmetic-grade imports, favoring suppliers with full dossier compliance. The Baden-Württemberg personal care manufacturing belt anchors formulation demand for high-purity grades.
India
Domestic wellness consumers absorb premium Ayurvedic positioning through specialized glass packaging and direct-store operations. FSSAI standards shape edible oil applications while CDSCO oversight applies to pharmaceutical excipient uses. Maharashtra-based retailers and Karnataka formulation units concentrate distribution for premium cosmetic grades.
Turkey
Orchard assets in Malatya and Erzincan provinces supply kernel feedstock to European and North American pressers, though climate volatility and currency instability squeeze contracted organic volumes. The country's national agricultural regulator oversees phytosanitary export protocols. Istanbul-based processors face mounting compliance burdens from EU and US buyer mandates.
Global Apricot Oil Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive orchard relationships and regulatory compliance capabilities determining shelf access. The upstream layer compresses around Turkish and Uzbekistani kernel suppliers with organic certification, while downstream formulation houses in France and Germany consolidate procurement leverage. Three archetypes dominate: integrated orchard-to-bottle operators, regulatory affairs-heavy European distributors, and wellness-channel direct marketers. Competitive moves concentrate on backward integration into orchard assets and supercritical CO2 extraction licensing for zero-residue product lines.
Among North American wellness distributors, NOW Foods and Aura Cacia occupy positions at the scale-driven and partnership-anchored ends respectively, with the latter exemplifying co-op distribution models through Frontier Natural Products Co-op relationships. Forest Essentials represents the Ayurvedic premium archetype, sitting within specialized glass packaging and direct-store operations targeting domestic Indian wellness consumers.
| Leading Market Players |
|---|
| NOW Foods |
| Aura Cacia |
| AMD Oil Sales LLC |
| Plantlife Natural Body Care |
| Frontier Natural Products Co-op |
| Greenwood Essencial |
| Forest Essentials |
| Starwest Botanicals |
| Life-Flo |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for organic-certified kernel shipments from Malatya orchards to Provence pressers compress margin buffers for non-integrated buyers while amplifying pricing power for captive orchard owners. This inventory-to-pricing linkage tightens most acutely where EU REACH documentation requirements intersect with Turkish agricultural volatility.
Pricing Analysis
Long-term offtake contracts dominate procurement between Parisian cosmetics houses and integrated Provence distillers, while spot-market purchases govern non-integrated North American wellness distributors sourcing from Uzbekistani cooperatives. Price differentiation rests on organic certification tier and cold-press equipment ownership. Cost compression in refined pharmaceutical grades is intensifying because ultra-low peroxide specifications constrain eligible suppliers. Mass-market personal care buyers exhibit highest price sensitivity; luxury skincare manufacturers absorb premiums for full tocopherol retention.
Supply Chain Analysis
Turkey and Uzbekistan anchor global kernel production, with Malatya and Erzincan provinces feeding European pressers and Ferghana Valley cooperatives supplying direct-contract spa operators. Raw material flows draw from apricot orchard waste streams, competing snack-food processor demand, and organic conversion timelines. Single-origin concentration exposes buyers to regional climate shocks and currency instability. Distribution runs through integrated French formulation houses, North American wellness-channel direct marketers, and Indian Ayurvedic retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The apricot oil market sits at a platform-economics inflection where traceability-verified supply chains function as interoperability layers between orchard assets and cosmetics laboratory information systems. Ecosystem lock-in now accrues to operators controlling both kernel provenance data and REACH-compliant documentation workflows.
For Market Incumbents: Fortify captive orchard relationships in Turkey's Malatya region to secure non-GMO feedstock streams against emerging organic cooperative competitors. Invest in supercritical CO2 extraction licensing to defend margin position against zero-residue technology disruptors targeting Swiss liposomal formulators. Channel control through direct-store operations in India represents the priority defensive lever.
For New Entrants and Emerging Players: Lead with USDA organic certification and orchard-to-bottle traceability documentation to penetrate North American wellness center procurement channels bypassing traditional wholesale intermediaries. The Rocky Mountain spa corridor offers lowest competitive density among penetrable geographies. A co-op partnership distribution model minimizes upfront working capital requirements.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory purity escalation creates persistent premium capture for compliance-capable operators. Acquisition targets should cluster around integrated orchard-to-bottle specialists with in-house ECHA dossier capabilities. The signal to watch is EU REACH Annex XIV authorization timeline compression for kernel-derived cosmetic substances.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Captive kernel supply from Turkish organic-certified orchards insulates margin stability from agricultural yield volatility. |
| Supercritical CO2 Extraction Licensing | Zero-residue oil production enables access to Swiss and German liposomal delivery system formulators. |
| REACH Annex XIV Compliance Investment | Full substance dossier submission secures preferential shelf access at Parisian luxury cosmetics houses. |
| Direct-to-Wellness-Channel Distribution | Bypassing wholesale intermediaries captures margin pools in California and Colorado spa operator procurement. |
| Ayurvedic Premium Positioning | Specialized glass packaging and direct-store operations in Indian domestic markets sustain pricing above commodity grades. |
Research Methodology
Initial hypotheses were tested against primary input from cold-press equipment operators, cosmetics formulation chemists, wellness center procurement managers, and organic certification auditors, then refined through secondary validation. Orchard yield data from Turkey's national agricultural regulator, EU ECHA substance registration databases, USDA organic certification records, and French customs export statistics anchored quantitative triangulation. Bottom-up kernel supply modeling converged with top-down cosmetics industry demand estimation.
Variance decomposition across extraction method, certification tier, application channel, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segmented volume-demand buildups incorporating pharmaceutical excipient specifications, aromatherapy channel expansion rates, and culinary application regulatory clearance timelines. Kernel supply concentration metrics and wellness center direct procurement penetration curves served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU REACH enforcement intensity, Turkish agricultural yield stability, or North American organic certification mandate acceleration would require recalibration. Forecasts reflect documented assumptions regarding phytosanitary protocol harmonization and supercritical CO2 extraction cost curves. Recalibration cycles align with material shifts in kernel supply geography, cosmetics regulatory thresholds, and wellness channel procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Global Pine Pollen Powder Market
Ingredients
Citrus Fiber Market
Ingredients
Elecampane Root Market
Ingredients
Edible Oils and Fats Market
Ingredients
Middle East & Africa Prebiotic Ingredients Market
Ingredients
Mallow Glycolic Extract Market
Ingredients
Collagen Casings Market
Ingredients
Middle East and Africa Pea Starch Market
Ingredients
Virginiamycin Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
Wort Concentrate Market
Ingredients
North America Vegetable Oils Market
Ingredients
Refined Coconut Oil Market
Ingredients
White Wheat Malt Market
Ingredients
Smoke Ingredients for Food Market