
 Global Galvanized Steel Wire Market | 2026-2036
Global Galvanized Steel Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Global Galvanized Steel Wire Market Foresight
REACH compliance is restructuring the cost-of-entry calculus for European galvanized wire exports, forcing coating chemistry reformulation and third-party certification spend. ArcelorMittal leverages its integrated European flat steel capacity to captive-produce zinc-coated feedstock. Bekaert sustains technology leadership in ultra-high tensile wire for tire cord and bridge cable applications. Tata Steel Limited anchors South Asian supply through its Jamshedpur and Kalinganagar galvanizing lines.
Galvanized steel wire consists of carbon steel wire coated with a zinc layer, typically applied through hot-dip galvanizing at 450°C or electro-galvanizing in alkaline or acid electrolytes, to impart corrosion resistance for outdoor and high-humidity environments. The primary industrial purpose spans tensioning, binding, fencing, and structural reinforcement where atmospheric exposure would degrade unprotected steel. Hot-dip galvanized wire dominates volume due to thicker zinc coatings and lower unit cost, though electro-galvanizing commands premium positioning in automotive components and precision electrical wiring where surface finish tolerances are tighter. Coated steel wire occupies the largest share of construction fencing and agricultural equipment procurement, while welded mesh is concentrating fastest in pre-fabricated building systems.
FDA, EPA, and OSHA frameworks in the United States govern worker exposure limits in galvanizing shops and wastewater discharge from pickling lines, directly shaping plant location and capital intensity decisions. ECHA's REACH restrictions on hexavalent chromium passivation layers and China's MEE emissions standards for zinc vapor and acid mist are converging to raise compliance costs for smaller continuous galvanizing operators. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded asset risk in coating technology choices.
Market Dynamics
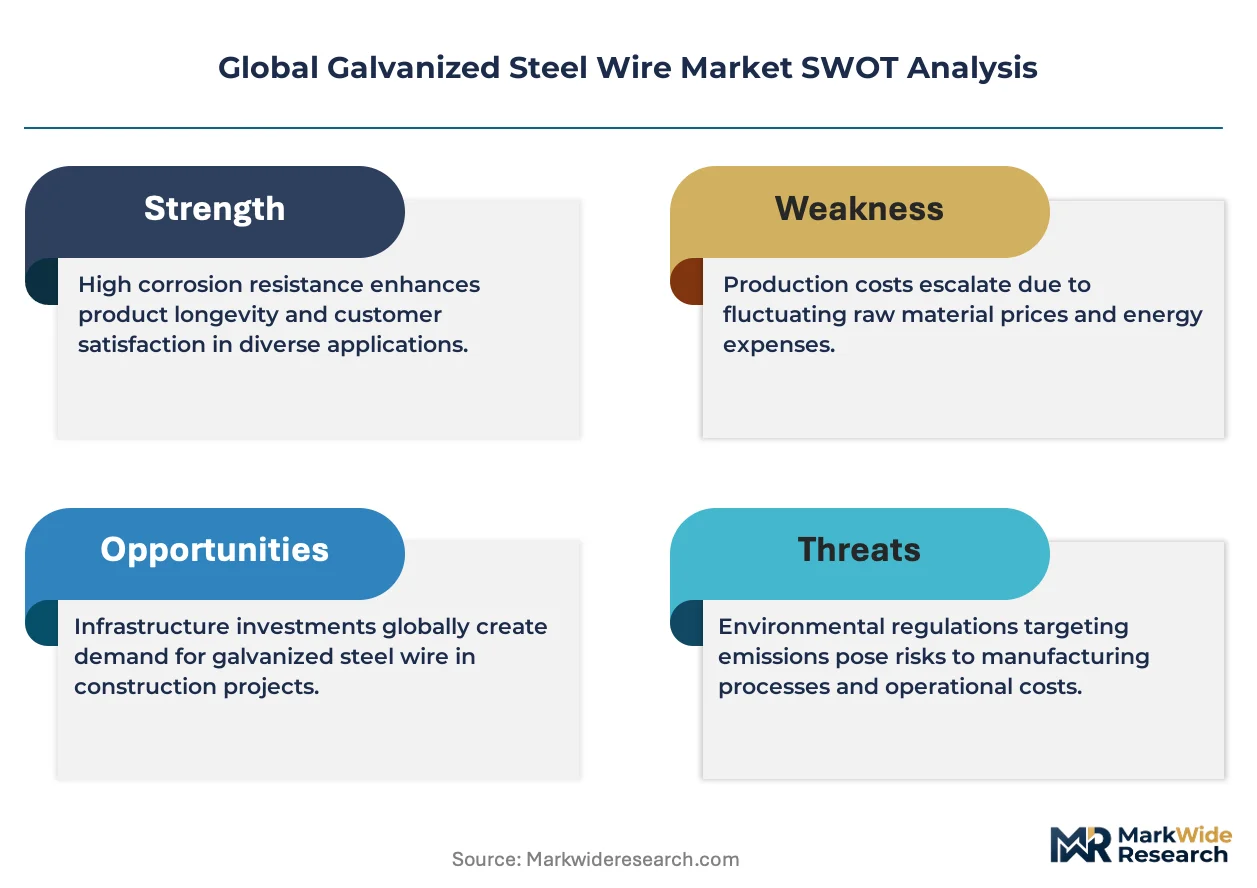
China's dual carbon goals are forcing mills to abandon coal-fired galvanizing furnaces and adopt electric induction heating, compressing margins for operators lacking capital to retrofit continuous lines. This decarbonization mandate is redrawing competitive boundaries between integrated steelmakers and standalone wire processors.
Growth Catalysts
- Rural electrification in India:Grid extension projects under the government's Saubhagya scheme are consuming millions of tonnes of galvanized stay wire and earth wire, with state electricity boards accelerating tender cycles.
- Hot-dip coating chemistry advances:Galfan and Zn-Al-Mg alloy coatings are extending service life in agricultural fencing from 15 to 30 years, justifying premium pricing in mechanized farming regions.
- REACH Article 67 restrictions:ECHA's tightening limits on hexavalent chromium in passivation layers are creating certified-supplier premiums for European exporters who reformulate early.
Market Restraints
- Zing price volatility:London Metal Exchange zinc futures swung 40% in 2022-2023, shredding hedging strategies for continuous galvanizers running 30-day zinc inventory cycles.
- Supply concentration in Hebei Province:Sixty percent of China's galvanized wire capacity clusters within 200 kilometers of Tianjin, creating single-point-of-failure exposure to MEE emissions enforcement.
- Polymer-coated wire substitution:PVC and nylon-jacketed steel wire is capturing 8-12% of coastal marine fencing applications where salt spray exceeds hot-dip zinc's corrosion threshold.
Strategic Opportunities
- Indonesian infrastructure buildout:The Ibu Kota Nusantara new capital project and Trans-Java toll road expansion are generating first-time demand for high-tensile bridge cable and gabion mesh.
- EU Green Deal carbon border adjustments:CBAM phase-in from 2026 creates tariff protection for European galvanizers using electric arc furnace feedstock and renewable-powered zinc pots.
- Digital twin integration:Siemens and Schneider Electric are piloting real-time coating thickness control using machine vision, enabling zero-defect production for automotive spring wire.
Industry Challenges
- Skilled furnace operator shortage:Master galvanizers with 20-plus years of bath chemistry experience are retiring faster than apprenticeship programs in Germany and Japan can replace them.
- MEE emissions compliance timelines:Chinese provincial environmental bureaus are demanding acid scrubber and zinc fume capture retrofits within 18-month windows, straining capex planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Galvanized Steel Wire Market |
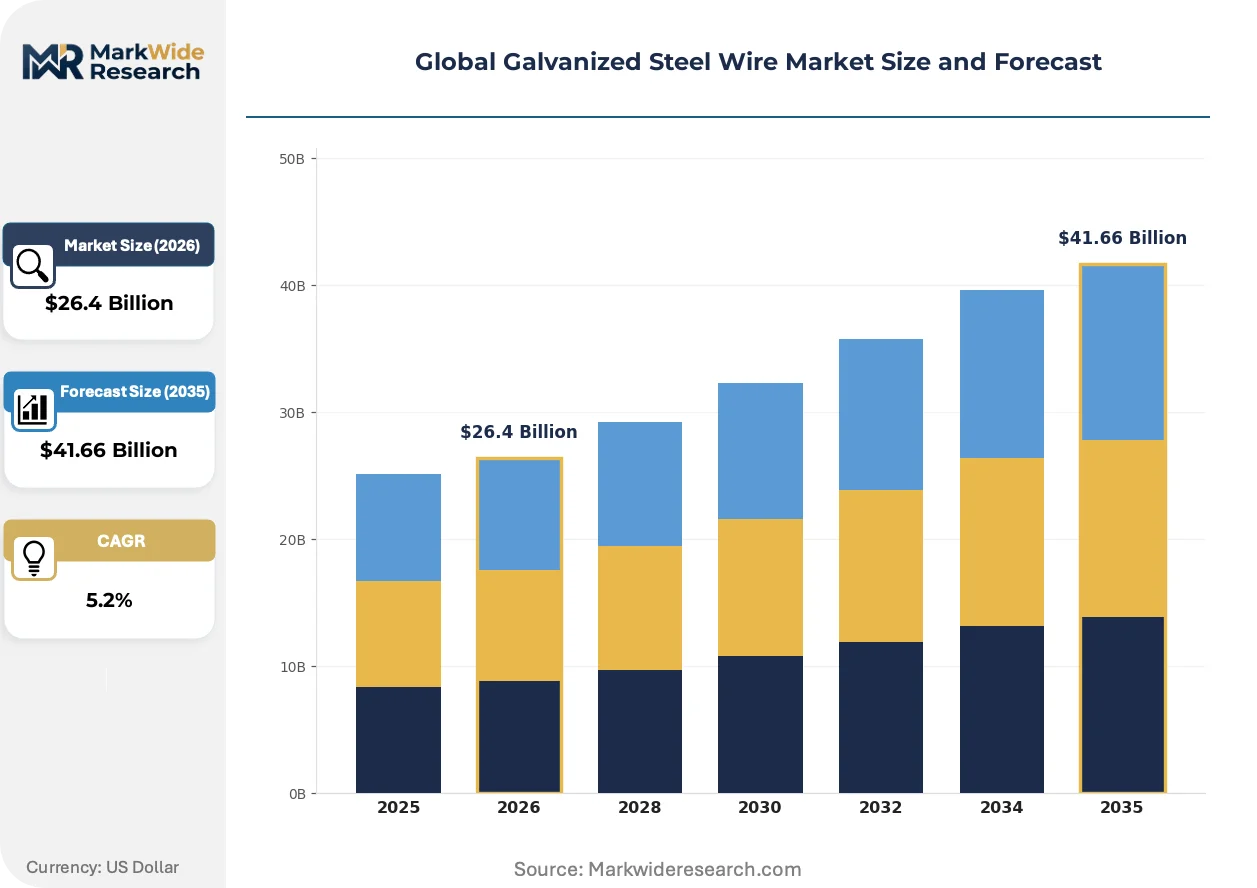
| Market Size in 2026 | $26.4 Billion |
| Market Size in 2035 | $41.66 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Steel Wire, Bright Steel Wire, Welded Wire, Braided Wire, Welded Mesh Technology: Hot-Dip Galvanizing, Electro-Galvanizing, Mechanical Plating, Continuous Galvanizing, Cold Galvanizing Application: Construction Fencing, Electrical Wiring, Automotive Components, Agricultural Equipment, Household Appliances End User Industry: Manufacturing Companies, Electrical Contractors, Farm Equipment Manufacturers, Appliance Makers, Mechanical Workshops |
| Companies Covered | ArcelorMittal, Bekaert, Nippon Steel Corporation, Tata Steel Limited, POSCO, JFE Steel Corporation, Gerdau S.A., Nucor Corporation, United States Steel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Galvanized Steel Wire Market Shifts & Advancements
Electrification of heat treatment and coating processes is converging with AI-driven quality control to compress defect rates and energy intensity simultaneously. These shifts are altering where competitive advantage resides in the value chain.
Continuous inline annealing followed by gas-pressure wiping for zinc coating thickness control is decentralizing quality assurance from centralized lab testing to real-time production line feedback. Automotive tier-1 suppliers in Germany and Japan are adopting this for tire cord wire. The technology is compressing lead times from order to shipment by eliminating offline sampling delays.
ECHA's REACH restrictions on chromium VI in passivation and China's MEE standards for acid mist emissions are forcing coating chemistry reformulation across both jurisdictions. European exporters face third-party certification costs of 50,000-100,000 euros per product line. Smaller continuous galvanizers in Poland and Italy are consolidating to spread compliance overhead across larger volumes.
Buyers in North American agricultural equipment are unbundling wire procurement from OEM supply agreements and sourcing directly from certified mills via B2B platforms. This disintermediation is visible most acutely in Iowa and Illinois grain belt regions where cooperatives now aggregate demand for fencing and baling wire. Distributors are responding with value-added cutting and custom coil winding services to defend relationships.
Global Galvanized Steel Wire Market Segmentation
Galvanized steel wire procurement decisions split across coating durability requirements, precision tolerances, and regulatory compliance burdens. Buyers in construction, automotive, and agricultural sectors weight total cost of ownership differently, creating distinct segment trajectories. The analysis examines four primary dimensions: product form, coating technology, end-use application, and buyer industry type.
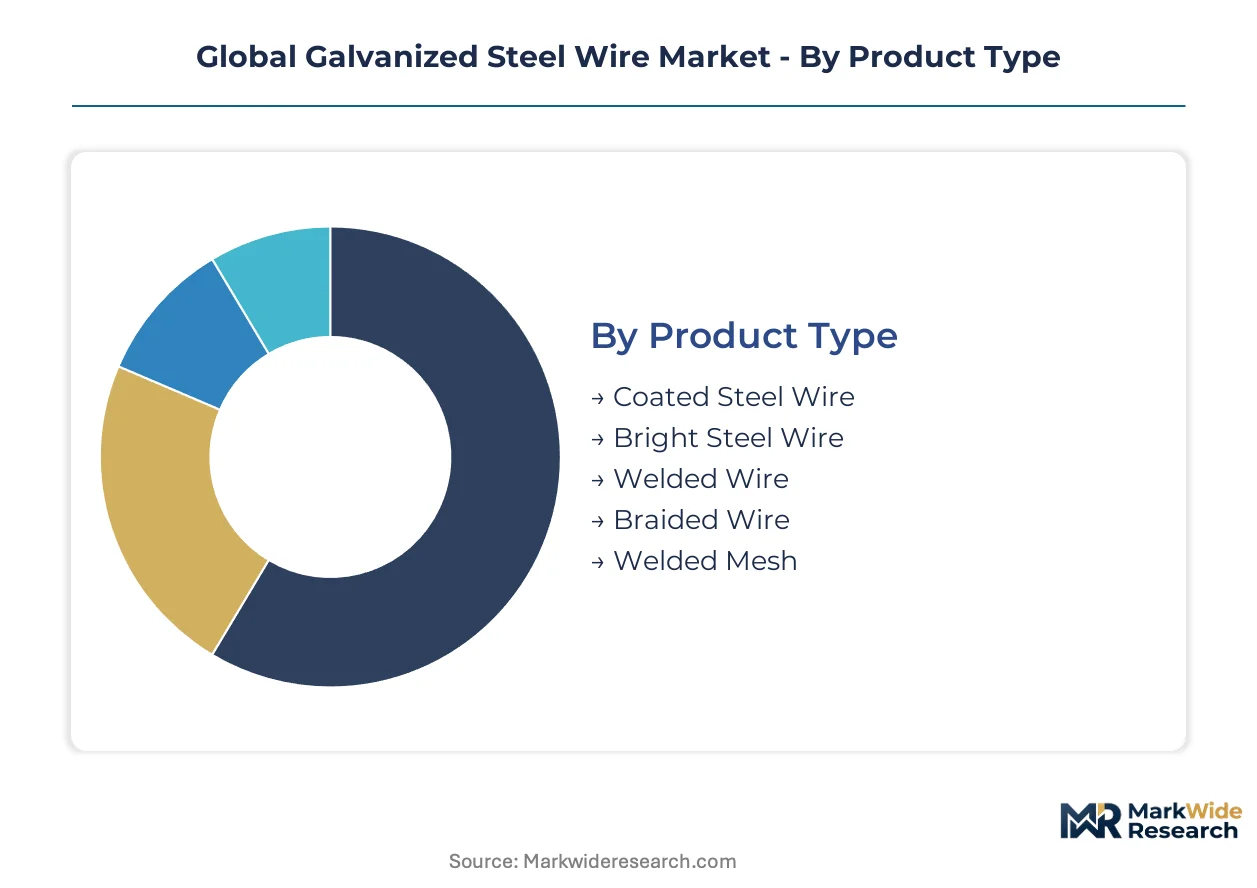
Product Type:
Buyers select wire form based on structural load requirements and installation labor intensity.
- Coated Steel Wire:Carbon steel core with zinc or zinc-alloy layers applied post-drawing, typically 45-85 microns thick for hot-dip variants. Demand concentrates in Indian rural electrification projects where state electricity boards specify coated stay wire for transmission line anchoring under CEA grid standards.
- Welded Mesh:Intersecting wires fused at junctions to create rigid panels for concrete reinforcement and gabion structures. Pre-fabricated building systems in Indonesia's Ibu Kota Nusantara project are accelerating specification for foundation mats and retaining walls.
- Bright Steel Wire:Cold-drawn uncoated wire with polished surface finish for subsequent coating or direct use in controlled environments. Mechanical workshops in Germany specify bright wire for custom fabrication where post-weld galvanizing is preferred.
- Welded Wire:Longitudinal and cross wires resistance-welded into grid patterns for fencing and animal containment. Farm equipment manufacturers in Iowa and Illinois source directly via B2B platforms, bypassing traditional distributor channels.
- Braided Wire:Multiple strands interwoven for flexibility and tensile load distribution in dynamic applications. Appliance makers specify braided configurations for suspension systems in washing machines and industrial dryers.
Coated steel wire leads on scale; welded mesh leads on momentum.
Technology:
Capital intensity and emissions compliance separate coating process selection.
- Hot-Dip Galvanizing:Immersion in molten zinc baths at 450°C producing thick, sacrificial coatings. Hebei Province mills cluster 60% of Chinese capacity near Tianjin, exposing operators to MEE emissions enforcement timelines demanding 18-month scrubber retrofits.
- Electro-Galvanizing:Electrolytic deposition in acid or alkaline baths yielding precise, thin coatings for surface-critical components. Automotive tier-1 suppliers in Japan specify electro-galvanized wire for tire cord where dimensional tolerances are tightest.
- Continuous Galvanizing:Inline annealing and gas-pressure wiping for real-time thickness control. German automotive suppliers adopt Siemens machine vision systems to eliminate offline sampling delays.
- Mechanical Plating:Cold welding of zinc powder onto steel via tumbling with glass beads, avoiding hydrogen embrittlement risks. Mechanical workshops select this for high-strength fasteners in structural bolting.
- Cold Galvanizing:Zinc-rich paint application for field repair and small-batch maintenance. Electrical contractors use cold galvanizing compounds for transmission tower touch-up where hot-dip facilities are inaccessible.
Hot-dip galvanizing dominates volume throughput; continuous galvanizing gains share fastest.
Application:
Corrosion exposure severity and mechanical load cycles dictate specification choices.
- Construction Fencing:Perimeter security and site demarcation using tensioned wire or welded panels. Infrastructure projects across India, Indonesia, and Vietnam are expanding procurement for temporary and permanent barriers.
- Automotive Components:Spring wire, tire cord, and cable reinforcement requiring fatigue resistance. Japanese and German OEMs specify ultra-high tensile grades with AI-driven defect detection.
- Agricultural Equipment:Baling wire, fencing, and vineyard trellis systems. North American grain belt cooperatives aggregate demand via direct mill sourcing, compressing distributor margins.
- Electrical Wiring:Stay wire, earth wire, and messenger cables for grid infrastructure. India's Saubhagya rural electrification scheme consumes millions of tonnes through accelerated state tender cycles.
- Household Appliances:Drum suspensions, heating elements, and structural frames. Appliance makers in South Korea and Mexico specify corrosion-resistant grades for humid climate export markets.
Construction fencing anchors volume; automotive components command premium positioning.
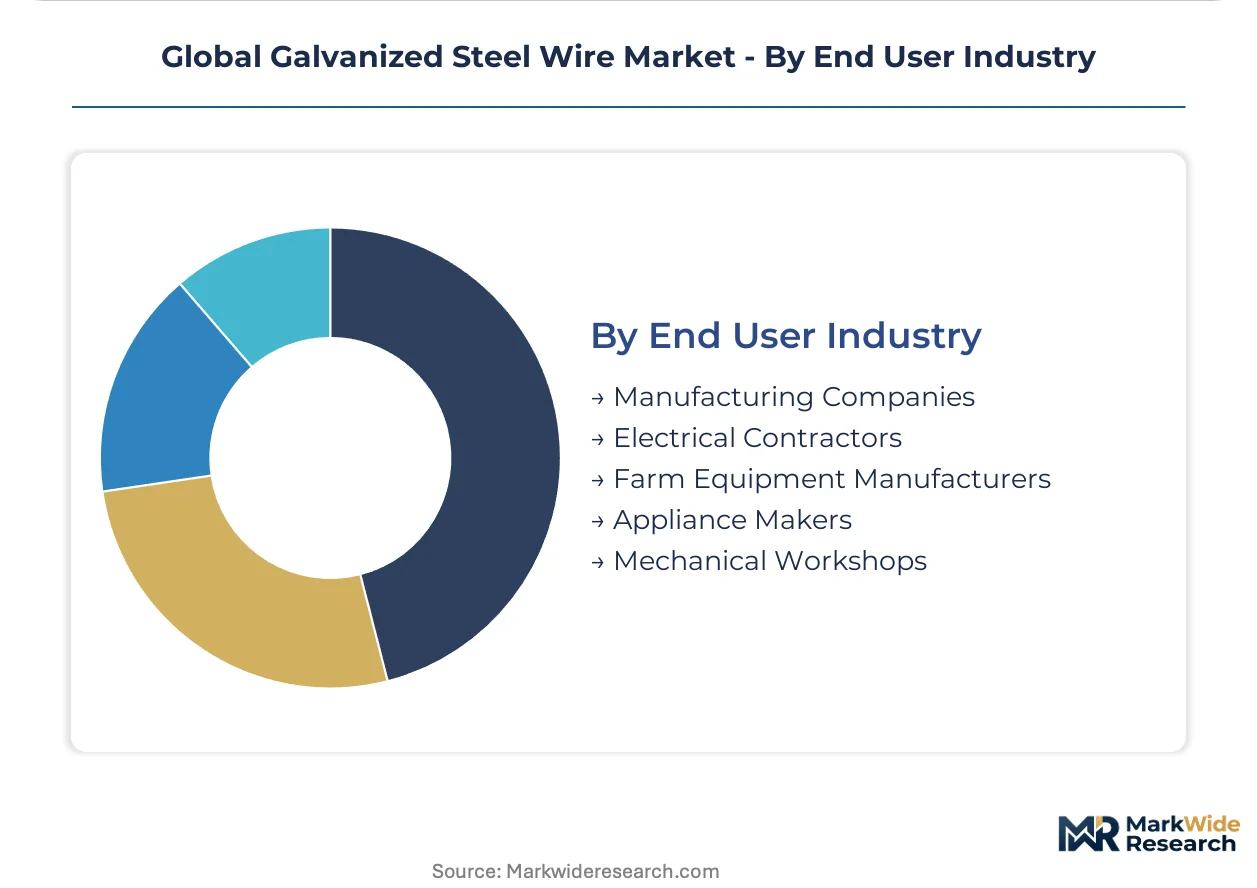
End User Industry:
Procurement scale and technical specification authority vary sharply across buyer types.
- Electrical Contractors:Grid infrastructure specialists purchasing stay wire and earth wire under utility tender specifications. Indian state electricity boards drive volume through centralized procurement.
- Farm Equipment Manufacturers:OEMs integrating wire into machinery and fencing systems. Direct sourcing from certified mills is displacing distributor relationships in North American agricultural regions.
- Manufacturing Companies:Diverse industrial buyers spanning automotive, appliance, and general fabrication. REACH compliance certification creates supplier premiums for European exporters serving this segment.
- Appliance Makers:White goods manufacturers specifying surface-finish-critical wire for visible components. Quality thresholds favor electro-galvanized supply from integrated steelmakers.
- Mechanical Workshops:Job shops and custom fabricators purchasing bright or cold-galvanized wire for small-batch production. This segment shows highest price sensitivity and supplier fragmentation.
Electrical contractors drive the largest individual contracts; farm equipment manufacturers are restructuring procurement channels most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master galvanizers with decades of bath chemistry expertise concentrate in Germany and Japan, yet retire faster than apprenticeship programs replace them. This talent scarcity is redrawing where quality leadership resides.
China
Hebei Province clusters sixty percent of national capacity within 200 kilometers of Tianjin, creating single-point-of-failure exposure. MEE emissions standards are forcing 18-month scrubber retrofits on acid mist and zinc vapor capture. Mills in Tangshan and Shijiazhuang are abandoning coal-fired furnaces for electric induction heating.
India
Rural electrification under the Saubhagya scheme consumes millions of tonnes of stay wire and earth wire through accelerated state tender cycles. CEA grid standards mandate coated wire specifications for transmission line anchoring. Jamshedpur and Kalinganagar galvanizing lines anchor South Asian supply for state electricity board procurement.
Germany
Automotive tier-1 suppliers specify ultra-high tensile grades with AI-driven defect detection for tire cord applications. REACH Article 67 restrictions on hexavalent chromium passivation are creating certified-supplier premiums for early reformulators. Siemens machine vision pilots in Bavaria enable real-time coating thickness control.
United States
FDA, EPA, and OSHA frameworks govern worker exposure limits in galvanizing shops and wastewater discharge from pickling lines. Iowa and Illinois grain belt cooperatives aggregate demand for fencing and baling wire via direct mill sourcing. Nucor Corporation and United States Steel Corporation operate integrated flat steel capacity for captive feedstock production.
Indonesia
The Ibu Kota Nusantara new capital project and Trans-Java toll road expansion generate first-time demand for high-tensile bridge cable and gabion mesh. Pre-fabricated building systems are accelerating welded mesh specification for foundation mats. Domestic procurement channels remain underdeveloped, favoring import partnerships.
Global Galvanized Steel Wire Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across coating technology tiers. Integrated steelmakers leverage captive flat steel capacity to control zinc-coated feedstock costs, while standalone wire processors face margin compression from emissions compliance retrofits. Three archetypes dominate: scale-driven integrated producers, technology-focused specialists in ultra-high tensile grades, and regional fabricators serving construction and agricultural procurement. Competitive moves concentrate on M&A to spread compliance overhead and strategic partnerships for digital twin integration in quality control.
Within the integrated producer tier, ArcelorMittal and Tata Steel Limited exemplify scale-driven positioning through European and South Asian galvanizing line networks. Bekaert occupies a specialist position representing technology leadership in precision coating applications. These three anchors illustrate how competitive advantage is splitting between feedstock control and process innovation.
| Leading Market Players |
|---|
| ArcelorMittal |
| Bekaert |
| Nippon Steel Corporation |
| Tata Steel Limited |
| POSCO |
| JFE Steel Corporation |
| Gerdau S.A. |
| Nucor Corporation |
| United States Steel Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between REACH-compliant European supply and conventional Asian output splits both pricing power and sourcing geography. Buyers seeking ECHA-certified wire for automotive or electrical applications absorb 15-20% premiums over commodity-grade alternatives, while Hebei Province mills compete on volume through coal-to-electric furnace conversions that compress their own margins. This bifurcation funnels procurement toward integrated steelmakers with captive zinc-coated feedstock, leaving standalone processors exposed to zinc inventory volatility and emissions retrofit costs.
Pricing Analysis
Bundled coating-certification services command premiums against unbundled commodity wire, with early REACH reformulators capturing certified-supplier positioning. Pricing stratifies across premium, standard, and economy tiers based on coating chemistry complexity and third-party audit status. Cost compression in standard-grade supply is intensifying because MEE compliance timelines in China are forcing 18-month scrubber investments that smaller operators cannot finance. Farm equipment manufacturers in North American grain belts show highest price sensitivity through cooperative direct-sourcing, while automotive tier-1 suppliers in Germany and Japan exhibit lowest sensitivity given defect-rate thresholds.
Supply Chain Analysis
Freight cost differentials between Hebei Province cluster exports and regional Indian mill supply are reshaping procurement geography for Southeast Asian infrastructure projects. Raw material flows draw from Australian zinc concentrate, Indonesian nickel for alloy coatings, and Chinese coking coal for furnace feedstock. Single-source vulnerability concentrates in the Tianjin-radius production hub where MEE enforcement could idle 60% of Chinese capacity simultaneously. Distribution runs through state electricity board tender systems in India, B2B platform direct sourcing in North America, and OEM supply agreements for automotive components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA REACH Article 67 restrictions on hexavalent chromium passivation are accelerating certified-supplier premiums and consolidating procurement toward early reformulators.
For Market Incumbents: Deepen backward integration into zinc-coated feedstock production to offset zinc price volatility exposure, while accelerating electric furnace retrofits ahead of MEE enforcement windows. Polymer-coated wire substitution in coastal marine applications threatens 8-12% volume erosion in traditional hot-dip segments. Certification investment in REACH-compliant coating chemistry represents the critical defensive lever against smaller Polish and Italian galvanizers consolidating to spread compliance overhead. For New Entrants and Emerging Players: EU Green Deal carbon border adjustments in Europe open a window for electric arc furnace-based galvanizers using renewable-powered zinc pots to capture tariff-protected share. Indonesian infrastructure buildout around Ibu Kota Nusantara presents the most penetrable geography given underdeveloped domestic procurement channels. Target bridge cable and gabion mesh specification through partnerships with Japanese engineering consultants already embedded in Trans-Java toll road expansion. For Investors and Strategic Acquirers: Consolidation pressure builds where 18-month MEE compliance timelines exceed standalone processor balance sheet capacity, particularly among Hebei Province operators lacking electric induction heating capital. Mid-cap European galvanizers with REACH certification infrastructure and automotive tier-1 relationships represent the priority acquisition archetype for long-term viability. Watch skilled furnace operator retirement rates in Germany and Japan as inflection indicators for quality leadership migration.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Induction Furnace Conversion | MEE emissions compliance in Hebei Province mandates coal-fired furnace abandonment, compressing margins for capital-constrained operators. |
| REACH-Compliant Coating Reformulation | ECHA Article 67 restrictions on hexavalent chromium passivation create certified-supplier premiums for early European reformulators. |
| Digital Twin Quality Integration | Siemens machine vision pilots in Bavaria enable real-time coating thickness control, eliminating offline sampling delays for automotive tire cord. |
| Direct Mill Sourcing Platforms | Iowa and Illinois grain belt cooperatives aggregate fencing and baling wire demand via B2B channels, bypassing traditional distributor relationships. |
| Zinc-Alloy Coating Development | Galfan and Zn-Al-Mg formulations extend agricultural fencing service life from 15 to 30 years, justifying premium pricing in mechanized farming regions. |
Research Methodology
Multiple input streams — primary interviews with galvanizing plant managers, automotive tier-1 procurement leads, and state electricity board tender officers; secondary validation through customs trade data, SEC filings from integrated steelmakers, and ECHA regulatory databases; plus technical literature on coating chemistry advances — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned furnace operators in Germany's automotive wire corridor, distributors in India's rural electrification supply chain, and environmental compliance officers at Hebei Province mills.
Data-stream reconciliation across coating technology tiers, end-use application clusters, and geographic production hubs informed analytical framework construction across the analysis window. Segmentation dimensions modeled include product form, coating chemistry type, corrosion exposure severity, and buyer procurement channel. CAGRs were derived from volume-demand elasticity analysis against infrastructure investment cycles and regulatory compliance cost pass-through assumptions, with zinc price volatility and MEE enforcement intensity as industry-specific forecast inputs.
Revisions become necessary when zinc futures volatility exceeds hedging strategy capacity, MEE enforcement timelines accelerate beyond 18-month retrofit windows, or polymer-coated wire substitution rates in coastal applications outpace baseline projections. Forecasts reflect documented assumptions about regulatory pass-through mechanics and technology adoption curves. Stakeholders should weight assumptions against their own operating context and balance sheet capacity for emissions compliance capital deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Amorphous Metal Cores Market
Metals
Nickel Market
Metals
Steel Sheet for Home Appliances Market
Metals
Wear Steel Plate Market
Metals
Stainless Steel Panels Market
Metals
Nickel Powder Plating Market
Metals
High Purity Tungsten Market
Metals
Lithium Tungstate Market
Metals
Global Tin Market
Metals
South America Metal Finishing Market
Metals
Metal Powder Market
Metals
GCC Aluminium Cans Market
Metals
Global Steel Market
Metals
Heat-Treated Steel Plates Market
Metals
Aluminum Smelting Market
Metals
Base Metals Market