
 United States Hydrogen Peroxide Market | 2026-2036
United States Hydrogen Peroxide Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hydrogen Peroxide Market Intelligence
The capital-intensity divergence between merchant producers and captive operators is collapsing as integrated Gulf Coast chemical complexes internalize hydrogen peroxide generation. Evonik Industries AG sustains its position through backward integration into anthraquinone raw materials and proprietary process technology. Solvay anchors its competitiveness via large-scale electrolytic production assets serving the pulp and paper corridor across the southeastern states.
Hydrogen peroxide is an inorganic peroxide with the chemical formula H₂O₂, typically manufactured through the anthraquinone auto-oxidation process using hydrogen and atmospheric oxygen, and functions as a powerful oxidizing agent across bleaching, disinfection, and chemical synthesis applications. The 50% concentration grade dominates industrial procurement volumes due to its balance of handling safety and oxidative efficacy in pulp bleaching sequences. Water treatment applications are expanding fastest among end-use segments, driven by EPA-mandated shifts away from chlorine dioxide in municipal systems seeking to control trihalomethane formation.
EPA regulations under the Safe Drinking Water Act and Clean Water Act shape product specifications and demand patterns, while OSHA process safety management standards govern concentrated solution handling protocols at industrial facilities. The Department of Transportation's hazardous materials classification for hydrogen peroxide above 52% concentration restricts logistics options and elevates regional supply requirements. Stakeholders must monitor state-level PFAS remediation mandates, as hydrogen peroxide-based advanced oxidation processes become the preferred destruction technology for emerging contaminant treatment.
Market Dynamics
EPA's trihalomethane limits under the Safe Drinking Water Act are forcing municipal utilities across the Midwest and Southeast to abandon chlorine-based disinfection, redirecting capital toward hydrogen peroxide-based advanced oxidation systems and reshaping procurement patterns for industrial-grade supply.
Growth Catalysts
- Safe Drinking Water Act mandates:EPA's tightening disinfection byproduct rules compel water treatment facilities to adopt peroxide oxidation, particularly in Texas and Louisiana where municipal system retrofits concentrate demand.
- Petrochemical cluster expansion:Gulf Coast chemical complex growth requires large-volume industrial-grade hydrogen peroxide for process applications, anchoring regional supply contracts.
- Anthraquinone process optimization:Proprietary auto-oxidation technology improvements reduce production energy intensity, lowering delivered costs for 50% concentration grades.
Market Restraints
- Anthraquinone raw material concentration:Backward integration into quinone derivatives limits supplier base to integrated chemical majors, constraining merchant market liquidity.
- Department of Transportation hazmat classification:Concentrations above 52% trigger stringent transport restrictions, fragmenting logistics networks and elevating regional supply premiums.
- Peracetic acid substitution:Food and beverage processors increasingly specify peracetic acid blends for cold aseptic filling, displacing hydrogen peroxide in packaging sterilization.
Strategic Opportunities
- PFAS remediation mandates:State-level regulations targeting per- and polyfluoroalkyl substances position advanced oxidation processes as the preferred destruction technology for emerging contaminant treatment.
- Pulp and paper corridor modernization:Southeastern bleaching sequence upgrades create demand for high-purity grades in elemental chlorine-free processes.
- Electrolytic production convergence:Integration of on-site electrolytic generation with renewable power purchase agreements enables carbon-intensity reductions for ESG-focused industrial buyers.
Industry Challenges
- Process safety management expertise:OSHA's concentrated solution handling protocols require specialized engineering talent scarce outside Gulf Coast chemical processing hubs.
- Legacy chlorine system integration:Municipal utilities face complex retrofit engineering to interface peroxide feed systems with existing water treatment infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hydrogen Peroxide Market |
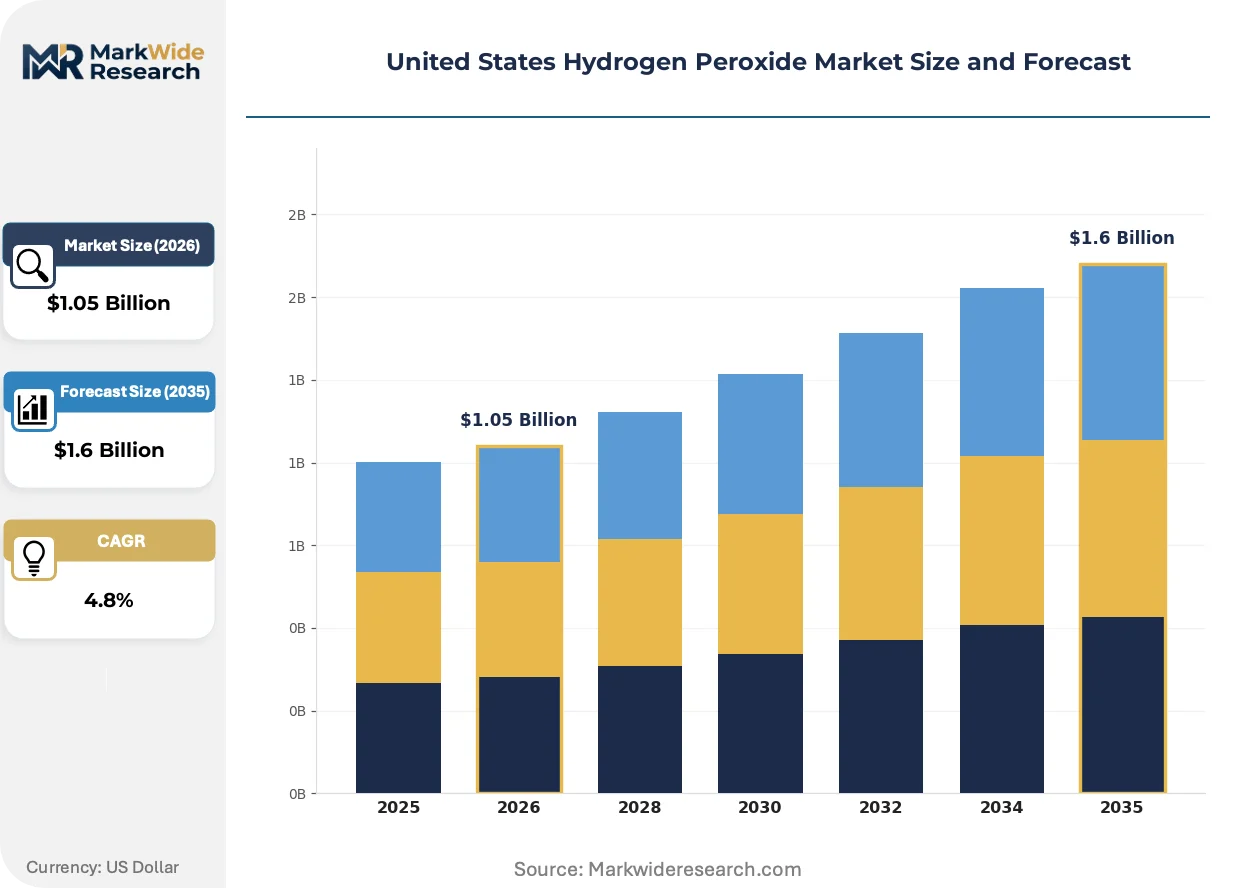
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.6 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 30% Hydrogen Peroxide, 50% Hydrogen Peroxide, 70% Hydrogen Peroxide, 90% Hydrogen Peroxide Application: Pulp & Paper, Textile, Water Treatment, Chemical Synthesis End User: Household, Industrial, Healthcare, Agriculture Distribution Channel: Online Retailers, Direct Sales, Distributors, Brick-and-Mortar Stores |
| Companies Covered | Evonik Industries AG, Solvay, Arkema, Ecolab Inc., FMC Corporation, BASF SE, Kemira, Nouryon, OCI Chemical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hydrogen Peroxide Market Strategic Shifts & Innovations
Process intensification and regulatory chemistry are reshaping how hydrogen peroxide is manufactured, specified, and consumed across American industrial and municipal markets.
Membrane electrolysis technology for on-site generation is decomposing the traditional merchant supply model for mid-scale industrial users. Food and beverage processors in the Upper Midwest are piloting modular electrolytic units to bypass concentrated solution transport constraints. This distributed production architecture is compressing regional pricing premiums and forcing merchant suppliers to defend contract positions through integrated service offerings.
EPA's Unregulated Contaminant Monitoring Rule expansion is accelerating advanced oxidation process adoption in municipal water treatment. The regulation's monitoring requirements for emerging contaminants are compelling utilities to install peroxide-based destruction capacity ahead of formal maximum contaminant level promulgation. Texas and Louisiana water authorities are advancing procurement most aggressively, driven by industrial discharge proximity and state-level enforcement prioritization.
Specification consolidation among pulp and paper buyers is concentrating procurement leverage with tier-one suppliers. Southeastern bleaching sequence operators are consolidating annual contracts around fewer, larger-volume agreements with integrated producers capable of backward anthraquinone supply security. This buyer concentration is visible across the Alabama-Georgia-South Carolina corridor, where mill closures have reduced the customer base while surviving facilities expand individual offtake volumes.
United States Hydrogen Peroxide Market Segmentation
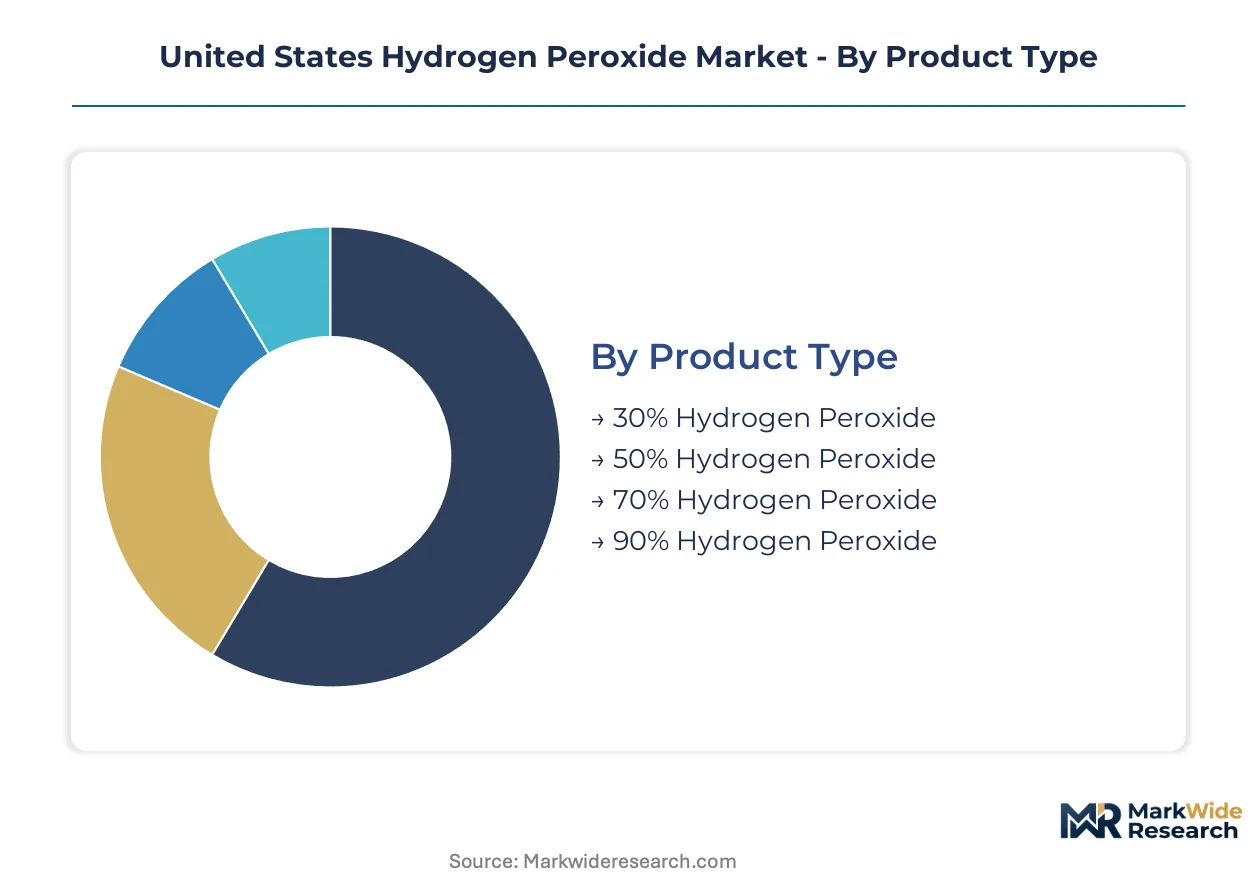
Hydrogen peroxide procurement patterns diverge sharply across concentration grades, with industrial buyers optimizing for handling safety and oxidative efficacy while municipal utilities prioritize regulatory compliance. Segment boundaries are blurring as electrolytic on-site generation disrupts traditional merchant supply models.
Product Type:
The 50% concentration grade captures the deepest margin pools, commanding premium pricing from pulp bleaching sequences and petrochemical oxidation processes that balance reactivity with transport economics.
- 30% Hydrogen Peroxide:Dilute aqueous solution favored by municipal water treatment facilities for advanced oxidation processes. Demand concentrates in Texas and Louisiana where EPA-mandated chlorine displacement is accelerating system retrofits.
- 50% Hydrogen Peroxide:Industrial workhorse concentration dominating pulp and paper procurement across the southeastern states. The anthraquinone-derived grade anchors long-term supply contracts with integrated chemical complexes seeking backward raw material security.
- 70% Hydrogen Peroxide:High-purity grade serving specialized chemical synthesis and semiconductor cleaning applications with stringent contamination limits.
- 90% Hydrogen Peroxide:Maximum concentration for propulsion and aerospace applications where storage density outweighs handling complexity and DOT transport restrictions.
The dominant share belongs to 50% Hydrogen Peroxide, while 30% Hydrogen Peroxide is closing the gap fastest on water treatment demand.
Application:
Application segmentation tracks divergent regulatory exposure, with water treatment applications climbing the fastest on Safe Drinking Water Act enforcement while pulp and paper contracts provide volume stability.
- Pulp & Paper:Elemental chlorine-free bleaching sequences across the Alabama-Georgia-South Carolina corridor specify high-purity grades. Southeastern mill consolidation is concentrating procurement leverage with fewer surviving facilities expanding individual offtake volumes.
- Water Treatment:Advanced oxidation processes for disinfection byproduct control and emerging contaminant destruction. Midwest and Southeast municipal utilities are redirecting capital from chlorine systems toward peroxide feed infrastructure under tightening EPA trihalomethane limits.
- Textile:Bleaching and desizing operations requiring consistent peroxide stability across variable temperature conditions.
- Chemical Synthesis:Oxidation feedstock for epoxidation and hydroxylation reactions in Gulf Coast petrochemical manufacturing.
Pulp & Paper retains the largest volume position, though Water Treatment is expanding most quickly on regulatory-driven infrastructure investment.
End User:
End user segmentation reflects fundamentally different procurement logics, with industrial buyers negotiating multi-year supply agreements while household consumers purchase through fragmented retail channels.
- Industrial:Petrochemical complexes, pulp mills, and chemical manufacturers procuring bulk volumes through direct sales relationships. Gulf Coast cluster expansions in Texas and Louisiana are anchoring regional supply contracts for merchant producers.
- Healthcare:Hospitals and pharmaceutical manufacturers requiring USP-grade material for sterilization and antiseptic applications with validated supply chain documentation.
- Household:Consumer disinfectant and laundry applications purchasing dilute solutions through retail and e-commerce channels.
- Agriculture:Crop treatment and irrigation system sanitation with seasonal demand patterns tied to planting cycles.
Industrial end users command the dominant procurement volume, while Healthcare is gaining share fastest on sterilization protocol standardization.
Distribution Channel:
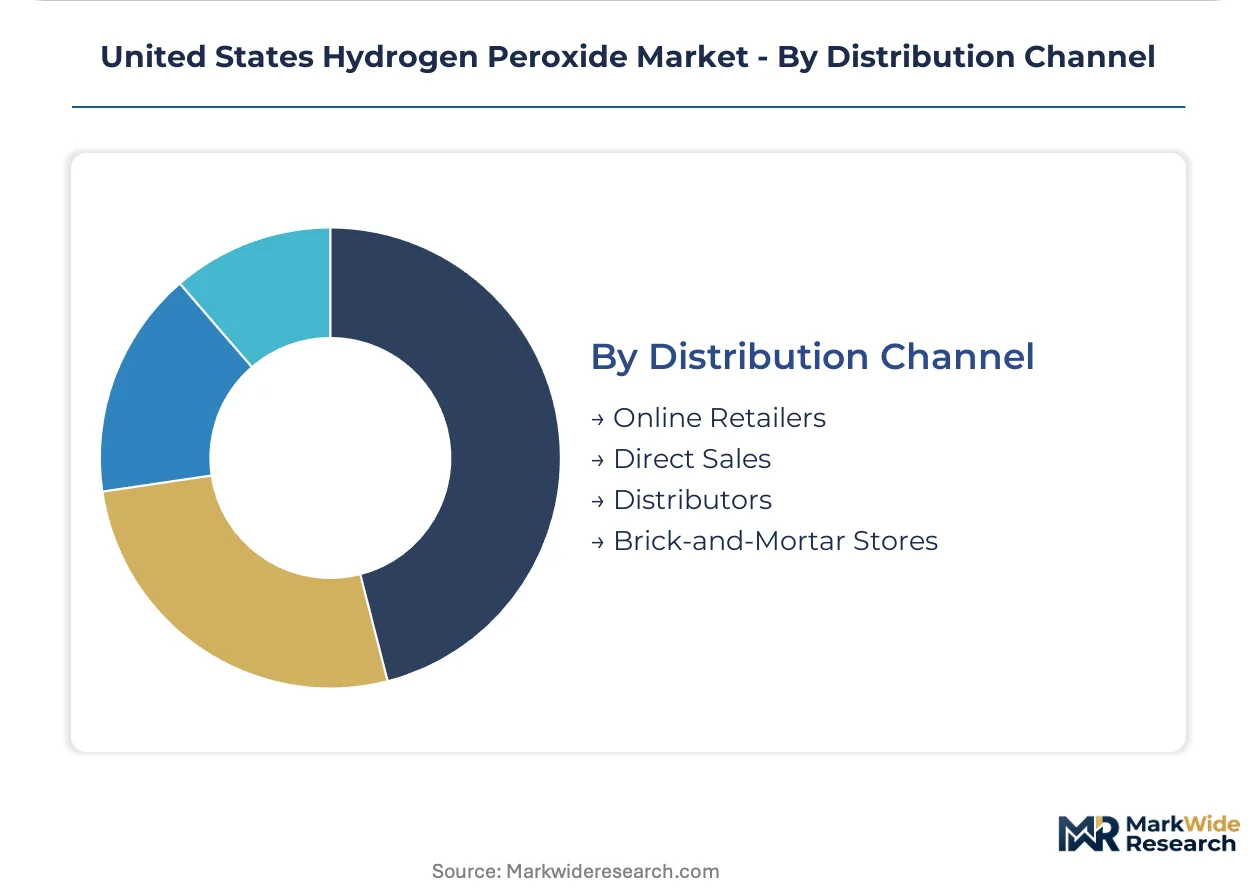
Channel structure is compressing as electrolytic on-site generation eliminates transport needs for mid-scale users, forcing traditional distributors to defend position through technical service bundling.
- Direct Sales:Large-volume industrial contracts with integrated producers bypassing intermediary markups. Gulf Coast chemical complexes and southeastern pulp mills negotiate directly with anthraquinone-integrated suppliers.
- Distributors:Regional chemical distributors serving mid-scale industrial users with inventory management and technical support. DOT hazmat classification for concentrations above 52% fragments logistics networks and elevates regional supply premiums.
- Online Retailers:E-commerce platforms capturing household and small commercial demand for dilute concentration grades.
- Brick-and-Mortar Stores:Mass retail and hardware channels for consumer disinfectant and cleaning product formulations.
Direct Sales holds the dominant channel position, though Distributors are defending relevance fastest through integrated service offerings for safety-critical handling protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast commands pricing leverage over Midwest utilities, where transport premiums for dilute grades compress margins against anthraquinone-integrated supply clusters in Texas and Louisiana.
Texas
Petrochemical complex expansions along the Houston Ship Channel anchor industrial-grade demand for 50% concentration supply. EPA's Safe Drinking Water Act enforcement accelerates municipal system retrofits in Dallas-Fort Worth and San Antonio. The Permian Basin oilfield services sector consumes peroxide for well stimulation and produced water treatment.
Louisiana
Mississippi River corridor chemical manufacturing concentrates merchant hydrogen peroxide offtake for oxidation processes. State environmental regulators prioritize trihalomethane reduction in Baton Rouge and New Orleans municipal systems. The Lake Charles industrial zone sustains captive production integration with ethylene oxide and propylene oxide derivatives.
Southeast
Alabama-Georgia-South Carolina pulp mills drive high-purity grade procurement for elemental chlorine-free bleaching sequences. Mill consolidation concentrates contract leverage with fewer surviving facilities expanding individual volumes. Savannah and Charleston ports facilitate imported raw material flows for anthraquinone derivative supply security.
Midwest
Chicago and Detroit water authorities redirect capital from chlorine infrastructure toward peroxide-based advanced oxidation systems under tightening EPA disinfection byproduct limits. Agricultural processing in Iowa and Illinois generates seasonal demand spikes for grain treatment and equipment sanitation. DOT hazmat restrictions fragment logistics networks, elevating regional supply premiums above Gulf Coast benchmarks.
California
Semiconductor fabrication in Silicon Valley specifies ultra-high-purity grades for wafer cleaning with contamination limits below parts-per-billion thresholds. State Water Resources Control Board mandates for emerging contaminant monitoring accelerate peroxide adoption in Los Angeles and San Diego municipal systems. Renewable hydrogen pilot projects explore electrolytic on-site generation to bypass concentrated solution transport constraints.
United States Hydrogen Peroxide Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with proprietary anthraquinone process specialists commanding premium positions while electrolytic modular suppliers undercut on delivered cost for mid-scale users. The market structure consolidates around integrated chemical majors with backward raw material security, leaving merchant operators exposed to quinone derivative supply volatility. Three archetypes dominate: Gulf Coast-integrated producers with captive hydrogen supply, European-headquartered multinationals with licensed process technology, and regional electrolytic specialists targeting distributed generation niches. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing long-term offtake agreements ahead of petrochemical cluster growth.
Among European-headquartered integrated producers, Evonik Industries AG and Solvay exemplify the technology-licensing archetype, occupying positions defined by proprietary auto-oxidation process control and anthraquinone derivative supply security. Arkema represents the specialty chemical diversification model, sitting within a portfolio context that extends beyond commodity peroxide into downstream derivatives. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning without requiring specific product or technology claims.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Solvay |
| Arkema |
| Ecolab Inc. |
| FMC Corporation |
| BASF SE |
| Kemira |
| Nouryon |
| OCI Chemical |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements with integrated Gulf Coast producers lock in anthraquinone-derived supply access while capping price volatility for southeastern pulp mills and Texas petrochemical complexes facing DOT hazmat transport premiums.
Pricing Analysis
Contract-to-spot pricing spreads widen dramatically for 50% concentration grades, with configured-to-order supply commanding premiums over standard merchant volumes. Price differentiation rests on backward anthraquinone integration status and EPA compliance documentation for municipal water treatment procurement. Cost compression in dilute 30% grades intensifies because electrolytic on-site generation bypasses merchant markups in the Upper Midwest. Industrial end users exhibit lowest price sensitivity due to captive process dependencies, while mid-scale municipal utilities negotiate hardest on delivered cost.
Supply Chain Analysis
Strategic stockpiling of anthraquinone derivatives dominates inventory strategy among integrated producers, while merchant operators run lean just-in-time positions exposed to quinone supply volatility. Manufacturing concentrates in Texas, Louisiana, and Ohio, with raw material dependencies spanning hydrogen feedstock, 2-alkylanthraquinone intermediates, and palladium catalyst systems. Single-source vulnerability runs through Gulf Coast hydrogen pipeline networks. Distribution runs through direct sales relationships for large-volume industrial buyers, supplemented by regional chemical distributors serving fragmented municipal utility demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as EPA-mandated chlorine displacement in municipal water treatment drives capital expenditure cycles across the Midwest and Southeast.
For Market Incumbents: Secure backward integration into anthraquinone raw materials to defend margin position against electrolytic modular entrants undercutting on delivered cost. Anchor long-term offtake agreements with Gulf Coast petrochemical cluster expansions before capacity additions materialize. Prioritize process safety management certification investments to differentiate from merchant competitors lacking OSHA-compliant handling protocols. For New Entrants and Emerging Players: Technical service gaps in municipal retrofit engineering present white-space opportunities where incumbents under-serve legacy chlorine system integration. Target mid-scale water treatment facilities in the Upper Midwest with modular electrolytic generation units bypassing DOT hazmat logistics constraints. Pursue equipment-leasing go-to-market models compressing upfront capital barriers for utilities. For Investors and Strategic Acquirers: Capital is best deployed toward electrolytic technology specialists with renewable power purchase agreement pipelines enabling carbon-intensity positioning for ESG-focused industrial buyers. Long-term viability favors assets with distributed generation architectures decoupled from anthraquinone supply volatility. Watch state-level PFAS remediation mandate promulgation velocity as the inflection signal for advanced oxidation process demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anthraquinone | Captures margin pools from quinone derivative supply security at Gulf Coast chemical complexes. |
| Electrolytic On-Site Generation Deployment | Bypasses DOT hazmat restrictions while serving ESG procurement criteria for carbon-conscious buyers. |
| Long-Term Municipal Supply Agreements | Locks in volume visibility ahead of EPA Safe Drinking Water Act enforcement acceleration. |
| Process Safety Management Certification | Differentiates handling capabilities for concentrated solutions above OSHA threshold concentrations. |
| PFAS Remediation Technology Partnerships | Positions advanced oxidation processes for emerging contaminant destruction mandate compliance. |
Research Approach
Initial hypotheses were tested against primary input from plant managers at integrated chemical complexes, procurement leads at southeastern pulp mills, municipal water treatment directors, and distribution channel partners, then refined through secondary validation against EPA enforcement databases, ACC industry statistics, DOT hazmat incident reports, and SEC 10-K filings. Bottom-up volume modeling triangulated with top-down macroeconomic drivers.
Variance decomposition across concentration grades, end-use industries, and regional production hubs structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating anthraquinone process energy intensity trends and electrolytic technology cost curves. Forecast inputs included state-level PFAS regulatory pipeline velocity and pulp mill capacity consolidation patterns.
Forecasts assume regulatory continuity in EPA Safe Drinking Water Act enforcement and state-level emerging contaminant monitoring regimes; material policy shifts would require re-modeling demand trajectories for municipal advanced oxidation adoption. Revision becomes warranted when electrolytic on-site generation cost curves cross anthraquinone-derived delivered cost thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Hypochlorite Bleaches Market
Disinfectants and Preservatives
Surface Disinfectant Products Market
Disinfectants and Preservatives
Deltamethrin Market
Disinfectants and Preservatives
Artificial Preservatives Market
Disinfectants and Preservatives
IV Disinfecting Caps Market
Disinfectants and Preservatives
Europe Hydrogen Peroxide Market
Disinfectants and Preservatives
Disinfectant Wipes Market
Disinfectants and Preservatives
Nisin Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
Sodium Bisulphite Market
Disinfectants and Preservatives
Sulfuryl Fluoride Market
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
Microbial Control Chemical Market
Disinfectants and Preservatives
North America Hydrogen Peroxide Market
Disinfectants and Preservatives
Global Antiseptic and Disinfectant Market
Disinfectants and Preservatives
MMA Triazine Market