
 Beryllium Copper for Industrial Equipment Market | 2026-2036
Beryllium Copper for Industrial Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Beryllium Copper for Industrial Equipment Market Insights
Multi-source procurement for beryllium copper alloys is expanding as machinery fabricators diversify away from concentrated supply chains. Materion leverages captive mining and refining operations to secure upstream control over high-purity beryllium feedstock. NGK Metals anchors its position through advanced strip and wire manufacturing in Japan. IBC Advanced Alloys differentiates via defense-focused product lines and North American casting capabilities.
Beryllium copper is a precipitation-hardenable copper alloy containing roughly 0.5-3% beryllium by weight, delivering tensile strengths exceeding 1,200 MPa while retaining thermal conductivity near 100 W/m·K, making it indispensable for electrical connectors, springs, and non-sparking tools in hazardous environments. Strip and wire forms command premium positioning due to tight dimensional tolerances required in electronics manufacturers and aerospace components. Rod and plate categories sustain volume throughput in oilfield tools and welding equipment, though margin pools concentrate in precipitation-hardened spring temper grades serving defense contractors.
OSHA beryllium exposure limits and EPA toxic substance reporting obligations shape product handling protocols and fabrication site location decisions across the United States. REACH registration requirements and RoHS material restrictions in Europe filter market access for non-compliant alloy suppliers. JIS standards in Japan and BIS certification pathways in India add further compliance layers for cross-border equipment shipments. Stakeholders must monitor evolving particulate exposure thresholds and recycling mandates to anticipate where certified alloy premiums will widen against commoditized alternatives.
Market Dynamics
OSHA's tightening beryllium exposure limits are forcing fabrication site relocations and capital-intensive ventilation retrofits across United States oilfield tool manufacturing, while REACH registration deadlines in Europe filter supplier eligibility and concentrate certified alloy premiums.
Growth Catalysts
- OSHA Workplace Safety Mandates:Tighter explosive atmosphere rules around non-sparking tools are expanding defense contractor orders for beryllium copper oilfield equipment in hazardous environments.
- Precision Aerospace Demand:German and Japanese manufacturers of high-tolerance connectors and springs are driving certified alloy consumption under JIS and REACH material standards.
- Thermal Management Requirements:Electronics manufacturers specify precipitation-hardened grades for heat-dissipating electrical connectors where copper alternatives fail conductivity thresholds.
Market Restraints
- Beryllium Feedstock Concentration:High-purity beryllium mining and refining capacity concentrates in limited upstream operations, creating supply vulnerability for alloy producers.
- Substitution Pressure from Copper-Nickel-Silicon:Lower-cost alloys are displacing beryllium copper in non-critical spring applications where extreme strength is not mandatory.
- EPA Toxic Substance Reporting:Fabrication facilities face elevated compliance costs and site location constraints under federal hazardous material tracking obligations.
Strategic Opportunities
- Indian Infrastructure Buildout:BIS certification pathways for industrial equipment are opening certified alloy penetration in power transmission and welding tool manufacturing.
- Defense Electrification:Connector demand for military vehicle power systems is creating new volume channels for high-conductivity strip and wire forms.
- Additive Manufacturing Convergence:Powder metallurgy and selective laser melting are enabling near-net-shape production of complex beryllium copper components previously machined from solid stock.
Industry Challenges
- Particulate Handling Expertise Gap:Fabrication facilities struggle to recruit certified technicians for safe beryllium machining and waste containment under OSHA protocols.
- Multi-Jurisdiction Certification Timelines:Simultaneous REACH, JIS, and BIS compliance processes extend product qualification cycles by 18-24 months for cross-border equipment shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beryllium Copper for Industrial Equipment Market |
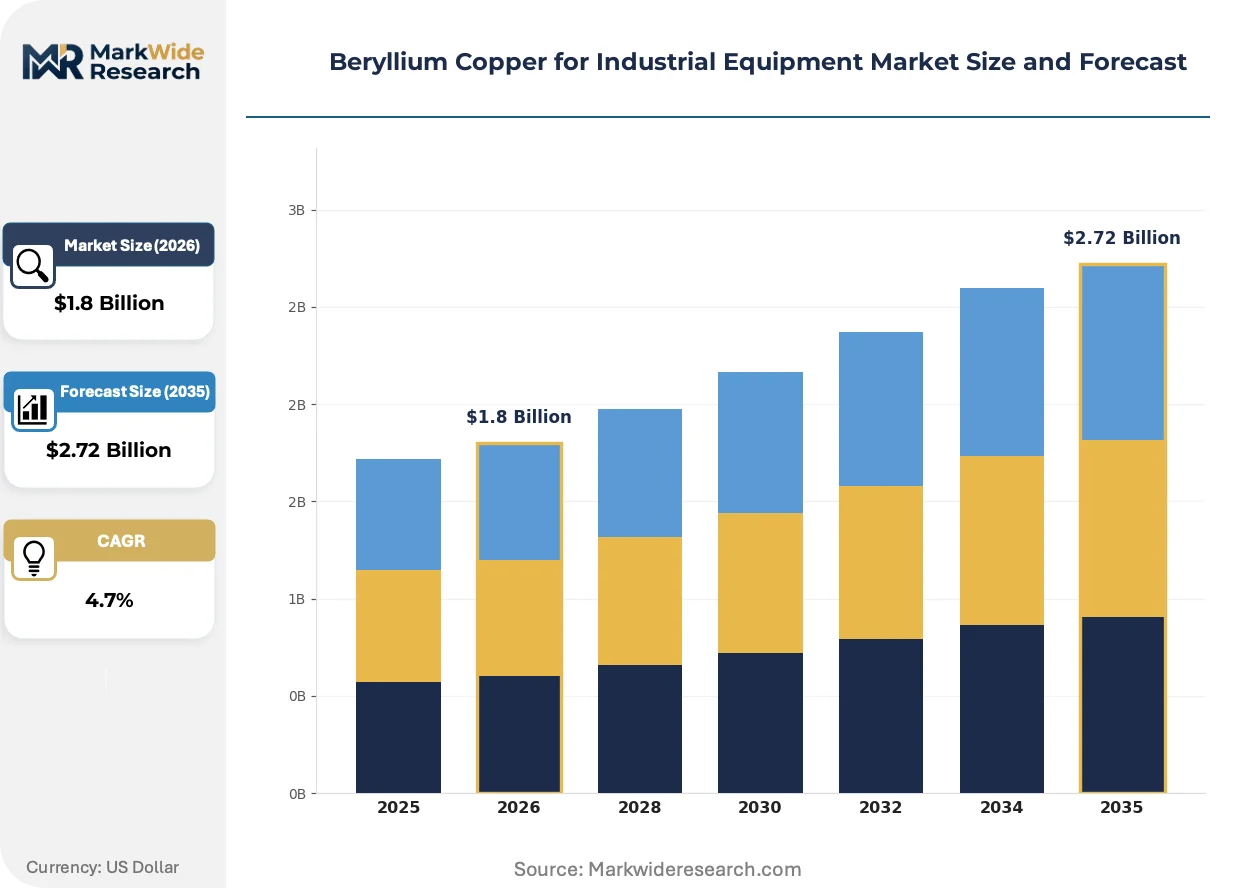
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rod, Wire, Plate, Strip, Tube Form: Annealed, Hardened, Spring Temper, Precipitation Hardened Application: Electrical Connectors, Springs, Welding Equipment, Aerospace Components, Oilfield Tools End User Industry: Electronics Manufacturers, Defense Contractors, Energy Services, Machinery Fabricators |
| Companies Covered | Materion, NGK Metals, IBC Advanced Alloys, Belmont Metals, Aviva Metals, Ampco Metal, ALB Copper Alloy, CNMC Ningxia Orient Group, Wieland-Werke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beryllium Copper for Industrial Equipment Market Trends and Innovations
Material processing advances and regulatory harmonization pressures are reshaping how beryllium copper alloys are specified, certified, and delivered to industrial equipment manufacturers across defense, aerospace, and energy verticals.
Near-net-shape powder metallurgy is decentralizing traditional machined-component supply chains by enabling direct formation of complex geometries without extensive material removal. Defense contractors in the United States are adopting these consolidated blanks for connector housings and spring elements. This compression of process steps is reducing lead times and raw material waste in high-mix, low-volume production environments.
REACH authorization requirements for beryllium compounds are tightening material traceability obligations across European aerospace supply chains. Manufacturers must now document alloy composition through every processing stage to maintain CE marking eligibility. German precision machining clusters are responding by consolidating supplier bases to pre-certified foundries with established ECHA registration portfolios.
Long-term service agreements are replacing spot purchases for critical spring and connector inventories in oilfield tool fleets. Equipment operators in the United States now contract directly with alloy processors for consignment stock and just-in-time tempering services. This shift compresses working capital cycles for fabricators while locking in volume commitments through multi-year offtake structures.
Beryllium Copper for Industrial Equipment Market Segmentation
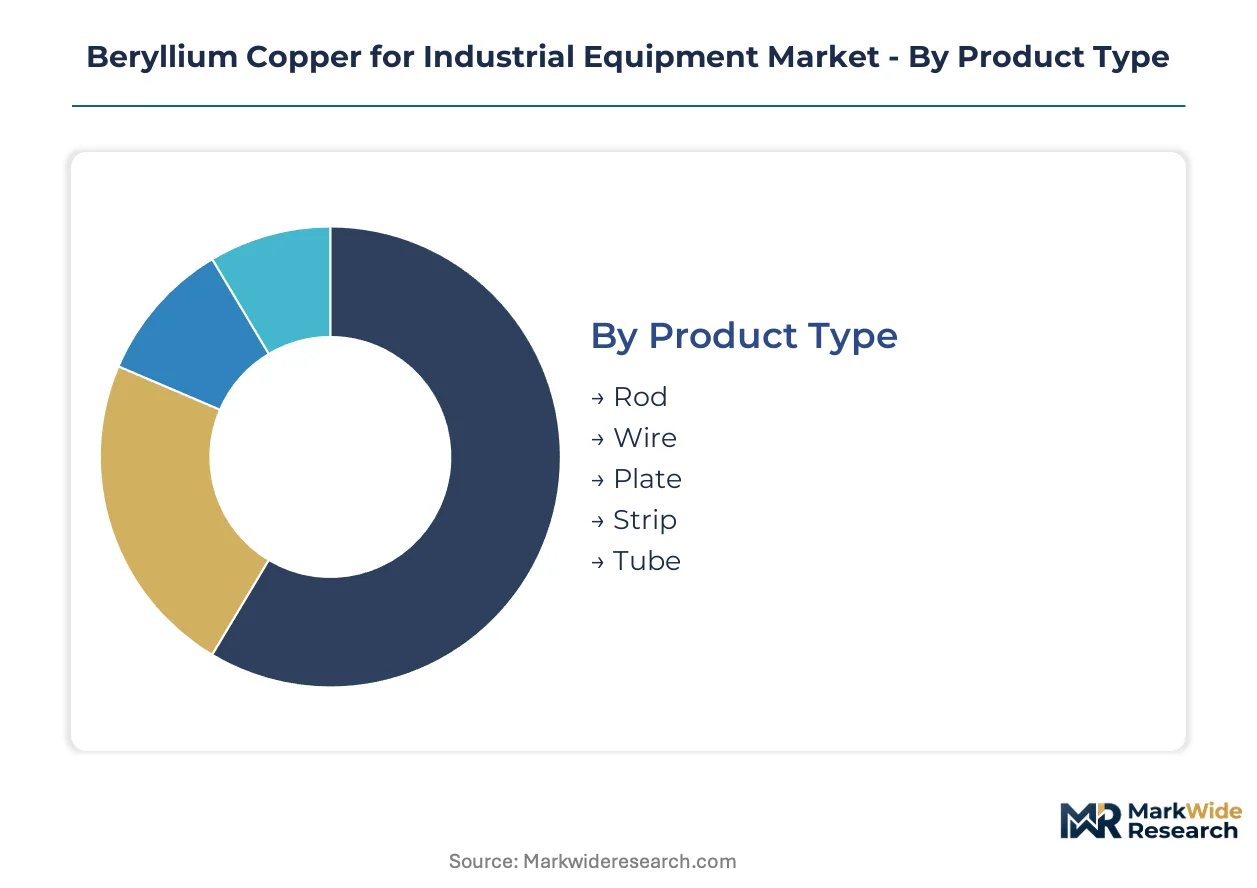
Beryllium copper alloys serve sharply differentiated technical requirements across defense, aerospace, and energy verticals. Segmentation reveals how form factors and temper grades concentrate margin pools in precision-machined components versus commodity oilfield tooling.
Product Type:
Buyers in this category differentiate by dimensional tolerance requirements and downstream machining intensity.
- Strip:Ultra-thin gauges down to 0.05mm enable high-density electrical connector arrays. German automotive electronics suppliers and Japanese robotics manufacturers drive certified alloy consumption under REACH and JIS material standards.
- Wire:Cold-drawn diameters spanning 0.025mm to 12mm serve precision spring applications. Defense contractors in the United States specify precipitation-hardened wire for military vehicle electrical systems where fatigue resistance is mandatory.
- Rod:Round bar stock for CNC-machined oilfield components.
- Plate:Flat stock for welding electrode fabrication and fixture plates.
- Tube:Hollow profiles for fluid handling in hazardous environment equipment.
Strip leads volumes today; wire is gaining share fastest.
Form:
Processing state determines mechanical properties and dictates which fabrication shops can handle the material.
- Precipitation Hardened:Age-hardened to 38-42 HRC delivering tensile strengths exceeding 1,200 MPa. Aerospace fastener manufacturers and defense connector suppliers pay premium spreads for this grade to avoid in-house heat treatment.
- Spring Temper:Cold-worked to high hardness for elastic components. Japanese precision spring fabricators dominate procurement of this form for robotics and semiconductor equipment.
- Annealed:Soft condition for complex forming operations before final hardening.
- Hardened:Mill-hardened stock for immediate machining without additional processing.
Precipitation hardened commands the highest unit margins; spring temper shows the steepest expansion trajectory.
Application:
End-use performance requirements separate price-insensitive specification buyers from cost-driven commodity purchasers.
- Aerospace Components:Fasteners, bushings, and landing gear pins requiring fatigue life certification. German machining clusters around Stuttgart and Munich concentrate demand for AMS-compliant alloy grades.
- Electrical Connectors:Heat-dissipating contacts where thermal conductivity must exceed 100 W/m·K. Electronics manufacturers in Japan and South Korea specify these grades for high-current density applications.
- Springs:Load-bearing elastic elements across industrial equipment.
- Welding Equipment:Non-sparking electrode holders and fixtures.
- Oilfield Tools:Non-sparking wrenches, hammers, and gauges for explosive atmospheres.
Aerospace components generate the highest alloy premiums; electrical connectors are expanding most quickly.
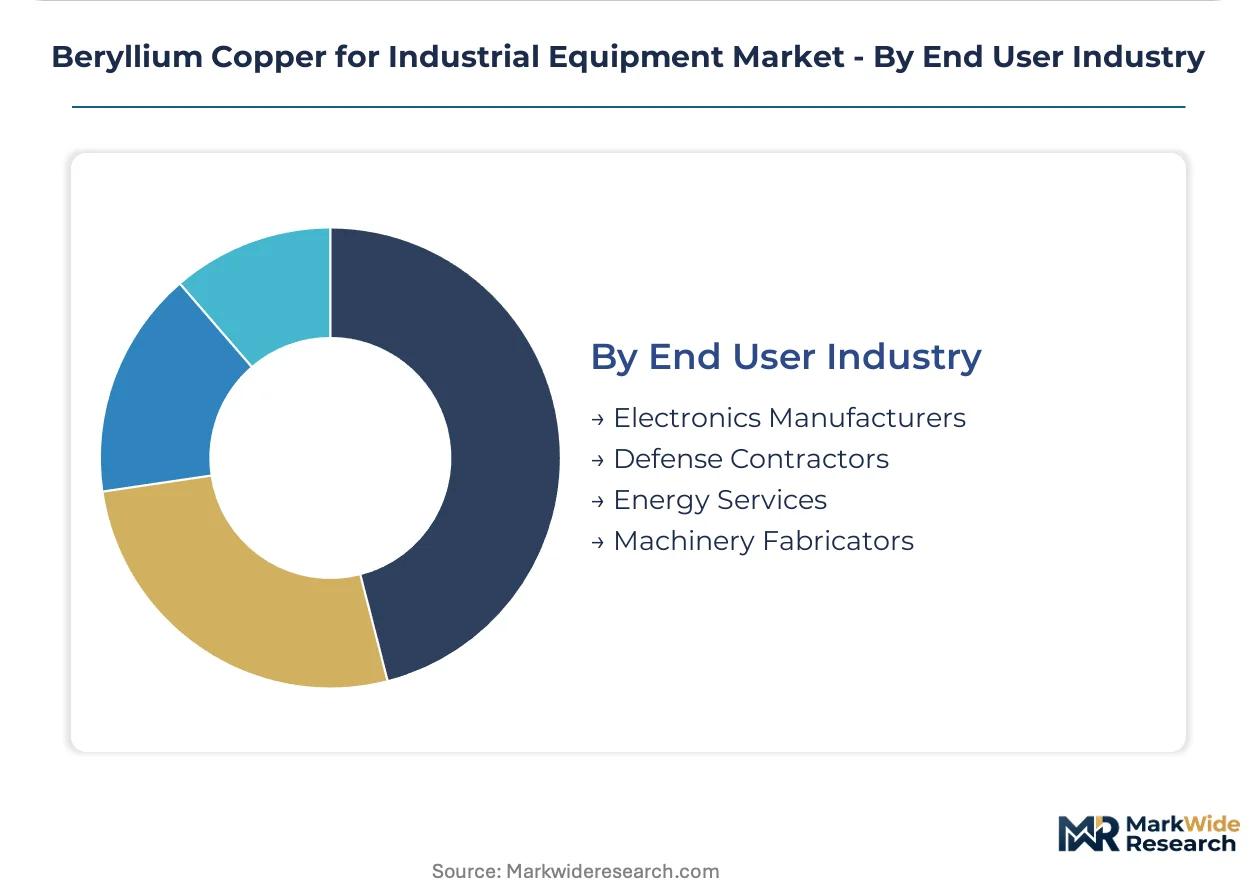
End User Industry:
Procurement sophistication and certification requirements create distinct customer tiers.
- Defense Contractors:Long-term offtake agreements with traceability mandates. United States prime contractors now contract directly with alloy processors for consignment stock and just-in-time tempering services.
- Electronics Manufacturers:High-volume, specification-driven purchasing with tight dimensional tolerances. Japanese consumer electronics and South Korean semiconductor equipment makers anchor demand for ultra-thin strip and wire.
- Energy Services:Oilfield tool fleet operators with cyclical replacement schedules.
- Machinery Fabricators:General industrial equipment builders with cost-sensitive sourcing.
Defense contractors anchor premium pricing; electronics manufacturers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping beryllium copper fabrication geography as OSHA exposure mandates in the United States elevate compliance costs and push capacity toward jurisdictions with streamlined permitting.
United States
Defense contractors anchor demand for non-sparking oilfield tools and aerospace connectors. OSHA's tightened beryllium exposure limits force fabrication site relocations and capital-intensive ventilation retrofits. Houston and Tulsa industrial clusters concentrate oilfield tool manufacturing under escalating federal hazardous material tracking obligations.
Germany
Precision-machined aerospace components drive certified alloy consumption for fasteners and landing gear pins. REACH registration requirements and RoHS material restrictions filter supplier eligibility and concentrate premiums among ECHA-registered foundries. Stuttgart and Munich machining clusters consolidate supplier bases to pre-certified operations with established authorization portfolios.
Japan
Electronics manufacturers and robotics fabricators specify ultra-thin strip and wire under JIS material standards. METI industrial policy reinforces domestic supply chain resilience for critical alloy grades. Nagoya and Osaka precision spring fabricators dominate procurement of cold-worked spring temper forms for semiconductor equipment.
China
Power transmission infrastructure and welding tool manufacturing expand certified alloy penetration. GB standards and MIIT industrial regulations govern material certification for cross-border equipment shipments. Yangtze River Delta fabrication clusters scale precipitation-hardened grade production for domestic aerospace and electronics verticals.
India
BIS certification pathways for industrial equipment open certified alloy penetration in welding electrode and fixture manufacturing. CEA power sector mandates and PLI scheme incentives accelerate domestic fabrication capacity. Gujarat and Maharashtra industrial corridors attract alloy processors seeking lower particulate handling compliance costs than Western jurisdictions.
Beryllium Copper for Industrial Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing and near-net-shape processing capabilities. The vendor base stratifies across integrated miners, specialized alloy processors, and regional distribution fabricators. Three archetypes dominate: upstream-integrated players with captive beryllium feedstock, precision-form specialists commanding dimensional tolerance premiums, and defense-focused operators with North American casting qualifications. Capacity expansion and strategic partnerships represent the dominant competitive vectors as fabricators seek to secure qualified supply under tightening certification timelines.
Among upstream-integrated players, Materion exemplifies the archetype of captive mining and refining operations securing high-purity beryllium feedstock control. NGK Metals occupies a position within the precision-form specialist tier, anchoring advanced strip and wire manufacturing capabilities. IBC Advanced Alloys represents the defense-focused operator archetype, sitting within North American casting and defense-qualified product lines.
| Leading Market Players |
|---|
| Materion |
| NGK Metals |
| IBC Advanced Alloys |
| Belmont Metals |
| Aviva Metals |
| Ampco Metal |
| ALB Copper Alloy |
| CNMC Ningxia Orient Group |
| Wieland-Werke |
| Others |
Pricing and Supply Chain Analysis
Defense contractor consolidation around long-term offtake agreements for precipitation-hardened grades is compressing spot market liquidity and forcing alloy processors to absorb beryllium feedstock volatility into contract structures.
Pricing Analysis
High-purity beryllium feedstock costs pass through to alloy premiums with limited lag, creating margin compression for processors lacking captive mining operations. Three-tier pricing structure across certified aerospace grades, standard industrial temper, and commodity oilfield specifications separates price-insensitive specification buyers from cost-driven fleet operators. Cost compression in commodity rod and plate categories is intensifying as copper-nickel-silicon alternatives capture non-critical spring applications. Electronics manufacturers in Japan and South Korea show the least price sensitivity due to thermal conductivity mandates, while machinery fabricators in India exhibit acute cost consciousness.
Supply Chain Analysis
Domestic content requirements under India's PLI scheme and China's MIIT industrial regulations are reshaping sourcing patterns toward local smelting and finishing capacity. High-purity beryllium mining concentrates in the United States and Kazakhstan, while precision strip and wire processing anchors in Japan and Germany. The supply chain rests on concentrated upstream feedstock and specialized downstream fabrication expertise. Single-source vulnerability in high-purity beryllium refining creates structural exposure to export restriction shocks. Distribution runs through direct mill relationships for defense and aerospace tiers, with regional distributors serving cost-sensitive industrial fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beryllium copper market compounds steadily as regulatory safety mandates harden substitution barriers and lock in specification-driven procurement.
For Market Incumbents: To counter copper-nickel-silicon displacement in mid-tier spring applications, deepen backward integration into high-purity beryllium feedstock and expand precipitation-hardening capacity in jurisdictions with streamlined OSHA permitting. Lock in defense contractor consignment stock agreements to compress competitor access to qualified volume channels. For New Entrants and Emerging Players: BIS certification pathways in India open a window for certified alloy penetration in welding electrode and power transmission infrastructure where incumbent presence remains thin. Target Gujarat and Maharashtra industrial corridors with additive manufacturing capabilities for near-net-shape connector housings. Pursue direct qualification with CEA-mandated utilities to bypass established distribution layers. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-form specialists commanding dimensional tolerance premiums in sub-0.1mm strip gauges. The five-to-ten-year viability thesis rests on regulatory ratcheting in explosive atmosphere standards across multiple jurisdictions. Monitor EPA toxic substance reporting threshold revisions as the inflection signal for fabrication site relocation waves and associated equipment spending cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beryllium Feedstock | Materion's captive mining operations secure margin insulation against concentrate price volatility. |
| Long-term Supply Agreement | Defense contractor consignment stock structures compress working capital cycles for qualified processors. |
| Capacity Expansion in Low-Compliance-Cost Jurisdictions | Gujarat fabrication clusters attract investment seeking relief from OSHA ventilation retrofit burdens. |
| Additive Manufacturing Qualification | Powder metallurgy capabilities enable near-net-shape production for complex connector geometries. |
| Multi-Jurisdiction Certification Investment | Simultaneous REACH, JIS, and BIS registration accelerates cross-border equipment shipment eligibility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, aerospace fastener engineers, oilfield tool fleet managers, and alloy processor technical directors with secondary validation against SEC 10-K filings, customs trade data, and ECHA registration databases. Bottom-up alloy consumption estimates by end-use application were triangulated against top-down market value reconstructions.
Comparable historical periods anchored the projection framework across the analysis window, with segmentation modeling across product form, temper grade, end-use industry, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating defense electrification capex cycles, electronics thermal management specifications, and oilfield safety mandate implementation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under beryllium export restriction scenarios or accelerated copper-nickel-silicon substitution in non-critical applications. Forecasts reflect documented assumptions regarding regulatory timeline adherence and certification backlog resolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Prebaked Anodes for Aluminum Market
Metals
North America Grain Oriented Electrical Steel Market
Metals
High Purity Base Metals Market
Metals
Copper Azoles Market
Metals
Aluminum Welding Market
Metals
North America Aluminum Market
Metals
Industrial Silver Market
Metals
Aluminium Powder Market
Metals
Global Mercury Market
Metals
Refined Nickel Market
Metals
Titanium Mill Products Market
Metals
Global Flat Steel Market
Metals
Arc Ferrite Magnet Market
Metals
Metal Finishing Market
Metals
Potassium Platinochloride Market
Metals
316 Stainless Steel Container Market