
 Aluminum Scrap Recycling Market | 2026-2036
Aluminum Scrap Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Scrap Recycling Market Analysis
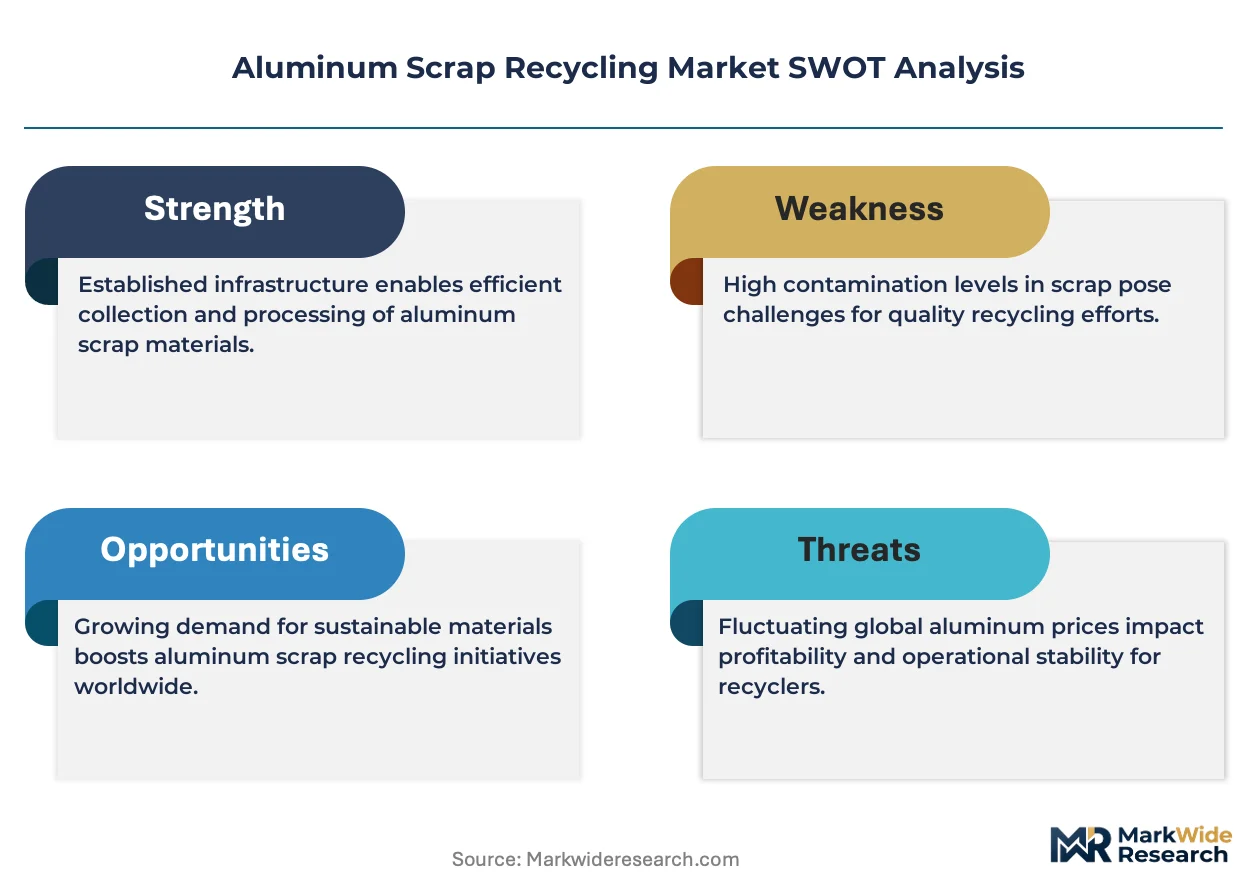
Project finance tied to green bond issuance is reconfiguring capital access for secondary aluminum producers. Novelis Inc. leverages its closed-loop recycling partnerships with automotive OEMs to secure long-dated offtake agreements. Norsk Hydro ASA anchors its position through captive hydro-powered smelting in Norway, yielding carbon-accounted metal premiums. REAL Alloy competes on toll-processing contracts that shift price risk to scrap suppliers while capturing volume fees.
Aluminum scrap recycling encompasses the collection, sorting, shredding, and remelting of post-consumer and post-industrial aluminum waste to produce specification-grade secondary alloys with recovered content typically exceeding 95 percent. The process serves primarily to displace energy-intensive primary aluminum in sectors where carbon footprint disclosure now governs supplier selection. Aluminum extrusions command durable margin pools because building-sector decarbonization mandates specify high-recycled-content structural profiles. Automotive end-user demand for wrought alloy sheet and casting ingots outpaces other segments as OEMs redesign components for closed-loop recyclability. Collection through industrial channels concentrates the cleanest feedstock, reducing downstream purification burdens and melting losses relative to curbside streams.
The EPA enforces hazardous waste classifications that determine which aluminum-bearing drosses and salt cakes trigger cradle-to-grave tracking, directly shaping processing economics for US operators. ECHA administers REACH substance restrictions that limit tramp element tolerances in scrap destined for food-contact and medical applications, filtering export flows into Europe. China's MEE imposes dual carbon goals that cap smelter emissions intensity, redirecting domestic demand toward imported scrap over primary metal. Stakeholders must monitor how carbon border adjustment mechanisms redefine competitive access for scrap-fed producers versus integrated primary smelters.
Market Dynamics
Carbon border adjustment mechanisms are forcing scrap-fed producers to document lifecycle emissions intensity while primary smelters face import tariffs on carbon-heavy metal, tilting procurement economics toward verified secondary supply chains.
Growth Catalysts
- EU Green Deal compliance:Automotive OEMs in Germany, France, and Italy now mandate minimum recycled content thresholds in powertrain castings, pulling specification-grade scrap through closed-loop collection networks.
- Building sector decarbonization:Structural engineers specify high-recycled-content aluminum extrusions for LEED and BREEAM certification, concentrating demand for 6063 alloy scrap in commercial construction clusters.
- Dual carbon goals in China:MEE emissions caps on domestic primary smelting redirect industrial buyers toward imported scrap streams, expanding seaborne trade flows from North American and European collection hubs.
Market Restraints
- Natural gas price volatility:Remelting furnaces in Germany and the Netherlands face input cost squeezes that compress toll-processing margins when scrap prices lag energy spikes.
- Curbside feedstock contamination:Post-consumer mixed scrap carries elevated magnesium and silicon loads that require downstream salt-slag treatment, raising unit processing costs versus industrial channel material.
- REACH substance restrictions:ECHA limits on tramp elements in food-contact and medical applications filter export flows, blocking certain scrap grades from premium end-use markets.
Strategic Opportunities
- India's PLI scheme for auto components:Secondary alloy producers can anchor capacity near Chennai and Pune industrial corridors to serve emerging EV casting demand with carbon-accounted metal.
- Sensor-based sorting convergence:X-ray fluorescence and laser-induced breakdown spectroscopy integration enables real-time alloy identification, unlocking value from previously commingled shredder fractions.
- Green bond project finance:Long-dated offtake agreements tied to certified low-carbon output attract institutional capital for brownfield capacity expansions in Norway and Quebec hydro-powered zones.
Industry Challenges
- Metallurgical technician scarcity:Operators struggle to hire personnel fluent in spectrographic analysis and salt-slag chemistry, slowing commissioning of advanced sorting and refining lines.
- Multi-standard certification timelines:Scrap processors seeking simultaneous ISO 14001, ASI Performance Standard, and customer-specific OEM approvals face 18-24 month audit cycles that delay contract eligibility.
- Legacy ERP integration:Mass-balance tracking systems for carbon accounting must interface with decades-old smelter control architecture, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Scrap Recycling Market |
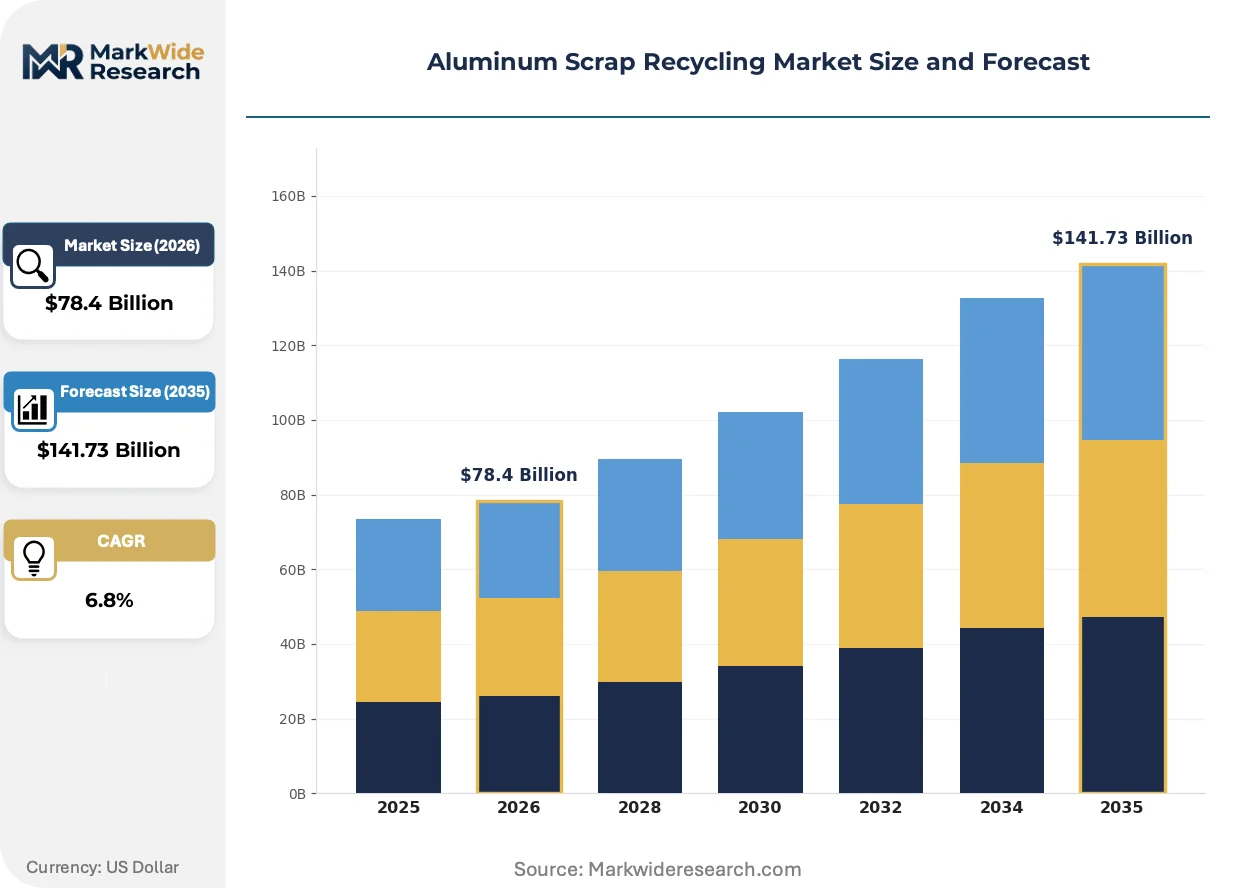
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Aluminum Foil, Aluminum Extrusions, Aluminum Ingots End User: Automotive, Construction, Aerospace, Packaging Collection Method: Curbside Collection, Drop-off Centers, Industrial Collection, Scrap Yards Processing Technology: Shredding, Melting, Purification, Casting |
| Companies Covered | Novelis Inc., REAL ALLOY, Norsk Hydro ASA, Sims Metal Management, ArcelorMittal S.A., Constellium, Matalco Inc., Aurubis AG, Alcoa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Scrap Recycling Market Emerging Trajectories
Digital traceability infrastructure and automated alloy identification are compressing quality assurance cycles while regulatory disclosure requirements harden specifications for secondary metal acceptance.
Artificial intelligence-driven scrap classification is digitizing material routing decisions in real time. German and Austrian shredding facilities deploy machine vision systems that match flake geometry and surface texture against alloy databases. Automotive tier-one suppliers now reject batches lacking blockchain-anchored provenance records, forcing upstream collectors to adopt sensor-to-ledger data pipelines.
REACH substance restrictions are tightening tramp element tolerances for scrap entering food-contact and medical applications. ECHA's updated annex XVII entries force exporters to pre-sort material streams before EU port arrival. Secondary smelters serving packaging and pharmaceutical verticals now maintain segregated furnace campaigns with dedicated crucible sets to avoid cross-contamination penalties.
Buyer consortiums are consolidating procurement of specification-grade secondary alloys through multi-year tolling agreements that transfer scrap price risk to processors. German automotive clusters negotiate directly with Novelis and Hydro for closed-loop extrusion and casting supply. This disintermediates traditional merchant traders and locks volume commitments to specific carbon-intensity thresholds verified by third-party auditors.
Aluminum Scrap Recycling Market Segmentation
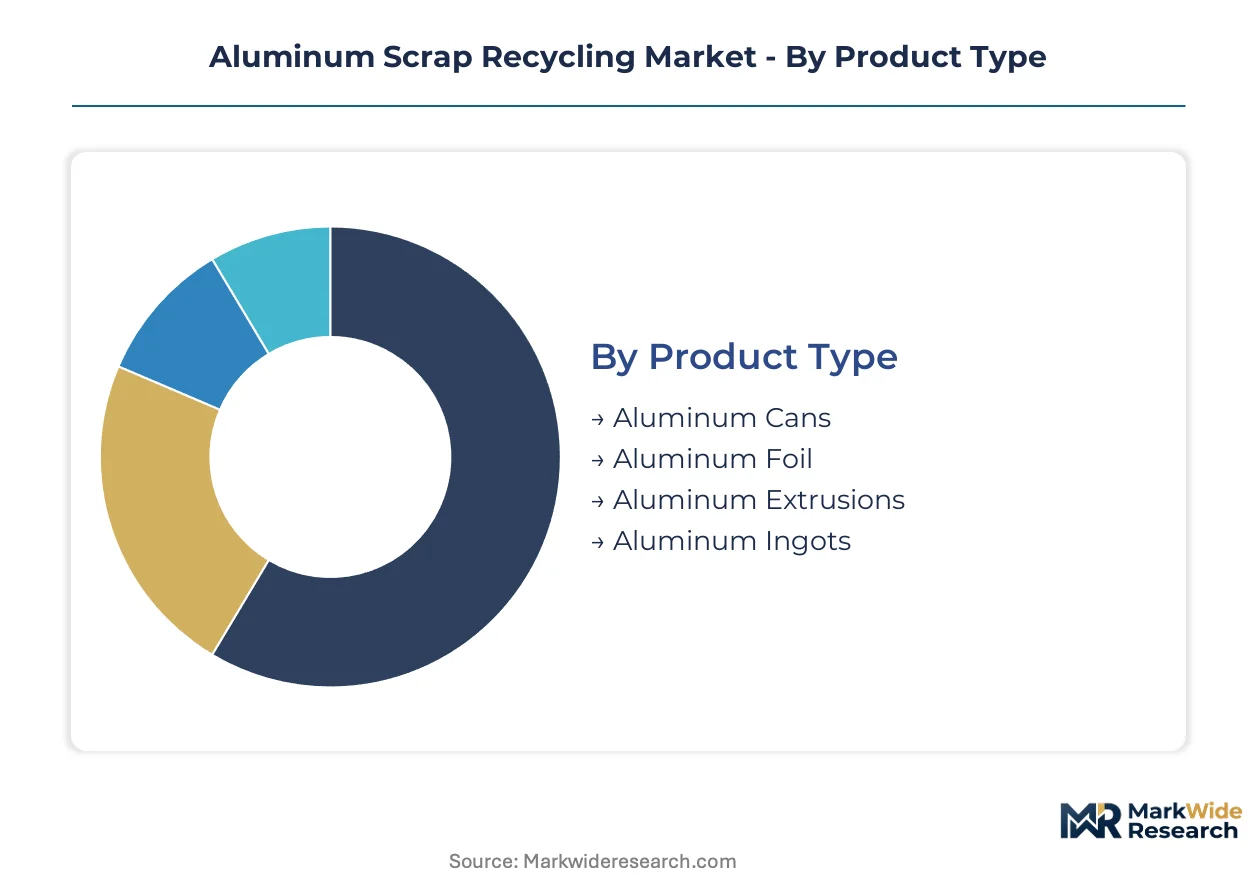
Segmentation in aluminum scrap recycling reveals how material form, collection channel purity, and end-use specifications create divergent margin structures across the value chain. Each dimension carries distinct processing economics and regulatory exposure that shape competitive positioning.
Product Type:
Material form determines alloy composition clarity and downstream purification burden.
- Aluminum Extrusions:Clean 6063 alloy profiles from building demolition carry predictable chemistry and minimal contamination. German construction clusters under EU Green Deal mandates now specify high-recycled-content structural extrusions for LEED certification, pulling premium-grade scrap through dedicated collection networks.
- Aluminum Cans:Beverage containers offer standardized 3104 alloy chemistry with established closed-loop infrastructure. Novelis operates dedicated can-to-can recycling circuits serving US and European packaging OEMs with carbon-accounted metal premiums.
- Aluminum Foil:Thin-gauge household and industrial foil requires delacquering before remelting, adding thermal processing costs.
- Aluminum Ingots:Specification-grade secondary ingots serve as tradable intermediate products for foundries lacking captive remelting capacity.
Aluminum extrusions command the established base. The steepest expansion runs through aluminum cans as beverage OEMs accelerate closed-loop commitments.
End User:
Application-specific alloy requirements create tiered pricing based on metallurgical tolerance and certification burden.
- Automotive:Powertrain castings and body sheet demand tight silicon and magnesium control. German OEMs now mandate minimum recycled content thresholds verified through ASI Performance Standard audits, concentrating procurement through Novelis and Hydro tolling agreements.
- Construction:Structural extrusions tolerate broader chemistry ranges than aerospace or medical applications. Commercial building decarbonization mandates in France and Italy specify high-recycled-content 6063 profiles, anchoring regional scrap flows.
- Aerospace:Aviation-grade alloys require extensive spectrographic verification and traceable provenance records.
- Packaging:Food-contact applications face ECHA REACH substance restrictions on tramp elements, filtering export flows into Europe.
Construction absorbs the highest tonnage volumes. Automotive applications are climbing the fastest as OEMs redesign components for closed-loop recyclability.
Collection Method:
Feedstock channel purity directly determines downstream processing economics and melting yield.
- Industrial Collection:Post-industrial scrap from manufacturing offcuts carries known alloy composition and minimal surface contamination. German automotive stamping plants generate clean 5xxx and 6xxx series flows that bypass shredding and move directly to remelting furnaces.
- Curbside Collection:Mixed post-consumer streams require extensive sensor-based sorting and salt-slag treatment for magnesium removal. Netherlands operators face elevated unit costs when natural gas price spikes compress toll-processing margins.
- Drop-off Centers:Consumer-delivered material offers intermediate purity between curbside and industrial channels.
- Scrap Yards:Merchant aggregators blend heterogeneous streams for volume sales to secondary smelters.
Industrial collection holds the margin advantage. Curbside infrastructure is expanding most quickly as municipalities extend separate collection mandates.
Processing Technology:
Technology selection hinges on feedstock contamination level and target alloy specification.
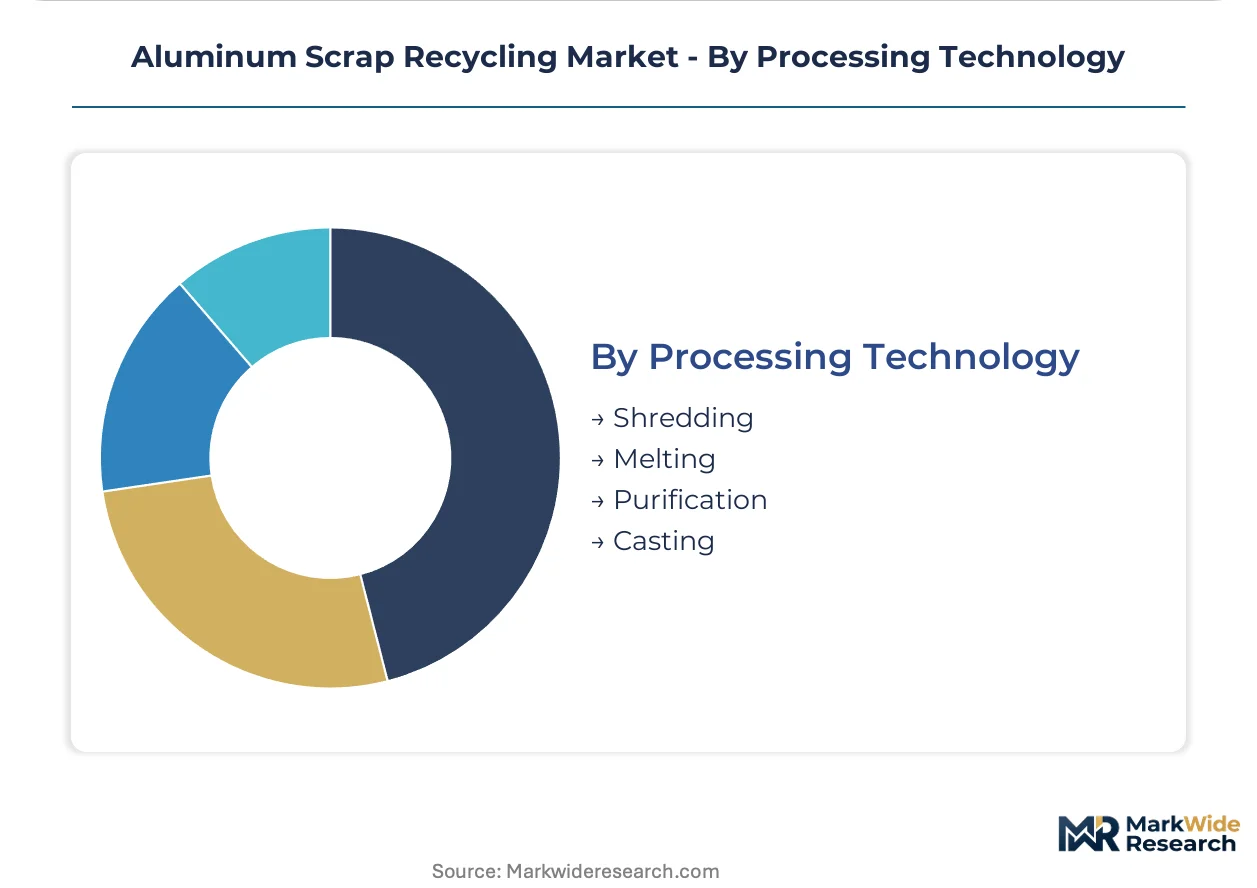
- Shredding:Size reduction liberates aluminum from mixed waste streams and prepares material for sensor-based sorting. German and Austrian facilities deploy X-ray fluorescence integration for real-time alloy identification.
- Melting:Rotary and reverberatory furnaces remelt sorted scrap into molten metal for casting or direct alloy adjustment.
- Purification:Salt-slag treatment and fluxing remove magnesium and silicon loads from contaminated feedstock.
- Casting:Direct chill and continuous casting solidify molten metal into specification ingots or rolling slabs.
Melting capacity represents the established base. Sensor-integrated shredding lines are gaining share fastest as machine vision systems compress quality assurance cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal compliance mandates are redirecting capital flows toward secondary aluminum capacity in jurisdictions with verified low-carbon power. Germany, China, and the United States anchor installed remelting infrastructure, while India and Norway concentrate new project finance attracted by hydroelectric and policy incentives.
Germany
Automotive OEMs in Stuttgart and Munich now require minimum recycled content thresholds in powertrain castings. The EU Green Deal and REACH compliance tighten scrap purity requirements across member states. Novelis and Hydro operate large secondary smelters in the industrial corridor serving these automotive clusters.
China
Industrial buyers redirect procurement toward imported scrap streams as domestic smelting faces emissions intensity caps. The MEE imposes dual carbon goals that cap smelter emissions intensity. Collection hubs in Guangdong and Zhejiang provinces expand seaborne import capacity for North American and European scrap flows.
United States
Beverage packaging OEMs accelerate closed-loop commitments through dedicated can-to-can recycling circuits. The EPA enforces hazardous waste classifications for aluminum-bearing drosses and salt cakes. Novelis anchors large-scale secondary capacity in the Southeast serving carbon-accounted metal premiums.
India
EV casting demand emerges in the Chennai and Pune industrial corridors as automotive component manufacturing scales. The PLI scheme for auto components attracts secondary alloy producers to anchor regional capacity. Scrap collection networks concentrate in Gujarat and Maharashtra serving foundry demand.
Norway
Carbon-accounted metal premiums attract long-dated offtake agreements from European automotive buyers. Norsk Hydro ASA anchors position through captive hydro-powered smelting. Project finance tied to green bond issuance reconfigures capital access for brownfield expansions in this low-carbon zone.
Aluminum Scrap Recycling Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a moderately consolidated structure where scale advantages in closed-loop collection networks offset toll-processing flexibility. The vendor base clusters around three archetypes: integrated aluminum producers with captive recycling assets, independent secondary smelters competing on alloy specification, and merchant traders aggregating heterogeneous scrap streams. Dominant competitive moves include M&A to secure collection network density and capacity expansion in hydro-powered zones to capture carbon-accounted premiums.
Among integrated producers, Novelis Inc., Norsk Hydro ASA, and REAL ALLOY occupy positions that exemplify divergent strategic archetypes. Novelis represents the closed-loop partnership model leveraging automotive OEM relationships. Norsk Hydro ASA anchors the low-carbon smelting tier through Norwegian hydroelectric integration. REAL ALLOY sits within the toll-processing specialist segment shifting price risk to feedstock suppliers.
| Leading Market Players |
|---|
| Novelis Inc. |
| REAL ALLOY |
| Norsk Hydro ASA |
| Sims Metal Management |
| ArcelorMittal S.A. |
| Constellium |
| Matalco Inc. |
| Aurubis AG |
| Alcoa Corporation |
| Others |
Supply Flow & Price Mechanics
Carbon border adjustment exposure determines both tier spreads and supply chain configuration across secondary aluminum markets. EU CBAM documentation requirements for imported primary metal compress margins for carbon-heavy producers while amplifying premiums for hydro-powered scrap-fed supply chains.
Pricing Analysis
Certification level creates the primary spread across specification-grade secondary alloys. Contract-based long-term offtake agreements dominate, with ASI Performance Standard and ISO 14001 tiers commanding premiums over uncertified merchant grades. Price differentiation hinges on carbon-intensity verification and closed-loop collection network access. Pricing pressure stems from natural gas cost spikes in German and Dutch remelting corridors. Merchant traders and toll-processors face acute sensitivity to scrap feedstock volatility, while automotive OEMs with captive sourcing show lower elasticity.
Supply Chain Analysis
Post-industrial scrap flows from Germany, the United States, and China anchor upstream feedstock availability. The supply chain draws from automotive stamping offcuts, building demolition extrusions, and beverage can collection circuits. Single-source vulnerability concentrates in German industrial corridor remelting capacity serving Stuttgart and Munich automotive clusters. Distribution runs through closed-loop partnerships between Novelis, Hydro, and tier-one automotive suppliers, bypassing traditional merchant channels for specification-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secondary aluminum recycling sits at an early-cycle expansion phase as carbon-accounted metal procurement shifts from voluntary preference to contractual mandate across European automotive supply chains.
For Market Incumbents: Harden closed-loop collection network density against emerging sensor-based sorting entrants. Secure toll-processing agreements with automotive OEMs before India's PLI scheme attracts greenfield capacity to Chennai and Pune corridors. Invest in captive hydro-powered smelting positions in Norway and Quebec to capture widening carbon-accounted premiums.
For New Entrants and Emerging Players: India's EV component manufacturing clusters represent the most penetrable entry point for secondary alloy capacity. Sensor-based sorting integration for mixed curbside scrap streams offers technology-led differentiation against incumbent volume players. Target toll-processing contracts that shift scrap price risk to suppliers while capturing volume fees.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors brownfield expansions over greenfield development. Long-term viability rests on securing offtake agreements with carbon-intensity thresholds verified by third-party auditors. Watch for EU CBAM implementation scope expansion as the signal for accelerated capital reallocation toward low-carbon zones.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Captive feedstock access reduces purification costs and locks automotive OEM supply commitments. |
| Green Bond Project Finance | Long-dated offtake agreements attract institutional capital for hydro-powered capacity expansions in Norway. |
| Sensor-Based Sorting Deployment | X-ray fluorescence integration unlocks value from commingled shredder fractions previously sold as downgraded material. |
| ASI Performance Standard Certification | Audited carbon-accounting enables premium pricing from German automotive clusters under EU Green Deal mandates. |
| Geographic Expansion to India | PLI scheme incentives anchor capacity near Chennai and Pune to serve emerging EV casting demand. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs. Secondary aluminum procurement managers at German automotive OEMs, remelting plant engineers in the Netherlands, and toll-processing contract specialists provided operational perspective. Secondary validation drew from EU trade statistics, EPA hazardous waste tracking databases, and ASI certification registries. Bottom-up scrap flow modeling and top-down alloy demand projections were triangulated for consistency.
Calibration against historical capacity utilization and price spread data informed the analytical framework across the analysis window. Segmentation dimensions included material form, collection channel purity, end-use specification, and processing technology intensity. CAGRs were derived from alloy-specific demand elasticities and carbon policy implementation timelines. Forecast inputs incorporated MEE emissions cap stringency and EU CBAM coverage expansion scenarios.
Practitioners should monitor natural gas price trajectories and REACH substance restriction updates for early signals of margin compression or market access barriers. Forecasts reflect assumptions about carbon border adjustment scope and scrap import tariff regimes. Cross-checking against EU ETS carbon price benchmarks and automotive OEM procurement disclosure filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Motor Lamination Material Market
Metals
US Ferrochrome Market
Metals
Crude Steel Market
Metals
Global Copper Market
Metals
Tinplate Market
Metals
Gold Smelting Market
Metals
Europe Aluminium Wire Rod Market
Metals
Global Nickel Alloy Welding Consumables Market
Metals
Steel Wire Market
Metals
Welding Materials Market
Metals
Metal Recycling Market
Metals
Aluminum Ingots Market
Metals
Silver Powder and Flakes Market
Metals
Merchant Bar Quality (MBQ) Steel Market
Metals
India Special Steel Market
Metals
Aluminium Conductors Market