
 Copper Ammonium Carbonate Market | 2026-2036
Copper Ammonium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Copper Ammonium Carbonate Market Outlook
Green chemistry process innovation is reshaping copper ammonium carbonate manufacturing, replacing energy-intensive precipitation methods with controlled crystallization that cuts waste streams. BASF SE leverages its integrated agrochemical platform to secure backward integration into copper salt precursors. Shanghai Mingdou Agrochemical Co. Ltd. anchors Asia-Pacific supply through dedicated fungicide intermediate capacity. Syngenta Group differentiates via proprietary formulation know-how that extends copper bioavailability in field applications.
Copper ammonium carbonate is a coordination compound formed from cupric salt, ammonium carbonate, and water, typically yielding a blue-green crystalline or powdered material with copper content between 50-55% by weight; manufacturers produce it via aqueous reaction followed by filtration, drying, and milling to specified particle sizes for fungicidal, pigment, or analytical reagent use. Powder grades dominate agricultural channels due to ease of blending with compatible pesticides and adjuvants, while crystal forms command premium positioning in laboratory and pharmaceutical procurement where purity thresholds exceed 98%. Solutions represent the fastest-growing configuration as pre-mixed fungicide concentrates reduce farmer handling steps and improve dosing accuracy in precision spraying systems.
EPA pesticide registration requirements under FIFRA govern copper ammonium carbonate sale in United States agricultural markets, mandating efficacy data and ecological risk assessments that extend product development timelines. ECHA REACH obligations in Europe restrict heavy metal impurity profiles and demand full substance dossiers for import authorization. India's CEA and state pollution control boards enforce effluent norms on copper salt manufacturers operating in Gujarat and Maharashtra. Stakeholders must monitor evolving residue limits in food-grade applications and align formulation investments with jurisdiction-specific registration pathways.
Market Dynamics
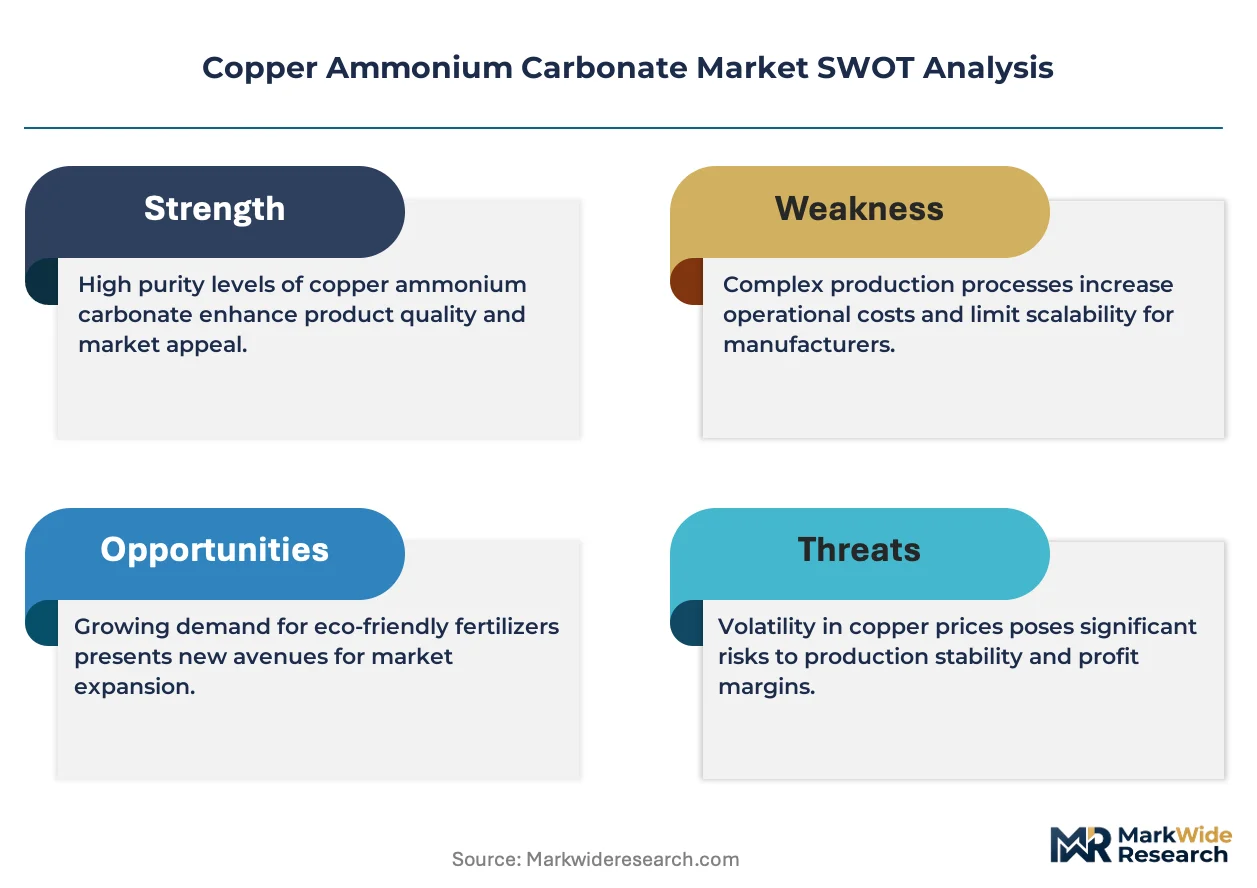
Controlled crystallization technology is compressing manufacturing waste streams while REACH compliance in Europe and EPA FIFRA registration in the United States force dual-track formulation investments that fragment R&D budgets across incompatible regulatory dossiers.
Growth Catalysts
- Specialty crop fungicide demand:Avocado, grape, and citrus growers in Brazil and India are expanding copper-based protective spraying programs to combat downy mildew and bacterial canker outbreaks.
- REACH authorization pathways:ECHA's streamlined substance dossier review for copper compounds with improved ecotoxicity profiles accelerates import clearance for compliant EU suppliers.
- Precision agriculture integration:Pre-mixed solution concentrates reduce farmer handling errors and enable drone-compatible ultra-low-volume application systems.
Market Restraints
- Copper sulfate feedstock volatility:Chilean and Peruvian mining output fluctuations transmit directly to ammonium carbonate precursor costs, squeezing contract manufacturer margins.
- Substitution pressure from synthetic strobilurins:Azoxystrobin and pyraclostrobin formulations capture share in broad-acre cereal protection where copper residues face tightening MRL scrutiny.
- Heavy metal impurity thresholds:ECHA REACH Annex XVII restrictions on cadmium and lead traces in copper salts force additional purification stages that extend batch cycle times.
Strategic Opportunities
- Organic certification tailwinds:EU Organic Regulation 2018/848 and USDA NOP standards list copper ammonium carbonate as approved for organic production, opening premium channel positioning.
- Pharmaceutical-grade crystal demand:Analytical reagent applications in quality control laboratories require 98%+ purity grades that command threefold agricultural powder premiums.
- Brazilian import substitution:Domestic blending facilities in São Paulo state could capture reconstitution value from imported technical grade material.
Industry Challenges
- Ecotoxicology study requirements:EPA FIFRA data call-ins for non-target organism effects demand 18-24 month field study timelines that delay product launch windows.
- Formulation stability expertise:Maintaining copper bioavailability across variable pH water sources requires specialized adjuvant chemistry knowledge concentrated among legacy fungicide developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copper Ammonium Carbonate Market |
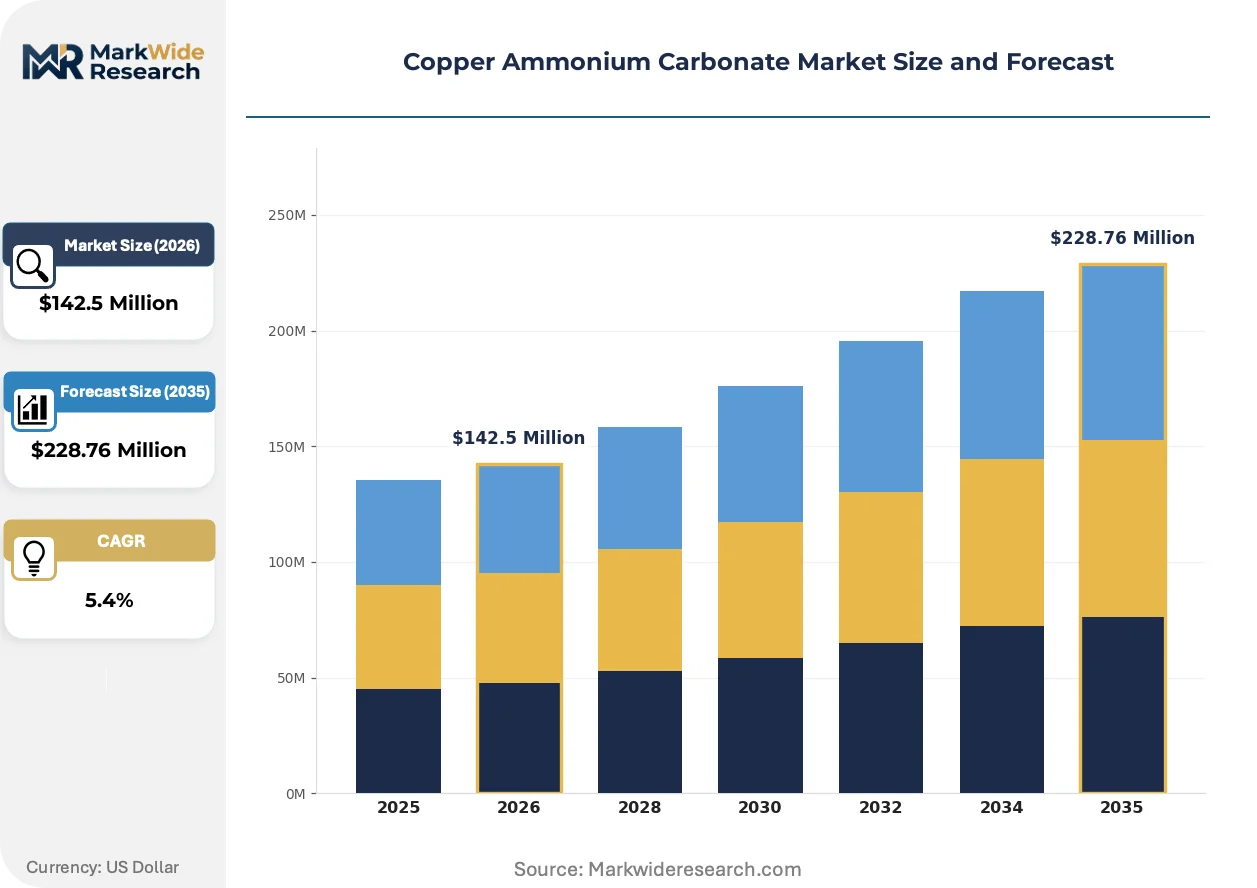
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $228.76 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystals, Powder, Granules, Solutions End User: Agriculture, Textiles, Pharmaceuticals, Chemicals Application: Fertilizers, Dyes, Wood Preservation, Antifungal Agents Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | BASF SE, Shanghai Mingdou Agrochemical Co. Ltd., Bayer AG, Thermo Fisher Scientific Inc., Hindustan Copper Limited, Syngenta Group, Hindalco, Tokyo Chemical Industry Co. Ltd., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper Ammonium Carbonate Market Strategic Shifts
Green chemistry process redesign and precision application hardware are converging to reshape how copper ammonium carbonate reaches field and laboratory end-users, with regulatory data requirements simultaneously elevating technical barriers to market entry.
Continuous flow reactor technology is migrating from pharmaceutical intermediate production into copper salt manufacturing, replacing batch precipitation with temperature-controlled microreactor sequences that cut solvent consumption by half. Agricultural formulators in California's Central Valley are piloting these systems for on-site concentrate production. The shift is compressing capital requirements for mid-scale producers while fragmenting legacy capacity concentrated in Gujarat and Jiangsu provinces.
ECHA REACH substance evaluation under the 2023-2025 Community Rolling Action Plan is tightening aquatic toxicity endpoints for copper compounds used in watershed-adjacent cropping. Manufacturers must now submit extended sediment organism study data that previous dossiers omitted. Vineyard operators in France's Bordeaux region face compressed re-registration timelines that favor suppliers with existing compliant formulations.
Direct procurement from technical grade producers is displacing traditional distributor intermediaries among Brazilian soybean cooperatives and Indian grape export associations. Large farming operations in Mato Grosso and Maharashtra now contract directly with Chinese and German manufacturers for containerized powder shipments. Channel compression is most visible in procurement departments exceeding 10,000 hectare managed acreage where in-house formulation blending justifies volume commitments.
Copper Ammonium Carbonate Market Segmentation
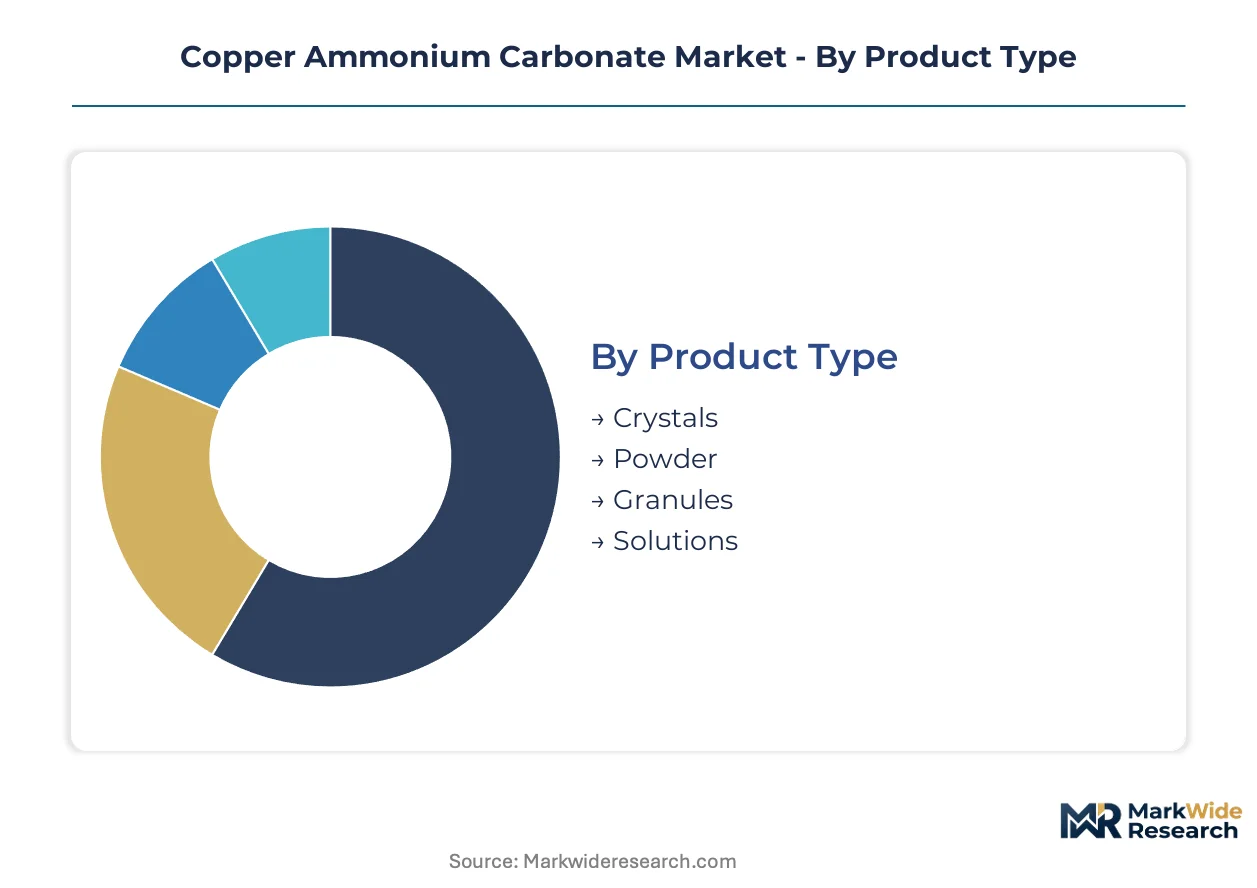
Segmentation in copper ammonium carbonate reveals divergent value chains where agricultural fungicide specifications clash with pharmaceutical purity mandates. Product form and end-use concentration dictate entirely different manufacturing footprints, regulatory pathways, and margin structures.
Product Type:
Mature powder grades dominate agricultural procurement while solution concentrates emerge as precision agriculture enablers.
- Powder:Fine-milled particles between 50-200 microns facilitate blending with compatible pesticides and wetting agents. Brazil's Mato Grosso soybean cooperatives and Maharashtra grape export associations direct procurement toward bulk powder shipments for in-house formulation blending.
- Solutions:Pre-mixed aqueous concentrates with stabilized copper content reduce farmer handling steps and enable drone-compatible ultra-low-volume spraying systems. California Central Valley formulators pilot continuous flow microreactors for on-site concentrate production.
- Crystals:Laboratory-grade crystalline forms exceeding 98% purity command premium positioning in analytical reagent channels.
- Granules:Controlled-release agglomerates serve specialized wood preservation and slow-feed fertilizer applications.
Powder handles the majority of throughput; solutions are gaining share fastest as precision spraying expands.
End User:
Cost tier stratification separates commodity agricultural buyers from premium pharmaceutical and textile purchasers.
- Agriculture:Specialty crop growers in avocado, citrus, and grape sectors drive protective spraying programs against downy mildew and bacterial canker. EU Organic Regulation 2018/848 and USDA NOP approvals position copper ammonium carbonate for premium organic channel access.
- Pharmaceuticals:Quality control laboratories demand 98%+ purity crystal grades for analytical reagent applications, commanding threefold agricultural powder premiums.
- Textiles:Dye mordant applications in synthetic fiber processing require consistent copper ion availability.
- Chemicals:Intermediate buyers supply downstream pigment and catalyst manufacturers with technical grade material.
Agriculture absorbs the dominant volume share; pharmaceuticals deliver the steepest margin expansion trajectory.
Application:
Volume concentration centers on crop protection while antifungal agent specifications fragment across industrial end-uses.
- Fertilizers:Copper micronutrient delivery systems address deficient soils in high-value horticulture.
- Antifungal Agents:Protective fungicide programs in Brazil and India combat endemic downy mildew pressure in tropical cropping systems.
- Dyes:Textile color fixation applications leverage copper-ammonia complex stability.
- Wood Preservation:Marine and ground-contact timber treatments utilize copper leach resistance.
Antifungal applications anchor demand volume; fertilizer integration is expanding most quickly as micronutrient awareness spreads.
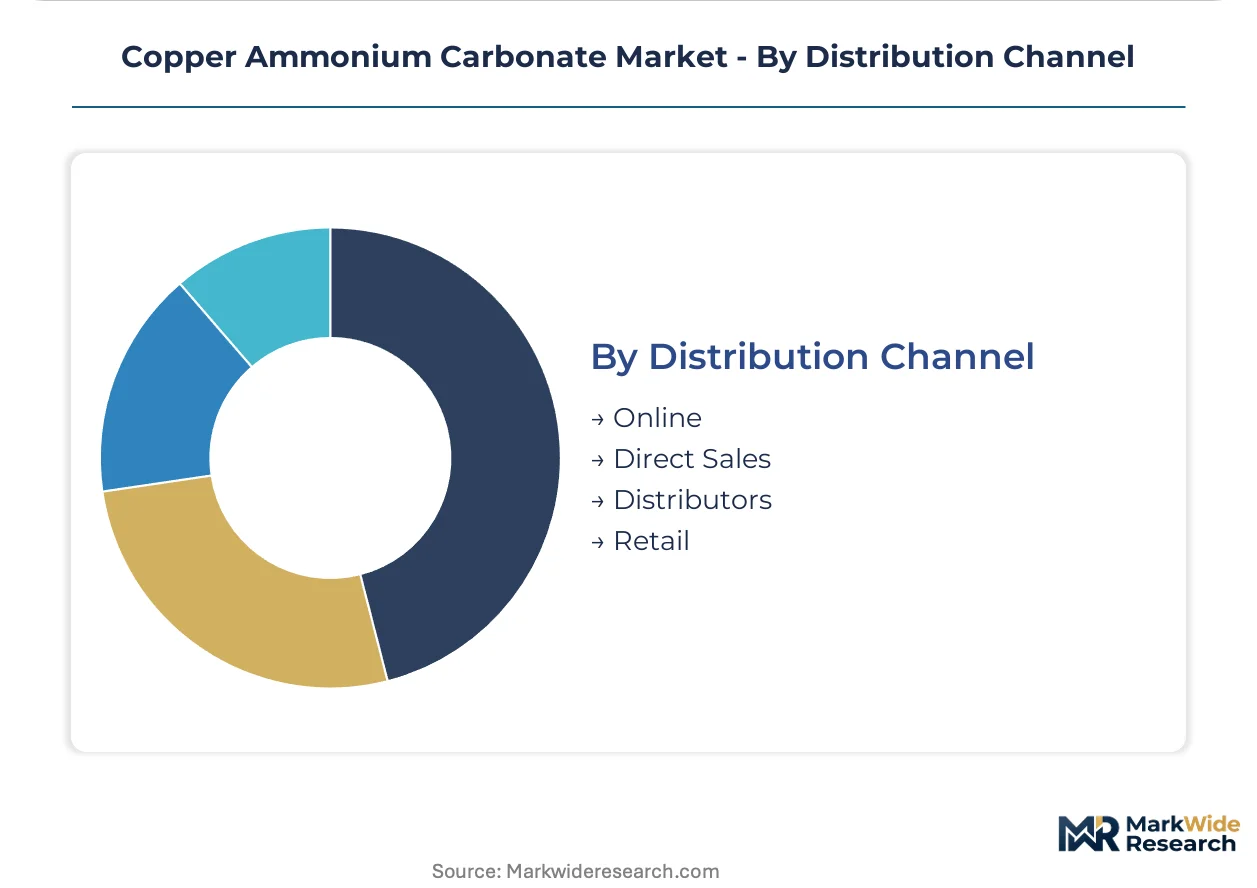
Distribution Channel:
Customer type and procurement scale determine channel selection between direct manufacturer relationships and intermediated supply.
- Direct Sales:Operations exceeding 10,000 managed hectares in Mato Grosso and Maharashtra contract containerized shipments directly from Chinese and German manufacturers.
- Distributors:Legacy agricultural supply houses serve fragmented smallholder networks with formulation blending and credit extension.
- Online:Laboratory chemical marketplaces facilitate pharmaceutical-grade crystal procurement with certificate of analysis transparency.
- Retail:Branded fungicide packages reach hobby vineyard and orchard operators through farm supply cooperatives.
Direct sales capture the largest transaction value; online channels are climbing the fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty crop cooperatives and export-oriented farming operations concentrate import demand across four distinct procurement zones, each shaped by local regulatory frameworks and agrochemical registration pathways.
Brazil
Avocado and citrus growers in São Paulo state drive protective fungicide programs against bacterial canker and downy mildew. ANVISA pesticide registration requirements mandate efficacy trials that extend product development timelines. Mato Grosso soybean cooperatives contract directly with Chinese manufacturers for containerized powder shipments, bypassing traditional distributor networks.
India
Maharashtra grape export associations and Gujarat cotton cooperatives anchor copper-based agrochemical consumption. The Central Electricity Authority and state pollution control boards enforce effluent discharge norms on copper salt manufacturers operating in Surat and Ahmedabad chemical clusters. Direct procurement from German and Chinese technical grade producers is displacing legacy distributor intermediaries among large farming operations.
United States
California Central Valley formulators pilot continuous flow microreactors for on-site concentrate production, reducing solvent consumption. EPA FIFRA registration under the Federal Insecticide, Fungicide, and Rodenticide Act mandates ecological risk assessments and non-target organism studies that compress re-registration timelines. Precision agriculture adoption in Fresno and Kern counties accelerates demand for drone-compatible ultra-low-volume application systems.
Germany
BASF SE leverages integrated agrochemical platforms to secure backward integration into copper salt precursors. ECHA REACH obligations restrict heavy metal impurity profiles and demand full substance dossiers for import authorization. The Ludwigshafen chemical cluster concentrates formulation expertise for EU-compliant copper compound production.
China
Shanghai Mingdou Agrochemical Co. Ltd. anchors Asia-Pacific supply through dedicated fungicide intermediate capacity in Jiangsu province. The Ministry of Ecology and Environment enforces dual carbon goals that pressure energy-intensive precipitation methods toward controlled crystallization alternatives. Yangtze River Delta manufacturers export technical grade material to Brazilian and Indian blending facilities.
Copper Ammonium Carbonate Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented supply tiers. Integrated agrochemical conglomerates with backward integration into copper salt precursors occupy positions distinct from regional formulators and laboratory chemical distributors. Three archetypes dominate: diversified chemical majors with captive raw material access, Asia-Pacific technical grade specialists serving export markets, and precision formulation developers with proprietary adjuvant chemistry. Competitive moves concentrate on regulatory dossier alignment across jurisdictions and green chemistry process licensing.
Among diversified chemical majors, BASF SE and Bayer AG exemplify integrated platform strategies that span precursor production through formulated product distribution. Shanghai Mingdou Agrochemical Co. Ltd. occupies a position within the Asia-Pacific technical grade export tier, supplying containerized shipments to Brazilian and Indian cooperatives. Syngenta Group represents the precision formulation archetype, with proprietary know-how extending copper bioavailability in field applications. These three companies illustrate how competitive positioning fragments across upstream control, regional supply scale, and application-specific technology differentiation.
| Leading Market Players |
|---|
| BASF SE |
| Shanghai Mingdou Agrochemical Co. Ltd. |
| Bayer AG |
| Thermo Fisher Scientific Inc. |
| Hindustan Copper Limited |
| Syngenta Group |
| Hindalco |
| Tokyo Chemical Industry Co. Ltd. |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Underutilized precipitation capacity in Gujarat and Jiangsu provinces compresses supplier pricing power while accelerating migration toward continuous crystallization investments that reset cost baselines for compliant export grades.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange copper quotations dominate technical grade procurement, with agricultural powder shipments carrying 15-20% premiums over base metal movements due to purification and milling costs. Price differentiation separates pharmaceutical crystal grades commanding threefold agricultural premiums from commodity fungicide powders where volume scale drives negotiation leverage. Cost compression in standard agricultural tiers intensifies as Brazilian cooperatives consolidate direct procurement volumes. Smallholder vineyard operators exhibit highest price sensitivity, while pharmaceutical laboratories purchasing certified analytical reagents show minimal elasticity.
Supply Chain Analysis
Tariff exposure between China and Brazil dominates supply chain risk calculations for Asia-Pacific technical grade exporters serving Latin American agricultural cooperatives. Manufacturing concentrates in Jiangsu province, Gujarat chemical clusters, and Ludwigshafen integrated sites, with each hub feeding distinct regulatory compliance tiers. Feedstock draws from Chilean copper concentrate, synthetic ammonia from natural gas reforming, and carbonate from soda ash derivatives. Single-source vulnerability permeates copper sulfate precursor supply where Peruvian mining disruptions transmit within one quarter to formulated product costs. Distribution runs through containerized bulk shipments for large cooperatives and distributor networks for fragmented smallholder access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green chemistry process disruption and REACH authorization streamlining create accelerated value capture windows for positioned participants across the copper ammonium carbonate value chain.
For Market Incumbents: Insulate formulation margins by securing backward integration into copper salt precursors through offtake agreements with Chilean concentrate suppliers or captive precipitation capacity in low-cost jurisdictions. Accelerate REACH-compliant dossier investments ahead of ECHA's 2023-2025 Community Rolling Action Plan evaluation waves to compress competitor re-registration timelines. Synthetic strobilurin substitution pressure in broad-acre cereals demands defensive positioning in specialty crop segments where organic certification protects price realization. For New Entrants and Emerging Players: Build out precision agriculture solution capabilities targeting California Central Valley drone-compatible concentrate demand where established players lack localized microreactor deployment. Brazilian domestic blending facilities in São Paulo state represent the most penetrable white-space opportunity, capturing reconstitution value from imported technical grade material. Direct sales contracts with Mato Grosso cooperatives exceeding 10,000 hectares offer the cleanest go-to-market path bypassing legacy distributor intermediaries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision formulation developers with proprietary adjuvant chemistry extending copper bioavailability across variable pH water sources. Long-term viability over the projection horizon favors acquisition targets combining green manufacturing process licensing with established regulatory dossiers across multiple jurisdictions. Watch for ECHA substance evaluation outcomes on aquatic toxicity endpoints as the critical inflection signal distinguishing compliant from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive copper sulfate supply from Chilean concentrate offtakes insulates margin against LME volatility. |
| Green Manufacturing Transition | Continuous flow microreactor deployment cuts solvent consumption and aligns with EU Green Deal compliance pathways. |
| Regulatory Dossier Investment | REACH substance dossier completion ahead of Community Rolling Action Plan evaluation accelerates EU market access. |
| Direct Sales Channel Buildout | Containerized bulk contracts with Brazilian and Indian cooperatives displace distributor intermediaries above 10,000 hectare scale. |
| Precision Formulation Development | Proprietary adjuvant chemistry extending copper bioavailability commands premium positioning in drone-compatible applications. |
Study Parameters
Cross-validation between primary interviews with agrochemical procurement managers, plant operations directors, and regulatory affairs specialists and secondary sources including customs trade data, SEC filings of diversified chemical majors, and ECHA substance dossier repositories anchors the qualitative findings. Bottom-up volume estimates from individual manufacturing facility capacities and top-down demand calibration from crop protection expenditure surveys were reconciled to establish market sizing boundaries.
Calibration against historical price movements and capacity utilization rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product form, end-use concentration, purity grade tier, and regional regulatory cluster. CAGRs were derived from regression analysis of correlated agricultural input expenditure trends and copper compound substitution elasticities. Forecast inputs incorporated specialty crop planting intentions in Brazil and India alongside precision agriculture adoption curves in California.
Stress conditions across copper concentrate supply disruptions, REACH authorization delays, and synthetic strobilurin price competition were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline stability and feedstock cost transmission mechanisms. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Caryophyllene Market
Specialty Chemicals
Betulinic Acid Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Glucono Delta Lactone Market
Specialty Chemicals
Bismaleimide Market
Specialty Chemicals
Cyclomethicone Market
Specialty Chemicals
Europe Sugarcane Wax Market
Specialty Chemicals
Global Photoacid Generators Market
Specialty Chemicals
Pegylated Lipids Market
Specialty Chemicals
Biocides Market
Specialty Chemicals
Biobased Propylene Glycol Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Salt Hydrate Market
Specialty Chemicals
Europe Aerosol Cans Market