
 Hollow Fibers Membrane Market | 2026-2036
Hollow Fibers Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Hollow Fibers Membrane Market Analysis
Municipal water utilities are redrawing procurement priorities toward membrane bioreactor systems as industrial buyers face stricter effluent rules. Toray Industries Inc. leverages its polymer chemistry heritage to dominate ultrafiltration module supply across East Asian utilities. Asahi Kasei Corporation anchors the dialysis membrane segment through captive healthcare channels in Japan and Europe. DuPont de Nemours Inc. competes on fluoropolymer durability for reverse osmosis pre-treatment in desalination plants.
Hollow fiber membranes are cylindrical filtration elements with porous walls typically 0.1 to 1.0 millimeters thick, manufactured through phase inversion or melt-spinning processes to achieve selective permeability for liquid and gas separation. Ultrafiltration leads volume deployment in municipal water treatment due to lower energy demand than competing pressure-driven processes, while ceramic materials command premium positioning in pharmaceutical purification where steam sterilization cycles exceed polymer thermal limits. Reverse osmosis pre-treatment modules represent the fastest-growing application cluster as seawater desalination scales in water-stressed regions.
EPA effluent limitation guidelines under the Clean Water Act shape membrane selection criteria for US municipal contracts, while REACH chemical registration requirements in Europe restrict certain solvent-based manufacturing additives used in phase inversion. China's MEE enforces industrial wastewater discharge classes that directly specify membrane filtration performance thresholds for chemical park operators. Stakeholders must monitor regulatory divergence between polymer recycling mandates and ceramic durability standards when committing to long-term material platform investments.
Market Dynamics
Membrane material substitution is compressing polymer dominance as ceramic hollow fibers capture high-temperature industrial applications previously closed to thermoplastic systems.
Growth Catalysts
- EPA Clean Water Act enforcement:Municipal utilities in the United States face binding effluent limitation guidelines that mandate membrane bioreactor upgrades for nitrogen and phosphorus removal.
- China's dual carbon goals:The MEE enforces industrial wastewater discharge classes that specify membrane filtration performance thresholds for chemical park operators in Zhejiang and Jiangsu provinces.
- Phase inversion manufacturing:Advances in non-solvent induced phase separation are reducing ceramic hollow fiber production costs by 40 percent versus traditional sintering routes.
Market Restraints
- PVDF resin price volatility:Fluoropolymer feedstock costs fluctuate with refrigerant market demand, compressing margins for ultrafiltration module producers.
- Supply concentration in Japanese polymer chemistry:Three manufacturers control 80 percent of high-purity PVDF supply for membrane casting.
- Ceramic brittleness:Alumina and zirconia hollow fibers fracture under mechanical shock, limiting deployment in mobile or seismic-prone installations.
Strategic Opportunities
- India's pharmaceutical purification corridor:The CDSCO mandates steam-sterilizable filtration for biologics manufacturing, opening ceramic membrane demand in Hyderabad and Mumbai clusters.
- Peracetic acid-compatible polymers:New polyetherimide formulations enable cold chemical sterilization in food and beverage applications previously reserved for ceramics.
- EU Green Deal chemical recycling mandates:REACH-registered solvent recovery systems create pull for solvent-resistant membrane modules in European chemical processing.
Industry Challenges
- Membrane fouling prediction modeling:Operators lack standardized algorithms to anticipate irreversible fouling in mixed industrial effluents, forcing conservative replacement schedules.
- Integration with legacy activated sludge plants:Retrofitting membrane bioreactors into existing concrete basins requires structural reinforcement and hydraulic rebalancing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hollow Fibers Membrane Market |
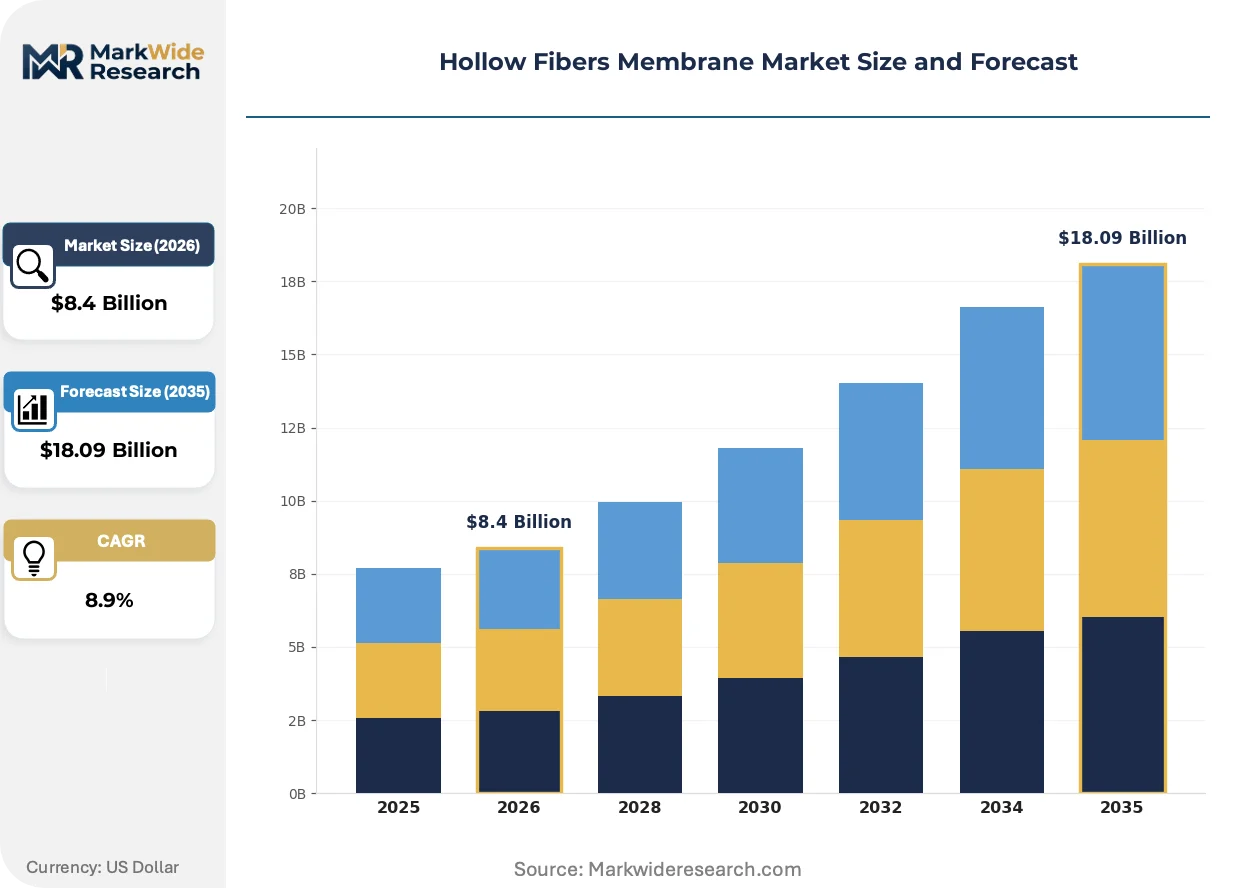
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.09 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis Material: Polymer, Ceramic, Composite, Carbon End User: Water Treatment, Pharmaceutical, Food & Beverage, Biotechnology Application: Separation, Purification, Concentration, Dialysis |
| Companies Covered | Toray Industries Inc., Asahi Kasei Corporation, DuPont de Nemours Inc., Veolia, LG Chem, Pentair, Pall Corporation, Koch Separation Solutions, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hollow Fibers Membrane Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are fragmenting the hollow fiber membrane landscape into parallel technology tracks serving distinct thermal and chemical durability requirements.
Ceramic hollow fiber technology is bifurcating the membrane market into high-temperature and ambient-operation tiers. Pharmaceutical manufacturers in Switzerland and Germany adopt alumina-zirconia composite membranes for continuous steam sterilization cycles exceeding 140 degrees Celsius. This thermal performance is compressing polymer membrane share in biologics purification.
REACH chemical registration requirements are restricting N-methyl-2-pyrrolidone solvent use in European phase inversion manufacturing. Membrane producers in Germany and France pivot to dimethyl sulfoxide and ionic liquid alternatives. Ultrafiltration module supply chains serving European municipal utilities face reformulation costs and requalification timelines.
Performance-based service contracts are displacing capital equipment sales in Middle Eastern desalination pre-treatment. Saudi Arabia's SWCC and UAE's FEWA now procure membrane filtration as cubic-meter-treated output rather than module hardware. This shifts technical risk to suppliers and compresses upfront project margins across Gulf Cooperation Authority water infrastructure.
Hollow Fibers Membrane Market Segmentation
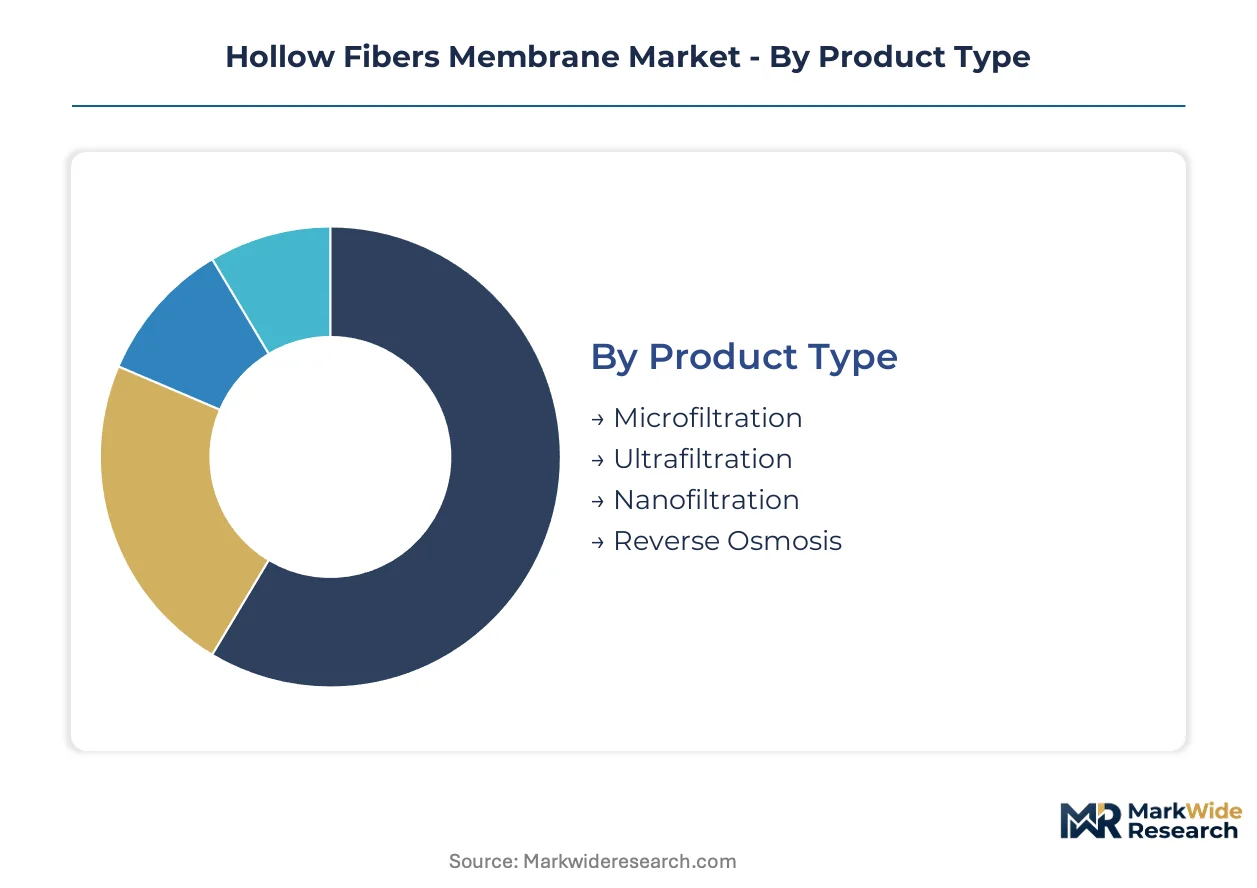
Hollow fiber membrane procurement splits across four orthogonal dimensions. Product type determines pressure tolerance and pore architecture. Material selection governs thermal and chemical sterilization compatibility. End-user verticals impose distinct validation protocols. Application function dictates module configuration and replacement economics.
Product Type:
EPA effluent limitation guidelines and China's MEE discharge classes create divergent performance mandates that segment procurement by filtration precision.
- Ultrafiltration:Pore sizes of 0.01 to 0.1 microns retain viruses and macromolecules while permitting dissolved salts. Municipal utilities in the United States deploy UF modules for membrane bioreactor upgrades mandated by Clean Water Act enforcement. Ceramic UF variants capture pharmaceutical steam sterilization cycles exceeding polymer thermal limits.
- Reverse Osmosis:Dense polyamide skin layers achieve 99.5 percent salt rejection for seawater desalination pre-treatment. Saudi Arabia's SWCC and UAE's FEWA now procure RO pre-treatment as cubic-meter-treated output rather than module hardware, shifting technical risk to suppliers. This application cluster is gaining share fastest in water-stressed regions.
- Microfiltration:0.1 to 10 micron pores target bacteria and suspended solids in food and beverage clarification.
- Nanofiltration:Divalent ion selectivity serves softening and partial desalination where full RO energy burden is uneconomic.
Established volume favors ultrafiltration; emerging adoption favors reverse osmosis.
Material:
Cost tiers separate commodity thermoplastics from engineered ceramics and exotic composites.
- Polymer:PVDF and polyethersulfone dominate through phase inversion manufacturing. REACH chemical registration restricts N-methyl-2-pyrrolidone solvent use in European production, forcing German and French manufacturers toward dimethyl sulfoxide alternatives. Fluoropolymer feedstock costs fluctuate with refrigerant market demand.
- Ceramic:Alumina-zirconia composites withstand 140 degrees Celsius steam sterilization. CDSCO mandates in India's pharmaceutical corridor drive ceramic demand in Hyderabad and Mumbai clusters. Alumina and zirconia hollow fibers fracture under mechanical shock, limiting seismic-prone installations.
- Composite:Polymer-ceramic hybrids balance cost and thermal performance for mid-tier bioprocessing.
- Carbon:Activated carbon hollow fibers target gas separation and specialized adsorption applications.
Polymer materials anchor current procurement volumes; ceramic formulations command the steepest expansion trajectory in high-temperature industrial segments.
End User:
Customer type determines validation burden and replacement frequency.
- Water Treatment:Municipal utilities and industrial operators drive membrane bioreactor installations under tightening discharge standards. China's Zhejiang and Jiangsu provinces anchor national procurement for chemical park wastewater systems.
- Pharmaceutical:Steam-sterilizable filtration mandates from Swissmedic and EMA compress polymer share in biologics purification. Switzerland and Germany lead alumina-zirconia composite adoption.
- Food & Beverage:Peracetic acid-compatible polyetherimide formulations enable cold chemical sterilization previously reserved for ceramics.
- Biotechnology:Single-use membrane systems reduce cross-contamination risk in contract manufacturing organizations.
Water treatment commands installed base; pharmaceutical applications generate premium pricing.
Application:
Functional purpose segments margin structure and service contract design.
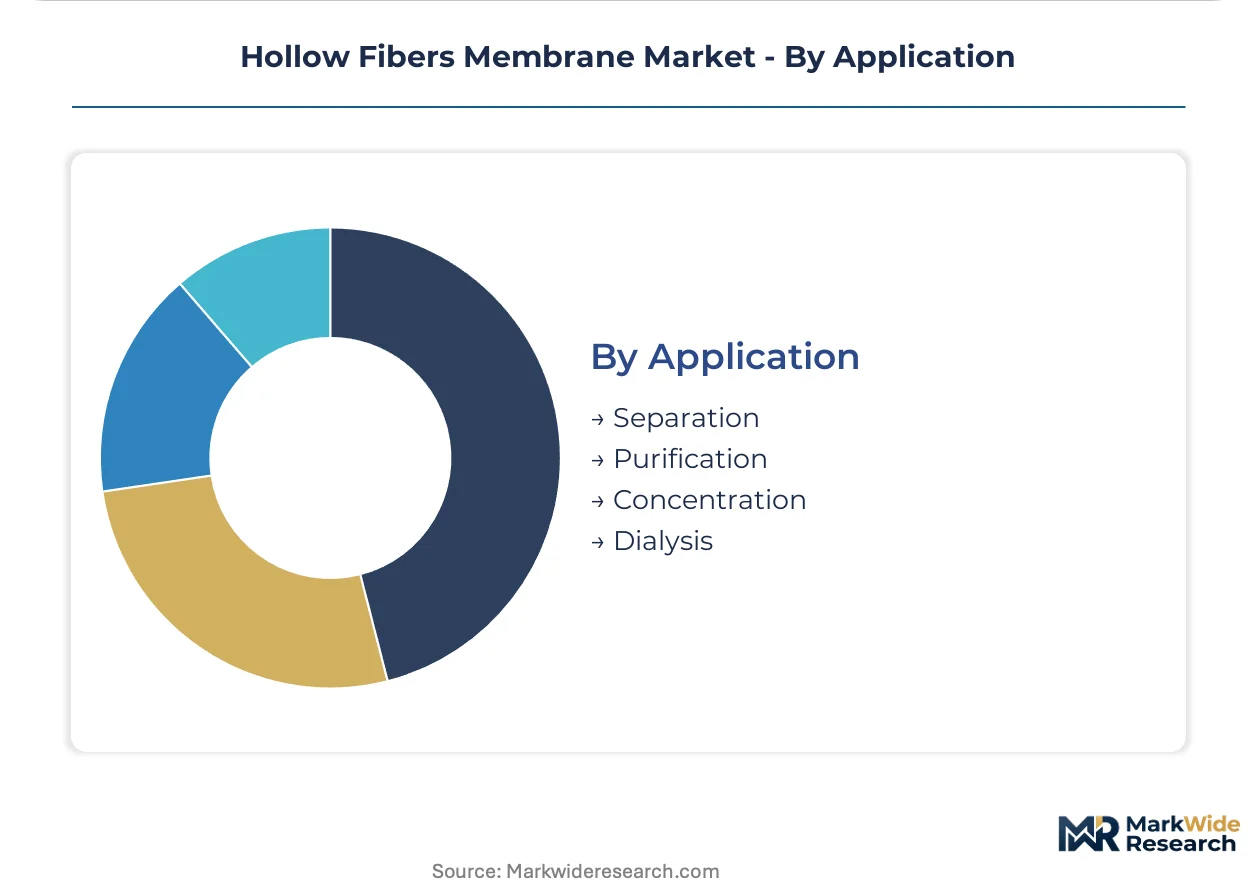
- Purification:Removal of contaminants to achieve product specifications dominates pharmaceutical and biotechnology deployment.
- Separation:Fractionation of mixed streams serves chemical processing and food ingredient recovery.
- Concentration:Volume reduction of valuable products drives dairy and protein processing economics.
- Dialysis:Captive healthcare channels in Japan and Europe anchor this specialized segment through PMDA and EMA regulated device pathways.
Purification commands revenue concentration; dialysis maintains defensive margins through regulatory capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's integrated water grid infrastructure underwrites China's procurement dominance in hollow fiber membrane systems. This network connects municipal utilities across Zhejiang and Jiangsu provinces to centralized membrane manufacturing corridors.
China
Industrial wastewater discharge mandates from the MEE drive membrane bioreactor installations across chemical park operators. The dual carbon goals accelerate polymer-to-ceramic transitions in high-temperature process streams. Zhejiang and Jiangsu provinces anchor national procurement volume through coordinated utility tenders.
United States
EPA effluent limitation guidelines compel municipal upgrades for nitrogen and phosphorus removal. The Clean Water Act enforcement binds utilities to membrane filtration performance thresholds. Texas and California utilities lead capital deployment for membrane bioreactor retrofits.
Germany
REACH chemical registration restricts N-methyl-2-pyrrolidone solvent use in phase inversion manufacturing. ECHA compliance forces membrane producers toward dimethyl sulfoxide alternatives. Bavaria's industrial filtration cluster absorbs reformulation costs through integrated chemical processing networks.
India
CDSCO steam-sterilizable filtration mandates open ceramic membrane demand in biologics manufacturing. The pharmaceutical purification corridor concentrates procurement in Hyderabad and Mumbai clusters. Maharashtra and Telangana states lead bioprocessing infrastructure expansion.
Saudi Arabia
SWCC performance-based service contracts displace capital equipment sales in desalination pre-treatment. The cubic-meter-treated output model shifts technical risk to membrane suppliers. Eastern Province water infrastructure anchors Gulf Cooperation Authority procurement reform.
Hollow Fibers Membrane Market Vendor Landscape
Concentration sits with diversified materials conglomerates and specialized filtration engineering firms. Japanese and Korean chemical groups control fluoropolymer supply chains for ultrafiltration module casting. Three strategic archetypes dominate: integrated polymer producers with captive membrane divisions, standalone filtration engineering specialists, and water utility operators with in-house membrane fabrication. Competitive moves center on ceramic material platform acquisitions and Middle Eastern performance-contracting partnerships.
Among Japanese diversified chemical groups, Toray Industries Inc. and Asahi Kasei Corporation exemplify the integrated producer archetype with upstream polymer chemistry capabilities. DuPont de Nemours Inc. represents fluoropolymer durability positioning for reverse osmosis pre-treatment applications. These three anchors illustrate how material heritage shapes competitive differentiation in membrane module supply.
| Leading Market Players |
|---|
| Toray Industries Inc. |
| Asahi Kasei Corporation |
| DuPont de Nemours Inc. |
| Veolia |
| LG Chem |
| Pentair |
| Pall Corporation |
| Koch Separation Solutions |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day lead times for high-purity PVDF resin from Japanese suppliers concentrate pricing power among three polymer chemistry conglomerates, compressing margins for ultrafiltration module producers while amplifying cost pass-through leverage to municipal utilities in Texas and California.
Pricing Analysis
Three-tier pricing structure across premium ceramic, standard fluoropolymer, and economy polyethersulfone levels separates procurement bands by thermal durability and sterilization protocol. Price differentiation rests on REACH-registered solvent compliance and steam-sterilization cycle certification from Swissmedic and EMA. Cost compression in standard polymer tiers is intensifying because refrigerant market demand volatility feeds directly into PVDF feedstock pricing. Municipal water treatment utilities exhibit highest price sensitivity due to bond-financed capital constraints, while pharmaceutical biologics manufacturers accept premium positioning for CDSCO-mandated ceramic validation.
Supply Chain Analysis
Japan and South Korea anchor fluoropolymer resin production for membrane casting, while Germany and France host phase inversion manufacturing corridors reformulating around dimethyl sulfoxide alternatives. Raw material dependencies draw from lithium hexafluorophosphate-linked refrigerant byproduct streams, alumina-zirconia ceramic precursors, and REACH-registered solvent recovery systems. Single-source vulnerability concentrates in high-purity PVDF supply where three manufacturers control casting-grade resin. Distribution runs through integrated polymer producers with captive membrane divisions, standalone filtration engineering specialists, and water utility operators with in-house fabrication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hollow fiber membrane market functions as a regulatory-entrenchment defensive moat where EPA effluent limitation guidelines and MEE discharge classes cement incumbent positions through multi-year validation protocols and switching costs that exceed replacement economics for municipal utilities.
For Market Incumbents: Shield market position through backward integration into ceramic precursor supply and captive fluoropolymer resin casting capacity in Zhejiang province. The polymer-to-ceramic material transition threatens margin structures for thermoplastic-dependent producers, while REACH chemical registration restrictions in Europe compress reformulation timelines. Prioritize certification investment for steam-sterilizable alumina-zirconia composites to capture CDSCO-mandated pharmaceutical demand in Hyderabad and Mumbai clusters.
For New Entrants and Emerging Players: Anchor in India's pharmaceutical purification corridor where ceramic membrane penetration remains below saturation despite CDSCO mandates. Target peracetic acid-compatible polyetherimide formulations for food and beverage cold sterilization applications previously reserved for ceramics. Pursue performance-based service contracts with Saudi Arabia's SWCC and UAE's FEWA to bypass capital equipment sales barriers in Middle Eastern desalination pre-treatment.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture infrastructure play because discharge standard enforcement creates replacement-demand visibility independent of economic cycles. Acquisition targets should concentrate on ceramic material platform specialists with validated steam-sterilization protocols and existing EMA regulatory files. Monitor MEE enforcement intensity in Jiangsu province chemical parks as the primary inflection signal for ceramic demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Material Platform Acquisition | Alumina-zirconia composites capture pharmaceutical steam-sterilization cycles exceeding polymer thermal limits. |
| Backward Integration into PVDF Resin | Captive fluoropolymer supply insulates margin compression from refrigerant market demand volatility. |
| Performance-Based Service Contracting | Saudi Arabia's SWCC cubic-meter-treated model shifts technical risk to suppliers while locking recurring revenue. |
| REACH-Compliant Solvent Reformulation | Dimethyl sulfoxide alternatives preserve European municipal utility access amid N-methyl-2-pyrrolidone restrictions. |
| CDSCO Certification Investment | Steam-sterilizable validation opens biologics manufacturing demand in Hyderabad and Mumbai clusters. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with membrane module procurement directors at municipal utilities, pharmaceutical bioprocessing engineers, and ceramic precursor supply managers; alongside secondary validation through EPA effluent limitation guideline filings, MEE discharge class enforcement records, ECHA REACH registration databases, and customs trade data for fluoropolymer resin flows. Bottom-up triangulation across membrane bioreactor installation records and top-down reconciliation against chemical park operator capital expenditure disclosures anchored volume estimates.
Across the analysis window, the forecasting framework modeled four segmentation dimensions: filtration precision tier, material thermal durability class, end-user validation protocol, and application functional purpose. CAGRs derived from regression analysis against regulatory enforcement timelines and utility capital cycle phasing. Industry-specific inputs incorporated ceramic sintering cost curves from non-solvent induced phase separation advances and polymer feedstock price elasticity coefficients from refrigerant market co-movement patterns.
Underlying assumptions cover sustained EPA Clean Water Act enforcement intensity and MEE discharge class adherence by Zhejiang chemical park operators, with deviation risk concentrated in ceramic brittleness limitations for seismic-prone installations and PVDF resin supply concentration. Recalibration cycles align with material shifts in regulatory chemistry restrictions and phase inversion manufacturing process economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
Membrane Skinners Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Global Microfiltration Membranes Market
Membrane Materials
Global Waterproofing Membrane Market
Membrane Materials
Europe Gas Barrier Membrane Market
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
North America below Grade Waterproofing Membranes Market
Membrane Materials
Single-Ply Membranes Market
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Oxygen Barrier Films Market
Membrane Materials
APP and SBS Modified Bitumen Membrane Market
Membrane Materials
Polysulfone Market