
 Global Cerium Oxide Nanoparticles Market | 2026-2036
Global Cerium Oxide Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cerium Oxide Nanoparticles Market Foresight
Multi-source procurement from specialty chemical distributors is hardening across the cerium oxide nanoparticles value chain. American Elements leverages its integrated rare earth supply position in the United States to sustain long-term contracts with semiconductor polishers. NYACOL Nano Technologies competes on dispersion stability and batch consistency, while Cerion anchors its position through toll manufacturing partnerships that extend regional reach without direct capital deployment.
Cerium oxide nanoparticles consist of CeO2 crystallites typically ranging from 1 to 100 nanometers in diameter, synthesized via wet chemical routes or sol-gel processes to achieve high oxygen storage capacity and surface reactivity for catalytic and polishing functions. The nanopowder category dominates current volume shipments due to its flexibility in downstream formulation, though nanoparticles dispersion formats command premium positioning among electronics producers seeking ready-to-use slurries for chemical mechanical planarization. Within end user industries, environmental firms represent the fastest-growing demand pool as flue gas treatment and wastewater catalysis applications expand.
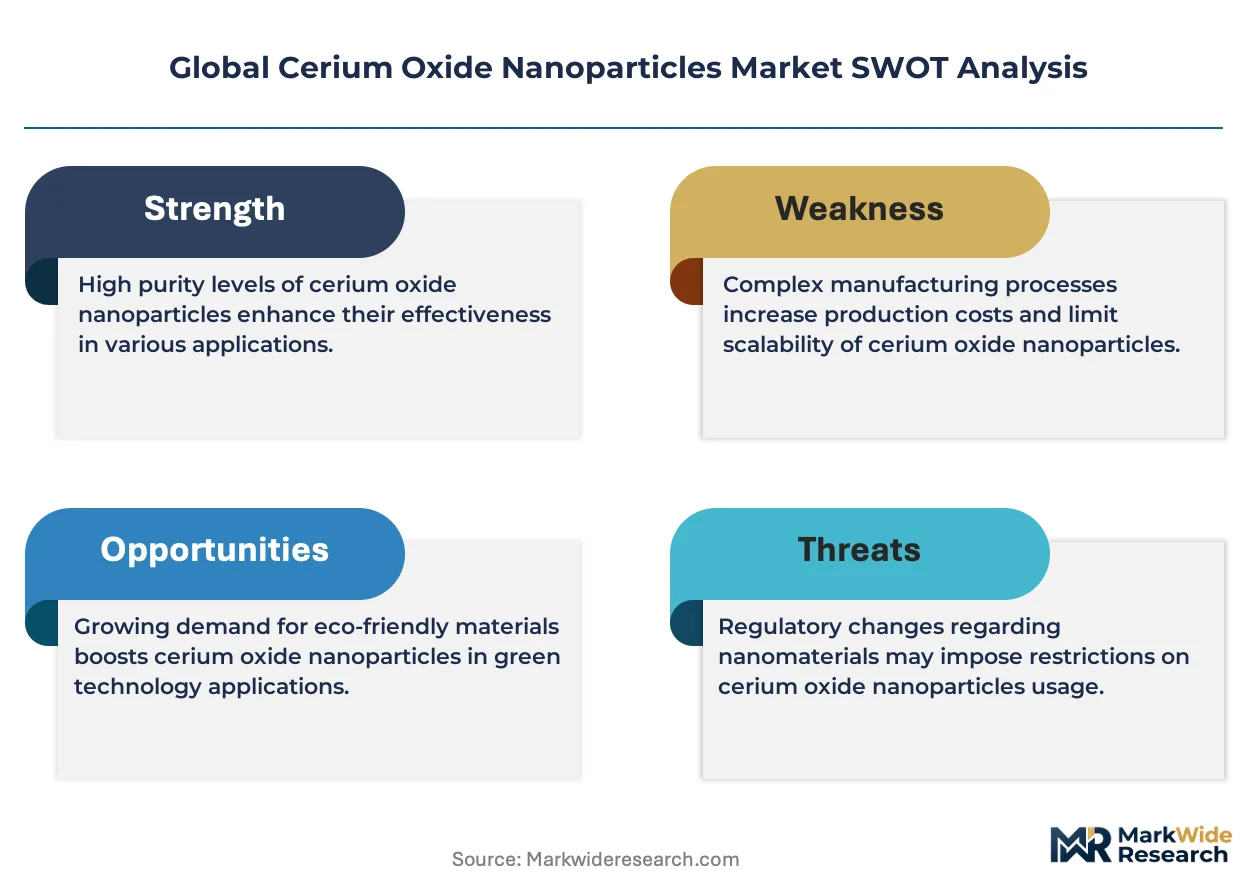
EPA oversight of rare earth processing emissions and REACH registration requirements for nanomaterial imports into Europe are elevating compliance costs and favoring producers with documented toxicity profiles and lifecycle assessments. China's MIIT continues tightening GB standards for nanoparticle manufacturing effluent, reshaping export availability from Shandong-based producers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate supply disruptions and qualification barriers before committing to long-term offtake agreements.
Market Dynamics
Semiconductor manufacturers are consolidating their slurry supply bases around nanoparticle producers with verified environmental compliance documentation, as chemical mechanical planarization operations now account for the dominant share of cerium oxide nanoparticle consumption across fabrication facilities.
Growth Catalysts
- EPA emissions standards:Tightening effluent controls on rare earth processing operations in the United States are accelerating qualification of low-emission nanoparticle suppliers by chemical distributors serving semiconductor polishers.
- Flue gas treatment:Environmental engineering firms in Germany and Japan are expanding catalytic oxidation capacity using cerium oxide nanoparticles for mercury and NOx capture at coal-fired and industrial combustion facilities.
- Jiangsu industrial cluster:Concentrated rare earth refining and nanoparticle synthesis operations in this Chinese province are achieving economies of scale that reduce unit costs for export-grade nanopowder shipments.
Market Restraints
- Rare earth concentrate volatility:Bastnasite and monazite ore price swings from Chinese and Australian mining operations transmit directly to cerium oxide nanoparticle feedstock costs, compressing margin predictability for downstream formulators.
- Shandong supply concentration:Export availability hinges on a narrow corridor of Shandong-based producers subject to MIIT effluent enforcement actions that disrupt shipment timing without advance notice.
- Colloidal silica substitution:Alternative abrasive chemistries for shallow-layer CMP operations are capturing select semiconductor process steps where surface defect tolerance permits lower-cost polishing media.
Strategic Opportunities
- India semiconductor fabrication:PLI scheme incentives for domestic chip manufacturing are creating qualification demand for nanoparticle slurry suppliers capable of meeting CDSCO import documentation and BIS standards alignment.
- Wastewater catalysis:Advanced oxidation process deployments for pharmaceutical and textile effluent treatment represent an emerging volume channel with less price sensitivity than electronics polishing applications.
- REACH registration completion:European nanoparticle importers with full ECHA dossier submissions are securing preferred supplier status as downstream formulators face downstream user obligations under the EU nanomaterial framework.
Industry Challenges
- Toxicological dossier gaps:Producers lacking OECD-compliant inhalation and dermal exposure studies face extended registration timelines in jurisdictions with evolving nanomaterial safety protocols.
- Dispersion stability engineering:Formulation chemists with rare earth surface chemistry expertise remain scarce relative to demand for shelf-stable nanoparticle slurries with six-month minimum viability windows.
- Capital intensity of aqueous synthesis:Continuous flow reactor installations for consistent crystallite size distribution require seven-figure equipment commitments that strain mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cerium Oxide Nanoparticles Market |
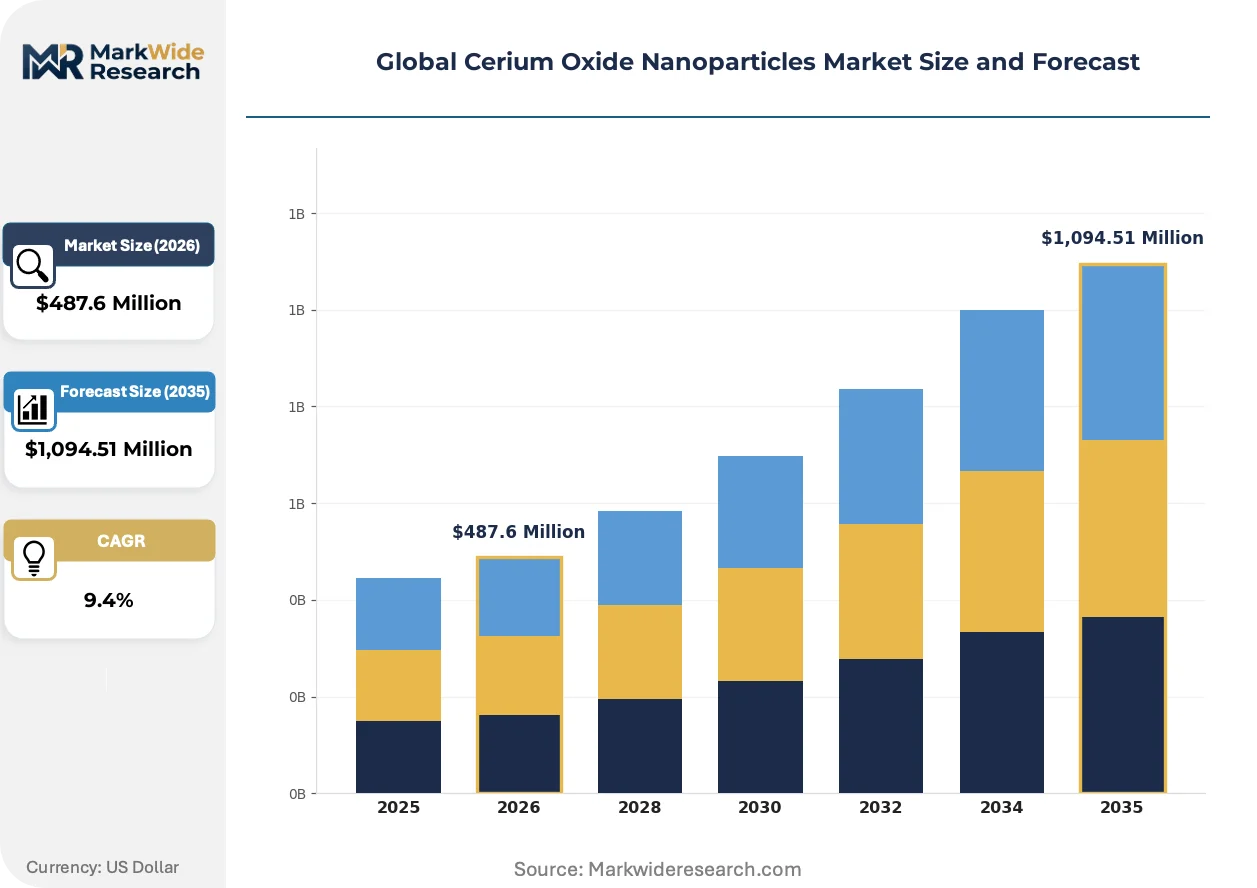
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,094.51 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanopowder, Nanoparticles Dispersion, Nano Suspension, Nanocubes, Nanorods Application: Catalysts, UV Absorbers, Fuel Additives, Polishing Agents, Biomedical Agents End User Industry: Ceramics Manufacturers, Chemical Suppliers, Electronics Producers, Textile Finishers, Environmental Firms Deployment Method: Wet Chemical Route, Sol-Gel Process, Hydrothermal Method, Precipitation Method, Combustion Synthesis |
| Companies Covered | Inframat Advanced Materials, Meliorum Technologies, American Elements, NYACOL Nano Technologies, PlasmaChem GmbH, Cerion, SkySpring Nanomaterials, Strem Chemicals, Nanophase Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cerium Oxide Nanoparticles Market Shifts & Advancements
Manufacturing process intensification and regulatory documentation automation are reshaping competitive differentiation among cerium oxide nanoparticle suppliers, separating integrated rare earth processors from toll-dependent formulators.
Surfactant-stabilized nanoparticle dispersions are absorbing market share from dry nanopowder formats in semiconductor CMP operations. Leading foundries in Taiwan and South Korea are specifying ready-to-use slurries to eliminate in-house dispersion variability and reduce process defect rates. This transition is absorbing capital allocation previously directed toward powder handling infrastructure, compressing the addressable market for basic nanopowder grades.
REACH nanomaterial registration requirements are forcing European importers to consolidate supplier relationships around dossier-complete producers. ECHA's 2022-2024 enforcement waves have removed several Asian exporters from qualified vendor lists, redirecting procurement toward American and Japanese suppliers with completed substance identity and hazard characterization filings. Electronics chemical distributors in the Netherlands and Germany are responding by establishing exclusive representation agreements with compliant manufacturers.
Long-term offtake contracting is displacing spot purchasing among semiconductor chemical buyers. Memory and logic fabricators in Japan and the United States are locking in three-to-five-year supply agreements with fixed-volume, escalated-pricing structures to secure allocation amid rare earth processing capacity constraints. This behavioral shift is most visible at advanced node facilities where slurry qualification cycles exceed eighteen months and supplier switching costs are prohibitive.
Global Cerium Oxide Nanoparticles Market Segmentation
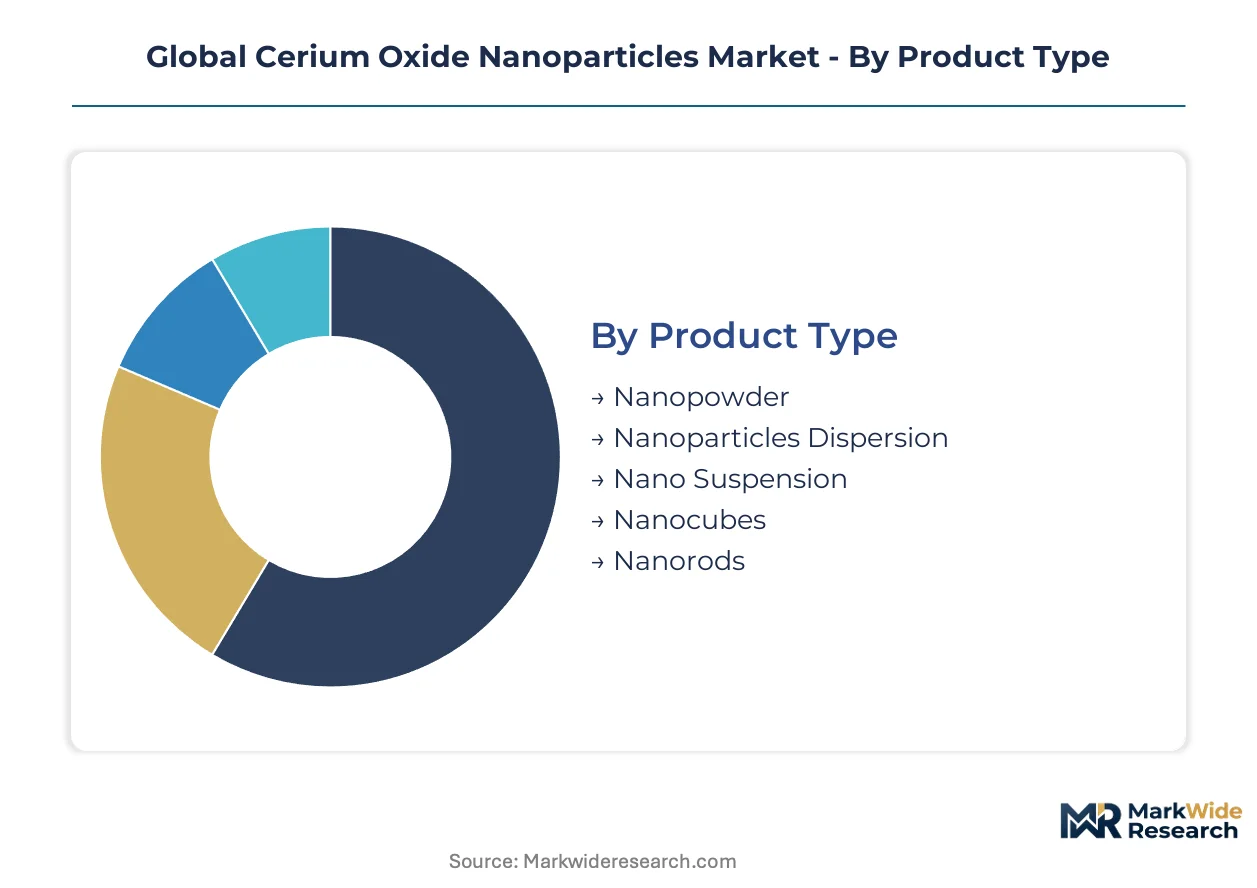
Cerium oxide nanoparticles serve divergent performance requirements across polishing, catalysis, and biomedical functions. Buyers select formats based on dispersion readiness, crystallite morphology, and regulatory documentation depth rather than commodity pricing alone.
Product Type:
Differentiation in this category centers on downstream handling costs and shelf stability requirements.
- Nanopowder:Dry CeO2 crystallites in 1-100 nanometer range offer maximum formulation flexibility for chemical distributors blending custom slurry concentrations. Semiconductor polishers in Taiwan and South Korea consume bulk volumes, though in-house dispersion infrastructure requirements limit adoption among smaller foundries.
- Nanoparticles Dispersion:Pre-stabilized aqueous suspensions eliminate particle agglomeration risks during storage. Electronics producers specify six-month viability windows to reduce process defect rates, driving premium positioning over basic powder grades.
- Nano Suspension:Higher solid-loading liquid formats suit continuous-feed catalytic reactors in flue gas treatment installations.
- Nanocubes:Faceted morphology delivers enhanced oxygen storage capacity for automotive catalytic converter applications.
- Nanorods:Anisotropic structures provide directional surface reactivity favored in specialized oxidation catalysis.
Nanopowder leads volumes today; nanoparticles dispersion is gaining share fastest.
Application:
Performance specifications vary sharply by functional chemistry and purity thresholds.
- Polishing Agents:Chemical mechanical planarization slurries demand ultra-low trace metal content below 10 ppm to prevent wafer contamination. Japanese memory fabricators lock in three-to-five-year supply agreements to secure allocation amid rare earth processing constraints.
- Catalysts:High oxygen storage capacity and redox cycling durability position cerium oxide for mercury capture and NOx reduction. German environmental engineering firms expand catalytic oxidation capacity at coal-fired facilities under tightening EU Industrial Emissions Directive enforcement.
- UV Absorbers:Transparent nanoparticle dispersions block ultraviolet degradation in coatings and plastics.
- Fuel Additives:Combustion efficiency improvements in diesel formulations drive modest volume demand.
- Biomedical Agents:Antioxidant and regenerative medicine applications require extensive toxicological dossier completion under FDA and EMA pathways.
Polishing agents command the dominant revenue share; catalyst applications expand most quickly.
End User Industry:
Procurement sophistication separates qualification-capable buyers from price-sensitive spot purchasers.
- Electronics Producers:Advanced node semiconductor fabricators impose 18-month slurry qualification cycles and mandate ISO-certified nanoparticle suppliers with documented environmental compliance. Long-term contracting behavior is displacing spot purchasing among Taiwan and United States memory producers.
- Environmental Firms:Flue gas treatment and wastewater catalysis deployments represent the steepest expansion trajectory with less price sensitivity than electronics polishing. Japanese engineering contractors specify cerium oxide for mercury capture at industrial combustion facilities.
- Ceramics Manufacturers:Structural and functional ceramic applications consume standard-grade nanopowder volumes.
- Chemical Suppliers:Formulation intermediaries blend and repackage for downstream specialty chemical markets.
- Textile Finishers:UV protection and antimicrobial finishing applications drive emerging demand.
Electronics producers anchor procurement volumes; environmental firms drive category growth.
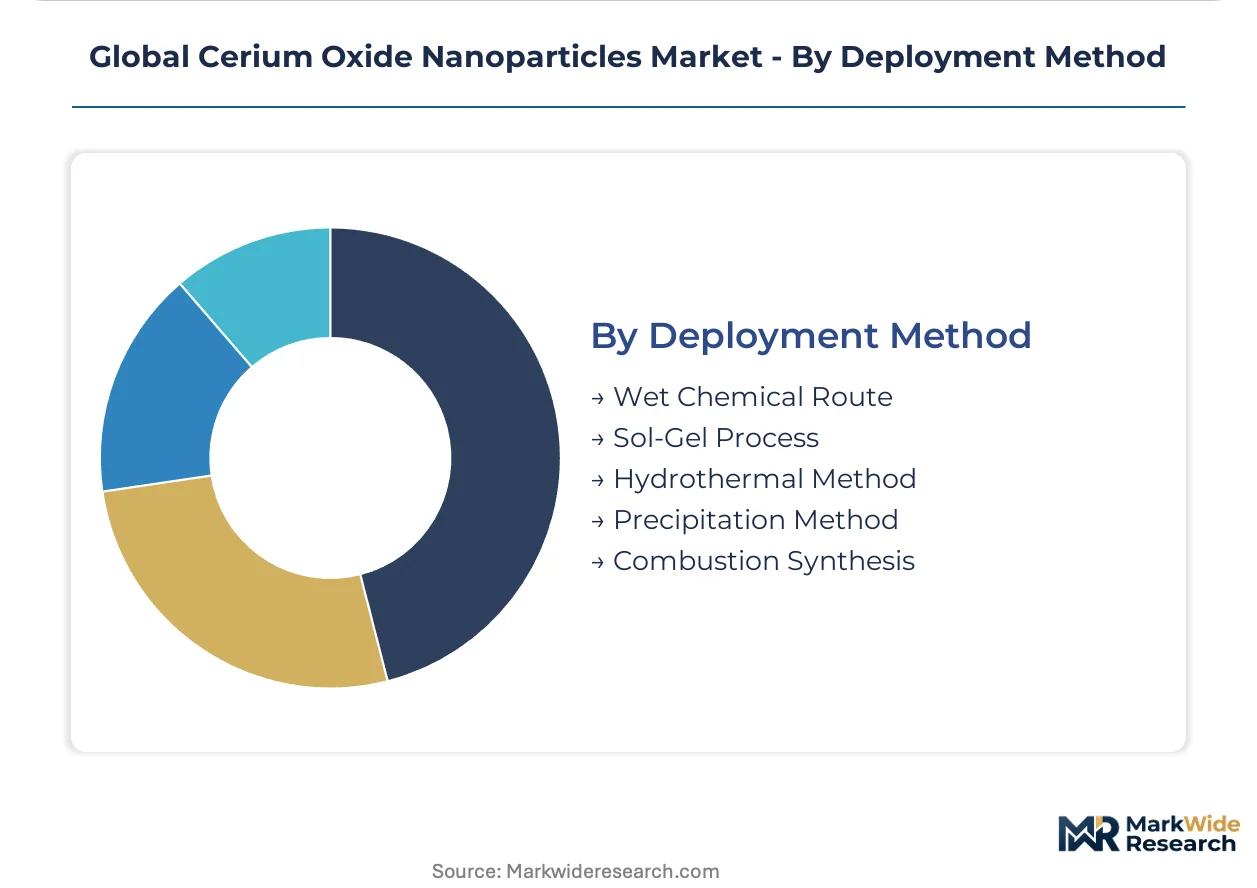
Deployment Method:
Capital intensity and batch consistency capabilities divide producer competitive positions.
- Wet Chemical Route:Precipitation and controlled oxidation in aqueous media achieves tight crystallite size distribution for semiconductor-grade specifications. Jiangsu-based producers achieve economies of scale that reduce unit costs for export-grade shipments.
- Sol-Gel Process:Alkoxide hydrolysis delivers high surface area nanoparticles with tunable porosity for catalytic applications. European importers favor sol-gel producers with completed ECHA dossier submissions under REACH nanomaterial registration requirements.
- Hydrothermal Method:High-pressure aqueous synthesis produces defined morphologies including nanorods and nanocubes.
- Precipitation Method:Lower-cost bulk production suits standard-grade ceramic and catalyst applications.
- Combustion Synthesis:Rapid high-temperature reaction generates metastable phases for specialized functional ceramics.
Wet chemical route dominates commercial output; sol-gel process commands premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province anchors the global cerium oxide nanoparticles supply base through concentrated rare earth refining and nanoparticle synthesis operations. EPA emissions standards in the United States and REACH nanomaterial registration requirements in Europe are reshaping procurement patterns across fabrication and environmental engineering sectors. Industrial clusters in China, Japan, Germany, and the United States concentrate both production capacity and downstream demand.
China
Semiconductor polishers and environmental catalyst buyers drive procurement volumes from domestic producers. MIIT continues tightening GB standards for nanoparticle manufacturing effluent, reshaping export availability from Shandong-based producers. The Jiangsu industrial cluster achieves economies of scale that reduce unit costs for export-grade nanopowder shipments bound for Taiwan and South Korea.
United States
Semiconductor fabricators consolidate slurry supply bases around nanoparticle producers with verified environmental compliance documentation. EPA oversight of rare earth processing emissions elevates compliance costs and favors producers with documented toxicity profiles and lifecycle assessments. American Elements leverages its integrated rare earth supply position to sustain long-term contracts with domestic polishers.
Japan
Memory and logic fabricators lock in three-to-five-year supply agreements with fixed-volume escalated-pricing structures. METI industrial policy supports advanced materials qualification for domestic chip manufacturing. Engineering contractors specify cerium oxide for mercury capture at industrial combustion facilities under tightening emissions enforcement.
Germany
Environmental engineering firms expand catalytic oxidation capacity using cerium oxide nanoparticles for mercury and NOx capture at coal-fired facilities. REACH registration requirements for nanomaterial imports elevate compliance costs and favor producers with completed ECHA dossier submissions. Electronics chemical distributors respond by establishing exclusive representation agreements with compliant manufacturers.
South Korea
Leading foundries specify ready-to-use slurries to eliminate in-house dispersion variability and reduce process defect rates. Domestic semiconductor producers drive premium positioning for nanoparticles dispersion formats over basic powder grades. Long-term contracting behavior displaces spot purchasing among memory producers seeking allocation security.
Global Cerium Oxide Nanoparticles Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized morphology formats and toll manufacturing partnerships. The vendor base separates into integrated rare earth processors with captive feedstock, dispersion-focused formulators competing on batch consistency, and toll-dependent specialists extending regional reach without direct capital deployment. Dominant competitive moves include strategic partnerships for regulatory documentation sharing and capacity expansion through continuous flow reactor installations.
Within the integrated supply tier, American Elements and NYACOL Nano Technologies exemplify contrasting positioning archetypes. American Elements occupies a position anchored to domestic rare earth supply security, while NYACOL Nano Technologies represents the dispersion-specialist vector competing on formulation stability. Cerion sits within the toll-manufacturing archetype, extending regional reach through partnership structures rather than owned production assets. These three company types collectively illustrate the strategic segmentation across feedstock control, formulation expertise, and capital-light expansion models.
| Leading Market Players |
|---|
| Inframat Advanced Materials |
| Meliorum Technologies |
| American Elements |
| NYACOL Nano Technologies |
| PlasmaChem GmbH |
| Cerion |
| SkySpring Nanomaterials |
| Strem Chemicals |
| Nanophase Technologies Corporation |
| Others |
Supply & Pricing Matrix
Rare earth surface chemists in China's Jiangsu province command wage premiums that compress margin spreads between nanopowder grades and ready-to-use dispersions. Labor-cost differentials between captive synthesis operations and toll-dependent formulators directly shape three-tier pricing structures across premium semiconductor-grade, standard catalyst-grade, and economy ceramic-grade product tiers.
Pricing Analysis
Input-cost pass-through from bastnasite and monazite concentrate volatility anchors contract-based long-term offtake structures with escalated-pricing clauses. Price differentiation separates REACH-registered European imports from unregistered Asian supply based on certification documentation depth and toxicological dossier completeness. Pricing pressure stems from colloidal silica substitution in shallow-layer CMP operations where surface defect tolerance permits lower-cost abrasive media. Electronics producers exhibit least price sensitivity due to eighteen-month qualification cycles, while ceramic manufacturers face acute margin compression from feedstock cost swings.
Supply Chain Analysis
Single-source vulnerability sits with Shandong-based producers subject to unannounced MIIT effluent enforcement actions that disrupt export timing without advance notice. Geographic supply concentration centers on China, Japan, and the United States, with Jiangsu rare earth refining operations feeding both domestic electronics producers and Taiwan-bound export channels. Raw material dependencies draw from Australian and Chinese mining operations for bastnasite concentrate, Japanese solvent extraction expertise, and German specialty surfactant inputs. Supply chain risk hinges on regulatory restriction divergence between EPA emissions standards and REACH nanomaterial registration timelines. Distribution runs through specialty chemical distributors in the Netherlands and Germany who consolidate qualified vendor lists around dossier-complete producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds as a regulatory demand accelerator, with EPA emissions standard tightening and REACH nanomaterial registration enforcement creating structural procurement preference for documented toxicity profile holders.
For Market Incumbents: Deploy continuous flow reactor capacity additions in low-emission jurisdictions to capture semiconductor polisher consolidation around verified environmental compliance documentation. Defensive positioning requires deepening captive rare earth feedstock control against concentrate price volatility, while extending toll manufacturing partnerships into India's PLI-subsidized semiconductor fabrication corridor to preempt qualification demand from domestic chip producers. For New Entrants and Emerging Players: Sol-gel process expertise for defined nanocube and nanorod morphologies offers the most penetrable wedge against integrated processors lacking specialized oxidation catalysis capabilities. White-space targets include wastewater advanced oxidation process deployments for pharmaceutical effluent treatment and mercury capture installations at German coal-fired facilities under EU Industrial Emissions Directive enforcement. Go-to-market execution should anchor on exclusive representation agreements with Netherlands-based electronics chemical distributors seeking REACH-compliant Asian supply alternatives. For Investors and Strategic Acquirers: Valuations sit cheapest among toll-dependent formulators with dispersion stability IP but lacking captive rare earth supply security. Long-term viability across the five-to-ten year window favors acquisition targets with completed OECD inhalation exposure studies and ECHA substance identity filings already submitted. The inflection signal to monitor is MIIT enforcement action frequency against Shandong producers, which would accelerate procurement migration toward integrated supply chain operators with documented environmental compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Concentrate Supply | Captive bastnasite sourcing from Australian mining operations insulates margin predictability against Chinese export quota volatility. |
| Continuous Flow Reactor Capacity Expansion | Seven-figure equipment commitments in Jiangsu achieve crystallite size distribution consistency demanded by Taiwan foundry specifications. |
| REACH Nanomaterial Registration Completion | Full ECHA dossier submissions secure preferred supplier status as Dutch distributors face downstream user obligation enforcement. |
| Long-term Supply Agreement with Memory Producers | Three-to-five-year fixed-volume contracts with Japanese fabricators lock in allocation amid rare earth processing capacity constraints. |
| Toll Manufacturing Partnership in India | CDSCO import documentation and BIS standards alignment through local partnership structures capture PLI scheme semiconductor fabrication incentives. |
Research Methodology
Multiple input streams — primary interviews with plant managers at Jiangsu rare earth refiners, procurement leads at Taiwan semiconductor foundries, and technical R&D directors at specialty chemical distributors; secondary validation through SEC 10-K filings, customs trade data, and ECHA registration dossiers; plus bottom-up and top-down triangulation — were reconciled to produce volume and value estimates.
Historical shipment patterns from Japanese memory fabricators and South Korean foundries were cross-referenced against panel input from environmental engineering contractors in Germany to anchor growth assumptions across the projection horizon. Segmentation modeling captured product type tier, end-use industry, deployment method, and regional production hub dimensions. CAGRs were derived from supply-side capacity buildout trajectories and demand-side qualification cycle timelines specific to semiconductor chemical mechanical planarization operations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MIIT effluent enforcement unpredictability, REACH registration timeline slippage, and colloidal silica substitution penetration in shallow-layer CMP process steps. Forecasts reflect assumptions about regulatory documentation completion rates and rare earth concentrate supply continuity that industry stakeholders may revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
Nano Zinc Oxide Market
Nanomaterials
Global Nano Silver Market
Nanomaterials
Lipid Nanoparticles Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Nanoparticle Analysis Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Polymer Nanocomposites Market
Nanomaterials
Nanotools Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Nanomaterials Market
Nanomaterials
Molybdenum Trioxide Nanopowder Market
Nanomaterials
Titanium Dioxide Nanomaterials Market