
 Huntite Market | 2026-2036
Huntite Market Size, Share, and Industry Trends Forecast 2026-2036
Huntite Market Outlook
A capital-intensity divergence between integrated miners and merchant processors is reorganizing competitive tiers in the Huntite Market. Huber Engineered Materials leverages captive mineral reserves in North America to control feedstock quality from extraction through calcination. Omya Group anchors its position through extensive downstream milling infrastructure and long-term supply contracts with polymer compounders. Specialty Minerals differentiates via technical service capabilities that help customers reformulate halogen-free flame retardant systems.
Huntite is a naturally occurring magnesium calcium carbonate mineral with the chemical formula Mg3Ca(CO3)4, typically refined to high purity for industrial applications where thermal decomposition at temperatures above 450°C provides endothermic fire suppression in polymer matrices. Synthetic huntite, produced through controlled precipitation methods, commands premium positioning in aerospace and electronics applications where batch consistency and trace contaminant limits exceed natural material performance. Natural huntite occupies volume leadership in construction fillers and rubber manufacturing, while composite huntite blends targeting plastics applications represent the fastest-growing formulation category as compounders seek balanced cost-performance profiles.
REACH registration requirements in Europe and EPA Toxic Substances Control Act oversight in the United States constrain market access for uncharacterized mineral imports, favoring suppliers with comprehensive substance dossiers and analytical certification. China's GB standards for industrial minerals and Japan's JIS fire safety testing protocols further fragment compliance obligations across major demand centers. Stakeholders must monitor regulatory divergence between halogen-free mandates and evolving smoke toxicity thresholds to anticipate which product grades will retain specification eligibility in key end-use sectors.
Market Dynamics
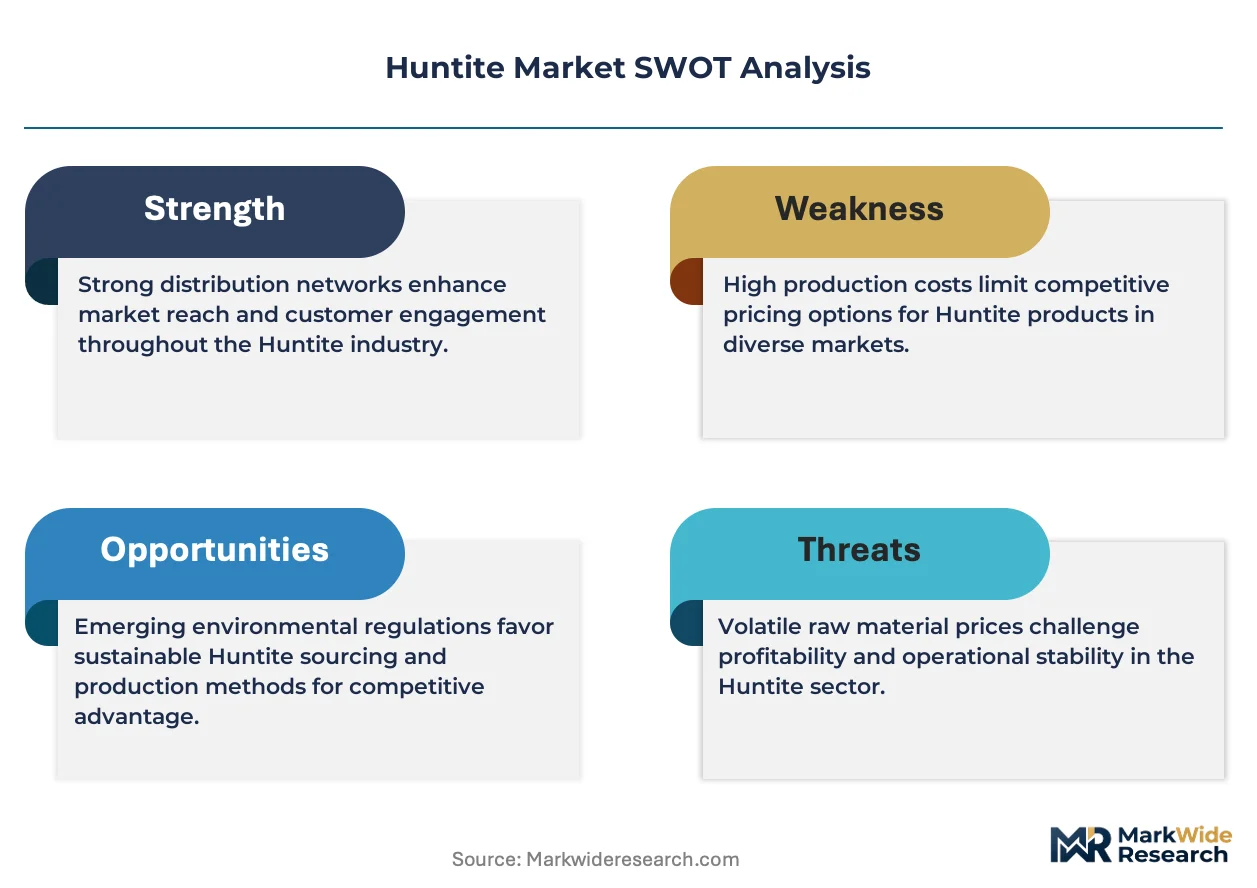
REACH registration dossiers and EPA TSCA compliance requirements are restructuring supplier eligibility in the Huntite Market, favoring integrated processors with captive mineral reserves and certified analytical laboratories over merchant traders.
Growth Catalysts
- Halogen-free mandate expansion:EU RoHS amendments and state-level flame retardant restrictions in California and Washington are compelling polymer compounders to reformulate with magnesium carbonate minerals.
- Aerospace thermal management:FAA fire safety standards for cabin interiors and cargo compartments are tightening smoke toxicity thresholds, driving specification of synthetic huntite in thermoset composites.
- China's industrial mineral clusters:Concentrated processing infrastructure in Liaoning and Shandong provinces supplies downstream construction and electronics manufacturers with cost-competitive feedstock.
Market Restraints
- Energy-intensive calcination:Natural gas price volatility directly impacts production economics for high-purity huntite grades, squeezing merchant processors without captive energy supply.
- Deposit concentration risk:Commercially viable huntite reserves cluster in specific geological formations, creating feedstock security concerns for non-integrated compounders.
- Aluminum hydroxide substitution:ATH delivers comparable endothermic performance at lower cost in non-aerospace applications, pressuring huntite pricing in construction fillers.
Strategic Opportunities
- India's construction chemicals sector:BIS fire safety standards for high-rise buildings are creating first-time specification opportunities for magnesium-based flame retardants in PVC flooring and cable compounds.
- Electric vehicle battery housings:Thermal runaway containment requirements are opening new specification pathways for huntite-polymer composites in EV battery tray applications.
- EU Green Deal industrial incentives:CSRD-aligned sustainability reporting is rewarding suppliers with verified low-carbon mineral processing, creating preference premiums for certified producers.
Industry Challenges
- REACH dossier maintenance:ECHA substance evaluation updates require continuous toxicological data generation, straining analytical budgets for mid-scale processors.
- Calcination asset specificity:Rotary kiln configurations optimized for huntite decomposition lack flexibility for alternative mineral processing, trapping capital in single-product infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Huntite Market |
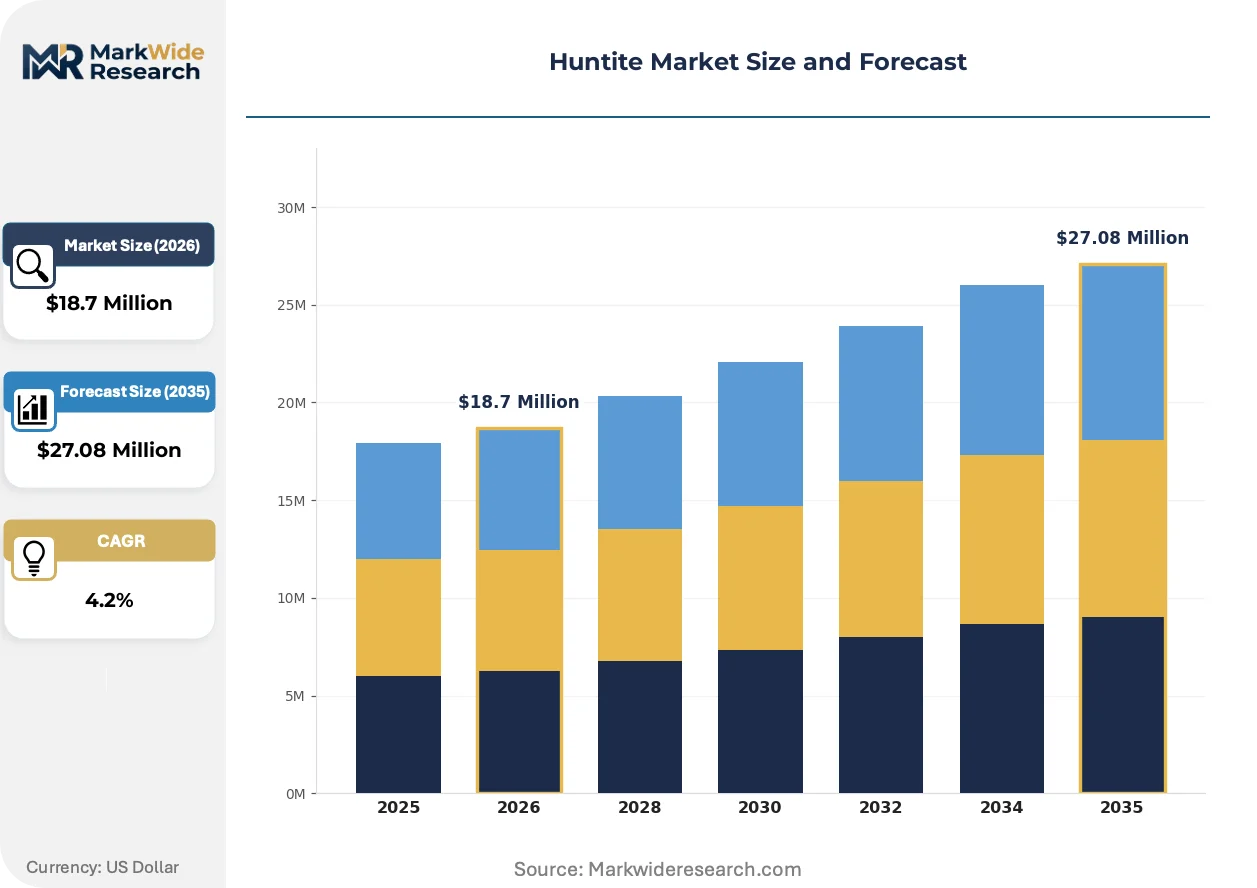
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $27.08 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Huntite, Synthetic Huntite, Composite Huntite, Industrial Grade Application: Flame Retardants, Fillers, Rubber Manufacturing, Plastics End User: Aerospace, Automotive, Construction, Electronics Distribution Channel: Direct Sales, Distribution Partners, Online Retail, Wholesale |
| Companies Covered | Huber Engineered Materials, Leap Labchem, Omya Group, Skyrun Industrial, Wanko Chemical, Specialty Minerals, Nordkalk Corporation, Sibleco, ICL Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Huntite Market Strategic Shifts
Synthetic huntite precipitation methods and composite mineral formulations are redrawing performance-cost boundaries, enabling suppliers to capture specification premiums previously reserved for engineered halogenated alternatives.
Controlled precipitation synthesis is displacing natural mineral sourcing in electronics-grade applications. Japanese semiconductor packaging manufacturers specify synthetic huntite for batch-to-batch consistency in epoxy molding compounds. This displacement is compressing margins for natural material traders while rewarding integrated producers with in-house precipitation capability.
REACH Annex XVII restrictions on halogenated flame retardants are tightening across EU member states. ECHA substance evaluation protocols now require comprehensive environmental fate data for competing mineral alternatives. Polymer compounders serving German automotive OEMs are responding by dual-sourcing certified huntite grades with full analytical traceability.
Specification-driven procurement is consolidating buyer power among tier-one polymer compounders. Long-term offtake agreements with aerospace and electronics OEMs are replacing spot-market purchasing for high-purity grades. This consolidation is most visible in China's Yangtze River Delta, where construction chemical distributors are losing share to direct mill relationships.
Huntite Market Segmentation
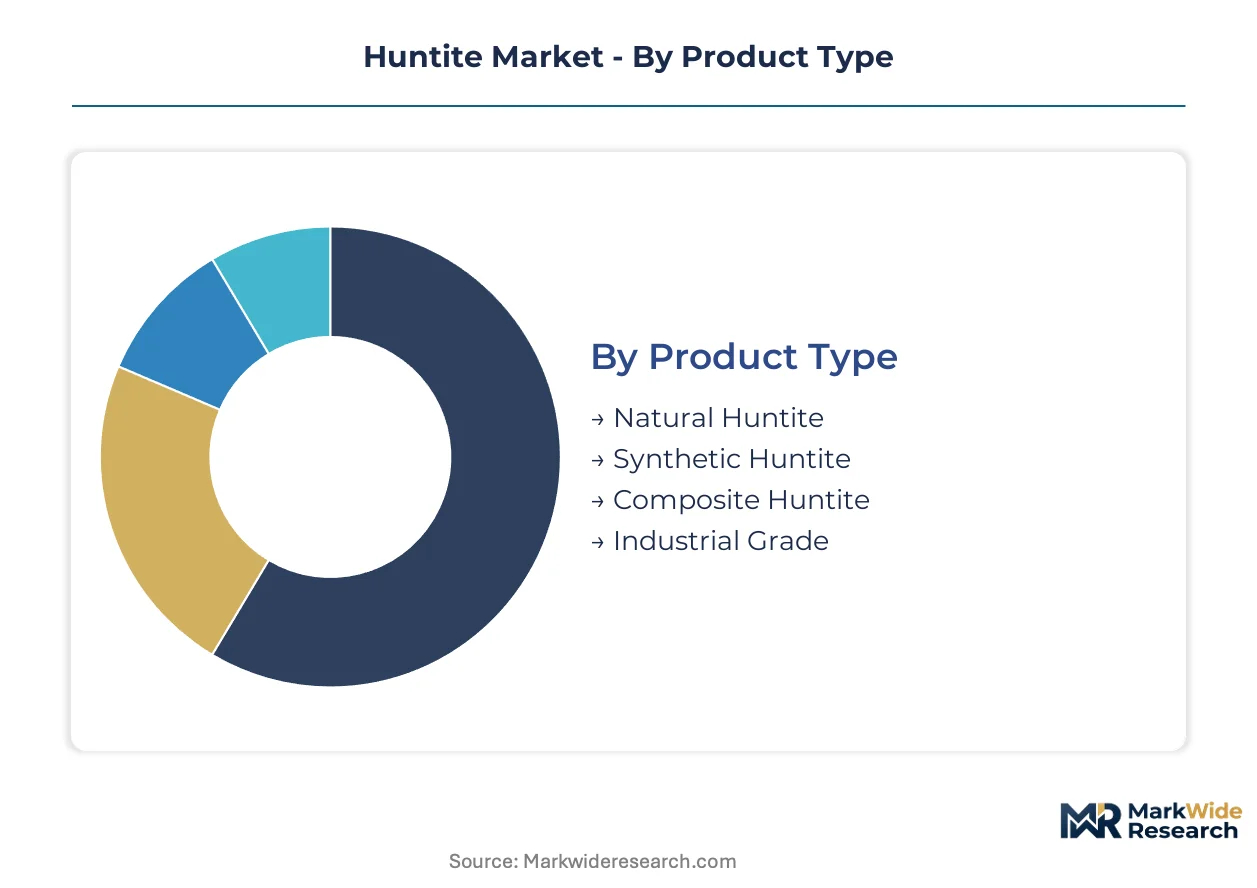
Huntite's industrial utility spans divergent specification regimes across flame retardancy, polymer reinforcement, and chemical processing. Segmentation reveals how mineral purity grades and synthesis methods align with distinct regulatory thresholds and end-use performance requirements.
Product Type:
Natural huntite dominates domestic supply chains in China and Turkey where sedimentary deposits support regional construction chemical industries. Synthetic grades travel through export channels to serve aerospace and electronics manufacturers in Germany, Japan, and the United States.
- Natural Huntite:Extracted from magnesium-calcium carbonate deposits and processed through calcination to 450°C decomposition thresholds. Chinese processors in Liaoning province supply regional PVC flooring compounders under GB fire safety standards.
- Synthetic Huntite:Manufactured via controlled precipitation of magnesium and calcium salts to achieve batch consistency below 50ppm trace contaminants. Japanese semiconductor packaging houses specify synthetic grades for epoxy molding compounds requiring JIS thermal stability certification.
- Composite Huntite:Blended formulations balancing cost and performance for mid-tier plastics applications.
- Industrial Grade:Lower-purity material serving bulk construction filler markets with relaxed contaminant specifications.
Natural huntite commands the established base. The steepest expansion runs through synthetic huntite.
Application:
Flame retardant applications concentrate value capture through aerospace and automotive specification premiums. Filler applications distribute volume across dispersed construction chemical supply chains with thinner margin structures.
- Flame Retardants:Endothermic decomposition at 450°C absorbs combustion heat while releasing carbon dioxide and water vapor to suppress flame propagation. German automotive cable manufacturers reformulate halogen-free harness compounds under EU RoHS amendments.
- Fillers:Cost-driven volume applications in construction materials and rubber goods where thermal properties are secondary to density and processing economics.
- Rubber Manufacturing:Reinforcing agent in high-temperature vulcanized compounds for industrial belting and seals.
- Plastics:Processing aid and property modifier in polypropylene and polyethylene compounding for consumer goods housings.
Flame retardant applications concentrate specification premiums. The steepest expansion trajectory cuts through plastics compounding as EV battery housing thermal management requirements multiply.
End User:
Aerospace and electronics end users impose the most stringent analytical certification requirements, sourcing through direct mill relationships. Construction sector procurement flows through layered distribution networks with lower documentation thresholds.
- Aerospace:FAA fire safety standards for cabin interiors mandate synthetic huntite in thermoset composites with documented smoke toxicity below specified thresholds. Boeing and Airbus tier-one suppliers maintain qualified producer lists with full analytical traceability.
- Electronics:Thermal management in semiconductor packaging and printed circuit board substrates requires sub-50ppm metallic contaminant limits achievable only through precipitation synthesis.
- Automotive:Wire harness and battery tray applications responding to thermal runaway containment regulations.
- Construction:PVC flooring, roofing membranes, and cable sheathing under national fire codes in China, India, and Southeast Asia.
Construction absorbs the volume base. Electronics is climbing the fastest on specification premiums.
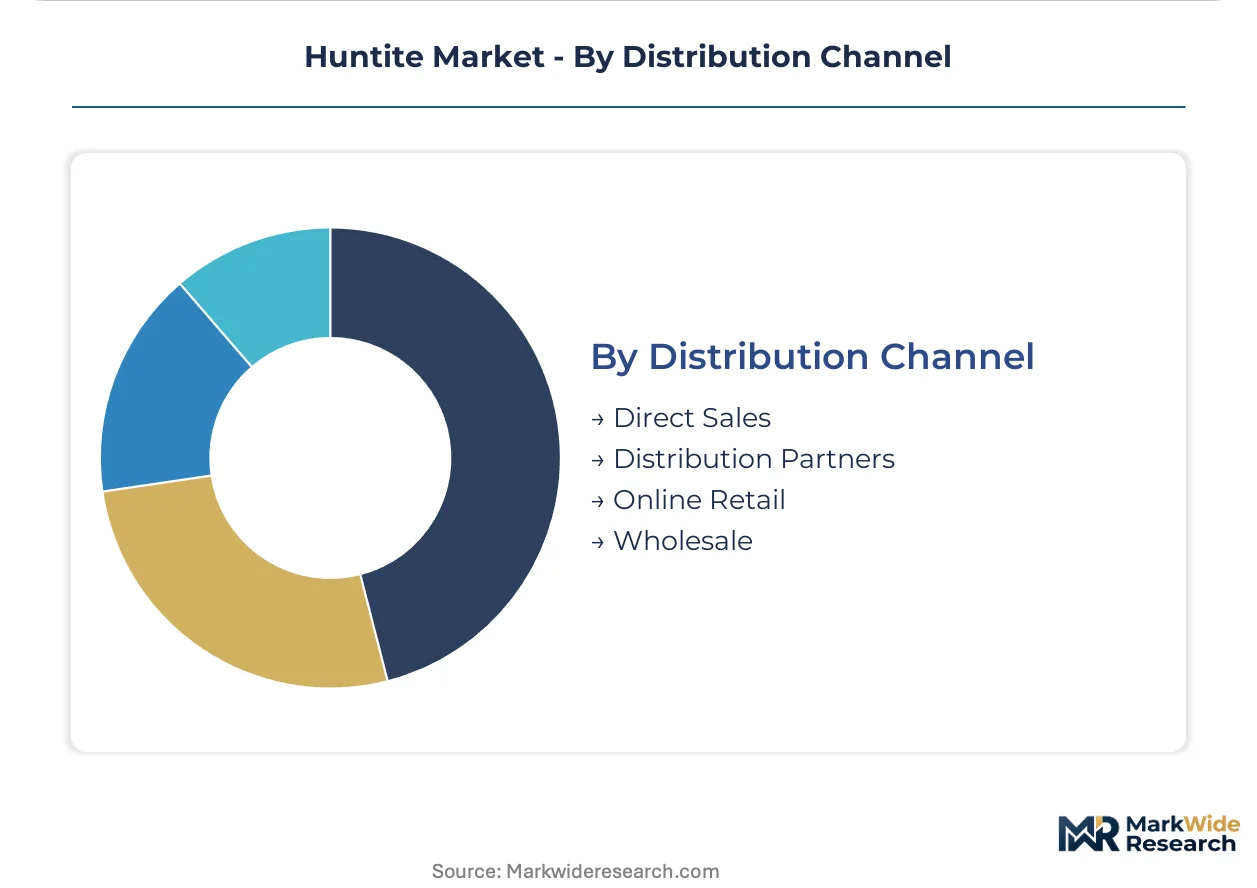
Distribution Channel:
Direct sales concentrate around aerospace and electronics OEMs with qualified supplier programs. Distribution partners retain relevance in construction chemicals where technical service requirements are lighter and order fragmentation is higher.
- Direct Sales:Long-term offtake agreements with polymer compounders serving aerospace OEMs and semiconductor packaging houses. Huber Engineered Materials and Omya Group maintain technical service teams at customer formulation laboratories.
- Distribution Partners:Regional chemical distributors stocking standard grades for construction chemical formulators and rubber processors.
- Online Retail:Limited to small-volume laboratory and R&D procurement.
- Wholesale:Bulk material aggregation for mineral traders serving non-integrated compounders.
Direct sales capture specification premiums. Distribution partners retain construction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in construction chemicals show acute price sensitivity to energy-driven calcination costs, while aerospace compounders absorb premium pricing for synthetic grades with documented traceability. This elasticity divergence shapes regional supply chain configurations.
China
Liaoning and Shandong provinces host concentrated huntite processing clusters serving domestic PVC flooring and cable manufacturers. GB standards for fire safety in high-rise construction mandate magnesium-based flame retardants in building materials. Dalian-based mineral processors supply downstream compounders under cost-competitive natural gas arrangements.
United States
FAA fire safety standards for commercial aircraft interiors drive synthetic huntite specification in thermoset composites. EPA TSCA compliance requirements favor integrated processors with certified analytical laboratories over import-dependent traders. Georgia and Alabama host aerospace chemical formulators maintaining qualified supplier relationships with Boeing tier-ones.
Germany
Automotive wire harness manufacturers reformulate halogen-free compounds under EU RoHS amendments and ECHA REACH substance evaluation protocols. Bavarian polymer compounders serve BMW and Volkswagen supply chains with full analytical traceability requirements. KBA vehicle safety standards reinforce specification rigor for cabin materials.
Japan
Semiconductor packaging houses specify synthetic huntite for epoxy molding compounds requiring JIS thermal stability certification. METI industrial standards govern contaminant limits in electronics-grade minerals. Kyushu-based chemical processors maintain precipitation synthesis capacity for sub-50ppm metallic impurity thresholds.
India
BIS fire safety standards for high-rise buildings create first-time specification opportunities in PVC flooring and cable compounds. Construction chemical demand concentrates in Maharashtra and Gujarat where industrial mineral distributors serve regional formulators. PLI scheme incentives for domestic manufacturing attract processing investment.
Huntite Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated miners with captive mineral reserves control feedstock quality and calcination economics, while merchant processors compete on milling infrastructure and distribution reach. Three archetypes dominate: backward-integrated mineral owners, downstream-focused compounders, and specialty service providers. Competitive moves concentrate on capacity expansion in low-energy-cost regions and strategic partnerships with polymer compounders seeking qualified supplier status.
Among North American integrated processors, Huber Engineered Materials exemplifies the captive-reserve archetype with upstream control over extraction through finished goods. European specialists Omya Group and Specialty Minerals occupy positions emphasizing downstream milling infrastructure and technical service capabilities respectively. These three represent distinct strategic vectors: mineral security, processing scale, and formulation support.
| Leading Market Players |
|---|
| Huber Engineered Materials |
| Leap Labchem |
| Omya Group |
| Skyrun Industrial |
| Wanko Chemical |
| Specialty Minerals |
| Nordkalk Corporation |
| Sibleco |
| ICL Group Ltd. |
| Others |
Value Chain & Pricing Dynamics
Aluminum hydroxide substitution in construction-grade flame retardants is simultaneously compressing huntite pricing in bulk fillers and redirecting procurement toward integrated mineral processors in China and Turkey. This displacement dynamic rewards suppliers with captive calcination assets while squeezing merchant traders dependent on spot-market natural gas.
Pricing Analysis
After-sales technical service contracts with polymer compounders drive lifetime value capture for synthetic huntite suppliers serving aerospace and electronics OEMs. Three-tier pricing structure across premium synthetic, standard natural, and economy industrial grades stratifies by certification level and batch consistency. Cost compression in natural huntite filler grades is intensifying because aluminum hydroxide delivers comparable endothermic performance at lower unit economics. Construction chemical distributors exhibit acute price sensitivity, while semiconductor packaging houses absorb premium positioning for sub-50ppm contaminant specifications.
Supply Chain Analysis
Inventory lead times for synthetic huntite extend beyond natural material cycles due to precipitation synthesis batch scheduling and JIS certification queues. Geographic supply concentration centers on China, Turkey, and Japan, with raw material dependencies spanning magnesium chloride feedstock, calcium carbonate sources, and natural gas for calcination energy. Single-source vulnerability runs through Liaoning province sedimentary deposits for natural grade processors. Distribution runs through direct mill relationships for aerospace and electronics OEMs, while construction chemicals flow via regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Halogen-free flame retardant mandates across EU RoHS amendments and state-level restrictions in California and Washington are disrupting formulation economics and opening specification windows for magnesium carbonate minerals.
For Market Incumbents: Secure long-term offtake agreements with tier-one polymer compounders serving Boeing and Airbus supply chains before aluminum hydroxide suppliers achieve REACH certification for electronics-grade applications. Deepen backward integration into captive mineral reserves in North America to defend calcination margin structures against natural gas volatility.
For New Entrants and Emerging Players: Anchor in India's construction chemicals sector where BIS fire safety standards for high-rise buildings create first-time specification opportunities without entrenched supplier relationships. Target Maharashtra and Gujarat regional formulators with cost-competitive natural huntite grades and technical service partnerships for PVC flooring compounds.
For Investors and Strategic Acquirers: The market sits at a regulatory inflection phase that favors integrated processors with precipitation synthesis capability and REACH dossier completeness. Five-to-ten year viability hinges on CSRD-aligned carbon accounting for mineral processing. Watch for ECHA substance evaluation updates on competing mineral alternatives as the signal for specification lock-in timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Mineral Reserves | Huber Engineered Materials controls feedstock quality from extraction through calcination in North American deposits. |
| Precipitation Synthesis Capacity Expansion | Japanese semiconductor packaging houses specify synthetic grades for JIS thermal stability certification requirements. |
| REACH Dossier Maintenance Investment | ECHA substance evaluation protocols demand continuous toxicological data generation for market access retention. |
| Direct Mill Relationship Development | Aerospace OEM qualified supplier programs replace spot-market purchasing with long-term analytical traceability contracts. |
| Green Manufacturing Transition | EU Green Deal industrial incentives reward verified low-carbon mineral processing with procurement preference premiums. |
Study Parameters
A standing panel of mineral processing plant managers, polymer compounder procurement leads, aerospace chemical formulators, and REACH regulatory consultants provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with downstream OEM technical directors and distribution channel partners, validated against customs trade data, SEC 10-K filings from listed processors, and ECHA registration dossiers. Bottom-up volume modeling triangulated with top-down market sizing from industry association reports.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning grade tier, end-use industry, synthesis method, and regional production hub. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact assessment incorporated natural gas price elasticity for calcination economics and halogen-free mandate penetration curves by jurisdiction.
Material uncertainties — regulatory divergence between halogen-free mandates and evolving smoke toxicity thresholds, energy price volatility for calcination assets, and aluminum hydroxide substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about REACH dossier maintenance costs and ECHA evaluation timelines. Revision becomes warranted when aluminum hydroxide achieves electronics-grade certification thresholds or when natural gas price volatility exceeds historical bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Copper Sputtering Target Market
Metals
Steel Long Products Market
Metals
Stainless Steel Round Bar Market
Metals
Europe Welding Consumables Market
Metals
Metal Forging Parts Market
Metals
Copper Powder Market
Metals
Arc Ferrite Magnet Market
Metals
Industrial Silver Market
Metals
Saudi Arabia Aluminum Market
Metals
Palladium Market
Metals
Industrial Metal Strips Market
Metals
Lithium Tungstate Market
Metals
Aluminum Flat Products Market
Metals
Copper and Copper Alloy Powder Market
Metals
Europe Aluminium Wire Rod Market
Metals
Global Electrolytic Copper Foil Market