
 United States Metal Casting Market | 2026-2036
United States Metal Casting Market Size, Share, and Industry Trends Forecast 2026-2036
United States Metal Casting Market Intelligence
Asset-light leasing arrangements for melting and molding equipment is tilting competitive dynamics toward mid-tier foundries that previously faced capital barriers. Precision Castparts Corp. leverages captive aerospace supply relationships to sustain premium positioning. Barron Industries anchors its competitiveness through specialized stainless steel and nickel-based superalloy capabilities. Signicast differentiates via high-volume investment casting automation that compresses lead times for medical and firearms components.
Metal casting encompasses the pouring of molten ferrous or non-ferrous alloys into refractory molds to produce near-net-shape components with tolerances typically ranging from ±0.5 mm to ±3 mm depending on process control. The technique serves as the backbone for manufacturing engine blocks, turbine blades, pump housings, and structural brackets where geometric complexity precludes forging or machining from solid. Sand casting retains the largest volume footprint due to its cost efficiency for iron and steel components above 50 kg, while die casting captures margin pools in thin-wall aluminum automotive housings where cycle time drives economics. Investment casting occupies the premium tier for superalloy aerospace and medical implants requiring intricacy beyond conventional mold capabilities.
EPA foundry air toxics standards and OSHA permissible exposure limits for respirable crystalline silica compel capital expenditure on baghouse filtration and mold-line automation, effectively raising minimum viable scale. NHTSA fuel economy mandates propagate aluminum die casting penetration into electric vehicle thermal management housings and battery tray structures. State-level environmental variances across Michigan, Ohio, and Indiana create uneven compliance cost burdens that stakeholders must map against customer proximity and logistics networks.
Market Dynamics
EPA foundry air toxics standards and OSHA silica exposure limits are compressing operating margins while simultaneously forcing consolidation toward capitalized operators capable of deploying automated mold lines and advanced baghouse filtration systems.
Growth Catalysts
- Aerospace turbine blade procurement:Commercial aviation and defense programs are expanding superalloy casting volumes for high-temperature engine components. OEMs are qualifying additional domestic suppliers to reduce single-source risk.
- NHTSA fuel economy mandates:Corporate Average Fuel Economy requirements are accelerating aluminum die casting penetration into electric vehicle battery trays and thermal management housings. Foundries with thin-wall capability are securing multi-year platform awards.
- Great Lakes manufacturing corridor concentration:Proximity to Detroit automotive engineering centers, Cleveland medical device clusters, and Chicago logistics hubs creates efficient supplier-customer matching. Michigan, Ohio, and Indiana collectively host the densest foundry infrastructure in North America.
Market Restraints
- Scrap metal price volatility:Ferrous and non-ferrous scrap input costs fluctuate with commodity cycles, compressing margin predictability for fixed-price contract manufacturers. Smaller foundries lack hedging instruments to offset this exposure.
- Silica exposure compliance burden:OSHA permissible exposure limits for respirable crystalline silica mandate capital expenditure on automated mold handling and ventilation upgrades. Minimum viable scale is rising, squeezing sub-$10 million revenue operators.
- Near-shoring substitution risk:Mexican foundry capacity expansion in Querétaro and Nuevo León offers lower labor cost structures for automotive castings. Some OEMs are diversifying supply geographically despite logistics complexity.
Strategic Opportunities
- Texas and Southeast industrial relocation:Automotive OEMs are expanding assembly capacity in Tennessee, South Carolina, and Texas. Greenfield foundry investments proximate to these plants can capture logistics advantages over legacy Great Lakes suppliers.
- Medical implant superalloy casting:Orthopedic and cardiovascular device manufacturers require cobalt-chrome and titanium investment castings with micron-level precision. FDA 510(k) pathway expertise creates defendable positioning.
- Inflation Reduction Act clean manufacturing incentives:Section 45X advanced manufacturing production credits reward domestic energy-intensive production with lower-carbon intensity. Foundries deploying electric induction melting can qualify for meaningful tax offsets.
Industry Challenges
- Tool and die maker shortage:Patternmaking and core box machining expertise is aging out of the workforce. Community college apprenticeship pipelines are insufficient to replace retiring craftsmen with CNC-programming competence.
- Multi-year EPA compliance timelines:New source review permitting for major facility modifications extends 18-36 months. Capital deployment decisions must anticipate regulatory approval delays that mismatch customer contract cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Metal Casting Market |
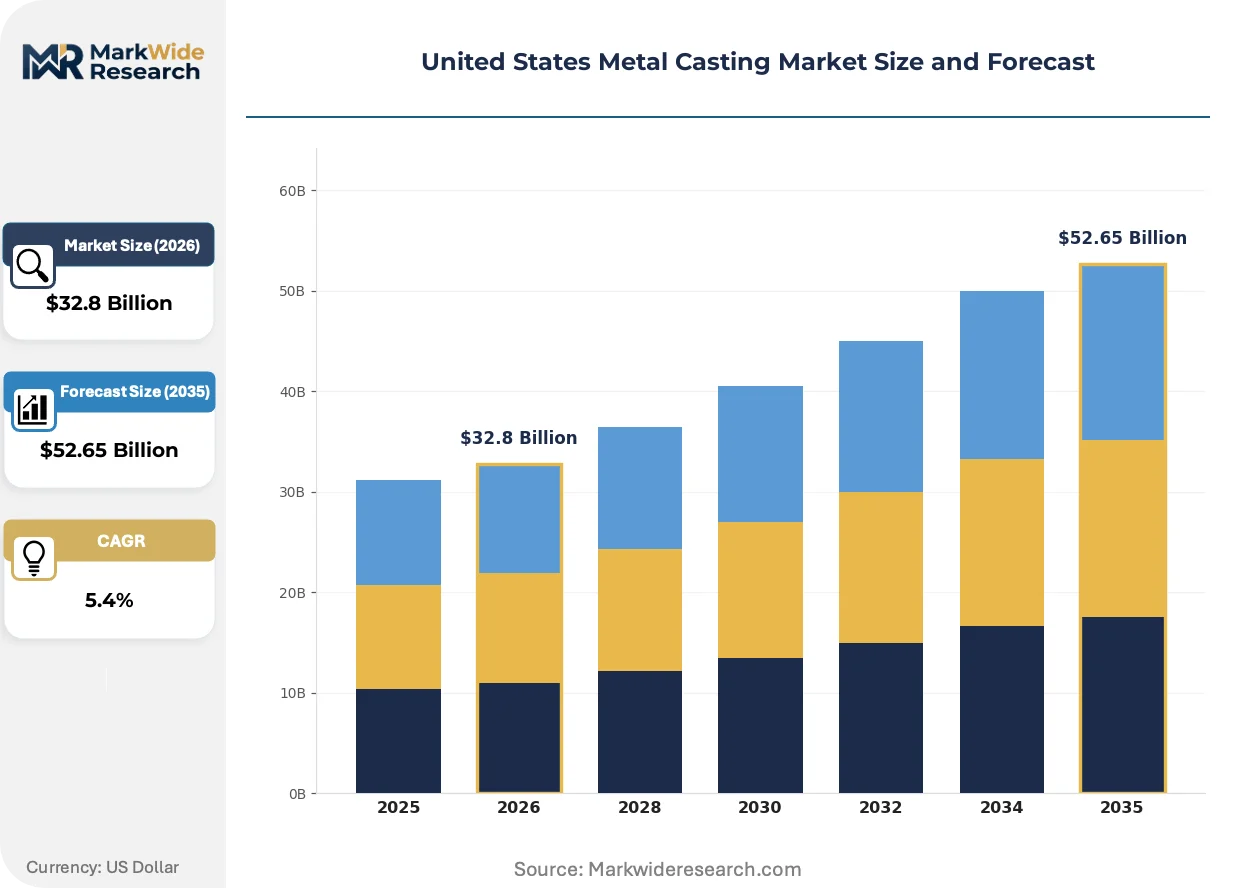
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sand Casting, Investment Casting, Die Casting, Permanent Mold Casting End User: Aerospace, Automotive OEM, Construction, Consumer Goods Material: Aluminum, Iron, Steel, Brass Technology: CNC Machining, 3D Printing, Traditional Molding, Casting Simulation |
| Companies Covered | Aristo-Cast, Barron Industries, Stainless Foundry & Engineering, Milwaukee Precision Casting, Aero Metals, American Casting Company, Signicast, Precision Castparts Corp., IPC Foundry Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Metal Casting Market Strategic Shifts & Innovations
Digital process control and additive manufacturing are restructuring how castings move from design to production, compressing development cycles and enabling geometries previously unachievable through conventional patternmaking.
Simulation-driven solidification modeling is collapsing the iteration cycles between casting design and first article approval. Automotive and aerospace engineers now validate gating and riser configurations virtually before cutting hard tooling. Tier-1 suppliers with integrated computational fluid dynamics capability are capturing program development work from pattern shops lacking digital competence.
EPA Maximum Achievable Control Technology standards for hazardous air pollutants are mandating continuous emissions monitoring and predictive maintenance integration. Foundries must deploy baghouse differential pressure sensors and thermal oxidizer control systems with automated reporting. Michigan and Ohio facilities face the steepest retrofit timelines due to older installed equipment bases and state implementation plan deadlines.
Consolidated procurement through tiered supplier tiering is reshaping how OEMs engage foundry capacity. Prime contractors are reducing approved vendor lists and awarding multi-year blanket orders to vertically capable suppliers. Tier-2 and tier-3 casting buyers in agricultural and construction equipment are experiencing extended lead times as capacity concentrates with preferred suppliers serving automotive and aerospace volume commitments.
United States Metal Casting Market Segmentation
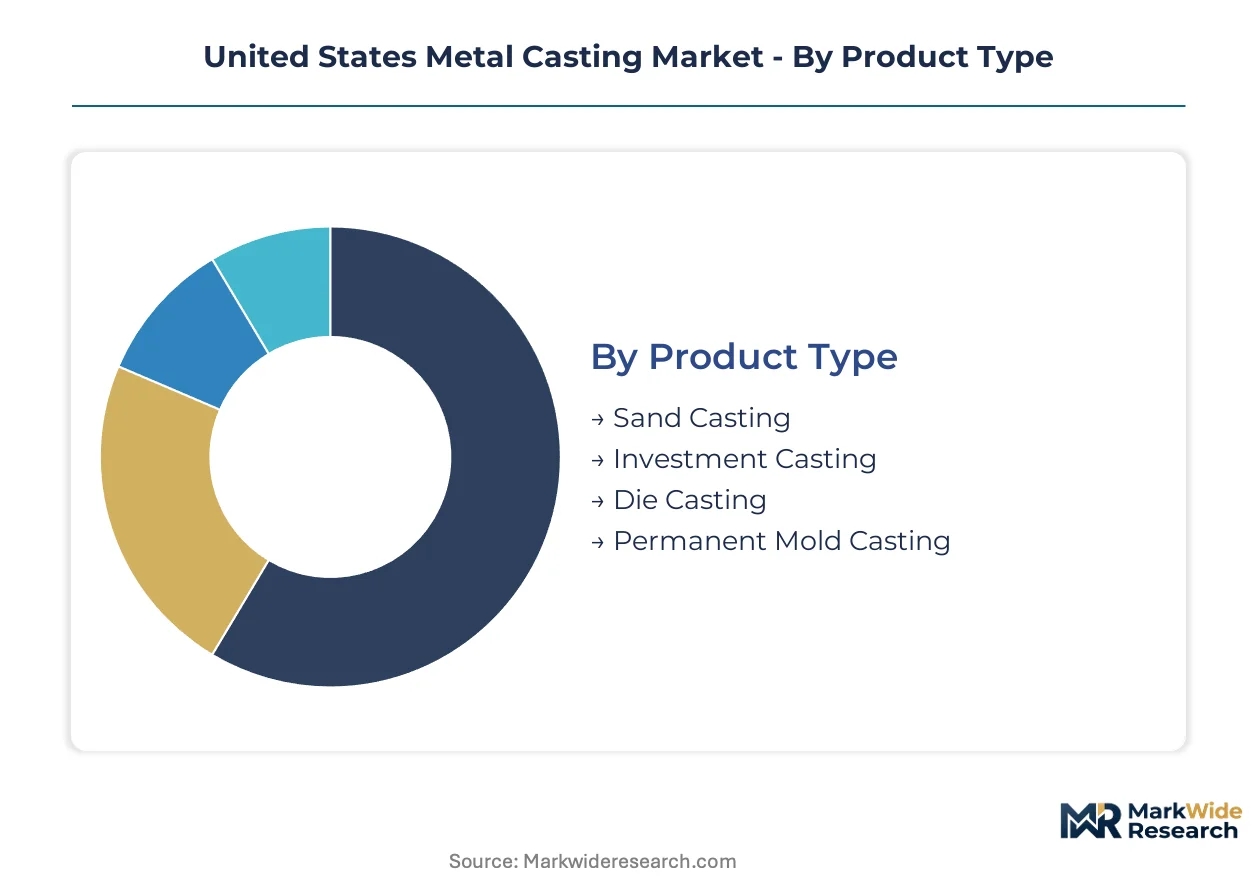
Segmentation in the United States Metal Casting Market reveals how process economics, regulatory exposure, and customer proximity create distinct competitive arenas. Foundries must align capital intensity and technical capability with specific segment requirements to secure sustainable positioning.
Product Type:
After-sales service intensity varies dramatically across casting processes, with die casting requiring continuous die maintenance programs and sand casting demanding pattern refurbishment cycles that lock foundries into long-term customer relationships.
- Sand Casting:Green sand and chemically bonded mold systems handle ferrous components above 50 kg with cost efficiency unmatched by precision processes. EPA air toxics compliance costs concentrate heaviest in legacy Michigan and Ohio facilities running high-volume automotive engine block programs.
- Die Casting:High-pressure aluminum injection achieves thin-wall geometries below 3 mm for EV battery trays and thermal management housings. NHTSA fuel economy mandates are accelerating platform awards to foundries with 4,000-ton press capacity proximate to Tennessee and Texas assembly plants.
- Investment Casting:Ceramic shell processes deliver superalloy turbine blades and medical implants with micron-level precision. FDA 510(k) pathway expertise creates defendable positioning in cobalt-chrome orthopedic segments.
- Permanent Mold Casting:Gravity-fed aluminum pouring offers middle-ground economics between sand and die processes for pump housings and agricultural components.
Sand casting holds the largest share; momentum sits with die casting.
End User:
Customer concentration patterns diverge sharply across end-use sectors, with aerospace procurement consolidating toward qualified dual-source arrangements while construction equipment buyers fragment across regional tier-2 suppliers.
- Aerospace:Superalloy turbine blade and structural housing procurement is expanding across commercial aviation and defense programs. OEMs are qualifying additional domestic suppliers to reduce single-source risk in critical engine components.
- Automotive OEM:Aluminum penetration into EV battery trays and motor housings is compressing traditional iron casting volumes. Platform awards increasingly favor foundries with integrated CNC machining and leak-testing capability.
- Construction:Hydraulic component and undercarriage casting demand tracks infrastructure spending cycles with pronounced regional variation.
- Consumer Goods:Firearms and recreational equipment castings prioritize investment casting automation for complex geometries at moderate volumes.
Automotive OEM commands the dominant revenue position; aerospace is expanding most quickly.
Material:
Scrap input cost volatility and melting energy intensity create divergent margin structures across alloy families, with aluminum benefiting from IRA Section 45X credits while ferrous grades face steeper OSHA silica compliance burdens.
- Aluminum:Secondary smelting from recycled feedstock dominates die casting supply chains. Electric induction melting configurations qualify for meaningful tax offsets under clean manufacturing incentives.
- Iron:Gray and ductile iron grades retain cost advantage in powertrain components above 25 kg. EPA Maximum Achievable Control Technology standards are mandating continuous emissions monitoring at older Great Lakes facilities.
- Steel:Carbon and alloy steel castings serve oilfield and mining equipment with specification requirements that resist substitution.
- Brass:Copper-zinc alloys occupy niche plumbing and decorative applications with stable but limited growth trajectories.
Iron maintains volume leadership; aluminum is gaining share fastest.
Technology:
Digital competence is separating tier-1 suppliers from pattern shops lacking simulation and additive manufacturing integration, with casting simulation now table stakes for aerospace and automotive program development work.
- Casting Simulation:Computational fluid dynamics validation of gating and riser configurations collapses iteration cycles before hard tooling commitment. Tier-1 suppliers with integrated simulation capability are capturing program development work from conventional pattern shops.
- 3D Printing:Binder jet and sand printing enable complex core geometries and rapid prototyping without traditional patternmaking. Tool and die maker shortages are accelerating foundry investment in printed mold components.
- CNC Machining:Post-cast finishing integration determines qualification for tight-tolerance aerospace and medical contracts.
- Traditional Molding:Manual patternmaking and core assembly persist in low-volume custom work but face workforce attrition pressures.
Traditional molding retains installed base dominance; casting simulation shows the steepest adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA Section 45X credits and NHTSA fuel economy mandates are redistributing foundry investment toward the Southeast and Texas, challenging the historical dominance of the Great Lakes corridor.
Great Lakes Manufacturing Corridor
Michigan, Ohio, and Indiana retain the densest foundry infrastructure in North America, anchored by Detroit automotive engineering centers and Cleveland medical device clusters. EPA Maximum Achievable Control Technology standards impose the steepest retrofit burdens here due to older installed equipment bases. Warren, Michigan and Cleveland, Ohio host concentrated superalloy and stainless steel casting operations serving aerospace and medical OEMs.
Southeast Industrial Belt
Tennessee, South Carolina, and Georgia are attracting greenfield foundry investments proximate to expanding automotive assembly capacity. NHTSA Corporate Average Fuel Economy requirements accelerate aluminum die casting awards for EV battery trays. Chattanooga, Tennessee and Greenville, South Carolina emerge as logistics-competitive alternatives to legacy Midwest suppliers.
Texas Manufacturing Triangle
Houston, Dallas-Fort Worth, and Austin anchor expanding demand for oilfield equipment castings and EV thermal management components. State-level environmental variances create lower compliance cost burdens versus EPA-heavy Midwest jurisdictions. San Antonio foundries capture proximity advantages to Mexico border logistics for cross-border supply chains.
Pacific Northwest Technology Corridor
Washington and Oregon concentrate investment casting expertise for aerospace turbine blades and medical implants. Boeing procurement centers in Seattle drive qualification programs for domestic superalloy suppliers. Portland, Oregon hosts specialized titanium casting operations serving orthopedic device manufacturers with FDA 510(k) pathway requirements.
United States Metal Casting Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered supply arrangements that favor vertically capable suppliers with integrated machining and testing. The vendor base separates into three strategic archetypes: aerospace-captive superalloy specialists, high-volume automotive die casters, and medical-precision investment casters. M&A activity concentrates on acquiring FDA-qualified facilities and automated mold-line capabilities. Geographic expansion toward Southeast automotive plants represents the dominant competitive move.
Among Great Lakes-based specialists, Barron Industries and Signicast exemplify divergent archetypes within the same regional cluster. Precision Castparts Corp. occupies a position as the aerospace-captive benchmark against which domestic qualification programs measure alternative suppliers. These three entities represent the competitive spectrum from stainless steel specialization through high-volume automation to integrated prime contractor supply.
| Leading Market Players |
|---|
| Aristo-Cast |
| Barron Industries |
| Stainless Foundry & Engineering |
| Milwaukee Precision Casting |
| Aero Metals |
| American Casting Company |
| Signicast |
| Precision Castparts Corp. |
| IPC Foundry Group |
| Others |
Cost & Logistics Intelligence
The Great Lakes manufacturing corridor spanning Michigan, Ohio, and Indiana concentrates legacy foundry capacity that shapes downstream pricing power across automotive and aerospace supply chains. EPA compliance burdens and silica exposure mandates at older facilities create cost asymmetries that tier-1 suppliers exploit to defend premium positioning against regional competitors.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k)-qualified investment casters commanding substantial premiums over general industrial suppliers. Contract-based long-term offtake agreements dominate aerospace turbine blade procurement, while spot-market volatility in ferrous scrap compresses margin predictability for sand casting operators serving construction equipment buyers. Cost compression in aluminum die casting is intensifying as NHTSA fuel economy mandates accelerate EV platform awards to thin-wall specialists. Automotive OEM procurement teams exhibit the highest price sensitivity, whereas medical device manufacturers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Precision Castparts Corp., Barron Industries, and Signicast anchor domestic superalloy and high-volume casting capacity alongside Mexican foundry expansion in Querétaro and Nuevo León. Ferrous scrap, aluminum ingot, and nickel-based superalloy feedstock draw from commodity markets with pronounced cyclical volatility. Single-source vulnerability concentrates in aerospace-qualified turbine blade suppliers where OEM dual-sourcing programs remain incomplete. Distribution runs through tiered supplier hierarchies with prime contractors consolidating approved vendor lists and funneling volume to vertically capable foundries with integrated machining and leak-testing capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Metal Casting Market is recovering from cyclical lows as aerospace procurement expansion and EV platform buildouts restore capacity utilization. Defense program superalloy demand and NHTSA fuel economy mandates provide the cyclical justification for strategic repositioning.
For Market Incumbents: Entrench aerospace-captive relationships by qualifying additional engine platforms before OEMs complete secondary supplier programs. Deploy capital toward automated mold-line upgrades that satisfy OSHA silica exposure limits while smaller competitors face compliance-driven exit pressure. Backward integration into precision CNC machining captures leak-testing and finishing work currently outsourced to specialized job shops. For New Entrants and Emerging Players: The Southeast industrial belt around Tennessee and South Carolina offers greenfield site availability proximate to expanding automotive assembly plants without the EPA retrofit burdens concentrated in legacy Great Lakes facilities. Target aluminum die casting for EV thermal management housings where NHTSA mandates create demand inelasticity and platform awards extend across multi-year horizons. Pursue qualification partnerships with tier-1 suppliers seeking geographic diversification away from single-region concentration risk. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core casting divisions lacking the capital intensity to satisfy EPA Maximum Achievable Control Technology standards. Long-term viability favors facilities with existing aerospace or medical qualifications that create defendable positioning against commodity competition. Monitor EPA permitting timelines and OSHA enforcement patterns as inflection indicators for consolidation velocity and margin recovery trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Mold-Line Deployment | OSHA silica compliance at scale separates capitalized operators from sub-$10 million revenue foundries facing forced exit. |
| Backward Integration into CNC Machining | Post-cast finishing capability determines qualification for tight-tolerance aerospace and EV battery tray contracts. |
| Southeast Greenfield Expansion | Proximity to Tennessee and Texas automotive assembly plants captures logistics advantages over legacy Midwest suppliers. |
| FDA 510(k) Pathway Investment | Medical implant superalloy casting creates defendable margin pools with orthopedic device OEMs requiring micron-level precision. |
| Electric Induction Melting Conversion | IRA Section 45X clean manufacturing credits offset energy costs for aluminum foundries deploying lower-carbon intensity configurations. |
Research Approach
Cross-validation between primary interviews with foundry operations directors, OEM procurement managers, aerospace tier-1 supplier quality engineers, and EPA compliance consultants anchors the qualitative findings against secondary validation from SEC 10-K filings, American Foundry Society technical publications, and OSHA enforcement databases. Bottom-up capacity utilization assessments across Michigan, Ohio, and Indiana facilities were reconciled with top-down demand modeling from NHTSA vehicle production projections and Boeing procurement disclosures.
Calibration against historical margin compression episodes during prior scrap metal price cycles refined the analytical framework across the projection horizon. Segmentation dimensions encompassed casting process type, end-use sector, alloy family, and geographic production cluster. CAGRs were derived from regression analysis of capacity expansion announcements, platform award timing, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated EPA Maximum Achievable Control Technology implementation schedules and IRA Section 45X credit qualification pathways.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Mexican foundry operators or accelerated EPA enforcement timelines would shift outcomes beyond modeled ranges. Quarterly review of scrap metal futures, aerospace platform qualification announcements, and Southeast automotive assembly plant ramp schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Copper Wire Market
Metals
Global Ultra-Low Alpha Metal Market
Metals
Global High Purity Titanium Powder Market
Metals
Global Copper Cathode Market
Metals
US Metal Fabrication Market
Metals
High Purity Base Metals Market
Metals
Aluminum Powders Pastes and Flakes Market
Metals
GCC Aluminium Cans Market
Metals
Vietnam Aluminum Market
Metals
316 Stainless Steel Container Market
Metals
Wear Steel Plate Market
Metals
Finished Steel Products Market
Metals
HSLA Steel Plate Market
Metals
Copper and Copper Alloy Market
Metals
US Copper Scrap Market
Metals
Amorphous Metal Cores Market