
 Ceramic Ball Bearings Market | 2026-2036
Ceramic Ball Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Ball Bearings Market Intelligence
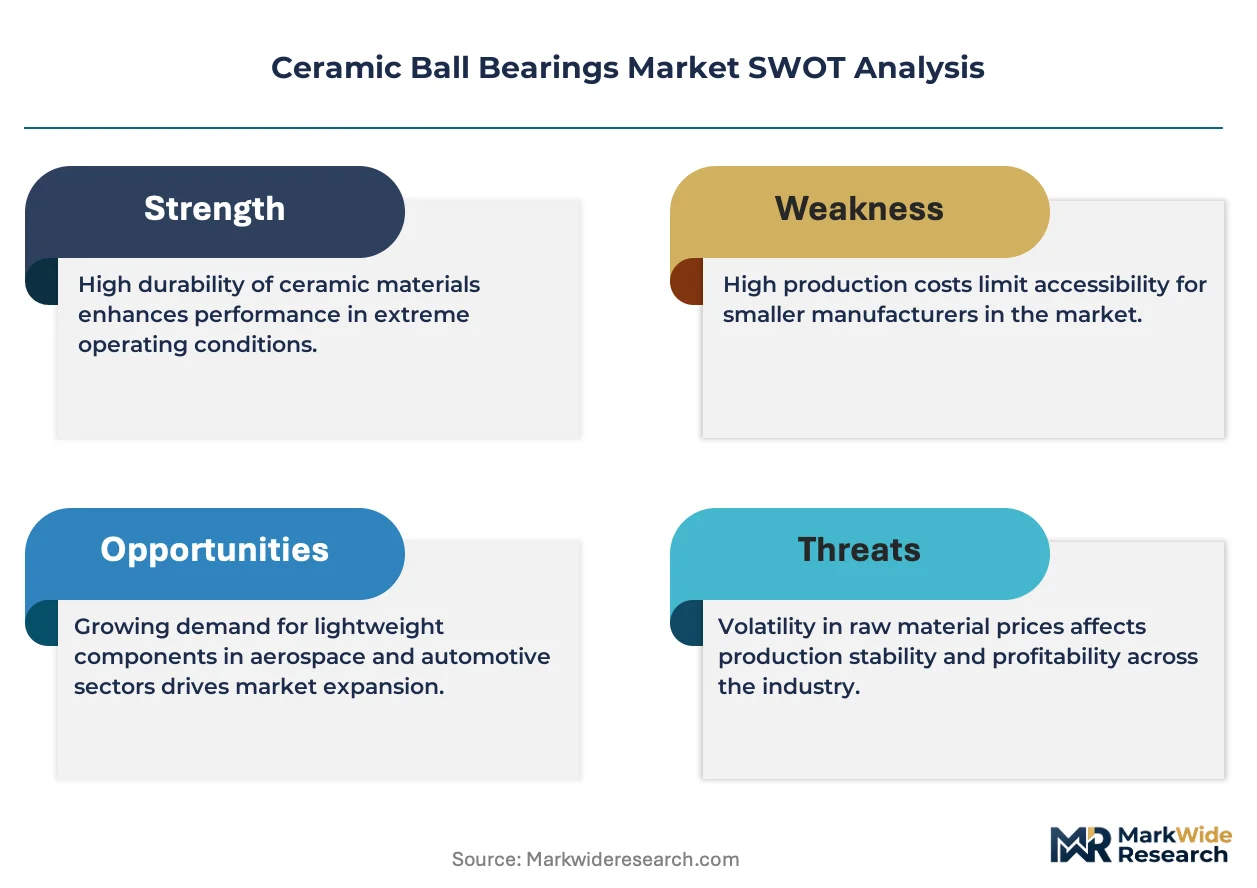
Buyer concentration across the ceramic ball bearings landscape is broadening as aerospace tier-one suppliers consolidate long-term contracts while medical device startups fragment procurement into smaller batch orders. SKF AB leverages its Nordic manufacturing footprint to sustain supply continuity for wind turbine OEMs. CeramTec GmbH anchors European demand through specialized silicon nitride formulations. CoorsTek, Inc. competes on material science depth across aerospace and semiconductor end uses.
Ceramic ball bearings incorporate precision-ground balls fabricated from silicon nitride, zirconia, or alumina ceramics, typically housed within steel or ceramic rings, delivering corrosion resistance and thermal stability above 1,000°C for extreme-duty rotational systems. Hybrid bearings dominate current volume as mature automotive and industrial applications prioritize cost-controlled performance upgrades. Full ceramic bearings represent the fastest-expanding margin pool, particularly in medical devices and semiconductor manufacturing where magnetic impermeability and chemical inertness command premium positioning. Miniature bearings across the size dimension capture concentrated robotics and precision instrument demand as automation densities intensify.
FAA airworthiness directives and EPA emissions frameworks in the United States compel bearing upgrades that withstand higher thermal and mechanical loads in next-generation propulsion systems. REACH and RoHS compliance requirements across Europe restrict traditional lubricants and surface treatments, redirecting R&D toward ceramic-compatible dry-running architectures. Stakeholders must monitor how evolving CSRD disclosure obligations reshape supplier qualification timelines and capital allocation across the value chain.
Market Dynamics
Material substitution away from steel bearings is accelerating as thermal load requirements in next-generation propulsion systems exceed conventional alloy limits. Aerospace manufacturers are consolidating procurement around hybrid ceramic architectures that satisfy FAA airworthiness directives without redesigning entire engine platforms.
Growth Catalysts
- Emissions compliance mandates:EPA and FAA frameworks compel bearing upgrades in high-temperature environments. Jet engine OEMs prioritize ceramic solutions that withstand thermal cycling above 1,000°C.
- Germany's precision engineering clusters:Stuttgart and Dresden anchor specialized silicon nitride supply chains. Medical device manufacturers source miniature bearings from this concentration.
- Silicon nitride formulations:Advanced ceramic powders deliver corrosion resistance and magnetic impermeability. Semiconductor fabrication equipment demands these properties for cleanroom compatibility.
Market Restraints
- Raw material concentration:High-purity silicon nitride powder production concentrates among limited specialty chemical suppliers. Price volatility in ceramic feedstocks compresses margin predictability.
- Technical limitation:Ceramic brittleness under impact loading restricts deployment in heavy shock applications. Steel bearings retain dominance in construction and mining equipment.
- REACH compliance friction:European restrictions on traditional lubricants and surface treatments delay product qualification timelines. Suppliers redirect R&D toward dry-running ceramic architectures.
Strategic Opportunities
- Medical robotics expansion:Surgical automation platforms require miniature ceramic bearings for MRI-compatible precision instruments. Magnetic impermeability commands premium positioning.
- Wind turbine OEM procurement:Nordic manufacturers seek supply continuity for offshore installations. Hybrid bearings reduce maintenance intervals in harsh marine environments.
- CSRD disclosure obligations:EU corporate sustainability reporting requirements reshape supplier qualification criteria. Early compliance positions vendors for tier-one aerospace contracts.
Industry Challenges
- Precision grinding talent scarcity:Ceramic ball fabrication requires specialized metrology and surface finish expertise. Workforce development lags behind capacity expansion plans.
- Multi-standard certification complexity:Simultaneous FAA, EASA, and ISO qualification extends product launch timelines. Testing redundancy consumes engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Ball Bearings Market |
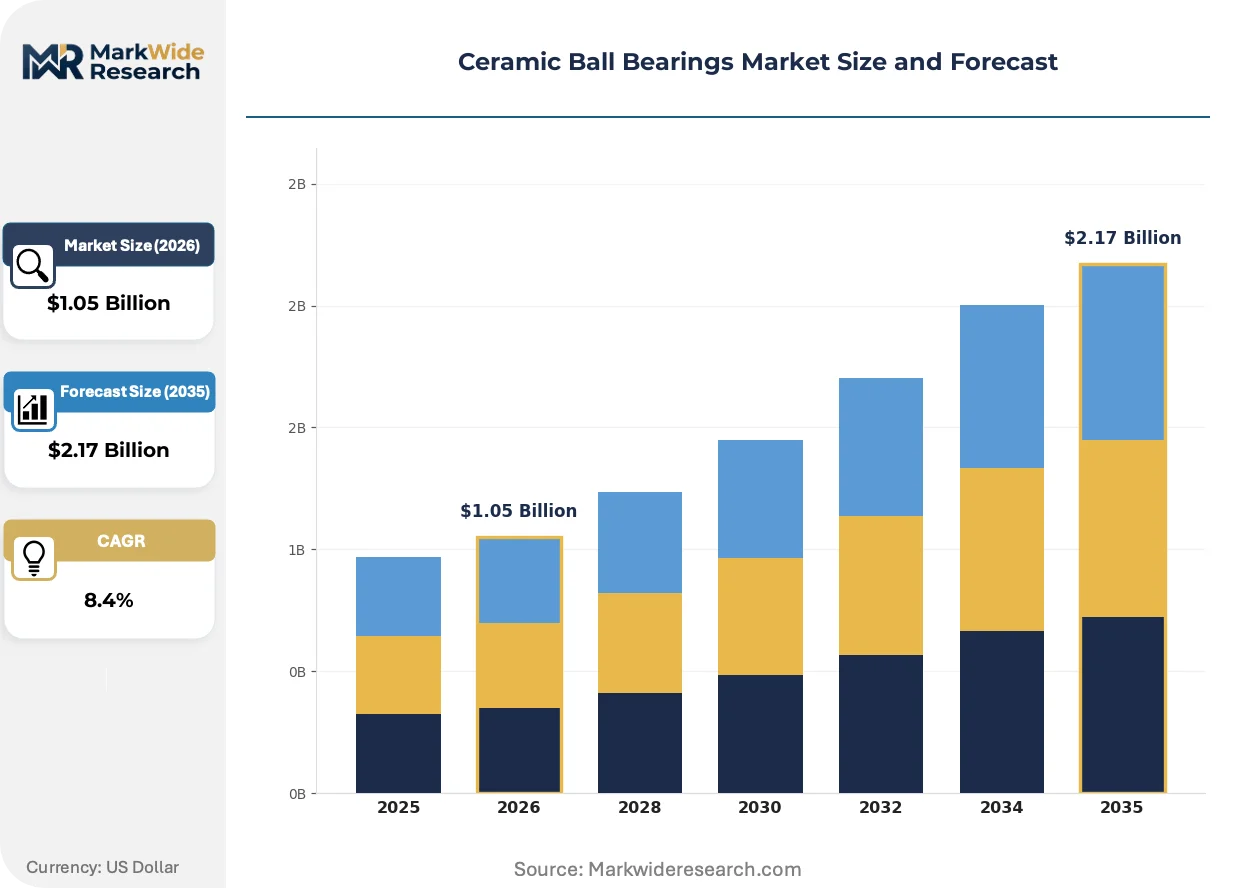
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Bearings, Full Ceramic Bearings, Standard Bearings, Miniature Bearings End User: Aerospace, Automotive, Medical Devices, Electronics Size: Standard Size, Mini Size, Large Size, Customized Size Application: High-Speed Machinery, Robotics, Precision Instruments, Consumer Products |
| Companies Covered | Kyocera Corporation, SKF AB, CeramTec GmbH, NTN Corporation, NSK Ltd., CoorsTek, Inc., Saint-Gobain S.A., Ortech Incorporated, NGK Spark Plug Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Ball Bearings Market Strategic Shifts & Innovations
Digital manufacturing and advanced material characterization are compressing development cycles for ceramic bearing architectures. Suppliers now integrate real-time quality monitoring with predictive performance modeling.
Additive manufacturing of ceramic preforms is integrating near-net-shape fabrication with conventional sintering processes. Aerospace tier-one suppliers adopt these hybrid production routes for prototype-to-production scaling. The technology is integrating design flexibility that compresses lead times for custom bearing geometries.
REACH and RoHS frameworks across Europe are restricting perfluorinated lubricants and hexavalent chromium surface treatments. Ceramic-compatible dry-running designs eliminate dependency on regulated chemistries. Medical device and semiconductor segments are accelerating qualification of unlubricated bearing systems.
Consolidated long-term contracting is displacing spot procurement among wind turbine and aerospace OEMs. Fragmented batch ordering persists among medical device startups seeking design flexibility. Germany and the Nordic region exhibit the strongest concentration of multi-year supply agreements.
Ceramic Ball Bearings Market Segmentation
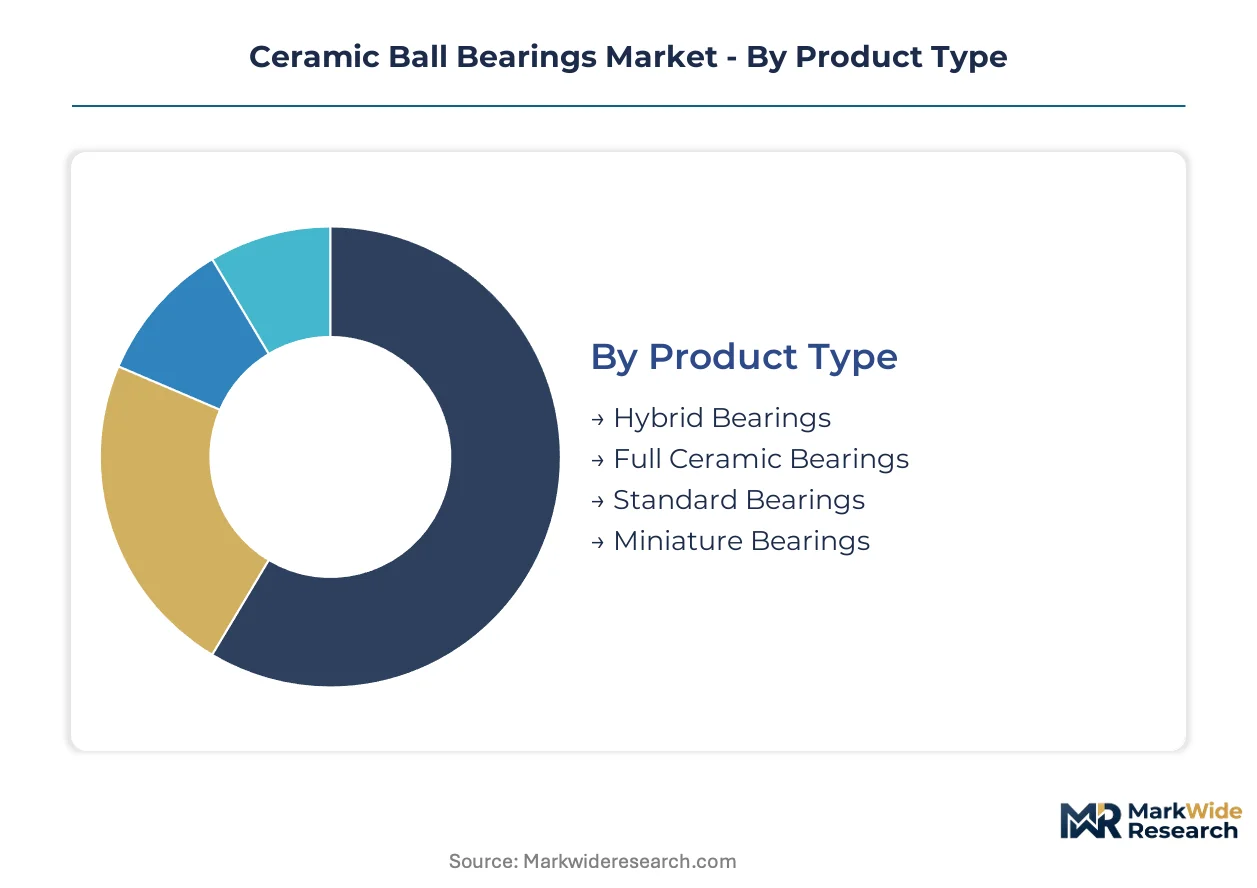
Ceramic ball bearing architectures fragment across material composition, dimensional scale, and duty-cycle intensity. Each segmentation axis carries distinct margin profiles and qualification barriers that reshape vendor positioning across aerospace, medical, and industrial end uses.
Product Type:
Hybrid architectures dominate current shipment volumes while full ceramic systems command the steepest price premiums. Steel-ceramic combinations anchor established automotive and wind turbine applications where cost discipline constrains material selection.
- Hybrid Bearings:Steel rings house precision-ground silicon nitride balls, delivering thermal stability above 1,000°C without full ceramic cost structures. Aerospace OEMs in Germany and the United States consolidate procurement around these architectures to satisfy FAA airworthiness directives while preserving engine platform compatibility.
- Full Ceramic Bearings:Both rings and rolling elements use silicon nitride, zirconia, or alumina ceramics, eliminating magnetic permeability and enabling cleanroom operation. Medical device manufacturers and semiconductor fabrication equipment suppliers absorb premium pricing to gain MRI compatibility and chemical inertness.
- Standard Bearings:Conventional dimensional series serve mature industrial replacement cycles with limited ceramic penetration.
- Miniature Bearings:Sub-10mm bore diameters target surgical robotics and precision instrumentation where space constraints override absolute load capacity.
Today's leader: Hybrid Bearings. Tomorrow's challenger: Full Ceramic Bearings.
End User:
Regulatory intensity and thermal load requirements concentrate demand differently across customer verticals. Aerospace and medical segments drive qualification investments while automotive volume sustains manufacturing scale.
- Aerospace:Jet engine OEMs specify hybrid and full ceramic bearings for turbine sections where thermal cycling exceeds steel alloy limits. EPA emissions frameworks and FAA airworthiness directives compel material upgrades in next-generation propulsion systems.
- Medical Devices:Surgical robotics and diagnostic imaging equipment demand miniature full ceramic bearings with absolute magnetic impermeability. REACH restrictions on traditional lubricants accelerate dry-running ceramic qualification.
- Automotive:High-performance drivetrain and electric vehicle motor applications adopt hybrid bearings for thermal management without full platform redesign.
- Electronics:Semiconductor wafer handling and cleanroom automation utilize ceramic corrosion resistance in chemically aggressive process environments.
Aerospace procurement concentrates multi-year contracts. Medical device demand fragments into design-flexible batch orders.
Size:
Dimensional segmentation maps directly to load capacity requirements and manufacturing process complexity. Miniature fabrication demands specialized grinding expertise that constrains supplier participation.
- Standard Size:ISO dimension series serve industrial machinery and automotive applications with established supply chains and competitive pricing.
- Mini Size:Sub-10mm outer diameters target medical robotics and precision instruments. Stuttgart and Dresden engineering clusters anchor European supply concentration for these specialized geometries.
- Large Size:Wind turbine main shaft and aerospace turbine applications require custom silicon nitride formulations and extended lead times.
- Customized Size:Application-specific geometries command prototype-to-production scaling through additive manufacturing of ceramic preforms.
Standard sizes capture volume. Customized sizes capture margin.
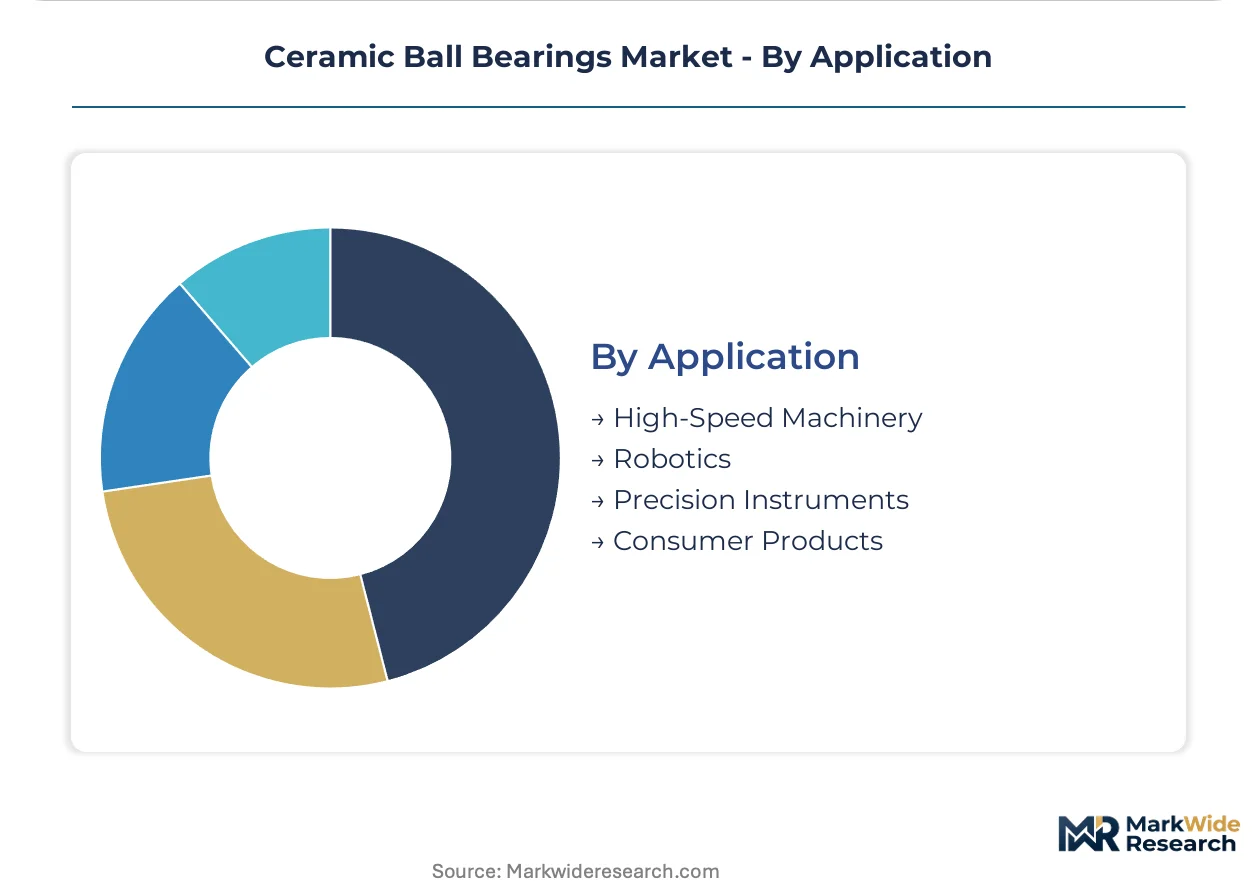
Application:
Rotational speed, precision tolerance, and environmental exposure differentiate application requirements. Each use case imposes distinct certification and performance validation protocols.
- High-Speed Machinery:Spindle applications in machine tools and turbochargers prioritize ceramic density advantages for reduced centrifugal loading at rotational speeds exceeding steel limits.
- Robotics:Articulated joint and end-effector bearings demand miniature full ceramic systems with absolute position repeatability in cleanroom or surgical environments.
- Precision Instruments:Metrology equipment and optical systems utilize thermal stability and dimensional consistency of silicon nitride to maintain calibration integrity.
- Consumer Products:Limited ceramic penetration in cost-sensitive applications, with isolated premium bicycle and sporting equipment niches.
Robotics applications expand fastest. Consumer products remain ceramic's final frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision engineering clusters while the United States drives aerospace procurement consolidation, yet both face tightening emissions frameworks that accelerate ceramic bearing substitution in high-temperature applications.
United States
Jet engine OEMs consolidate long-term hybrid bearing contracts to satisfy FAA airworthiness directives for next-generation propulsion systems. EPA emissions standards compel thermal load upgrades exceeding conventional steel alloy limits. Aerospace manufacturing concentrates in Connecticut and Ohio, where tier-one suppliers anchor specialized silicon nitride procurement networks.
Germany
Stuttgart and Dresden engineering clusters anchor European silicon nitride supply chains for medical device miniature bearings. REACH restrictions on traditional lubricants redirect R&D toward dry-running ceramic architectures. Precision manufacturers in Baden-Württemberg sustain multi-year supply agreements with wind turbine OEMs seeking offshore maintenance reduction.
Japan
Semiconductor fabrication equipment makers source full ceramic bearings for cleanroom magnetic impermeability requirements. METI industrial standards accelerate qualification of advanced ceramic powders for high-speed spindle applications. Nagoya-area automotive suppliers adopt hybrid bearings for electric vehicle thermal management without platform redesign.
China
Wind turbine installation growth drives hybrid bearing demand for harsh marine environment durability. MIIT industrial upgrading programs support domestic ceramic powder production capacity expansion. Yangtze River Delta manufacturing bases integrate precision grinding capabilities for robotics miniature bearing supply.
Sweden
Nordic wind turbine OEMs prioritize supply continuity for offshore installations requiring extended maintenance intervals. National climate targets accelerate renewable energy bearing procurement commitments. Gothenburg-area industrial clusters specialize in hybrid bearing logistics for North Sea and Baltic Sea wind farm deployments.
Ceramic Ball Bearings Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across ceramic bearing architectures, creating a tiered structure where material science depth separates premium positioning from volume manufacturing. The vendor base clusters around three strategic archetypes: integrated ceramic powder producers, precision grinding specialists, and diversified industrial component manufacturers. Dominant competitive moves include strategic partnerships for silicon nitride feedstock security and capacity expansion in miniature bearing fabrication.
Among European specialists, CeramTec GmbH and SKF AB occupy distinct positions within the competitive hierarchy. CeramTec exemplifies the material science archetype through its specialized formulations, while SKF represents diversified industrial scale. Japanese precision manufacturers including NSK Ltd. and NTN Corporation anchor Asia-Pacific supply continuity. Kyocera Corporation sits within the integrated ceramic producer tier, leveraging captive powder capabilities.
| Leading Market Players |
|---|
| Kyocera Corporation |
| SKF AB |
| CeramTec GmbH |
| NTN Corporation |
| NSK Ltd. |
| CoorsTek, Inc. |
| Saint-Gobain S.A. |
| Ortech Incorporated |
| NGK Spark Plug Co., Ltd. |
| Others |
Cost & Logistics Intelligence
EPA emissions mandates and FAA airworthiness directives gate qualified supply access for ceramic bearing vendors, reserving premium-tier pricing power for manufacturers with demonstrated thermal cycling certification above 1,000°C. Buyers without multi-year aerospace procurement relationships face extended qualification timelines that compress their negotiating leverage against incumbent suppliers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard hybrid bearing tiers while premium full ceramic formulations retain margin insulation. Three-tier pricing structure across aerospace-qualified, industrial-grade, and automotive-economy levels separates buyers by certification burden and volume commitment. Pricing pressure stems from silicon nitride powder cost volatility among limited specialty chemical suppliers. Medical device startups exhibit highest price sensitivity due to fragmented batch procurement, whereas semiconductor OEMs absorb premiums for magnetic impermeability.
Supply Chain Analysis
Precision grinding talent scarcity in Germany's Stuttgart cluster and Japan's Nagoya region constrains miniature bearing output expansion despite downstream demand acceleration. Supply concentrates in Germany, Japan, and China for finished bearings, drawing from high-purity silicon nitride powder sources in the United States and Europe. Single-source vulnerability in ceramic feedstock production elevates margin unpredictability. Distribution runs through direct long-term contracting with wind turbine and aerospace OEMs, with spot procurement serving medical device fragment demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic bearing margins expand through silicon nitride powder cost compression and medical device premium-tier absorption of full ceramic pricing. Hybrid architectures sustain volume manufacturing scale while full ceramic systems capture expanding margin pools.
For Market Incumbents: Anchor supply continuity through captive silicon nitride powder partnerships or backward integration into ceramic feedstock production. Defend aerospace tier-one relationships against emerging precision grinding specialists by accelerating FAA-EASA dual certification timelines. Capacity expansion in Germany's Baden-Württemberg region reinforces proximity to Stuttgart engineering clusters. For New Entrants and Emerging Players: Capture surgical robotics miniature bearing demand where MRI compatibility requirements exclude steel-bearing incumbents. Medical device batch procurement offers lowest qualification barriers versus consolidated aerospace contracting. Partner with additive manufacturing ceramic preform specialists to compress custom geometry lead times for design-flexible buyers. For Investors and Strategic Acquirers: Valuations sit cheapest among precision grinding specialists without captive powder supply. Five-to-ten year viability favors integrated ceramic producers with demonstrated cleanroom qualification track records. Monitor FAA airworthiness directive expansion scope as inflection signal for hybrid bearing demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Nitride Powder Backward Integration | Captive feedstock supply insulates margin from specialty chemical price volatility. |
| FAA-EASA Dual Certification Investment | Simultaneous qualification compresses aerospace tier-one supplier onboarding timelines. |
| Additive Manufacturing Preform Partnership | Near-net-shape fabrication enables prototype-to-production scaling for custom geometries. |
| Dry-Running Architecture R&D | REACH-compliant designs eliminate dependency on restricted perfluorinated lubricants. |
| Medical Robotics Miniature Bearing Capacity | MRI-compatible precision instruments command premium positioning in surgical automation. |
Research Approach
Direct dialogue with aerospace procurement directors, medical device R&D leads, wind turbine OEM supply chain managers, and precision grinding operations heads combined with secondary validation from FAA airworthiness filings, EPA emissions compliance databases, ECHA REACH substance restrictions, and customs trade flow records. Bottom-up demand modeling triangulated against top-down industry capacity assessments.
Segment-level volume and value trajectories across the projection horizon reflect product type, end user vertical, dimensional scale, and geographic manufacturing cluster dimensions. CAGRs derive from regression analysis of historical procurement patterns against regulatory mandate implementation schedules. Forecast inputs incorporate silicon nitride powder capacity expansion announcements and aerospace engine platform thermal load specifications.
Feedstock price volatility, regulatory qualification timeline extensions, and precision grinding workforce availability are the dominant revision risks to modeled outputs. Material deviation in ceramic powder supply concentration or FAA directive scope expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Front Forks Market
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
Marine Wheel Bearings Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
Automotive Aftermarket Shock Absorbers Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Vehicle Radiator Market
Vehicle Components
India Automotive Steering System Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Global Tyre Inflators Market