
 United Kingdom Passenger Vehicles Lubricants Market | 2026-2036
United Kingdom Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Passenger Vehicles Lubricants Market Analytics
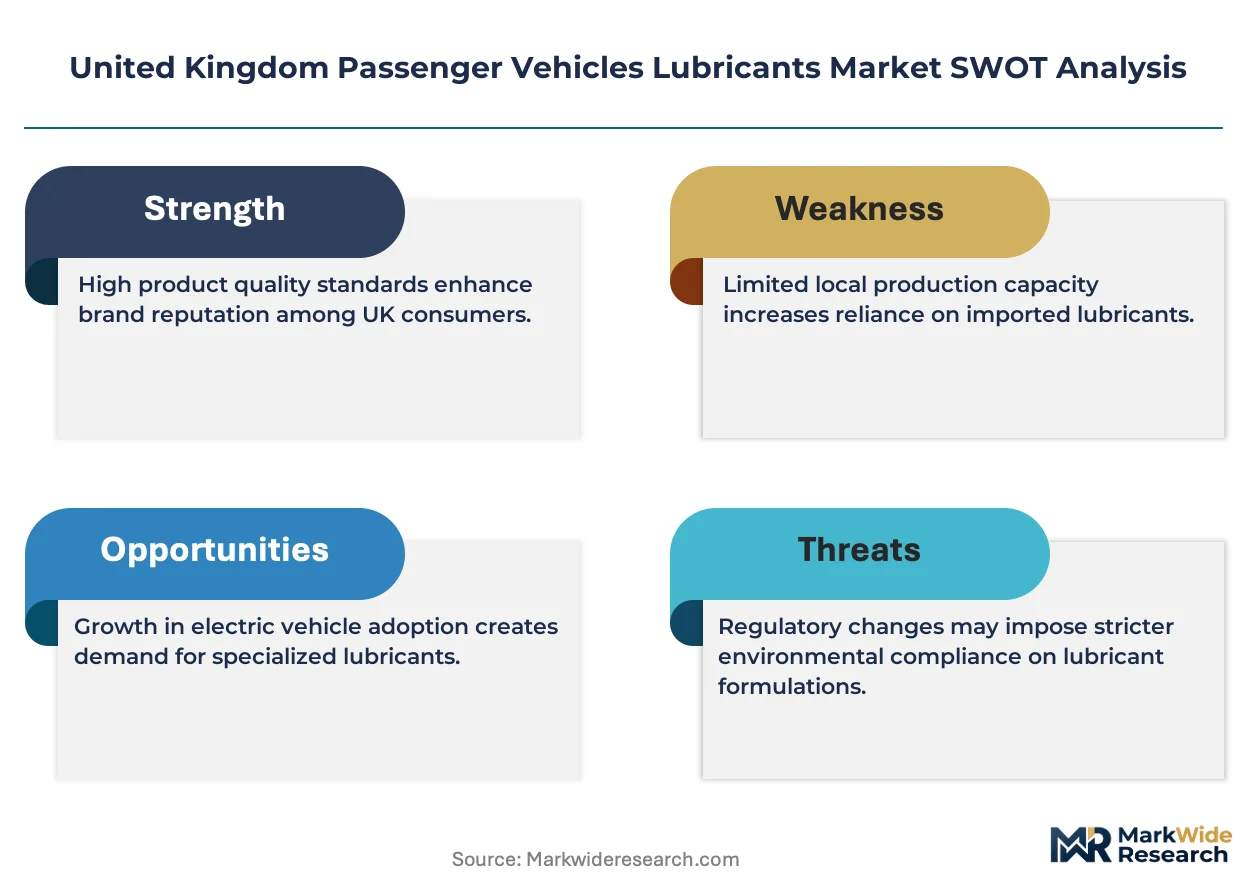
Euro 7 emission standards is rebalancing the cost-of-entry calculus for UK lubricant suppliers, forcing reformulation investments that favor capital-rich participants. BP PLC (Castrol) leverages its Whitchurch blending facility to sustain domestic supply security for OEM fill programs. Shell plc anchors its position through channel control of motorway service station networks. Fuchs Petrolub SE differentiates via specialized high-performance synthetics for premium German marques operating in Britain.
United Kingdom Passenger Vehicles Lubricants encompass refined petroleum-derived or synthetic base stocks compounded with additive packages to reduce friction, dissipate heat, and prevent wear in internal combustion and hybrid powertrains, typically formulated to SAE viscosity grades and ACEA performance categories for temperate maritime climates. Their primary commercial purpose centers on extending engine and driveline service intervals while enabling compliance with manufacturer warranty conditions. Engine oil formulations command the deepest margin pools due to volume density and OEM certification complexity, while synthetic and semi-synthetic categories capture the fastest trajectory as turbocharged downsized engines proliferate across British parc vehicles. Viscosity grades 5W-30 and 0W-20 dominate replacement demand, reflecting manufacturer specifications for cold-start protection in Scotland and northern England.
The Driver and Vehicle Standards Agency enforces MOT testing protocols that indirectly lubricant quality through emission pass-fail thresholds, while the UK's implementation of REACH chemical registration constrains additive chemistry portfolios available to domestic blenders. The Competition and Markets Authority monitors retail fuel and lubricant channel pricing, influencing distribution economics for independent workshop segments. Stakeholders must monitor the pace of zero-emission vehicle mandates and their lubrication-system implications for residual internal combustion service demand.
Market Dynamics
The UK's Euro 7 emission readiness timeline is compressing reformulation cycles, forcing lubricant suppliers to accelerate additive chemistry investments and recertify products ahead of the 2025-2027 regulatory window.
Growth Catalysts
- Fleet electrification hybrids:Hybrid powertrains retain internal combustion lubrication needs while demanding thermally stable formulations. Fleet operators in England's West Midlands automotive cluster are expanding synthetic lubricant adoption to protect turbocharged downsized engines.
- REACH chemical registration:The UK's implementation of REACH constrains additive chemistry portfolios available to domestic blenders, creating compliance-driven demand for pre-registered premium formulations that guarantee supply security.
- Extended drain intervals:Synthetic and semi-synthetic categories capture volume as OEM specifications for 5W-30 and 0W-20 viscosity grades enable longer service intervals, reducing total cost of ownership for commercial vehicle operators.
Market Restraints
- Base oil supply concentration:Group III and PAO synthetic base stocks depend on limited North Sea and Middle Eastern refining capacity, exposing UK blenders to input cost volatility and freight disruptions.
- Zero-emission vehicle mandates:The UK's 2035 new ICE sales prohibition threatens residual lubricant demand, compressing the addressable market window for passenger vehicle engine oils and transmission fluids.
- Additive package complexity:ACEA C-category low-SAPS formulations require expensive friction modifier and ashless dispersant chemistries that strain margin structures for independent blenders without OEM certification scale.
Strategic Opportunities
- Scotland's northern fleet corridor:Cold-start protection specifications for 0W-20 grades are underpenetrated in Scotland's independent workshop segment, creating white space for synthetic-first distribution partnerships.
- Motorway service station channel control:Shell plc's anchoring position demonstrates the value of captive retail fuel and lubricant networks for premium brand exposure to transient high-mileage drivers.
- Hybrid thermal management fluids:Convergence of electrified powertrains with retained ICE components is automating demand for dedicated hybrid lubricants that manage battery proximity heat loads alongside traditional engine protection.
Industry Challenges
- OEM certification timeline compression:Euro 7 readiness requirements are forcing 18-24 month recertification cycles for engine oils, straining R&D bandwidth and testing facility access for mid-tier suppliers.
- Additive chemist scarcity:Formulation expertise in low-SAPS, high-TBN diesel passenger car oils is concentrating at capital-rich participants, creating hiring friction for domestic blenders seeking Euro 7 compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Passenger Vehicles Lubricants Market |
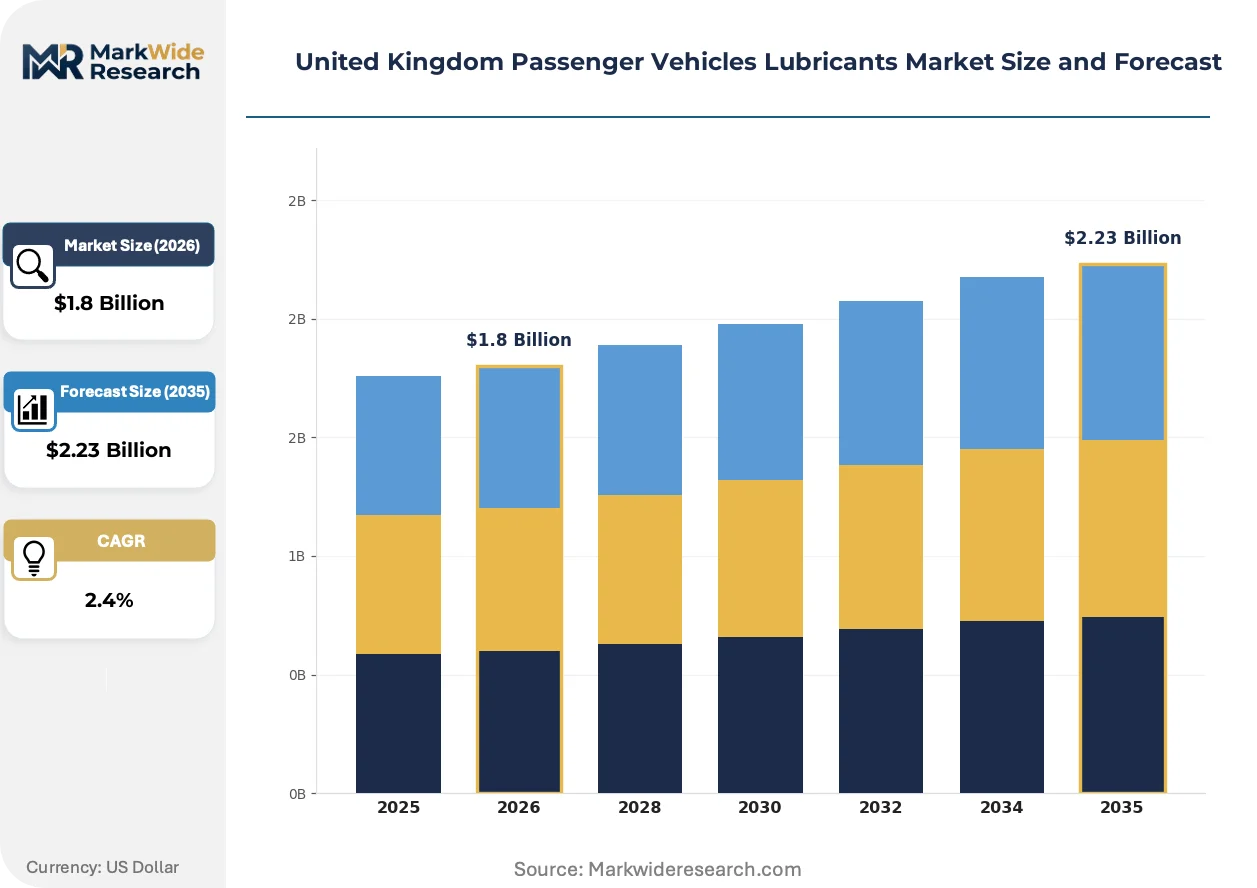
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Gear Oil Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Packaging Type: Bottles, Drums, Bulk Containers, Pails Formulation: Synthetic, Mineral, Semi-Synthetic, Bio-Based |
| Companies Covered | TotalEnergies, Fuchs Petrolub SE, BP PLC (Castrol), Exol Lubricants Limited, Chevron Corporation, ExxonMobil Corporation, Petronas Lubricants International, Morris Lubricants, Shell plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Passenger Vehicles Lubricants Market Evolving Landscape
Reformulation velocity is the defining feature of this market, with suppliers racing to synchronize product pipelines with emission standards, powertrain diversification, and distribution channel consolidation.
Artificial intelligence in tribology testing is automating the screening of friction modifier candidates, compressing formulation development from 36 months to 18 months. Castrol and Fuchs Petrolub are deploying machine learning models to predict additive synergy in ACEA C5/C6 categories. This acceleration is automating competitive pressure on mid-tier blenders lacking computational chemistry infrastructure.
REACH chemical registration constraints are reshaping additive chemistry portfolios available to UK domestic blenders, forcing substitution of boron and sulfur-based friction modifiers with molybdenum dithiocarbamate alternatives. The Competition and Markets Authority monitors retail channel pricing impacts, but compliance costs concentrate in England's independent workshop segment where volume purchasing power is weakest.
Workshop procurement consolidation is compressing distributor margins as large independent chains centralize lubricant buying through direct manufacturer agreements. Scotland and northern England's fragmented garage network still relies on traditional motor factor intermediaries, but digital procurement platforms are penetrating the West Midlands cluster first, displacing relationship-based supply arrangements with price-transparent, specification-matched ordering systems.
United Kingdom Passenger Vehicles Lubricants Market Segmentation
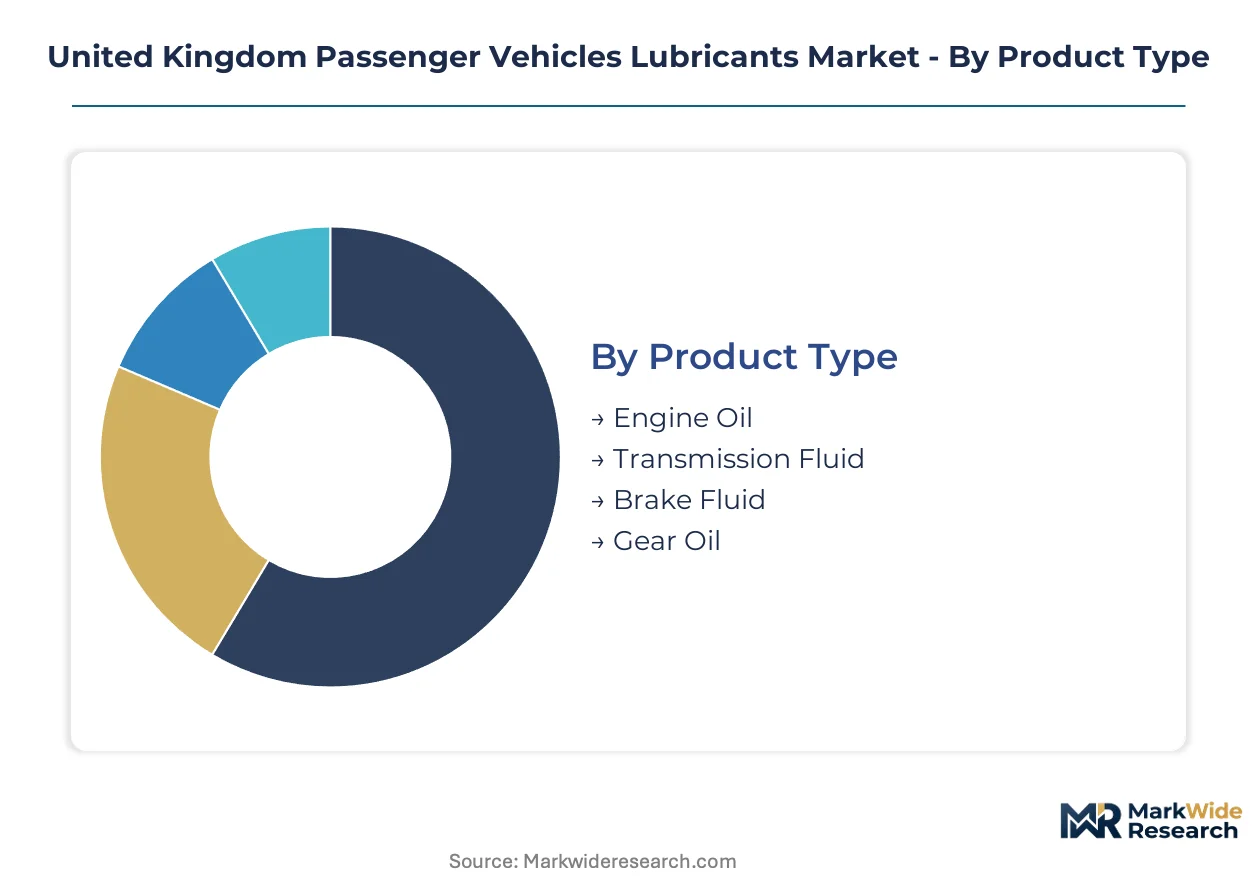
Segmentation in the United Kingdom Passenger Vehicles Lubricants Market reveals how procurement decisions split across technical specifications, operational scale, and regulatory compliance pressures. Understanding these divides exposes where margin concentrates and where suppliers must align formulation investments with buyer purchasing logic.
Product Type:
Workshop procurement decisions pivot on service interval economics and OEM warranty compliance, with each fluid category carrying distinct certification burdens and margin structures.
- Engine Oil:Formulated from Group III base stocks or PAO synthetics with ACEA C-category additive packages for low-SAPS emission system protection. Demand concentrates in England's West Midlands automotive cluster where fleet operators specify extended drain intervals for turbocharged downsized powertrains. Euro 7 readiness timelines are compressing reformulation cycles for this category.
- Transmission Fluid:Specialized friction-modified formulations for dual-clutch and continuously variable transmissions requiring OEM-specific approvals. Scotland's northern fleet corridor shows underpenetration in independent workshops, creating distribution white space for synthetic-first suppliers.
- Brake Fluid:Glycol-ether or silicone-based hydraulic fluids meeting DOT 4 and DOT 5.1 specifications for ABS and ESP system compatibility.
- Gear Oil:Hypoid gear lubricants with extreme pressure additives for differential and manual transmission applications in high-torque delivery vehicles.
Engine oil leads on scale; transmission fluid leads on momentum.
Viscosity Grade:
Cold-start protection requirements and fuel economy regulations drive viscosity selection, with northern UK climates and OEM CAFE-equivalent targets pulling specifications in competing directions.
- 0W-20:Ultra-low viscosity synthetic formulations enabling cold-cranking performance below minus 35 degrees Celsius. Scotland's independent workshop segment remains underpenetrated for this grade despite manufacturer specifications for hybrid thermal management.
- 5W-30:The dominant replacement demand grade balancing cold-flow and high-temperature shear stability. Fleet operators across England's West Midlands specify this viscosity for service interval extension.
- 10W-40:Semi-synthetic workhorse grade for older vehicle parc and high-mileage engines in cost-sensitive maintenance segments.
- 15W-50:High-viscosity protection for performance applications and heavily loaded engines in commercial passenger vehicle derivatives.
5W-30 dominates volume throughput; 0W-20 is climbing the fastest on hybrid powertrain proliferation.
Packaging Type:
Procurement scale and workshop infrastructure determine packaging economics, with digital platforms now penetrating traditional motor factor relationships in concentrated automotive clusters.
- Bottles:One-liter and five-liter retail formats for DIY consumers and small independent garages with limited storage capacity. These formats face margin pressure from supermarket and online channel price transparency.
- Drums:Two-hundred-liter containers for high-volume fleet maintenance depots and quick-lube chains with centralized lubricant storage systems.
- Bulk Containers:Intermediate bulk containers and tanker deliveries for OEM fill programs and large distributor blending operations.
- Pails:Twenty-liter pails balancing portability with volume pricing for mid-sized workshops in fragmented northern England garage networks.
Drums lead on commercial volume; bottles lead on channel accessibility.
Formulation:
REACH chemical registration constraints and Euro 7 additive chemistry requirements are reshaping the cost-of-entry calculus across formulation tiers, favoring capital-rich participants with pre-registered premium portfolios.
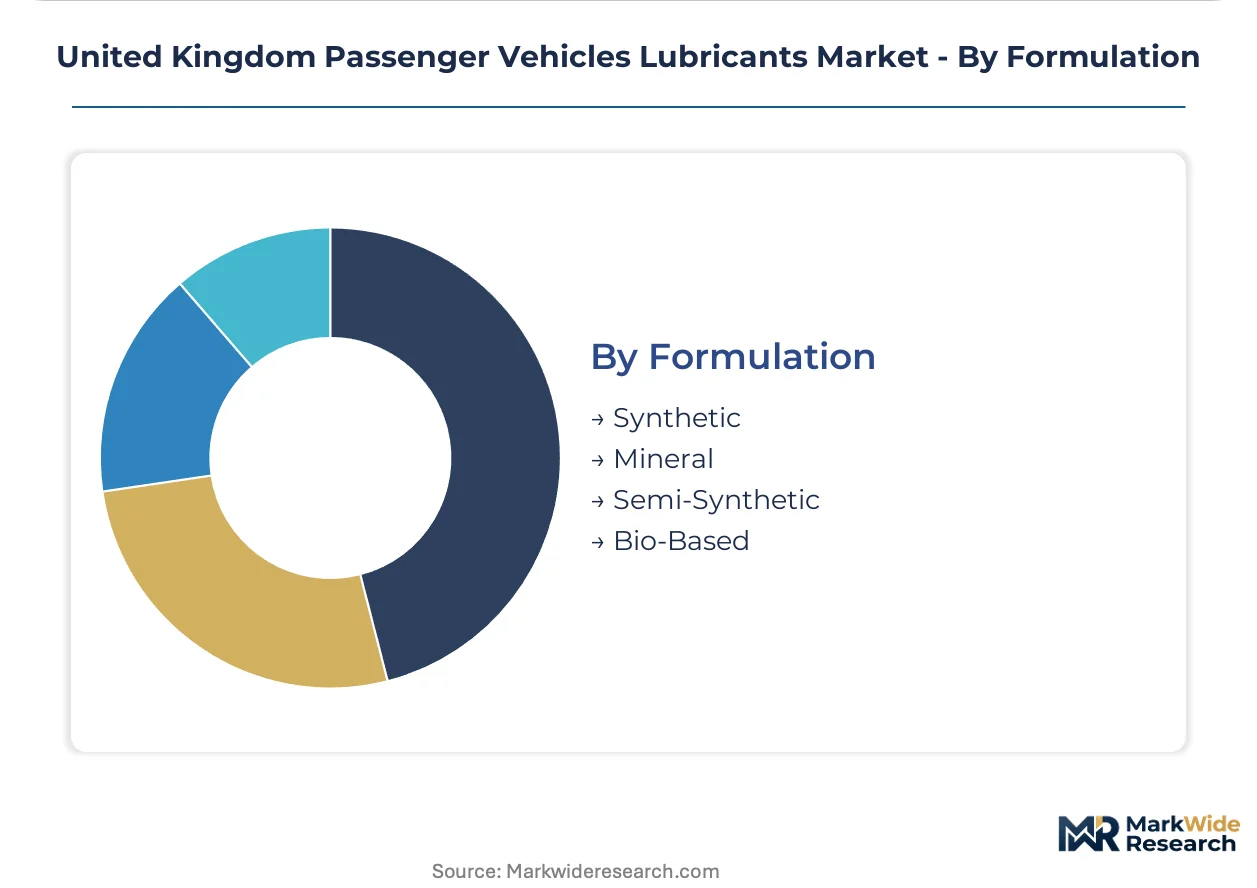
- Synthetic:Group III, PAO, and ester-based formulations delivering thermal stability for turbocharged engines and extended drain intervals. Fleet operators in England's West Midlands automotive cluster are expanding adoption to protect downsized powertrains.
- Mineral:Solvent-refined Group I base stocks for price-sensitive service segments and older vehicle parc with less demanding OEM specifications.
- Semi-Synthetic:Blended formulations capturing volume from workshops balancing cost and performance for mainstream passenger vehicle maintenance.
- Bio-Based:Vegetable oil-derived base stocks with biodegradable additive packages for environmentally sensitive fleet procurement policies and municipal vehicle contracts.
Synthetic leads on margin capture; bio-based is gaining share fastest on sustainability procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized lubricant formulation talent clusters in England's West Midlands automotive corridor, anchoring technical service capabilities for fleet operators and OEM fill programs across the British Isles.
England
Fleet operators in the West Midlands automotive cluster specify extended drain interval synthetics for turbocharged downsized engines. The Driver and Vehicle Standards Agency enforces MOT emission pass-fail thresholds that indirectly validate lubricant quality specifications. Birmingham and Coventry host concentrated blending operations serving domestic OEM programs and aftermarket distribution networks.
Scotland
Cold-start protection requirements for 0W-20 viscosity grades remain underpenetrated in Scotland's independent workshop segment. REACH chemical registration constraints limit additive chemistry portfolios available to domestic blenders operating north of the border. Aberdeen and Glasgow maintain fragmented garage networks that still rely on traditional motor factor intermediaries rather than digital procurement platforms.
Wales
Industrial vehicle derivatives in South Wales generate steady demand for high-viscosity gear oils and hydraulic fluids. The Competition and Markets Authority monitors retail channel pricing across Welsh motorway service stations and independent workshops. Cardiff and Newport serve as distribution nodes for synthetic formulations moving west from English blending facilities.
Northern Ireland
Cross-border supply chain configurations expose Northern Irish distributors to freight disruptions from limited North Sea base oil refining capacity. Local workshops face compressed margins on ACEA C-category low-SAPS formulations requiring expensive friction modifier chemistries. Belfast anchors procurement consolidation as larger independent chains centralize lubricant buying through direct manufacturer agreements.
United Kingdom Passenger Vehicles Lubricants Market Competitive Landscape
The competitive structure tilts toward integrated petroleum majors with captive base oil supply and established OEM certification relationships. Three tiers have crystallized: capital-rich multinationals with full additive chemistry portfolios, mid-sized specialists concentrated in high-performance synthetics, and regional blenders serving price-sensitive service segments. Strategic moves center on motorway service station channel control and accelerated Euro 7 reformulation timelines compressing R&D bandwidth.
Among petroleum majors, BP PLC (Castrol), Shell plc, and Fuchs Petrolub SE exemplify divergent positioning archetypes. Castrol leverages its Whitchurch blending facility to sustain domestic supply security for OEM fill programs. Shell anchors market presence through captive retail fuel and lubricant networks at motorway service stations. Fuchs occupies a specialist position via high-performance synthetic formulations targeting premium marque requirements. These three represent distinct competitive vectors: manufacturing scale, distribution control, and technical specialization.
| Leading Market Players |
|---|
| TotalEnergies |
| Fuchs Petrolub SE |
| BP PLC (Castrol) |
| Exol Lubricants Limited |
| Chevron Corporation |
| ExxonMobil Corporation |
| Petronas Lubricants International |
| Morris Lubricants |
| Shell plc |
| Others |
Value Network & Pricing Analysis
Captive blending capacity at Whitchurch anchors BP PLC's domestic supply security while simultaneously underwriting premium pricing power for OEM fill programs against independent workshop segments. This integration pattern concentrates margin capture with capital-rich multinationals that control both base stock sourcing and certification relationships.
Pricing Analysis
The bundled-vs-unbundled service split separates motorway service station networks from traditional motor factor channels. Three-tier pricing structure across premium, standard, and economy levels tracks ACEA certification grade and volume scale, with fleet operators in England's West Midlands commanding favorable contract terms. Cost compression in the independent workshop segment intensifies because REACH compliance costs concentrate where purchasing power is weakest. DIY consumers at supermarket channels exhibit highest price sensitivity; OEM-certified synthetics for premium marques show lowest.
Supply Chain Analysis
Regional distribution centers in Birmingham and Coventry operate hub-and-spoke patterns feeding Scotland's fragmented garage network and Northern Ireland's cross-border configurations. Base oil sourcing draws from North Sea refining capacity and Middle Eastern Group III/PAO production, with additive packages resting on pre-registered REACH portfolios. Single-source vulnerability concentrates in specialized friction modifier chemistries for ACEA C-category formulations. Distribution runs through motorway service station captive networks and direct manufacturer agreements with consolidated workshop chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scotland's underpenetrated 0W-20 segment against England's West Midlands saturation creates a geographic-arbitrage play for synthetic-first suppliers exploiting the cold-start specification differential. The REACH registration cost burden tilts northward, compressing independent blender margins where procurement consolidation lags.
For Market Incumbents: To counter zero-emission vehicle mandates compressing residual ICE lubricant demand, Castrol and Shell should deepen backward integration into additive chemistry portfolios and extend channel control through digital procurement platform partnerships with consolidated workshop chains. For New Entrants and Emerging Players: Scotland's independent workshop segment represents the most penetrable white-space target, with Aberdeen and Glasgow garages still reliant on traditional motor factor intermediaries. A synthetic-first distribution partnership model bypassing established English blending facilities offers viable go-to-market positioning. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier blenders with REACH-registered portfolios because Euro 7 recertification timelines are straining R&D bandwidth and testing facility access. Long-term viability hinges on hybrid thermal management fluid capabilities. Watch fleet electrification hybrid penetration rates as the inflection indicator for residual ICE lubricant demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Chemistry | REACH pre-registration portfolios guarantee supply security for domestic blenders facing Euro 7 deadlines. |
| Digital Procurement Platform Launch | Price-transparent specification-matched ordering displaces relationship-based motor factor arrangements in the West Midlands. |
| Hybrid Thermal Management Fluid Development | Battery proximity heat load formulations capture electrified powertrain lubrication needs retained alongside ICE components. |
| Motorway Service Station Channel Expansion | Captive retail fuel and lubricant networks deliver premium brand exposure to transient high-mileage driver segments. |
| Scotland Distribution Partnership | 0W-20 synthetic-first positioning addresses underpenetrated cold-start protection specifications in fragmented northern garage networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant blenders, fleet procurement managers, OEM platform engineers, and aftermarket distributors with secondary validation against customs records, ACC industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up volume triangulation across viscosity grades and formulation tiers was cross-checked against top-down market sizing from petroleum major disclosures.
Historical reference periods anchored the projection horizon to established SAE viscosity adoption curves and ACEA specification transition timelines. Segmentation modeling spanned product type, viscosity grade, packaging format, formulation tier, and regional procurement cluster. CAGRs were derived from trend extrapolation adjusted for regulatory milestone impacts. Forecast inputs incorporated Euro 7 implementation pacing and hybrid powertrain penetration assumptions.
Underlying measurement precision varies by segment; synthetic formulations and fleet channel volumes carry tighter precision than bio-based categories and DIY retail estimates. Forecasts reflect documented assumptions around emission standard timelines and base oil supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Road Marking Machine Market
Automotive Parts
Wiper Systems Market
Automotive Parts
Global Passenger Vehicles Lubricants Market
Automotive Parts
Insert Drive for Torque Wrench Market
Automotive Parts
Cheetah Friction Reduction Technologies Market
Automotive Parts
Automotive Key Blanks Market
Automotive Parts
Undercarriage Systems Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Automotive Fuel Rail Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
Tow Bar Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
Automotive Brake Wheel Cylinder Market