
 Automotive Aftermarket Shock Absorbers Market | 2026-2036
Automotive Aftermarket Shock Absorbers Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Aftermarket Shock Absorbers Market Insights
The EU Green Deal is repositioning aftermarket shock absorber procurement toward lower-emission, longer-life damping technologies. KYB Corporation leverages its mono-tube manufacturing scale to serve performance-oriented repair shops across Japan and Europe. Tenneco Inc. anchors its aftermarket position through Monroe's brand strength in North American retail channels. ZF Friedrichshafen AG competes on integrated chassis system expertise that extends from OE supply into replacement demand.
Automotive aftermarket shock absorbers are hydraulic or gas-charged damping devices, typically specifying stroke lengths of 100–300 mm and operating pressures up to 20 bar, that dissipate kinetic energy from suspension movement to maintain tire contact and vehicle stability. Their primary commercial purpose is restoring or enhancing ride control in vehicles beyond original equipment service life. Gas shock absorbers dominate volume in mature replacement markets where durability expectations drive premium selection, while coil-over shock absorbers capture margin pools in the performance tuning segment where adjustability commands price premiums. Distribution channel dynamics reveal offline retail and wholesalers still control the bulk of transaction volume, though online retail is gaining share among DIY customers seeking direct-fit compatibility tools.
NHTSA safety standards and EPA material compliance requirements shape product certification and market access for suppliers serving the United States. ECE R30 and REACH chemical restrictions govern European aftermarket entry, while China's GB standards and MIIT vehicle inspection protocols dictate replacement intervals in that market. Stakeholders must monitor how regulatory divergence across these three jurisdictions affects inventory complexity and certification costs.
Market Dynamics
Fleet operators are compressing replacement cycles for commercial vehicle damping systems as stricter EU F-Gas Regulation and analogous environmental frameworks mandate upgraded inspection protocols. This regulatory pressure is reshaping procurement patterns across repair networks and independent service channels.
Growth Catalysts
- EU F-Gas Regulation:Mandates for lower-emission damping technologies accelerate upgrade cycles among commercial fleets operating across Germany, France, and Italy.
- Aging vehicle parc:Extended vehicle lifespans in the United States and China sustain replacement demand for hydraulic and gas-charged shock absorbers beyond original equipment service intervals.
- Performance tuning culture:Coil-over and adjustable damping systems capture premium margin pools in Japan and Germany where enthusiast segments prioritize ride customization.
Market Restraints
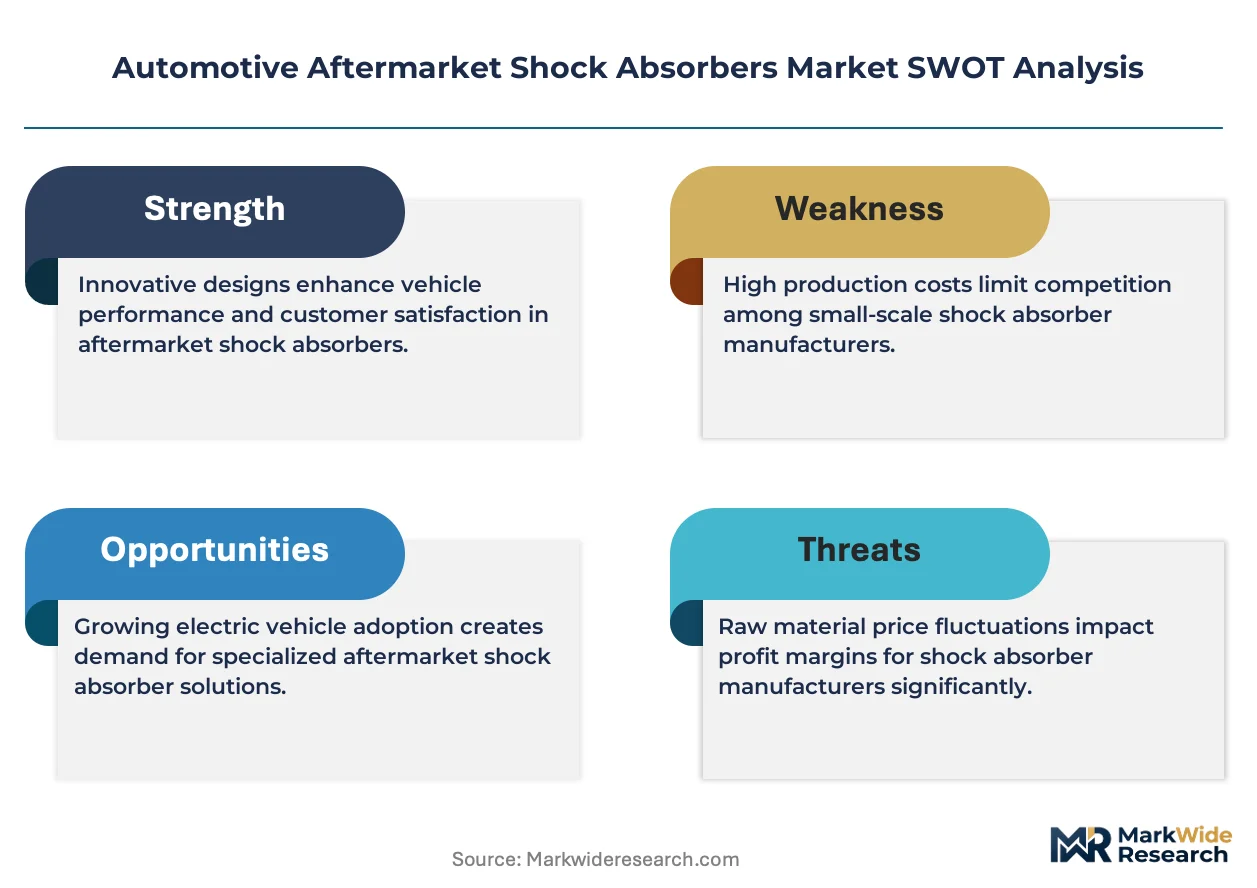
- Steel and rubber input volatility:Raw material price swings compress margin stability for manufacturers dependent on commodity-grade piston rods and seal compounds.
- Supply concentration in East Asian forging:Dependence on concentrated precision machining capacity creates vulnerability to regional logistics disruptions.
- REACH chemical restrictions:Compliance costs for hydraulic fluid formulations and surface treatments limit product line flexibility for suppliers serving European aftermarket channels.
Strategic Opportunities
- India commercial vehicle aftermarket:Underpenetrated replacement infrastructure for heavy-duty damping systems offers expansion potential as Bharat Stage VI compliance raises vehicle complexity.
- Online direct-fit compatibility tools:Digital channels bypass traditional wholesale layers, capturing DIY customer segments seeking VIN-matched product selection.
- EU Green Deal procurement incentives:Public fleet tenders increasingly specify lifecycle emission metrics, favoring suppliers with verified durability testing and circular material content.
Industry Challenges
- Certification timeline compression:Divergent NHTSA, ECE R30, and GB standard testing protocols extend product validation cycles for multi-region suppliers.
- Integration complexity with active suspension:Electromechanical damping systems require specialized diagnostic equipment that independent repair shops rarely stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Aftermarket Shock Absorbers Market |
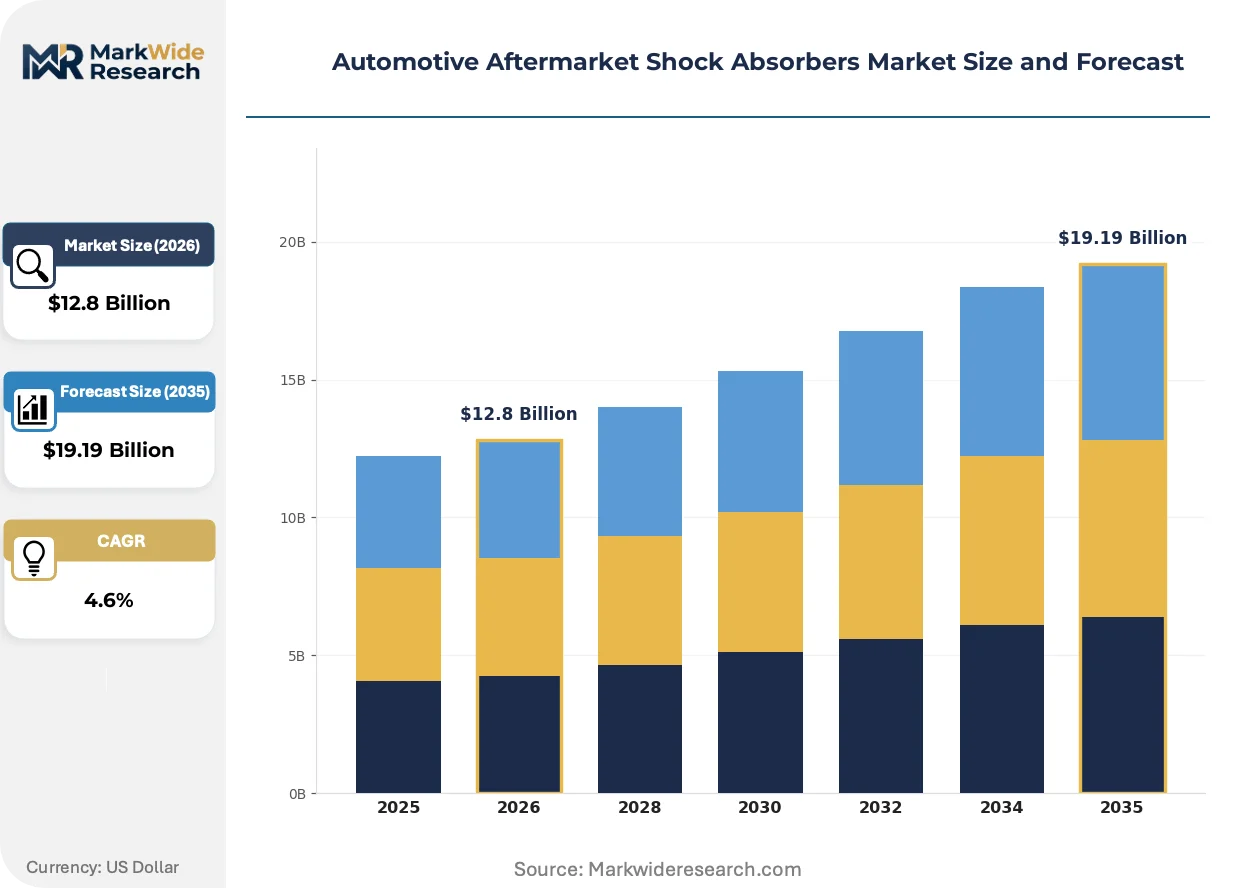
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Shock Absorbers, Twin-Tube Shock Absorbers, Mono-Tube Shock Absorbers, Coil-Over Shock Absorbers Vehicle Type: SUVs, Sedans, Trucks, Vans Distribution Channel: Online Retail, Offline Retail, Wholesalers, OEM Suppliers End User: Do-It-Yourself (DIY) Customers, Repair Shops, Fleet Owners, Automotive Workshops |
| Companies Covered | Hitachi Astemo Ltd., Bilstein, KYB Corporation, Gabriel India Limited, Fox Factory Holding Corp., Tenneco Inc., Monroe, Koni BV, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Aftermarket Shock Absorbers Market Trends and Innovations
Electrification of chassis systems and digital distribution platforms are actively reshaping how damping technologies reach end-users. Three converging developments are restructuring competitive positioning across the value chain.
Mono-tube gas shock technology is expanding into mainstream replacement channels previously dominated by twin-tube designs. Independent repair shops in Germany and Japan are adopting these units for their superior heat dissipation and extended service intervals. The technology is expanding into fleet maintenance contracts where total cost of ownership calculations now override upfront part pricing.
REACH chemical restrictions and EPA material compliance requirements are forcing reformulation of hydraulic fluids and seal elastomers. Suppliers serving both jurisdictions must maintain dual inventory streams or absorb certification redundancy costs. European aftermarket distributors report extended lead times for products awaiting updated safety data sheet approvals.
DIY buyers are migrating toward online retail platforms equipped with direct-fit compatibility verification tools. This channel compression disintermediates traditional wholesale jobbers who previously controlled technical specification access. The shift is most visible in United States and Australian markets where consumer comfort with VIN-based parts lookup exceeds other geographies.
Automotive Aftermarket Shock Absorbers Market Segmentation
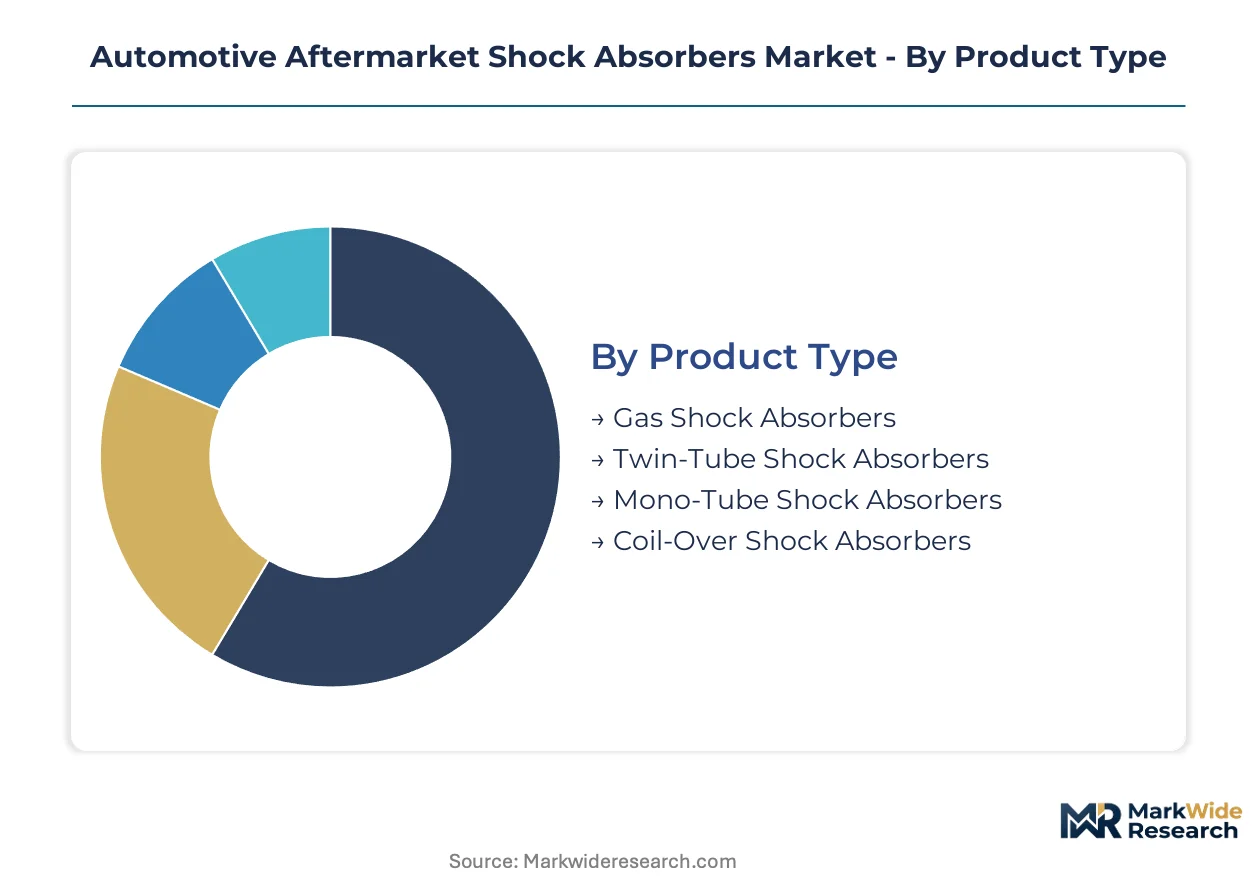
Shock absorber segmentation reveals how capital allocation, technical specifications, and channel economics split replacement demand across distinct buyer profiles. Understanding these divides helps suppliers align forging capacity, inventory depth, and certification investments with where margin pools actually concentrate.
Product Type:
Capital intensity varies sharply across damping architectures, with precision machining requirements and thermal management complexity driving facility investment tiers.
- Gas Shock Absorbers:Nitrogen-charged single or dual-chamber designs operating at 15–20 bar pressures deliver superior fade resistance under sustained loads. Fleet operators in Germany and the United States specify these units for commercial vehicle contracts where total cost of ownership calculations override upfront part pricing, though seal compound reformulation under REACH and EPA rules extends certification timelines.
- Mono-Tube Shock Absorbers:Single-piston designs with larger oil capacity and better heat dissipation command premium positioning in performance-oriented channels. Japanese and German repair shops adopt these for enthusiast vehicles where adjustability and extended service intervals justify price premiums, yet the specialized forging equipment required limits supplier entry.
- Twin-Tube Shock Absorbers:Concentric cylinder construction dominates economy replacement tiers with lower manufacturing complexity.
- Coil-Over Shock Absorbers:Integrated spring-damper assemblies target tuning segments requiring ride height customization.
Most installed capacity flows through Gas Shock Absorbers. Expansion is steepest in Mono-Tube Shock Absorbers.
Vehicle Type:
Application severity and duty cycle intensity determine replacement frequency and specification grade across passenger and commercial categories.
- Trucks:Heavy-duty leaf spring and air suspension systems in commercial configurations impose the harshest damping loads, with axle ratings exceeding 10 tons driving accelerated wear cycles. Fleet maintenance contracts in the United States and China concentrate demand for reinforced piston rods and high-temperature seal packages, though steel input volatility compresses margin stability for suppliers serving this segment.
- SUVs:Higher center-of-gravity vehicles with independent or solid rear axle configurations require specialized valving profiles to manage body roll. Aftermarket volume in Germany and Australia clusters around all-terrain and towing specifications where load-leveling shocks command price premiums, yet integration complexity with electronic stability systems challenges independent repair shop capabilities.
- Sedans:Passenger car damping systems emphasize ride comfort over durability, with lighter duty cycles extending replacement intervals.
- Vans:Commercial delivery configurations split between light-duty passenger variants and heavy cargo applications with divergent specification needs.
Trucks absorb the highest per-vehicle damping expenditure. SUVs are climbing the fastest as performance tuning cultures deepen.
Distribution Channel:
Channel selection determines margin capture, technical support obligations, and inventory velocity for suppliers navigating wholesale compression.
- Offline Retail:Brick-and-mortar jobbers and parts stores maintain immediate availability for emergency repairs, with counter staff providing fitment guidance that reduces return rates. United States and Canadian markets retain strong transaction volume through this channel, though real estate and labor costs elevate breakeven thresholds for regional distributors.
- Online Retail:Digital platforms with VIN-matched compatibility tools bypass traditional wholesale layers, capturing DIY segments in Australia and the United States where consumer technical confidence exceeds other geographies.
- Wholesalers:Traditional jobbers control bulk volume to independent repair networks through established credit terms and route delivery.
- OEM Suppliers:Authorized dealer channels service warranty extensions and brand-loyal replacement demand with genuine parts positioning.
Wholesalers still move the largest transaction volumes. Online Retail is expanding most quickly as compatibility verification tools mature.
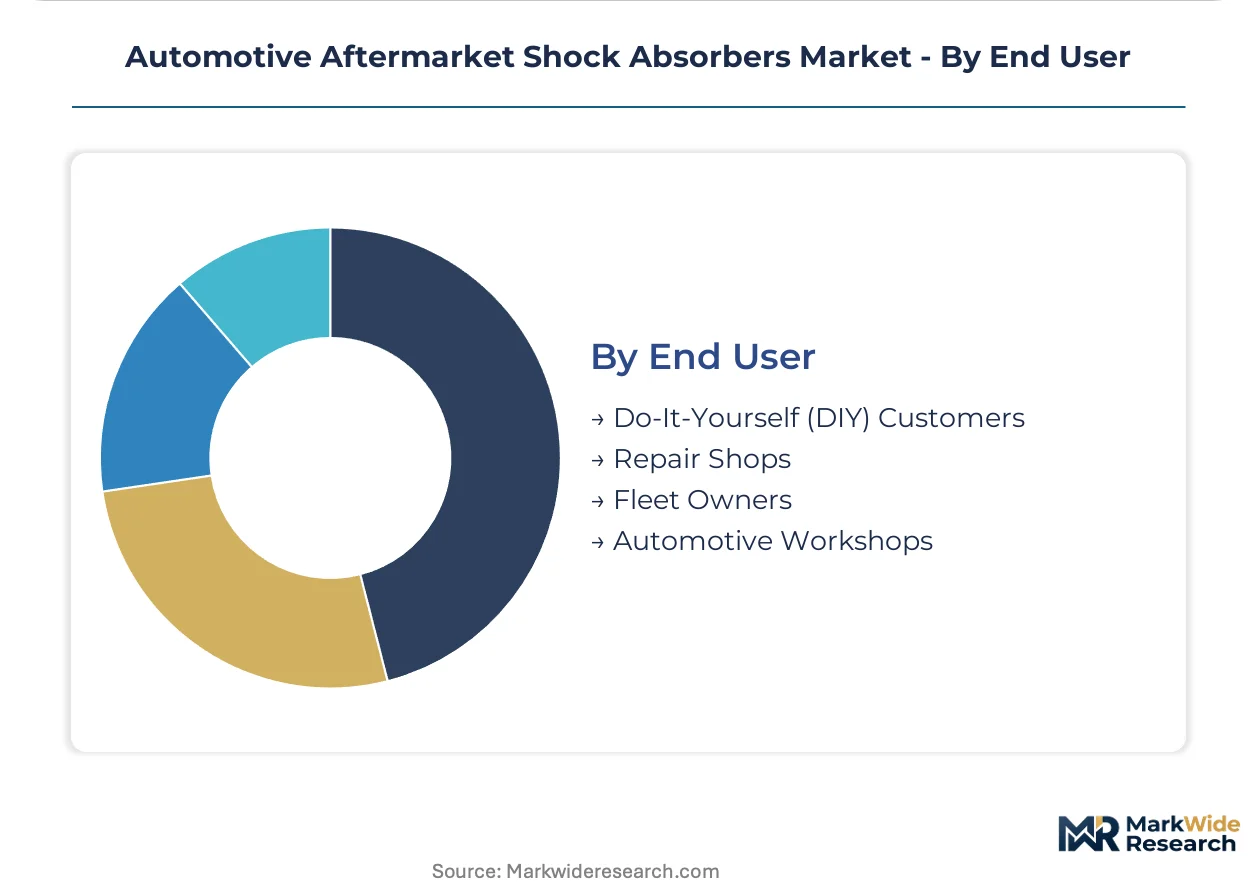
End User:
Technical sophistication and purchase authority split procurement patterns between self-directed consumers and institutional buyers.
- Fleet Owners:Centralized purchasing for commercial vehicle pools leverages scale negotiations and lifecycle cost modeling, with documented maintenance histories enabling predictive replacement scheduling. EU F-Gas Regulation compliance mandates in Germany, France, and Italy accelerate upgrade cycles for operators seeking tender eligibility, though diagnostic equipment standardization across mixed fleets strains capital budgets.
- Repair Shops:Independent and franchise service centers balance part quality against warranty exposure, with labor rates influencing markup tolerance on premium damping technologies.
- Do-It-Yourself (DIY) Customers:Self-installer segments prioritize direct-fit compatibility and video installation support over technical consultation.
- Automotive Workshops:Specialized suspension tuners and restoration shops command niche expertise premiums for custom valving and classic vehicle applications.
Repair Shops represent the deepest installed relationships. Fleet Owners are gaining share fastest as environmental mandates reshape procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized suspension engineers cluster around Stuttgart, Detroit, and Shanghai, anchoring regional aftermarket innovation networks. These workforce concentrations shape procurement patterns and technical specification standards across their respective markets.
United States
Commercial fleet operators in Michigan and Ohio compress replacement cycles for heavy-duty damping systems. NHTSA safety standards mandate upgraded inspection protocols for interstate carriers. The Detroit-Warren corridor hosts dense networks of independent repair shops sourcing gas-charged units for pickup trucks and SUVs.
Germany
Performance tuning workshops in Bavaria and Baden-Württemberg drive premium demand for adjustable mono-tube configurations. EU F-Gas Regulation compliance requirements accelerate upgrade schedules for commercial vehicle operators seeking public tender eligibility. Stuttgart's automotive supplier ecosystem supplies specialized valving expertise to regional aftermarket channels.
China
Aging commercial vehicle fleets in Shandong and Hebei provinces sustain replacement volume for hydraulic damping systems. MIIT vehicle inspection protocols dictate mandatory replacement intervals for trucks operating under GB standards. The Yangtze River Delta manufacturing belt produces precision-forged piston components for domestic aftermarket distributors.
Japan
Enthusiast segments in Kanto and Kansai regions prioritize coil-over assemblies with ride-height adjustability. METI industrial standards govern material certification for seal compounds and hydraulic fluids. Osaka-based tuning shops source mono-tube units from domestic suppliers with verified heat dissipation testing.
India
Bharat Stage VI compliance raises vehicle complexity in Maharashtra and Gujarat, expanding aftermarket infrastructure needs for commercial damping systems. The country's national automotive regulator enforces emission-linked inspection protocols that accelerate component replacement. Pune's industrial corridor attracts forging investments serving domestic heavy-duty aftermarket demand.
Automotive Aftermarket Shock Absorbers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the aftermarket shock absorber landscape. The vendor base splits between integrated chassis system suppliers and specialized damping component fabricators. Three archetypes dominate: mono-tube technology specialists, twin-tube volume manufacturers, and performance tuning equipment providers. Capacity expansion and portfolio diversification represent the dominant competitive moves as firms respond to divergent certification timelines across NHTSA, ECE R30, and GB standard jurisdictions.
Within the integrated system supplier tier, ZF Friedrichshafen AG and KYB Corporation occupy positions that span original equipment and replacement demand. Tenneco Inc. anchors the brand-recognized aftermarket channel through its Monroe operations. Bilstein represents the performance-oriented archetype with specialized positioning in adjustable damping configurations. These firms exemplify how geographic origin and corporate structure shape strategic options without dictating specific competitive actions.
| Leading Market Players |
|---|
| Hitachi Astemo Ltd. |
| Bilstein |
| KYB Corporation |
| Gabriel India Limited |
| Fox Factory Holding Corp. |
| Tenneco Inc. |
| Monroe |
| Koni BV |
| ZF Friedrichshafen AG |
| Others |
Pricing and Supply Chain Analysis
Steel and rubber compound costs cascade through automotive aftermarket shock absorber pricing tiers from precision forging centers in China and Germany to fleet procurement contracts in the United States. REACH-compliant seal elastomers and high-grade piston rod materials command premium positioning in European channels, while commodity-grade inputs feed economy replacement segments where buyer price sensitivity peaks.
Pricing Analysis
The bundled-versus-unbundled service split separates fleet maintenance contracts with lifecycle cost modeling from transactional retail purchases. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal performance specifications, with mono-tube configurations capturing margin premiums in Japanese and German tuning channels. Pricing pressure stems from steel input volatility and REACH reformulation costs that compress margins on hydraulic fluid formulations. Fleet owners exhibit lowest price sensitivity due to total cost of ownership frameworks, while DIY segments in online channels drive hardest bargain hunting.
Supply Chain Analysis
Direct-to-fleet channels handle commercial vehicle volume through long-term maintenance agreements, while wholesale jobbers feed independent repair networks. Manufacturing gravity centers on China, Germany, and Japan, where precision forging capacity for piston rods and specialized machining for mono-tube housings concentrate. Raw material flows draw from Swedish steel billet, Malaysian rubber compounds, and Taiwanese seal elastomers. Single-source vulnerability in East Asian precision machining creates exposure to regional logistics disruptions. Distribution runs through layered wholesale networks in mature markets, with digital platforms disintermediating traditional jobbers in Australia and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as EU F-Gas Regulation and analogous environmental mandates shift procurement authority toward premium damping technologies with verified durability testing.
For Market Incumbents: Extend mono-tube manufacturing scale into fleet maintenance contracts where total cost of ownership calculations override upfront part pricing. Backward integration into precision forging capacity in Germany or Japan defends margin position against steel input volatility. Certification investment for dual NHTSA-ECE R30 compliance creates barrier against emerging Asian suppliers lacking multi-jurisdiction testing infrastructure. For New Entrants and Emerging Players: Enter via India's underpenetrated commercial vehicle aftermarket where Bharat Stage VI compliance raises vehicle complexity and replacement infrastructure gaps persist. Target heavy-duty truck damping segments in Maharashtra and Gujarat where domestic forging investments lag demand growth. Go-to-market leverage rests on direct-fit compatibility platforms that bypass traditional wholesale layers and capture fleet procurement digitization trends. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs and certification timeline compression strain mid-tier suppliers lacking scale to absorb regulatory redundancy. Long-term viability favors integrated chassis system suppliers with captive OE relationships feeding aftermarket demand. Acquisition target archetype: mono-tube technology specialists with verified heat dissipation testing and established repair shop relationships in Japan or Germany. Signal to watch: fleet tender specifications incorporating lifecycle emission metrics as mandatory scoring criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Tube Capacity Expansion | Captures premium margin pools in German and Japanese performance tuning channels. |
| REACH-Compliant Fluid Reformulation | Maintains European aftermarket access as ECHA restrictions tighten hydraulic seal compounds. |
| Direct-Fit Platform Development | Disintermediates wholesale jobbers by enabling VIN-matched DIY customer self-selection. |
| Fleet Maintenance Contracting | Locks in commercial vehicle volume through predictive replacement scheduling and lifecycle pricing. |
| Dual Certification Investment | Reduces product validation redundancy across NHTSA, ECE R30, and GB standard jurisdictions. |
Research Methodology
Bottom-up fleet operator and repair shop modeling reconciled against top-down forging capacity and vehicle registration tracking forms the analytical core of this study. Primary interviews with aftermarket distributors, Tier 1 supplier procurement leads, OEM platform engineers, and fleet maintenance directors combined with secondary validation from vehicle production databases, IHS Markit registration data, customs trade records, and SEC filings from publicly traded chassis suppliers. Triangulation across these sources calibrated replacement demand assumptions against manufacturing output and import-export flows.
Input-output matrices mapped shock absorber content per vehicle across passenger car, SUV, truck, and van segments, with propulsion architecture and regional production clusters as cross-cutting dimensions. CAGRs derived from regression analysis of historical replacement intervals, vehicle age distributions, and regulatory mandate timelines. Industry-specific forecast inputs included MIIT inspection protocol enforcement rates in China and EU F-Gas Regulation compliance thresholds across member states.
Inputs from fleet operators and aftermarket distributors were available through the study window; gaps in independent repair shop inventory data and emerging market replacement frequency statistics introduce uncertainty bands around DIY segment projections. Forecasts reflect assumptions regarding regulatory enforcement consistency and steel price normalization. Periodic stress-testing of base assumptions against REACH chemical restriction amendments and NHTSA safety standard revisions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Precision Bearing Market
Vehicle Components
Front Forks Market
Vehicle Components
Crank Case Ventilation Valve Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Tricycle Vending Cart Market
Vehicle Components
Vehicle Retarder Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
Advanced Driver Assistance System (ADAS) Sensor Market
Vehicle Components
Air Suspension Market
Vehicle Components
Hydrostatic Transmission Market
Vehicle Components
Bicycle Chain Market
Vehicle Components
Refrigerated Trailer Hinges Market
Vehicle Components
Car Radiator Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Charge Air Coolers Market