
 Bicycle Accessories Market | 2026-2036
Bicycle Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Accessories Market Analysis
The capital-intensity divergence between high-volume manufacturers and precision component specialists is unwinding as e-bike electrification raises tooling requirements. Shimano Inc. anchors its position through captive drivetrain production at scale. Garmin Ltd. differentiates via GPS-enabled device ecosystems that command premium positioning. Specialized Bicycle Components Inc. competes on integrated design-to-retail control across its dealer network.
Bicycle accessories comprise supplementary equipment—including lighting systems, mechanical security devices, inflation apparatus, and cargo carriers—fabricated from aluminum alloys, vulcanized rubber, engineered polymers, and hardened steel grades, primarily serving rider safety, vehicle utility, and performance optimization. Lights and locks occupy the largest revenue pools due to mandatory equipment laws in urban jurisdictions, while bags and pumps carry thinner margins despite higher unit volumes. Waterproof and reflective feature sets attract premium pricing in the commuting application segment, where all-weather reliability determines purchase decisions.
EU REACH compliance and CE marking requirements govern chemical composition and electrical safety for accessories sold across member states, while the US Consumer Product Safety Commission enforces mechanical integrity standards for locks and lights. Japan's Ministry of Economy, Trade and Industry maintains JIS certification protocols that constrain market entry for non-compliant suppliers. Stakeholders must track evolving e-bike voltage classifications and associated accessory interoperability standards as electrification redefines product boundaries.
Market Dynamics
E-bike electrification is forcing a fundamental recalibration of accessory design standards as voltage classifications under EU and US safety rules reshape material specifications and interoperability requirements across the entire component ecosystem.
Growth Catalysts
- EU REACH compliance mandates:Chemical composition standards for rubber compounds and polymer formulations in lighting housings and lock mechanisms are accelerating supplier consolidation toward certified producers.
- Urban fleet replacement cycles:Amsterdam and Copenhagen municipal cycling programs generate sustained demand for waterproof lighting systems and hardened steel security devices.
- Aluminum alloy forging advances:Precision stamping capabilities around Stuttgart are enabling lighter cargo carrier architectures that meet e-bike weight thresholds.
Market Restraints
- Engineered polymer feedstock volatility:Specialized nylon grades for weatherproof housings face price instability tied to petrochemical supply chains concentrated in German and Dutch port complexes.
- JIS certification barriers:Japan's Ministry of Economy, Trade and Industry protocols create extended approval timelines for GPS-enabled devices and electronic locking systems.
- Mechanical key substitution:Smartphone-based digital access systems are eroding demand for traditional pin-tumbler and disc-detainer lock architectures in premium commuter segments.
Strategic Opportunities
- Indian urban micromobility expansion:Metro rail integration programs in Bengaluru and Delhi are creating first-mile/last-mile accessory demand for collapsible pumps and modular cargo systems.
- US Inflation Reduction Act e-bike incentives:Federal tax credits for electric bicycle purchases are expanding the addressable market for voltage-compatible lighting and charging accessories.
- Direct-to-consumer channel maturation:Specialized digital platforms are compressing distributor margins while enabling real-time fitment data integration for component matching.
Industry Challenges
- Embedded software certification timelines:GPS tracking modules and smart lock firmware face extended FCC and CE marking approval cycles that delay product launches.
- Multi-material bonding expertise gaps:Vulcanized rubber-to-aluminum interfaces in waterproof lighting assemblies require specialized process engineering talent concentrated in legacy automotive supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Accessories Market |
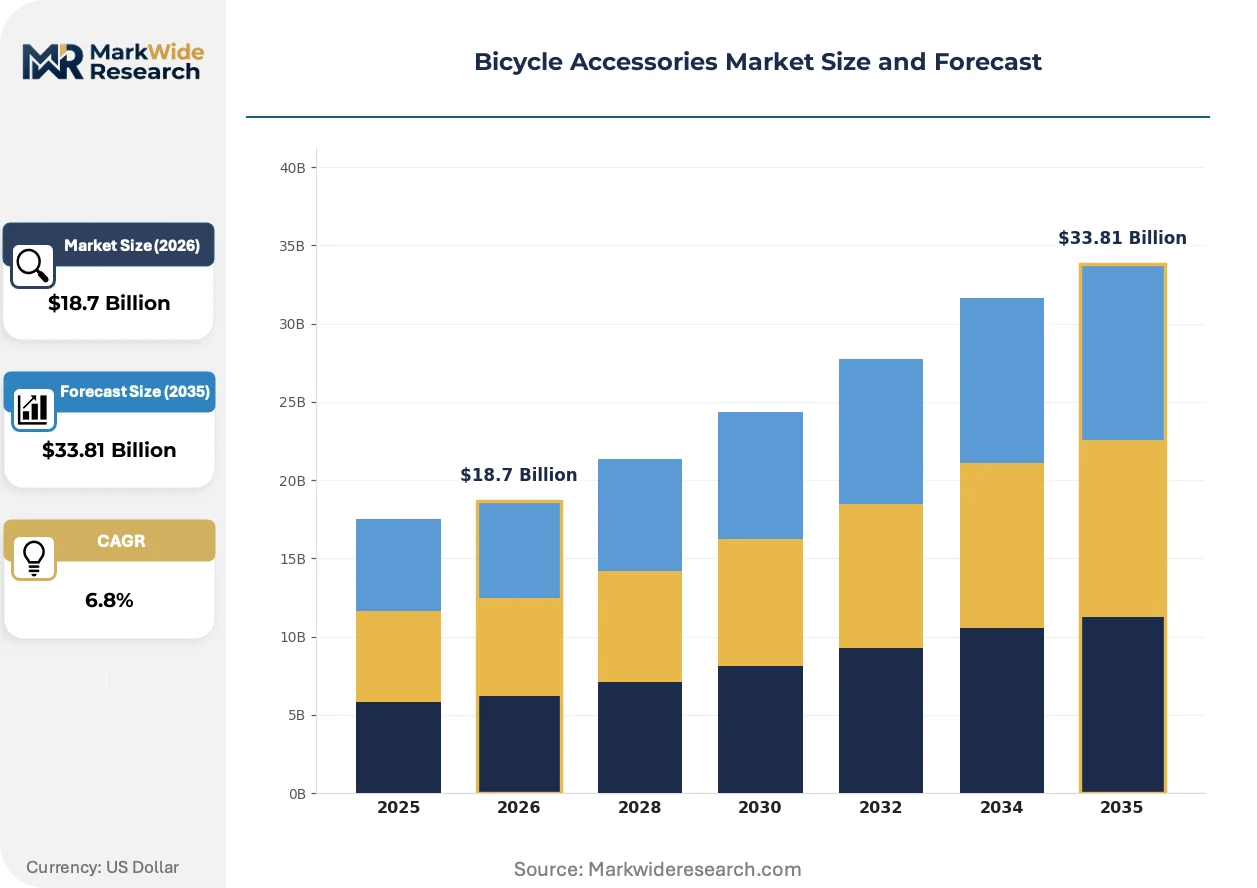
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lights, Locks, Pumps, Bags Feature: Waterproof, Lightweight, Reflective, Adjustable Application: Commuting, Touring, Racing, Leisure Material: Aluminum, Rubber, Plastic, Steel |
| Companies Covered | Garmin Ltd., Specialized Bicycle Components Inc., Shimano Inc., Thule Group AB, Fox Factory Holding Corp., Giant Manufacturing Co., Ltd., SRAM LLC, ABUS August Bremicker Söhne KG, Trek Bicycle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Accessories Market Emerging Trajectories
Accessory architectures are converging around electrification compatibility and connected functionality as traditional mechanical systems face obsolescence pressure from integrated electronic alternatives.
Li-ion battery-integrated lighting systems are displacing dynamo-powered and disposable battery alternatives across commuter and touring segments. German component specialists and Scandinavian fleet operators are adopting these architectures fastest. The technology is displacing legacy wiring harness standards and creating demand for unified voltage management protocols.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-free thermal management in high-output LED drivers. Manufacturers serving the Dutch and Belgian markets are redesigning heat dissipation geometries to eliminate compressed gas cooling. The policy is compressing design cycles for lighting engineers while favoring aluminum-intensive thermal solutions over polymer housings.
Subscription-based accessory service bundles are emerging as an alternative to outright ownership in corporate cycling programs. Fleet managers in Copenhagen and Utrecht are piloting all-inclusive maintenance contracts covering lights, locks, and inflation equipment. This model is most visible in Northern European urban jurisdictions with mature cycling infrastructure and standardized equipment specifications.
Bicycle Accessories Market Segmentation
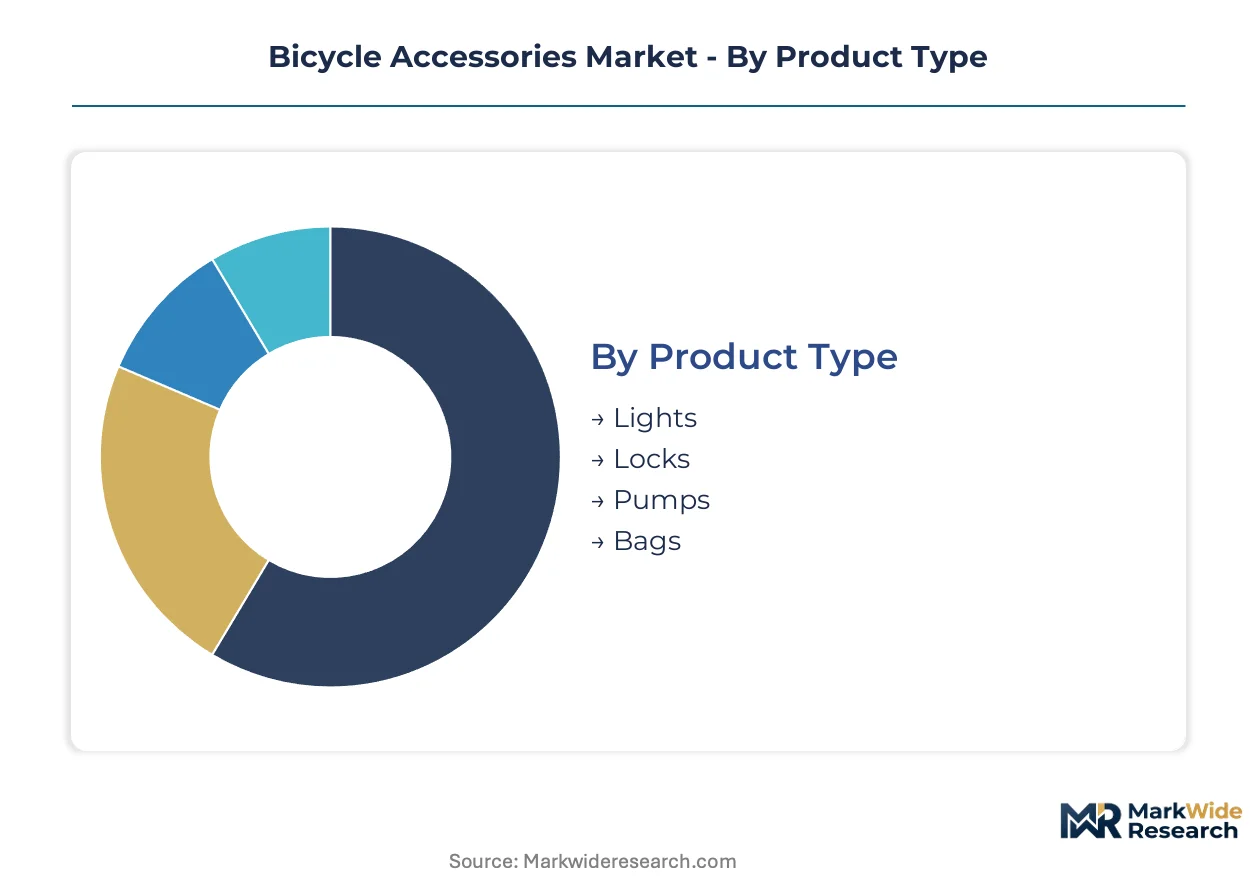
Segmentation in bicycle accessories reveals how regulatory mandates, material science advances, and rider use cases fragment demand across incompatible technical specifications. Understanding these divisions exposes where supplier consolidation and premium pricing power concentrate.
Product Type:
Geographic concentration varies sharply: lights and locks serve regulated urban fleets domestically in Northern Europe, while pumps and bags follow export-led recreational demand into North American and Asian markets.
- Lights:LED arrays with integrated Li-ion cells and thermal management substrates dominate technical roadmaps. Amsterdam and Copenhagen municipal procurement specifications for waterproof housings and standardized mounting interfaces drive volume concentration in certified German and Dutch suppliers.
- Locks:Hardened steel shackles and disc-detainer mechanisms face displacement pressure from Bluetooth-enabled electronic alternatives. Premium commuter segments in German urban centers show fastest adoption of smartphone-based access systems, eroding traditional mechanical key demand.
- Pumps:High-pressure floor models and portable mini-pumps with flexible hose attachments serve touring and roadside repair applications. Japanese cycling culture sustains precision gauge demand for high-volume road tire inflation.
- Bags:Pannier systems and handlebar-mounted carriers utilize welded seam construction and quick-release mounting hardware. Danish long-distance touring routes generate specialized waterproof cargo requirements distinct from urban utility patterns.
Lights hold the largest share; momentum sits with locks as electronic access architectures gain regulatory acceptance.
Feature:
Cost tier stratification separates mandatory compliance features from discretionary performance upgrades, with waterproofing and reflectivity commanding regulatory premiums while lightweight materials extract enthusiast margins.
- Waterproof:IPX4 and IPX6 rated housings with vulcanized rubber gaskets and sealed cable entry points define technical baselines for all-weather commuting. Dutch and Belgian fleet specifications eliminate non-compliant suppliers from municipal tender processes.
- Reflective:Retroreflective textile integration and LED beacon systems serve dawn and dusk visibility mandates. German StVZO road traffic regulations prescribe specific luminosity thresholds that shape product development priorities.
- Lightweight:Magnesium alloy pump barrels and carbon-reinforced polymer lock bodies target gram-conscious racing segments. Italian and Spanish road cycling cultures sustain premium pricing for mass-reduced accessories.
- Adjustable:Modular mounting systems and telescoping frame pump designs accommodate diverse bicycle geometries. Direct-to-consumer channel growth demands universal fitment compatibility across proprietary frame standards.
Waterproof specifications dominate unit economics; lightweight configurations are climbing the fastest as e-bike weight thresholds tighten.
Application:
Volume concentration clusters in utility commuting where replacement cycles are shortest, while margin extraction succeeds in specialized touring and racing segments with technical performance requirements.
- Commuting:Daily-use accessories face accelerated wear patterns and theft exposure, compressing replacement intervals. Urban infrastructure investments in Utrecht and Malmö standardize equipment specifications across corporate cycling programs.
- Touring:Multi-day reliability demands redundant systems and field-serviceable components. German long-distance cycling routes (Fernradwege) sustain demand for durable pump and bag architectures.
- Racing:Minimalist weight targets and aerodynamic integration constrain design freedom. Italian professional cycling team equipment protocols influence amateur purchasing patterns through visible sponsorship exposure.
- Leisure:Occasional-use accessories prioritize affordability over durability, channeling volume through mass retail. Spanish and Portuguese coastal tourism markets show seasonal demand spikes for rental fleet equipment.
Commuting generates the highest unit volumes; touring delivers the steepest expansion trajectory as long-distance route networks mature across Central Europe.
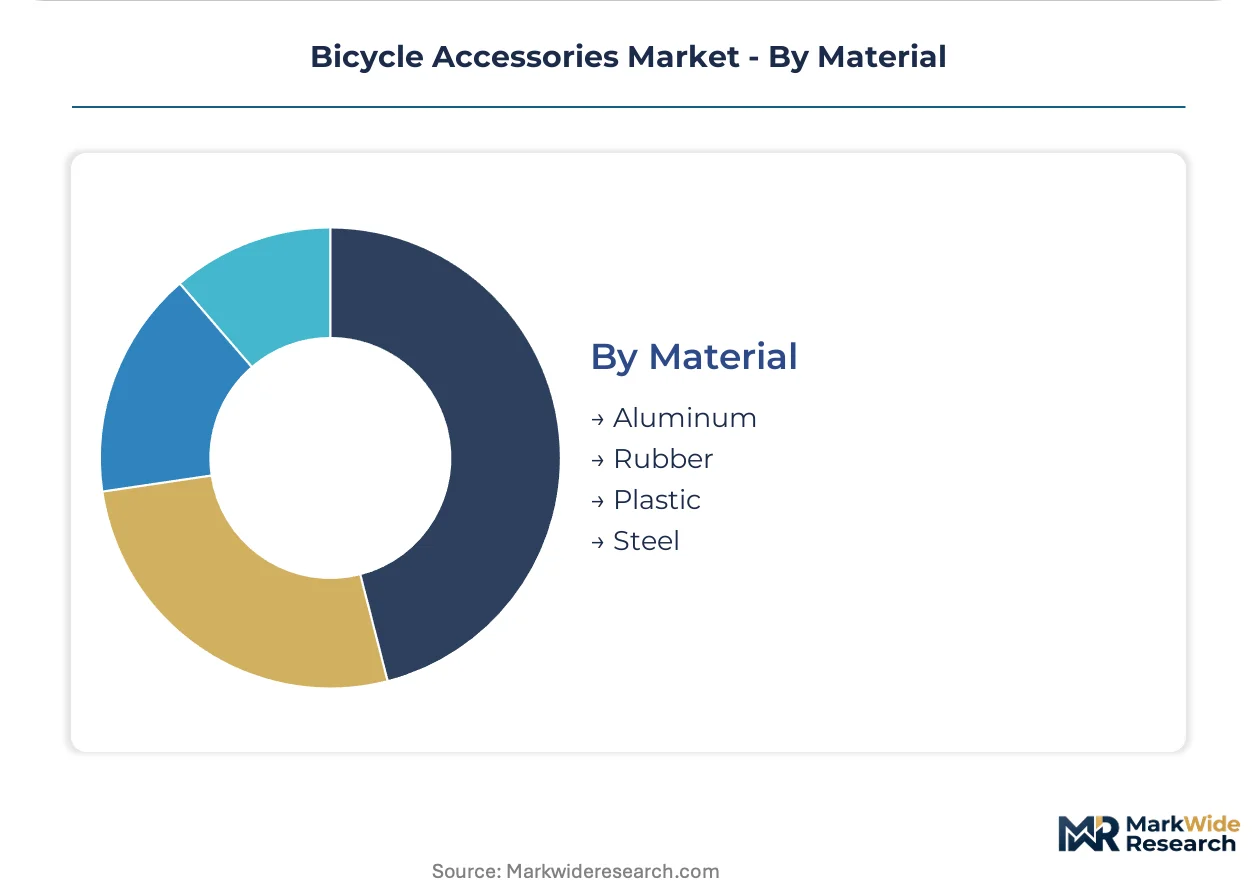
Material:
Supply concentration in German aluminum forging and Dutch petrochemical processing shapes regional cost structures, while Japanese steel metallurgy and Southeast Asian rubber compounding serve specialized performance tiers.
- Aluminum:6061-T6 and 7075-T6 alloy extrusions enable heat dissipation in LED housings and structural integrity in cargo racks. Stuttgart-area precision metalworking clusters provide captive supply for high-volume lighting manufacturers.
- Steel:Boron-alloyed and hardened grades resist cutting and prying attacks in security applications. Japanese JIS-certified heat treatment protocols maintain quality differentiation in premium lock segments.
- Rubber:Vulcanized EPDM and natural rubber compounds seal electrical enclosures and dampen vibration in pump mechanisms. REACH compliance constraints on chemical additives consolidate supply toward certified European compounders.
- Plastic:Glass-filled nylons and ABS formulations reduce cost in non-structural housings and adjustment mechanisms. Price volatility in benzene-derived feedstocks concentrates procurement risk around Rotterdam and Antwerp port complexes.
Aluminum commands the largest material share; engineered polymers are gaining share fastest as housing designs integrate complex geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German suppliers command premium pricing for precision-forged aluminum components, while Chinese manufacturers capture volume share in polymer housings through cost-optimized injection molding clusters.
Germany
Stuttgart's precision metalworking ecosystem supplies heat-dissipating LED housings and lightweight cargo racks to Amsterdam and Copenhagen fleet operators. REACH compliance mandates from ECHA constrain rubber compound formulations, consolidating procurement toward certified domestic suppliers. Baden-Württemberg forging operations are expanding 6061-T6 alloy capacity to meet e-bike weight classification thresholds under EU safety rules.
Netherlands
Amsterdam and Utrecht municipal cycling programs generate replacement demand for waterproof lighting and hardened steel locks on compressed replacement cycles. EU F-Gas Regulation phase-down schedules are accelerating refrigerant-free thermal management redesigns among Dutch lighting engineers. Rotterdam port complexes concentrate engineered polymer feedstock procurement, exposing suppliers to benzene-derived price volatility.
United States
Federal tax credits under the Inflation Reduction Act are expanding the addressable market for voltage-compatible e-bike accessories across commuter segments. FCC certification timelines for GPS-enabled devices and smart lock firmware create extended approval cycles that delay product launches. Pacific Northwest urban cycling infrastructure investments are standardizing equipment specifications across corporate cycling programs.
Japan
METI-administered JIS certification protocols constrain market entry for electronic locking systems and GPS tracking modules from non-compliant foreign suppliers. Precision gauge demand for high-volume road tire inflation sustains specialized pump manufacturing in legacy industrial clusters. Japanese steel metallurgy maintains quality differentiation in premium security applications through certified heat treatment protocols.
India
Metro rail integration programs in Bengaluru and Delhi are creating first-mile/last-mile accessory demand for collapsible pumps and modular cargo systems. BIS safety standards for electrical accessories are accelerating supplier consolidation toward certified domestic producers. Maharashtra industrial corridors are attracting polymer compounding investments to serve price-sensitive leisure cycling segments.
Bicycle Accessories Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where precision component specialists coexist with high-volume polymer processors. The vendor base fragments across captive drivetrain producers, integrated design-to-retail operators, and specialized security device manufacturers. Three archetypes dominate: scale-driven drivetrain integrators, ecosystem-platform GPS specialists, and precision-forging aluminum suppliers. Competitive moves concentrate on strategic partnerships for voltage interoperability standards and backward integration into certified polymer compounding.
Within the integrated design-to-retail tier, Specialized Bicycle Components Inc. and Trek Bicycle Corporation occupy positions that exemplify dealer-network control strategies. Garmin Ltd. anchors the connected-device ecosystem archetype. Shimano Inc. represents scale-driven captive production of precision mechanical components. SRAM LLC and Fox Factory Holding Corp. sit within the performance-oriented specialist tier, while Thule Group AB and ABUS August Bremicker Söhne KG exemplify European-origin precision engineering structures. Giant Manufacturing Co., Ltd. occupies a position among Asia-Pacific volume producers.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Specialized Bicycle Components Inc. |
| Shimano Inc. |
| Thule Group AB |
| Fox Factory Holding Corp. |
| Giant Manufacturing Co., Ltd. |
| SRAM LLC |
| ABUS August Bremicker Söhne KG |
| Trek Bicycle Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Stuttgart aluminum forgers and Dutch lighting manufacturers lock in heat-dissipating LED housing supply while fixing input costs against Rotterdam petrochemical volatility. These contracts bundle REACH-certified rubber compound procurement with precision forging capacity, giving certified suppliers pricing visibility that spot-market competitors cannot match.
Pricing Analysis
Configured-to-order pricing for GPS-enabled locks and Li-ion integrated lighting systems commands spreads over standard mechanical alternatives. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked fleet equipment from aftermarket commodity replacements. Price differentiation hinges on certification grade and customization level. Cost compression in polymer housings is intensifying because benzene feedstock volatility concentrates procurement risk around Antwerp port complexes. Corporate cycling programs show lowest price sensitivity; leisure rental fleets in Southern Europe exhibit highest.
Supply Chain Analysis
Just-in-time inventory strategies dominate German precision metalworking clusters serving Amsterdam and Copenhagen municipal fleets, while strategic stockpiling of REACH-certified rubber compounds buffers Dutch lighting assemblers against ECHA regulatory delays. Supply concentrates in Germany, Netherlands, and Japan. The ecosystem draws from aluminum alloy extrusions, vulcanized EPDM compounds, and hardened steel grades. Single-source vulnerability in Stuttgart-area forging capacity threatens LED thermal management substrate availability. Distribution runs through authorized dealer networks and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bicycle accessories market functions as a service-attach opportunity where subscription-based maintenance bundles for corporate cycling programs expand faster than standalone hardware sales. Fleet managers in Utrecht and Copenhagen increasingly procure all-inclusive lighting, lock, and inflation equipment contracts rather than capital purchases.
For Market Incumbents: Compound dealer network control with backward integration into certified polymer compounding to defend against direct-to-consumer platform erosion. Captive supply of REACH-compliant rubber gaskets locks out emerging Asian competitors facing ECHA approval timelines. Prioritize firmware certification investment for smart lock architectures before FCC and CE marking cycles lengthen further. For New Entrants and Emerging Players: Smartphone-based digital access system integration represents a service-layer gap where mechanical lock incumbents under-serve premium commuter segments. Target Indian metro rail integration programs in Bengaluru and Delhi with collapsible pump and modular cargo configurations. Pursue white-label partnerships with domestic BIS-certified electrical accessory producers to bypass JIS and CE approval barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among GPS-enabled device ecosystem specialists with firmware subscription attach rates. Long-term viability favors precision aluminum forging operations with captive Stuttgart-area capacity and municipal fleet procurement relationships. Watch for EU F-Gas Regulation enforcement intensity as inflection indicator for thermal management redesign demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH certification captive supply locks out non-compliant competitors from Dutch municipal tenders. |
| Smart Lock Firmware Certification Investment | FCC and CE marking preemptive completion accelerates product launch timelines against regulatory backlog. |
| Direct-to-Consumer Platform Launch | Real-time fitment data integration compresses distributor margins while capturing enthusiast segment pricing. |
| Subscription Service Bundle Development | Corporate cycling program maintenance contracts in Copenhagen generate recurring revenue exceeding hardware margins. |
| Indian Domestic Manufacturing Partnership | BIS-certified production capacity addresses Bengaluru metro rail first-mile accessory demand with tariff advantage. |
Methodological Framework
The analysis maps lighting systems, mechanical security devices, inflation apparatus, and cargo carriers, each validated through procurement managers at municipal cycling programs, R&D directors at precision metalworking clusters, regulatory affairs specialists at polymer compounders, and aftermarket distribution channel heads. Primary interviews combined with secondary validation from ECHA REACH registration databases, EU F-Gas Regulation implementation filings, SEC 10-K disclosures from listed component manufacturers, and municipal procurement tender documents. Bottom-up unit demand modeling triangulates against top-down market sizing across certification tiers.
Consistency checks validated volume and value outputs against external benchmarks including customs trade data for aluminum alloy extrusions and benzene-derived polymer feedstocks. The analytical framework segments by product type, feature specification, application use case, and material composition across the projection horizon. CAGRs derive from replacement cycle analysis for fleet equipment and adoption curve modeling for electronic access systems. Forecast inputs incorporate e-bike voltage classification regulatory evolution and urban infrastructure investment pipelines.
Underlying assumptions cover EU and US safety rule stability, with deviation risk concentrated in JIS certification timeline extensions and engineered polymer feedstock price volatility. Forecasts reflect documented assumptions with directional-only reliability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
Cylindrical Roller Bearings Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market
Vehicle Components
US Group 2 Powered Mobility Devices Market
Vehicle Components
Spark Plug Accessories Market
Vehicle Components
Grille Guard Market
Vehicle Components
Wheel Seals Market
Vehicle Components
Automotive Sensors Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Trailer Stabilizer Market
Vehicle Components
Industrial Brake Caliper Market
Vehicle Components
Global Truck and Trailer Landing Gear Market
Vehicle Components
Rail Wheel and Axle Market
Vehicle Components
Automotive Air Flow Sensors Market