
 Global Tyre Inflators Market | 2026-2036
Global Tyre Inflators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tyre Inflators Market Foresight
Skilled maintenance technician availability is reorganizing how fleet operators and repair workshops source tyre inflator equipment across developed markets. Robert Bosch GmbH leverages its automotive aftermarket channel density to sustain replacement-part pull-through in European service bays. VIAIR anchors the North American portable compressor segment through specialized 12-volt and off-road product lines. Michelin competes on brand trust and co-placement with its tire retail network, while Stanley Black & Decker, Inc extends its DeWalt power-tool ecosystem into cordless inflator formats for construction-adjacent users.
Tyre inflators are pressure-delivery devices engineered to restore or maintain optimal inflation in pneumatic tires, typically spanning operating ranges from 30 PSI for passenger vehicles to 150 PSI for commercial truck applications. The primary commercial purpose centers on preventing uneven tread wear, reducing fuel consumption, and eliminating blowout risk across road-going and off-road fleets. Digital and automatic shut-off technology segments command margin premiums by eliminating operator guesswork in high-volume fleet settings. Battery powered and cordless formats represent the fastest-growing structural categories as lithium-cell economics improve and mobile service models proliferate. Manual and basic pneumatic types remain entrenched in emerging-market roadside assistance and low-frequency consumer use where capital constraints override convenience preferences.
FDA oversight of workshop air quality intersects with OSHA compressor safety standards in the United States, while REACH chemical compliance and CE marking govern material composition and electrical safety across European imports. China's GB standards and MIIT energy-efficiency directives shape domestic manufacturing specifications and export eligibility for battery-powered units. Stakeholders must monitor evolving tire pressure monitoring system integration mandates and battery transportation regulations to anticipate product redesign cycles and certification timelines.
Market Dynamics
Fleet operators are consolidating tyre inflator procurement around automatic shut-off units as tire pressure monitoring system mandates tighten across major automotive markets, compressing replacement cycles for legacy pneumatic equipment.
Growth Catalysts
- NHTSA Tire Pressure Monitoring Standards:United States enforcement of TPMS installation and maintenance protocols is expanding addressable demand for precision calibration equipment in commercial vehicle service bays.
- Lithium-ion cell chemistry advances:Energy density improvements in cylindrical battery formats are extending cordless inflator runtime to full-shift coverage for mobile roadside technicians.
- Commercial fleet electrification:Electric vehicle weight distribution characteristics are accelerating tire wear rates and inflating maintenance frequency requirements for last-mile delivery operators.
Market Restraints
- Cobalt and lithium carbonate price volatility:Battery raw material cost swings are compressing margins on cordless units and forcing OEMs toward LFP cell alternatives with lower energy density.
- Guangdong and Zhejiang manufacturing concentration:Compressor motor and pump assembly capacity clusters in China's Pearl River Delta, exposing supply continuity risk to regional power rationing or port congestion.
- Manual inflator substitution persistence:Foot-pump and basic pneumatic formats retain installed base in price-sensitive emerging markets where capital recovery periods override convenience premiums.
Strategic Opportunities
- India commercial vehicle parc expansion:Heavy truck and bus fleet growth under the PLI scheme for automotive components is creating first-time demand for workshop-grade automatic inflators in tier-2 cities.
- Telematics-integrated smart inflators:Convergence of pressure sensors with fleet management platforms enables predictive maintenance alerts and usage-based service contracting.
- EU Green Deal circular economy requirements:Extended producer responsibility frameworks for battery-powered tools are creating refurbishment and battery-swap service revenue streams.
Industry Challenges
- Certification timeline compression:CE marking and GB standards updates for battery transport and electromagnetic compatibility are extending product redesign cycles and delaying regional launches.
- Technician training deficits:Digital gauge calibration and lithium battery safety protocols require upskilling programs that fleet maintenance departments struggle to resource at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tyre Inflators Market |
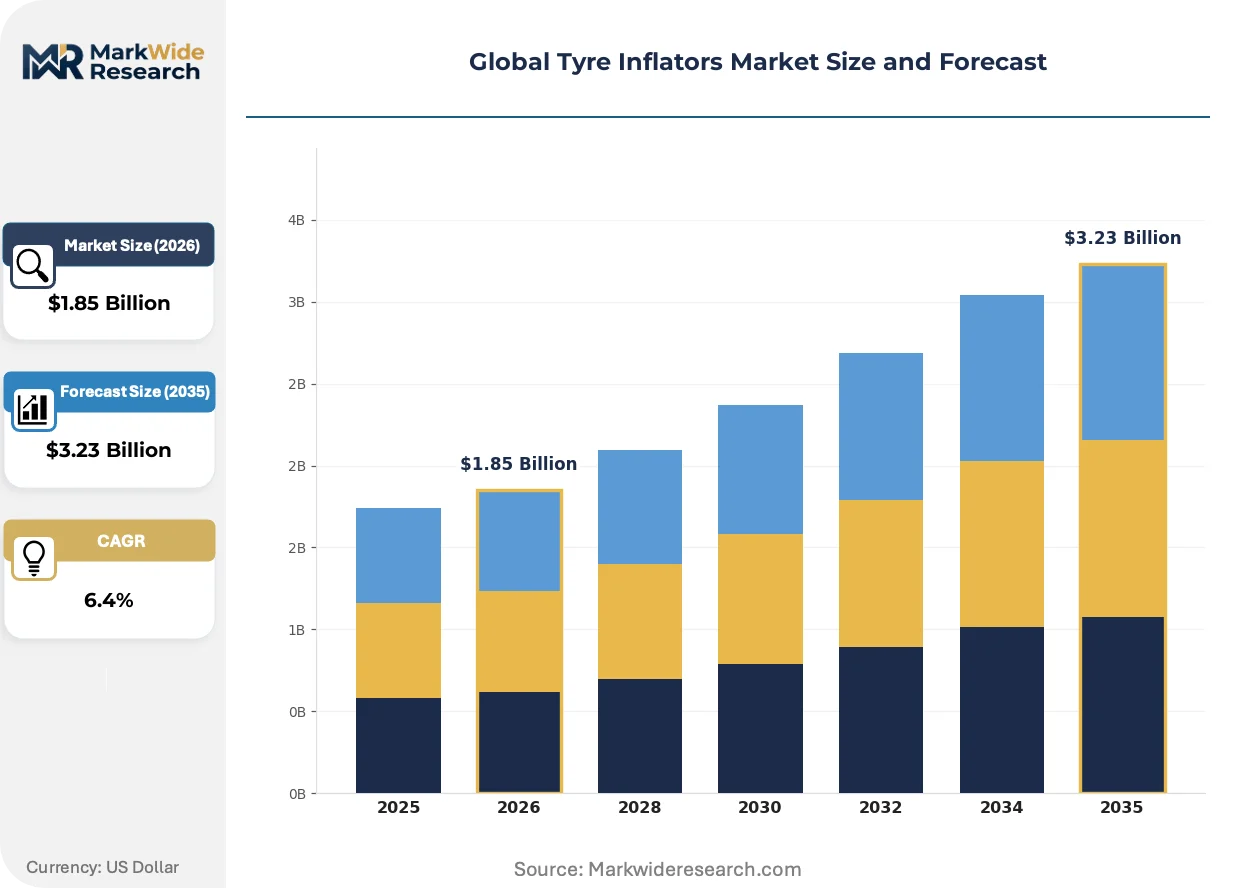
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Digital, Electric, Manual, Air Compressor Technology: Pneumatic, Cordless, USB Rechargeable, Battery Powered, Automatic Shut-off Application: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Agricultural Vehicles, Construction Machines End User: Vehicle Owners, Fleet Operators, Repair Workshops, Roadside Assistance, Gas Stations |
| Companies Covered | Michelin, Slime, VIAIR, BONAIRE Industries, Hendrickson USA, Kensun, Robert Bosch GmbH, Stanley Black & Decker, Inc, DeWalt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tyre Inflators Market Shifts & Advancements
Solid-state pressure sensing and brushless motor architectures are converging to redefine portability benchmarks, while regulatory integration mandates and shifting procurement authority are restructuring channel economics.
Micro-electromechanical pressure sensors are replacing analog Bourdon tube gauges in mid-tier cordless units, delivering accuracy within 0.5 PSI across temperature extremes. Fleet maintenance departments in Germany and the United States are specifying MEMS-equipped models for warranty compliance documentation. This sensor migration is miniaturizing inflator form factors to glove-box stowage dimensions previously unattainable in 12-volt formats.
REACH chemical compliance and the EU F-Gas Regulation are restricting refrigerant-based cooling in compressor motors and lubricant formulations in pump assemblies. Manufacturers are reformulating synthetic oils and transitioning to air-cooled architectures to maintain export eligibility. European aftermarket distributors are prioritizing CE-marked units with full material disclosure documentation, filtering non-compliant inventory from their supplier rosters.
Direct fleet procurement is displacing traditional jobber and distributor intermediaries for high-volume automatic shut-off units. Large logistics operators in the United States and China are issuing tender specifications that bundle inflators with tire pressure monitoring system service contracts. This authority consolidation is most visible in long-haul trucking and last-mile delivery verticals where total cost of ownership modeling overrides upfront equipment pricing.
Global Tyre Inflators Market Segmentation
Tyre inflator segmentation reveals divergent procurement patterns between developed markets prioritizing precision and emerging economies optimizing capital efficiency. Understanding these structural divides enables targeted positioning across price-performance tiers and regulatory environments.
Product Type:
Domestic manufacturing dominates manual and basic pneumatic formats across South Asia and Southeast Asia, while portable and digital units flow through export channels from Chinese and German production clusters.
- Portable:Compact 12-volt and battery-integrated designs serve mobile roadside technicians and recreational vehicle owners. Fleet operators in the United States and Germany specify these for emergency response vehicles where storage space is constrained.
- Digital:MEMS pressure sensors deliver accuracy within 0.5 PSI for warranty compliance documentation. Repair workshops in Japan and South Korea mandate digital readouts for passenger vehicle service protocols.
- Electric:Mains-powered units anchor workshop installations where continuous duty cycles exceed cordless runtime limits.
- Manual:Foot-pump and hand-pump formats retain installed base in India and Brazil where capital recovery periods override convenience premiums.
- Air Compressor:Stationary tank-mounted systems serve multi-bay commercial facilities with centralized air distribution.
Manual formats hold the largest share; momentum sits with portable configurations.
Technology:
Cost tiers stratify sharply between legacy pneumatic infrastructure and cordless premium positioning driven by lithium-cell economics.
- Pneumatic:Compressed-air dependency ties these units to workshop infrastructure with limited mobility. Emerging-market repair bays in Mexico and Turkey continue procurement for high-volume truck tire service.
- Cordless:Brushless motor architectures paired with 21700 cylindrical cells enable full-shift runtime for mobile technicians. Last-mile delivery fleets in California and Shanghai are standardizing cordless specifications.
- USB Rechargeable:Low-capacity lithium-polymer formats target consumer glove-box storage for emergency inflation of passenger vehicle tires.
- Battery Powered:Removable pack systems allow field swapping in remote agricultural and construction settings where grid access is unreliable.
- Automatic Shut-off:Pressure-triggered motor termination eliminates operator error in high-volume fleet maintenance environments.
Pneumatic systems retain volume leadership; cordless platforms are climbing the fastest.
Application:
Vehicle parc composition and enforcement intensity determine segment prioritization across national markets.
- Passenger Vehicles:TPMS mandate compliance in the United States and European Union sustains replacement demand for precision calibration equipment.
- Commercial Trucks:150 PSI operating requirements and dual-tire configurations demand high-flow compressor capacity. Long-haul operators in Germany and Australia specify automatic shut-off units for depot-based maintenance.
- Two-Wheelers:Compact portable formats dominate Southeast Asian markets where motorcycle density exceeds four-wheeled vehicle populations.
- Agricultural Vehicles:Large-bore tires and remote field locations favor high-capacity battery-powered units with extended hose reach.
- Construction Machines:Severe-duty specifications and off-road terrain exposure drive demand for reinforced housing and vibration-resistant gauges.
Passenger vehicles command the greatest volume; commercial trucks show the steepest expansion trajectory.
End User:
Procurement authority is consolidating around direct fleet purchasing and away from traditional distributor intermediaries.
- Vehicle Owners:Retail channel purchases concentrate in emergency preparedness segments, with USB-rechargeable formats gaining preference for glove-box storage.
- Fleet Operators:Tender specifications now bundle inflators with tire pressure monitoring system service contracts. Logistics operators in China and the United States issue volume commitments that override upfront equipment pricing.
- Repair Workshops:Workshop-grade pneumatic and digital units remain the core revenue base for aftermarket distributors in France and Italy.
- Roadside Assistance:Mobile service providers in Brazil and South Africa prioritize cordless portability for highway response coverage.
- Gas Stations:Coin-operated and free-use inflation stations serve consumer convenience demand in Japan and South Korea.
Repair workshops represent the largest installed base; fleet operators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA tire pressure monitoring enforcement anchors the United States as the dominant geography, with regulatory spillover effects reshaping equipment specifications across Germany, China, India, and Japan.
United States
Commercial fleet electrification accelerates tire wear rates for last-mile delivery operators, expanding maintenance frequency requirements. NHTSA TPMS installation and maintenance protocols mandate precision calibration equipment in vehicle service bays. Detroit and Chicago logistics clusters standardize automatic shut-off inflator specifications through direct tender contracts.
Germany
Long-haul trucking operators specify high-flow automatic units for depot-based dual-tire maintenance. REACH chemical compliance and EU F-Gas Regulation restrict refrigerant-based cooling in compressor motors, forcing air-cooled architecture transitions. Stuttgart and Munich aftermarket distributors prioritize CE-marked inventory with full material disclosure documentation.
China
GB standards and MIIT energy-efficiency directives shape domestic manufacturing specifications for battery-powered export units. Pearl River Delta compressor motor clusters in Guangdong and Zhejiang expose supply continuity risk to regional power rationing. Shanghai last-mile delivery fleets standardize cordless specifications with brushless motor architectures.
India
Heavy truck and bus fleet growth under the PLI scheme for automotive components creates first-time workshop-grade demand in tier-2 cities. BIS certification requirements govern electrical safety for imported battery-powered units. Maharashtra and Gujarat commercial vehicle hubs drive procurement consolidation around automatic shut-off formats.
Japan
Repair workshops mandate digital readouts with MEMS pressure sensors for passenger vehicle service protocols. METI industrial standards shape precision equipment specifications for warranty compliance documentation. Tokyo and Osaka service bay networks specify glove-box stowage dimensions for compact portable formats.
Global Tyre Inflators Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding aftermarket channel density and the latter anchoring portable and off-road niches. The structure reflects automotive heritage advantages in precision calibration against power-tool ecosystem extensions into cordless mobility. Strategic archetypes include diversified industrial conglomerates, specialized compressor fabricators, and tire-brand-affiliated equipment marketers. Competitive moves concentrate on channel consolidation through automotive aftermarket partnerships and lithium-cell supply security arrangements.
Within the diversified industrial tier, Robert Bosch GmbH and Stanley Black & Decker, Inc exemplify contrasting ecosystem strategies. Bosch leverages automotive aftermarket channel density to sustain replacement-part pull-through in European service bays. Stanley Black & Decker extends its DeWalt power-tool ecosystem into cordless inflator formats for construction-adjacent users. VIAIR occupies a specialist position anchoring the North American portable compressor segment through dedicated 12-volt product lines.
| Leading Market Players |
|---|
| Michelin |
| Slime |
| VIAIR |
| BONAIRE Industries |
| Hendrickson USA |
| Kensun |
| Robert Bosch GmbH |
| Stanley Black & Decker, Inc |
| DeWalt |
| Others |
Supply & Pricing Matrix
Compressor motor scale economies in Guangdong and Zhejiang manufacturing clusters concentrate supply-side leverage among vertically integrated OEMs, compressing price floors for cordless units while elevating premium tiers for CE-marked automatic shut-off equipment. This concentration forces tier-2 assemblers into manual format commoditization or battery-pack sourcing partnerships to remain viable.
Pricing Analysis
Factory gate spreads between Pearl River Delta export hubs and German aftermarket distributors span three performance tiers. Pricing stratifies across premium automatic shut-off units, standard digital formats, and economy manual pumps, with CE certification and MEMS sensor integration commanding measurable premiums. Cost compression in cordless lithium-ion segments intensifies as cobalt carbonate volatility forces LFP cell substitutions. Fleet operators show lowest price sensitivity through tender bundling, while emerging-market roadside assistance providers prioritize capital recovery over convenience features.
Supply Chain Analysis
Strategic stockpiling of 21700 cylindrical cells and brushless motor components dominates inventory strategy among North American and European distributors preparing for NHTSA and REACH compliance deadlines. Manufacturing concentrates in China, Germany, and Vietnam, with compressor pump assemblies drawing from steel forging clusters and rare-earth magnet suppliers. Single-source vulnerability runs through Guangdong power grid stability and lithium carbonate processing capacity. Distribution runs through automotive aftermarket distributors and direct fleet procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lithium-ion cell chemistry maturation and TPMS mandate enforcement across major automotive markets create a high-growth disruption window for precision tyre inflator equipment. This inflection compresses replacement cycles for legacy pneumatic infrastructure while elevating cordless and automatic shut-off formats.
For Market Incumbents: Compound aftermarket channel density through tire retail network co-placement agreements and captive battery-pack supply arrangements. Defend against specialist compressor fabricators by accelerating CE marking documentation for full material disclosure compliance. Prioritize brushless motor R&D to extend runtime differentiation against emerging LFP-based competitors. For New Entrants and Emerging Players: Lead with telematics-integrated smart inflator development targeting last-mile delivery fleet operators in California and Shanghai. White-space concentrates in tier-2 Indian cities under PLI scheme expansion and agricultural battery-swap service models. Go-to-market should anchor predictive maintenance alert bundling with existing fleet management platform providers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors MEMS sensor specialists and cylindrical cell pack integrators over legacy pneumatic assemblers. Long-term viability hinges on circular economy service revenue streams under EU Green Deal extended producer responsibility frameworks. Watch for BIS certification timeline compression in India as inflection indicator for regional manufacturing relocation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cylindrical Cell Supply | Mitigates cobalt price volatility exposure for cordless inflator OEMs serving fleet operators. |
| Telematics Platform Partnership | Enables predictive maintenance alerts through pressure sensor integration with fleet management systems. |
| CE Marking Fast-Track Investment | Accelerates REACH and F-Gas compliance documentation for European aftermarket distributor eligibility. |
| Battery-Swap Service Infrastructure | Creates recurring revenue under EU Green Deal circular economy extended producer responsibility mandates. |
| Tier-2 India Distribution Buildout | Captures first-time workshop-grade demand from PLI scheme commercial vehicle parc expansion. |
Research Methodology
The analysis maps portable, digital, electric, manual, and air compressor product categories, each validated through fleet maintenance directors, aftermarket distributor procurement leads, OEM platform engineers, and roadside assistance operators. Primary interview findings triangulate against customs trade records, SEC automotive supplier filings, NHTSA TPMS enforcement databases, and IHS vehicle production data. Bottom-up unit economics and top-down market sizing converge through segment-level reconciliation.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework models product type, technology platform, vehicle application, and end-user procurement authority dimensions. CAGRs derive from segment-level growth rate reconciliation with macro vehicle parc and electrification penetration assumptions. Forecast inputs incorporate lithium-cell cost curves and regulatory mandate implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained TPMS enforcement intensity or lithium carbonate supply stabilization would require recalibration. Forecasts reflect assumptions on fleet electrification maintenance frequency and brushless motor adoption curves. Revision becomes warranted when BIS certification delays or REACH chemical restriction expansions cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
5th Wheel Hitches Market
Vehicle Components
US Group 2 Powered Mobility Devices Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
Japan Automotive Pneumatic Actuators Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
Snowplows Market
Vehicle Components
Mobility Aids and Transportation Equipment Market
Vehicle Components
Engine Valve Market
Vehicle Components
Gas Station Equipment Market
Vehicle Components
Vehicle Exhaust Hose Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Mechanical Control Cables Market