
 Global Automotive Exhaust Gas Turbochargers Market | 2026-2036
Global Automotive Exhaust Gas Turbochargers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Exhaust Gas Turbochargers Market Intelligence
Software-enabled boost control and over-the-air performance updates is rebalancing the value proposition beyond just hardware. This shift places new emphasis on integrated electronics and control units. BorgWarner Inc. leverages its expertise in electrification to develop advanced e-turbo systems. Meanwhile, Garrett Motion Inc. sustains its market position through specialization in high-performance variable geometry turbochargers for diverse engine platforms.
An automotive exhaust gas turbocharger is a turbine-driven forced induction device that increases an internal combustion engine's efficiency and power output. It uses exhaust gas flow to spin a turbine, which in turn drives a compressor wheel at speeds often exceeding 150,000 RPM. Electric Turbochargers represent the fastest-growing product type, aimed at eliminating turbo lag. The OEM channel continues to be the primary route to market for both variable geometry and wastegate turbocharger technologies.
Emissions regulations are the primary external force shaping product development and technology roadmaps. The US EPA, the EU with its Euro 7 framework, and China's Ministry of Ecology and Environment with its GB standards all mandate reductions in NOx and CO2. These rules compel the adoption of more efficient and complex turbocharging solutions. The key strategic decision for suppliers is allocating R&D capital between advancing ICE efficiency and pivoting to components for hybrid powertrains.
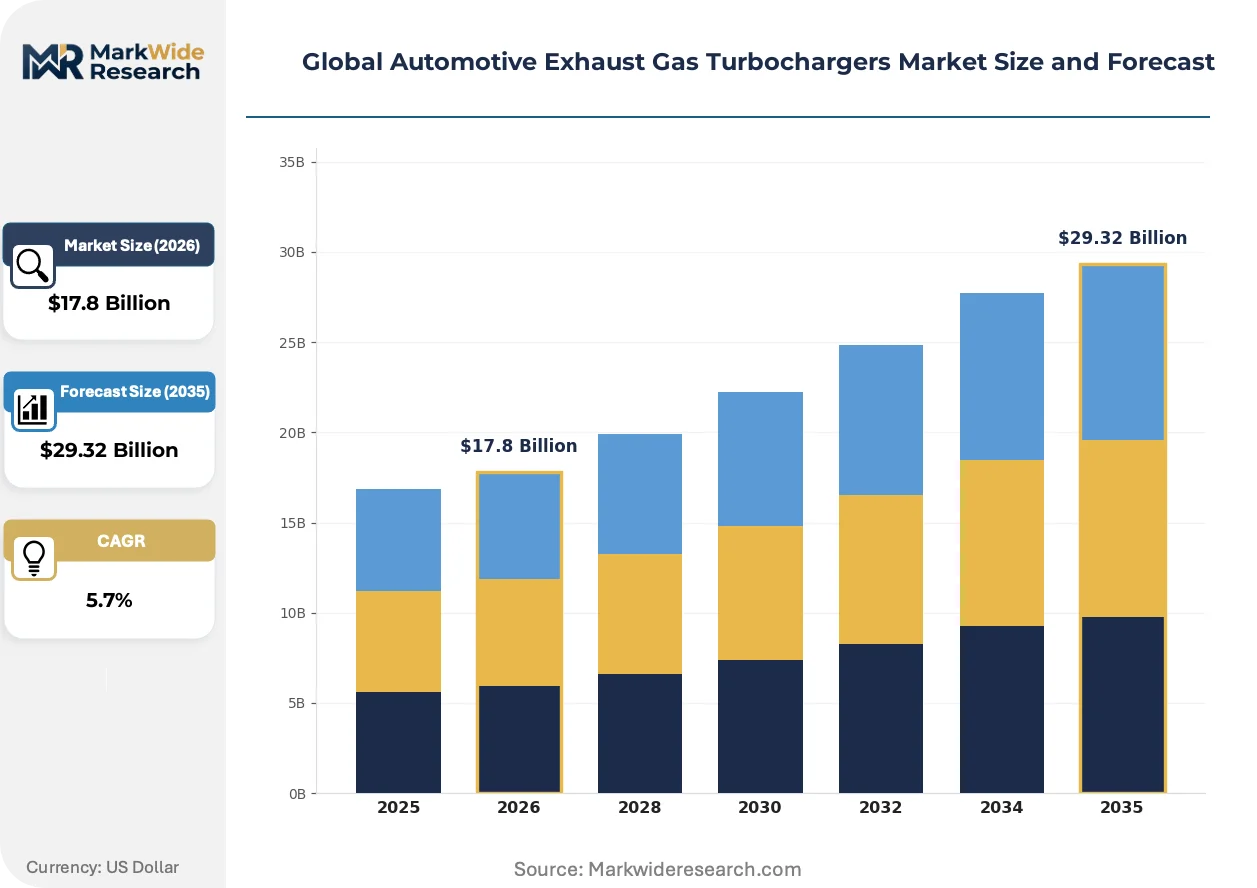
Market Dynamics
The central dynamic shaping the turbocharger market is the dual mandate placed on suppliers. They must invest heavily in advancing internal combustion engine efficiency to meet near-term emissions rules while simultaneously reallocating capital toward components for electrified powertrains.
Growth Catalysts
- Stringent Emissions Standards:Europe's Euro 7 framework and China's GB standards mandate lower NOx, compelling adoption of efficient variable geometry turbochargers.
- Light Commercial Vehicle Demand:Expanding logistics fleets in China require durable, fuel-efficient turbochargers to reduce operational costs for commercial vehicle operators.
- Hybrid Powertrain Integration:The adoption of 48V mild-hybrid systems creates a specific need for electric turbochargers to eliminate low-RPM turbo lag.
Market Restraints
- BEV Substitution Threat:The transition to battery electric vehicles presents a fundamental threat to the market, which depends on internal combustion engines.
- Input Material Volatility:Turbine wheels rely on nickel-based alloys, exposing manufacturers to significant price volatility and supply chain risks for the metal.
- Thermal Management Complexity:High heat from downsized engines creates significant thermal management challenges, impacting component longevity and complicating integration.
Strategic Opportunities
- Hydrogen Combustion Engines:Developing turbochargers for hydrogen internal combustion engines (H2-ICE) in heavy-duty trucks presents a new growth vector beyond traditional fuels.
- Performance Aftermarket Expansion:The high-margin performance tuning market in North America offers opportunities for specialized turbochargers and associated electronic control module upgrades.
- Circular Economy Models:Establishing remanufacturing programs for complex turbochargers creates new revenue streams and helps meet OEM sustainability objectives.
Industry Challenges
- Software Integration Complexity:Ensuring seamless, secure communication between the turbocharger's electronic control unit and the main vehicle ECU presents a significant software engineering and cybersecurity challenge.
- Specialized Engineering Talent:A scarcity of engineers with combined expertise in high-speed rotating machinery, power electronics, and control software hinders the development of advanced e-turbo systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Exhaust Gas Turbochargers Market |
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $29.32 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Variable Geometry Turbochargers, Twin-Scroll Turbochargers, Electric Turbochargers, Wastegate Turbochargers, Twin-Turbo Systems Technology: Ball Bearing, Journal Bearing, Variable Nozzle, Electrically Assisted, Ceramic Ball Bearing Application: Light Commercial Vehicles, Sports Cars, Passenger Vehicles, Heavy Duty Trucks, Agricultural Machinery End User: OEMs, Aftermarket Suppliers, Fleet Operators, Rental Agencies, Vehicle Refurbishers |
| Companies Covered | IHI Corporation, Cummins Inc., BorgWarner Inc., Mahle, Toyota Industries Corporation, Garrett Motion Inc., Continental AG, BMTS Technology GmbH & Co. KG, Mitsubishi Heavy Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Exhaust Gas Turbochargers Market Strategic Shifts & Innovations
The evolution of turbochargers reflects a fundamental shift from purely mechanical air pumps to integrated electromechanical systems. This change is driven by the need for precise boost control and immediate response to meet both performance demands and stringent emissions regulations.
Electric turbochargers use an integrated motor to pre-spool the compressor, eliminating lag. Premium and high-performance vehicle segments are the primary adopters for enhanced responsiveness. This technology is expanding into mainstream mild-hybrid powertrains, blurring the line between forced induction and electrification to improve overall drive cycle efficiency.
China's GB VI emissions standards impose strict real-world emissions testing and on-board diagnostic requirements. This regulation compels manufacturers of both light-duty and heavy-duty vehicles to use more sophisticated and durable turbocharging systems. The commercial vehicle segment is most affected, requiring components that maintain compliance over long service lives.
A shift is occurring in the aftermarket from purely mechanical replacements to software-enabled performance upgrades. This disrupts traditional garage and distributor channels, favoring suppliers who control both the hardware and the integrated software stack. This trend is most visible in the European and North American performance tuning communities.
Global Automotive Exhaust Gas Turbochargers Market Segmentation
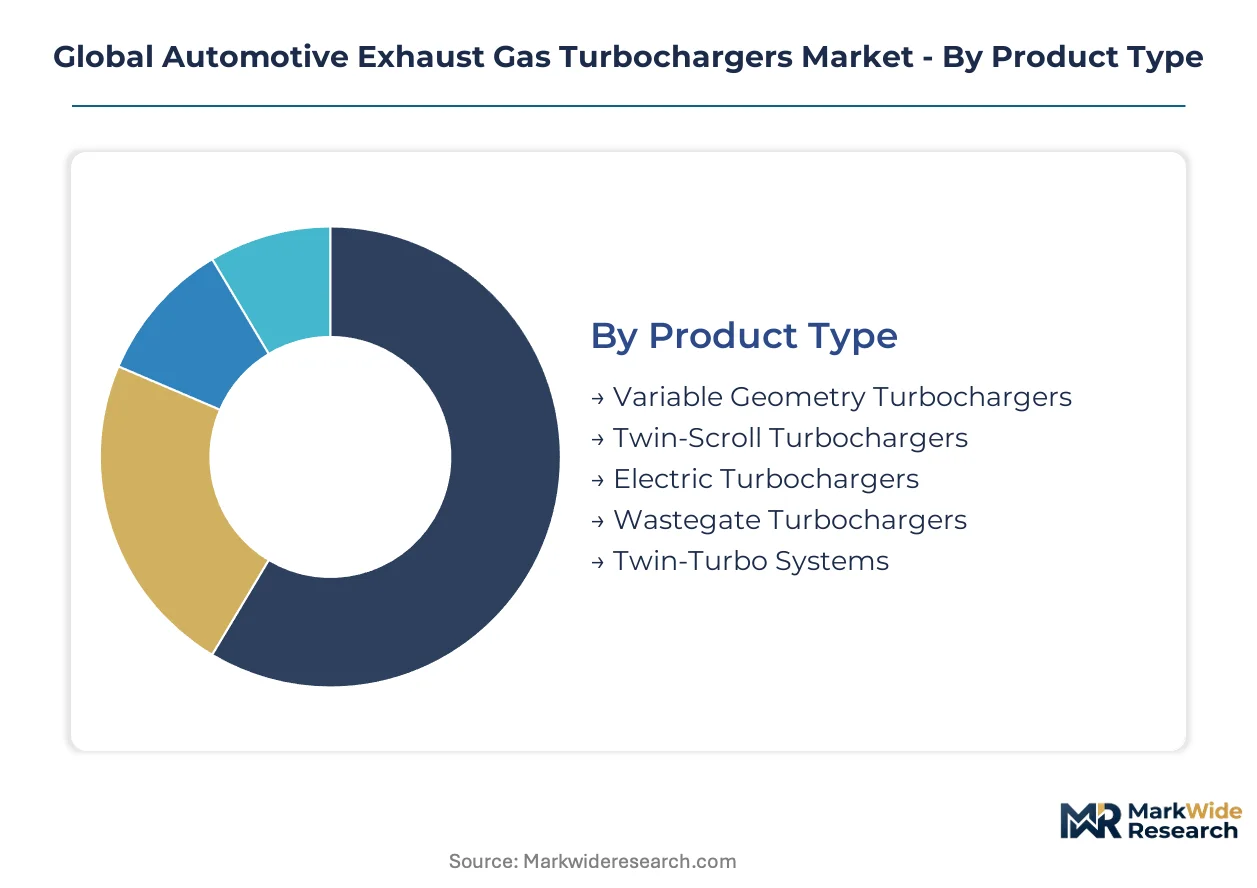
Segmentation provides a granular view of the Global Automotive Exhaust Gas Turbochargers Market, illuminating distinct demand patterns and technological requirements across various applications. This detailed breakdown helps stakeholders understand where innovation is concentrated and how different market forces shape product development and investment priorities.
Product Type:
The capital intensity of developing and manufacturing different turbocharger product types varies significantly, influencing supplier investment strategies.
- Variable Geometry Turbochargers:Feature adjustable vanes that alter exhaust gas flow to the turbine, optimizing boost across engine speeds. Their adoption is widespread in diesel engines in Europe and China, compelled by stringent NOx emission standards.
- Twin-Scroll Turbochargers:Separate exhaust pulses to the turbine, improving scavenging and reducing lag compared to single-scroll designs.
- Electric Turbochargers:Use an integrated electric motor to spool the compressor, eliminating turbo lag and providing immediate boost. Demand concentrates in premium and mild-hybrid vehicle segments, driven by the need for enhanced responsiveness and overall drive cycle efficiency.
- Wastegate Turbochargers:Incorporate a valve to bypass excess exhaust gas around the turbine, regulating boost pressure effectively.
- Twin-Turbo Systems:Employ two turbochargers, often in series or parallel configurations, to deliver broad power bands in high-performance engines.
Most installed capacity flows through Wastegate Turbochargers. Expansion is steepest in Electric Turbochargers.
Technology:
Turbocharger technologies are differentiated by their performance characteristics and suitability for specific engine demands, driving diverse engineering investments.
- Ball Bearing:Utilize rolling elements to reduce friction, allowing the turbine shaft to spin more freely and respond quicker to throttle inputs. These are preferred in performance-oriented applications and some premium passenger vehicles for their superior transient response.
- Journal Bearing:Rely on a thin film of oil for lubrication, offering a cost-effective and durable solution for many standard engine applications.
- Variable Nozzle:Employ movable vanes to optimize exhaust gas velocity and angle entering the turbine, enhancing efficiency and reducing emissions.
- Electrically Assisted:Integrate an electric motor with the turbocharger to provide immediate boost and eliminate lag, enhancing engine response. This technology finds primary application in hybrid powertrains and high-performance vehicles, addressing low-RPM torque requirements.
- Ceramic Ball Bearing:Incorporate ceramic balls for lighter weight and higher temperature resistance, further improving spool-up times in specialized high-performance units.
Higher margins are typically associated with Electrically Assisted technology. Volume production relies heavily on Journal Bearing technology.
Application:
The volume demand for turbochargers varies significantly across different vehicle applications, influencing manufacturing scale and design priorities.
- Light Commercial Vehicles:Require robust and fuel-efficient turbochargers to reduce operational costs for fleet operators, particularly in expanding logistics networks. This segment sees high demand in China, where stringent GB standards compel advanced turbocharging solutions.
- Sports Cars:Utilize high-performance turbochargers for maximum power output and rapid throttle response, often incorporating advanced materials and designs.
- Passenger Vehicles:Represent the largest volume segment for turbochargers, driven by engine downsizing trends and emissions regulations across global markets. Demand concentrates in compact and mid-size cars in China and Europe, aiming for fuel efficiency and performance.
- Heavy Duty Trucks:Demand durable and high-efficiency turbochargers capable of sustaining heavy loads and long operating hours, crucial for freight transport.
- Agricultural Machinery:Employ turbochargers to boost engine power and torque for demanding field operations, enhancing productivity in farm equipment.
Regulatory compliance is most acutely felt in Heavy Duty Trucks. Innovation cycles are fastest in Sports Cars.
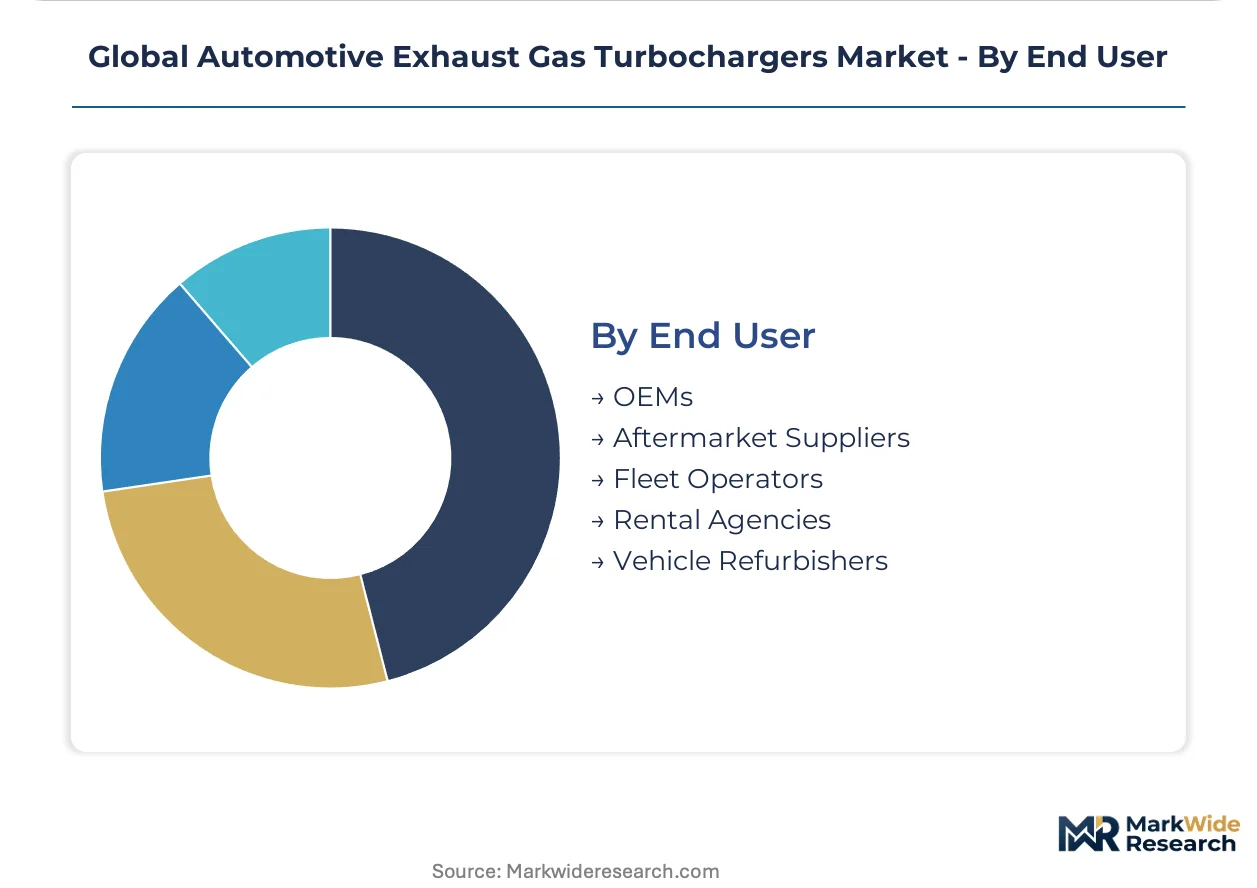
End User:
Supply concentration varies among end-user segments, reflecting distinct procurement models and distribution channels for turbocharger components.
- OEMs:Represent the primary route to market for new turbocharger units, integrating them directly into vehicle production lines. Their procurement strategies prioritize long-term supply agreements and co-development partnerships to meet specific engine requirements.
- Aftermarket Suppliers:Provide replacement turbochargers and performance upgrade kits for vehicles already in operation, catering to repair and tuning markets. This segment is growing in North America and Europe, driven by demand for enhanced vehicle performance.
- Fleet Operators:Purchase turbochargers for maintenance and repair of their commercial vehicle fleets, focusing on durability and cost-effectiveness.
- Rental Agencies:Require reliable and easily maintainable turbochargers for their diverse vehicle fleets, ensuring consistent operation and minimal downtime.
- Vehicle Refurbishers:Source turbochargers for restoring and upgrading older vehicles, often seeking cost-effective or specialized components.
The largest volume of turbochargers is consumed by OEMs. Aftermarket Suppliers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's automotive production volume significantly contrasts with Germany's focus on high-performance and premium segments for turbochargers. Both nations face stringent emissions mandates compelling technological advancements. Demand for efficient forced induction systems remains high in their respective markets.
China
China's vast automotive manufacturing base drives significant demand for robust turbochargers, particularly in light commercial vehicles. The Ministry of Ecology and Environment's GB VI emissions standards compel the adoption of sophisticated turbocharging solutions. Automotive manufacturing hubs in Shanghai and Guangzhou actively integrate advanced systems to meet these regulatory requirements. This ensures vehicles maintain compliance over long service lives.
Germany
Germany's premium automotive sector requires high-performance turbochargers for enhanced responsiveness and efficiency. The European Union's Euro 7 framework necessitates advanced solutions to reduce NOx and CO2 emissions. Engineering centers in Bavaria and Baden-Württemberg are at the forefront of developing electrically assisted turbocharger technologies. These innovations support the country's leading car manufacturers.
United States
The United States market exhibits strong demand for performance aftermarket turbochargers and robust units for heavy-duty trucks. US EPA regulations drive the need for improved fuel efficiency and lower emissions across vehicle categories. Detroit and other automotive research centers focus on integrating advanced turbocharging into new engine designs. This includes solutions for alternative fuels.
Japan
Japan's automotive industry prioritizes fuel efficiency and hybrid powertrain integration, creating specific demand for compact and efficient turbochargers. The country's stringent environmental regulations encourage continuous innovation in engine efficiency technologies. Manufacturers in Toyota City and other major production sites are actively developing advanced turbocharger designs. These designs support the next generation of hybrid vehicles.
Global Automotive Exhaust Gas Turbochargers Market Key Industry Players
Top-tier vendors anchor the premium and high-performance segments, while a broader base of suppliers competes in the volume-driven aftermarket. The market structure features a mix of established automotive component giants and specialized turbocharger manufacturers. Strategic archetypes include vertically integrated OEMs, independent technology specialists, and regional aftermarket providers. Competitive moves center on technology licensing and strategic partnerships to develop next-generation e-turbo systems.
Within the advanced technology tier, BorgWarner Inc. represents a major automotive supplier leveraging its electrification expertise to develop sophisticated e-turbo systems. Garrett Motion Inc. occupies a position as a specialist in high-performance variable geometry turbochargers, serving diverse engine platforms globally. German-based Continental AG, a diversified automotive technology company, also contributes significantly to the market, focusing on integrated solutions. These entities anchor innovation in boost control and integrated electronics, driving the shift beyond traditional hardware. Their strategies often involve extensive R&D to meet evolving emissions standards and hybrid powertrain demands across various vehicle applications.
| Leading Market Players |
|---|
| IHI Corporation |
| Cummins Inc. |
| BorgWarner Inc. |
| Mahle |
| Toyota Industries Corporation |
| Garrett Motion Inc. |
| Continental AG |
| BMTS Technology GmbH & Co. KG |
| Mitsubishi Heavy Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Original Equipment Manufacturers (OEMs) concentrate demand for new turbocharger units, establishing long-term supply agreements that drive contract-based pricing models. This procurement approach prioritizes stability and co-development over spot market fluctuations.
Pricing Analysis
Capacity additions in China are reshaping price floors for volume-driven turbocharger units. Pricing for new turbochargers primarily operates on a contract-based long-term offtake model with OEMs, driven by customization level and performance specifications. Aftermarket suppliers utilize per-unit transactional pricing, where brand premium and after-sales service differentiate offerings. Pricing softness stems from the looming threat of battery electric vehicle substitution. Fleet operators exhibit the highest price sensitivity, while premium vehicle manufacturers prioritize performance.
Supply Chain Analysis
Dual-sourcing requirements often mandated by OEMs mitigate supply chain risks for critical turbocharger components. Supply concentration centers on automotive manufacturing hubs in China, Germany, and Japan. The production of turbine wheels depends on nickel-based alloys, exposing manufacturers to significant input material volatility. Integrated electronics and control units are also critical dependencies. Distribution primarily runs through the OEM channel, with aftermarket suppliers gaining share in replacement and performance upgrade markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global automotive exhaust gas turbochargers market presents a geographic-arbitrage play, leveraging lower manufacturing costs in China against the premium technology demands driven by Europe's Euro 7 framework. This dynamic allows for differentiated product strategies across regions.
For Market Incumbents: Lock in long-term supply agreements with major OEMs for next-generation e-turbo systems to counter the BEV substitution threat. Investing heavily in R&D for hydrogen combustion engine (H2-ICE) turbochargers provides a new growth vector. Deepen vertical integration into power electronics and control software to manage software integration complexity. Expand production capacity for advanced variable geometry turbochargers in key markets like China.
For New Entrants and Emerging Players: Specialized performance tuning communities in North America represent an underserved buyer archetype for advanced turbocharger solutions. Target the high-margin performance aftermarket with bundled software-enabled upgrades and specialized hardware. Establish remanufacturing programs for complex turbochargers, providing a cost-effective option for fleet operators. Focus on developing niche solutions for hydrogen combustion engines to avoid direct competition with established players.
For Investors and Strategic Acquirers: Major automotive component suppliers are the most active acquirers in this space, seeking to bolster electrification and software capabilities. Focus on independent technology specialists with expertise in e-turbo control software, power electronics, or advanced thermal management solutions. The long-term viability of hybrid powertrains and hydrogen combustion engines will sustain this market for the next 5-10 years. OEM announcements regarding next-generation hybrid or H2-ICE platform commitments serve as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop advanced e-turbo systems for 48V mild-hybrids | This initiative meets demand for immediate boost and drive cycle efficiency in mainstream hybrid powertrains. |
| Expand remanufacturing programs for complex turbochargers | Establishing circular economy models creates new revenue streams and supports OEM sustainability objectives. |
| Invest in R&D for hydrogen combustion engine turbochargers | This opens a new growth vector for heavy-duty trucks beyond traditional internal combustion fuels. |
| Secure long-term supply agreements with major OEMs | These agreements ensure stable demand and co-development opportunities for next-generation turbocharger technologies. |
| Enhance software integration for boost control and OTA updates | This shifts the value proposition beyond hardware, demanding expertise in integrated electronics and control units. |
Research Approach
Direct dialogue with OEM platform engineers, Tier 1 procurement leads, aftermarket distributors, and engine R&D directors informed this analysis. Primary interviews were combined with extensive secondary research for validation. Secondary data sources included vehicle production databases, IHS Markit registration data, and relevant industry reports. A bottom-up and top-down triangulation approach ensured robust market sizing.
A bottom-up approach, validated by top-down market sizing, guided the forecast across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and regional production cluster. Compound annual growth rates were derived from historical trends and future projections, incorporating key forecast inputs like evolving emissions standards and vehicle electrification roadmaps.
Underlying measurement precision varies by segment; OEM and Passenger Vehicles carry tighter precision than others. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates. Deviation in battery electric vehicle adoption rates or geopolitical shifts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Europe Turbocharger Market
Powertrain
Spark Plugs Market
Powertrain
Automotive Balance Shaft Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
Automotive Conversion Kit Market
Powertrain
India Automotive Engine Oils Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Automotive Water Pump Market
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
Global Automotive Powertrain Systems Market
Powertrain
Clutch Friction Plate Market
Powertrain
Iridium Spark Plug Market
Powertrain
Automotive Coil Spring Market
Powertrain
Diesel Engine Market