
 Japan Ceramic Ball Bearings Market | 2026-2036
Japan Ceramic Ball Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Ceramic Ball Bearings Market Intelligence
Modular bearing cartridge systems is rebalancing procurement patterns across Japanese precision equipment builders. NSK Ltd. leverages captive ceramic powder processing to control silicon nitride purity grades from raw material through finished component. JTEKT Corporation anchors its position through integrated spindle-bearing assemblies for machine tool OEMs. Tsubaki Nakashima specializes in sub-micron grade balls for dental handpiece and surgical robot applications.
Japan ceramic ball bearings are rolling-element bearings utilizing precision-machined ceramic spheres, typically silicon nitride with fracture toughness exceeding six MPa·m½, seated within steel or hybrid rings to achieve operating speeds twenty to forty percent beyond conventional steel equivalents while eliminating electric pitting in motor applications. Their primary purpose centers on extreme-duty environments where corrosion resistance, thermal stability, or electrical insulation proves critical to equipment longevity. Deep groove configurations occupy the largest volume share due to standardized dimensional interchangeability across robotics and pump rebuild programs. Aerospace applications within the industry vertical dimension command premium positioning through JIS B 1514 precision class requirements and extended qualification cycles. Silicon nitride material grades sustain the broadest adoption across medical device and high-speed equipment applications given established supply chain maturity and proven failure-mode predictability.
METI administers industrial standards coordination through JIS certification pathways, while PMDA governs biocompatibility and sterilization compatibility for bearings deployed in surgical instrumentation and diagnostic imaging equipment. The Ministry of Economy, Trade and Industry also oversees carbon-neutrality-linked procurement incentives that favor domestic ceramic component sourcing in public infrastructure bids. Stakeholders must track evolving JIS precision class revisions and PMDA material submission requirements as hybrid bearing architectures penetrate semiconductor lithography and proton therapy equipment segments.
Market Dynamics
METI's semiconductor equipment localization mandate is compressing certification timelines for ceramic bearing suppliers serving lithography and wafer-handling systems across the Kansai industrial corridor.
Growth Catalysts
- Silicon nitride servo integration:Precision robotics manufacturers in Osaka and Nagoya are expanding procurement of ceramic bearings for high-speed motor assemblies, driven by JIS B 1514 precision class requirements for next-generation automation.
- Carbon-neutrality procurement incentives:METI-linked public infrastructure bids now favor domestic ceramic component sourcing, redirecting capital toward localized silicon nitride powder processing and finished bearing production.
- Medical device sterilization standards:PMDA biocompatibility pathways for surgical robots and diagnostic imaging equipment are mandating ceramic bearing architectures that eliminate electric pitting and corrosion failure modes.
Market Restraints
- Silicon nitride powder supply concentration:Captive production of high-purity ceramic powder remains concentrated among integrated manufacturers, limiting independent bearing producers' margin flexibility and batch consistency.
- JIS precision class revision friction:Evolving dimensional tolerance requirements for hybrid bearing architectures create requalification costs and design freeze delays for semiconductor equipment OEMs.
- Steel bearing cost substitution:Conventional steel rolling-element bearings retain price advantage in non-critical speed applications, compressing ceramic penetration in pump rebuild and general industrial maintenance markets.
Strategic Opportunities
- Proton therapy equipment certification:PMDA material submission pathways for radiation-resistant bearing systems in particle accelerator gantries remain underdeveloped, creating first-mover advantage for qualified suppliers.
- Dental handpiece sub-micron grade expansion:Surgical instrument manufacturers in the Kansai corridor are specifying ceramic ball tolerances below 0.25 micrometers for high-speed turbine applications.
- Modular cartridge system adoption:Machine tool OEMs are standardizing integrated spindle-bearing assemblies that simplify field replacement and reduce mean-time-to-repair in precision machining centers.
Industry Challenges
- Ceramic powder metallurgy talent scarcity:Fracture toughness optimization for silicon nitride grades exceeding six MPa·m½ requires specialized materials engineers concentrated among legacy suppliers.
- Extended aerospace qualification cycles:JIS B 1514 precision class certification for flight-critical applications demands multi-year testing protocols that strain working capital for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Ceramic Ball Bearings Market |
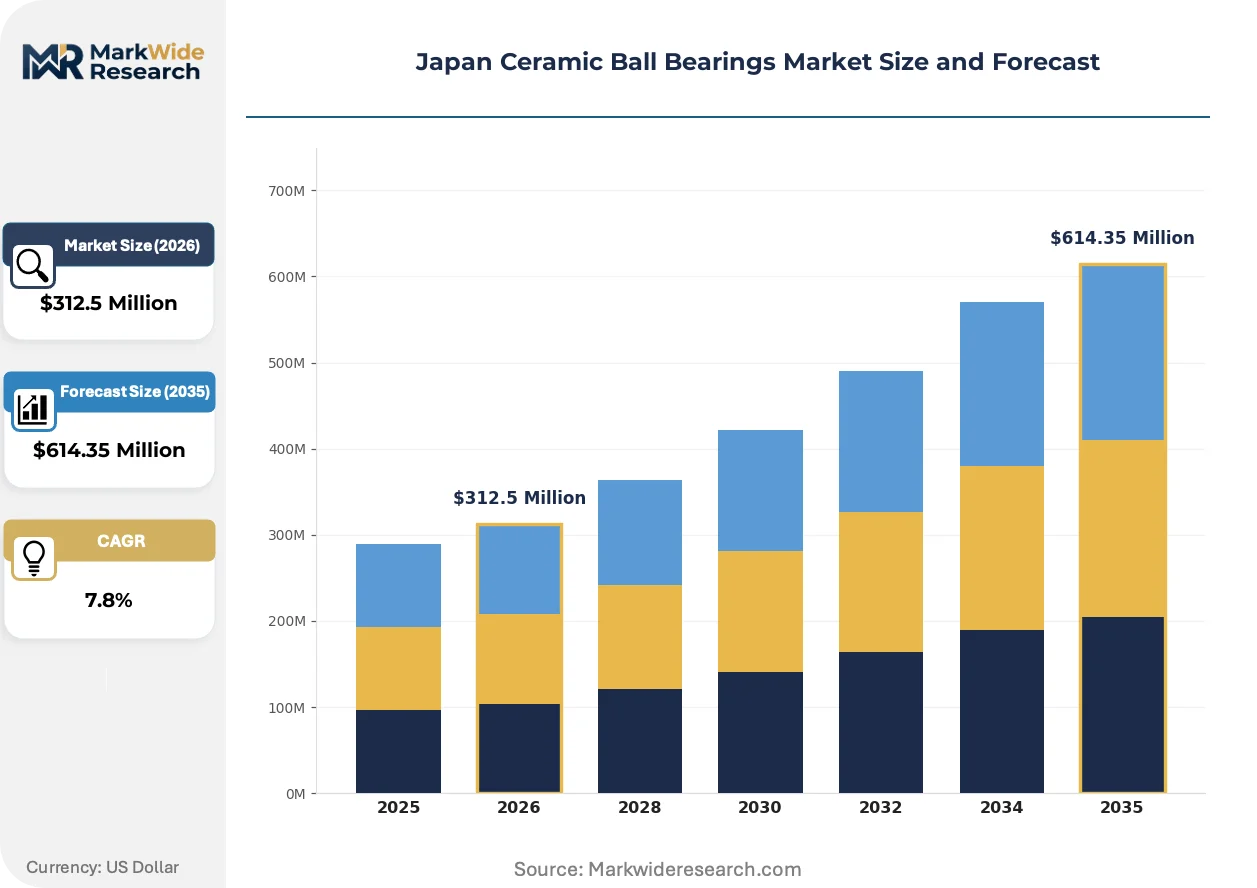
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $614.35 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angular Contact, Deep Groove, Thrust, Self-Aligning Industry Vertical: Aerospace, Automotive OEMs, Electrical Equipment, Marine Material: Silicon Nitride, Zirconia, Alumina, Composite Application: Robotics, Medical Devices, High-Speed Equipment, Pumps |
| Companies Covered | Tipton Corp., NSK Ltd., Tsubaki Nakashima, JTEKT Corporation, NTN Corporation, Niterra, Toshiba Materials, Nachi-Fujikoshi Corp., Amatsuji Steel Ball, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Ceramic Ball Bearings Market Strategic Shifts & Innovations
Hybrid ceramic-steel bearing architectures are compressing traditional procurement boundaries between component suppliers and finished equipment builders across Japanese precision manufacturing.
Silicon nitride rolling elements with engineered surface finishes are decentralizing maintenance scheduling for semiconductor lithography equipment. Wafer-handling system OEMs in Kyoto and Osaka are specifying these bearings for continuous-duty vacuum environments. The technology is decentralizing service contract structures from calendar-based to condition-based replacement models.
METI's domestic supply chain reinforcement policies are accelerating material traceability requirements for ceramic bearings deployed in public infrastructure. Equipment builders must now document silicon nitride powder origin through finished component for carbon-neutrality-linked procurement scoring. Semiconductor lithography and proton therapy equipment segments face the steepest compliance curve under these revised submission protocols.
Consolidated procurement by precision robotics manufacturers is compressing vendor counts for ceramic bearing supply. Machine tool and automation OEMs in the Kansai corridor are qualifying single-source integrated spindle-bearing assemblies rather than discrete component sourcing. This concentration is most visible among servo motor assemblers serving medical device and semiconductor capital equipment verticals.
Japan Ceramic Ball Bearings Market Segmentation
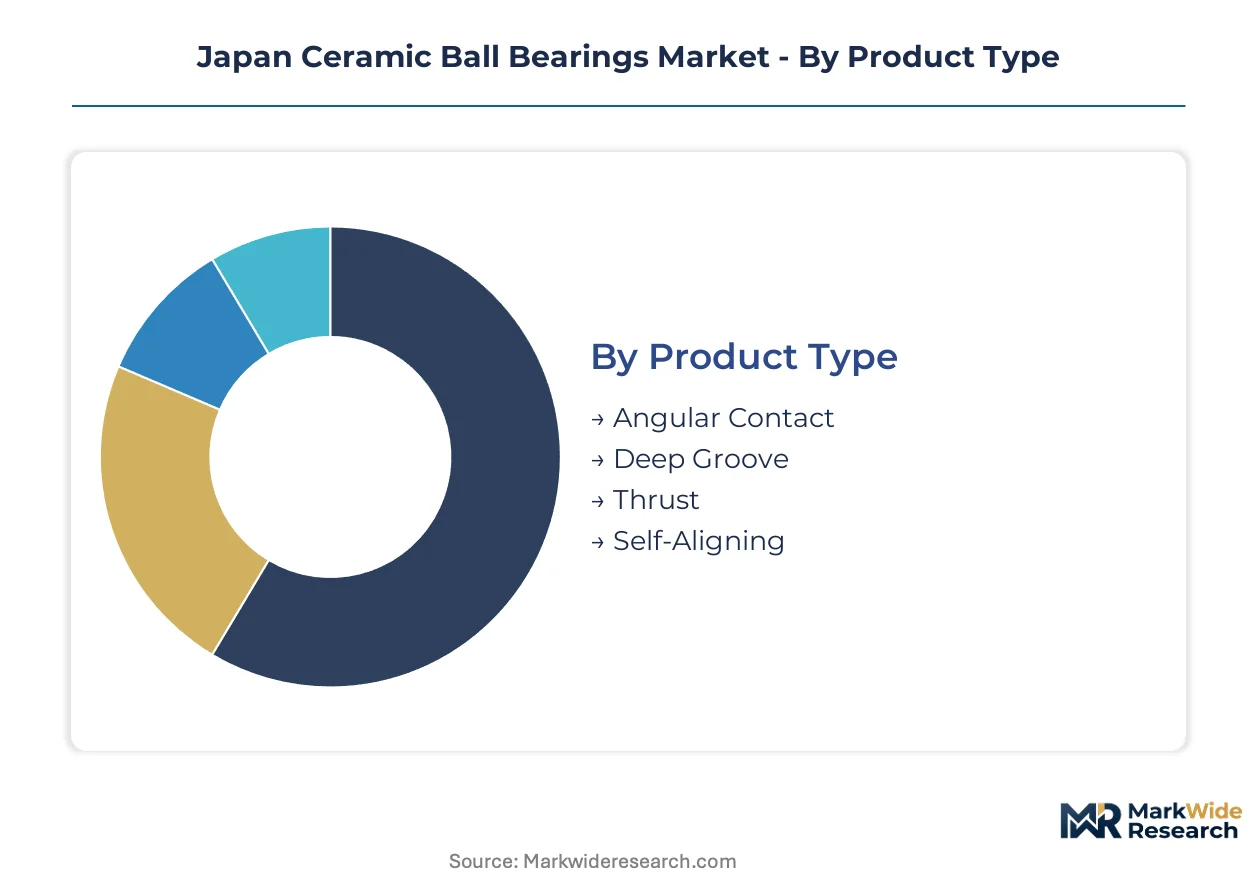
Segmentation in the Japan ceramic ball bearings market reveals how procurement specifications diverge across precision equipment verticals. Each dimension—product geometry, end-use industry, ceramic chemistry, and duty cycle—creates distinct certification and sourcing requirements for suppliers serving the Kansai industrial corridor.
Product Type:
Standardization dominates at the commodity tier while angular contact variants demand application-specific preload engineering for high-speed spindles.
- Deep Groove:These bearings accommodate combined radial and axial loads through standardized dimensional interchangeability. Robotics manufacturers in Osaka specify deep groove configurations for servo motor rebuild programs where field replacement compatibility reduces inventory complexity.
- Angular Contact:Designed for simultaneous radial and thrust load absorption through optimized contact angle geometry. Machine tool OEMs in Nagoya integrate these into motorized spindle assemblies where thermal stability and rotational precision determine machining accuracy.
- Thrust:Axial-load-only configurations for vertical shaft arrangements in pump and compressor systems.
- Self-Aligning:Compensate for mounting misalignment in marine propulsion and heavy equipment applications.
Leading the category by volume: Deep Groove. Expanding most quickly: Angular Contact.
Industry Vertical:
Margin concentration follows certification burden, with aerospace and medical device applications commanding premium positioning through extended qualification protocols.
- Aerospace:JIS B 1514 precision class requirements and multi-year failure-mode testing govern flight-critical bearing deployments. Component suppliers must demonstrate silicon nitride fracture toughness exceeding six MPa·m½ under thermal cycling regimes.
- Medical Devices:PMDA biocompatibility pathways mandate ceramic architectures that eliminate electric pitting in surgical robots and diagnostic imaging equipment. Sterilization compatibility for autoclave and gamma radiation exposure drives material grade selection.
- Automotive OEMs:Electric vehicle motor applications leverage ceramic insulation properties against bearing currents.
- Electrical Equipment:High-frequency motor and generator applications prioritize electrical isolation.
- Marine:Corrosion resistance in saltwater environments favors ceramic rolling elements.
Highest certification barrier: Aerospace. Steepest demand trajectory: Medical Devices.
Material:
Supply chain maturity determines adoption velocity, with silicon nitride grades benefiting from established powder processing infrastructure in the Kansai region.
- Silicon Nitride:Fracture toughness above six MPa·m½ combined with thermal shock resistance enables operating speeds twenty to forty percent beyond steel equivalents. METI's domestic sourcing incentives favor localized powder production for semiconductor equipment supply chains.
- Zirconia:Transformation toughening mechanisms deliver superior wear resistance in dental handpiece turbines where sub-micron ball tolerances below 0.25 micrometers are specified.
- Alumina:Cost-effective ceramic for moderate-speed pump and general industrial applications.
- Composite:Hybrid ceramic-matrix formulations for specialized radiation-resistant environments.
Dominant by procurement volume: Silicon Nitride. Gaining share fastest: Zirconia.
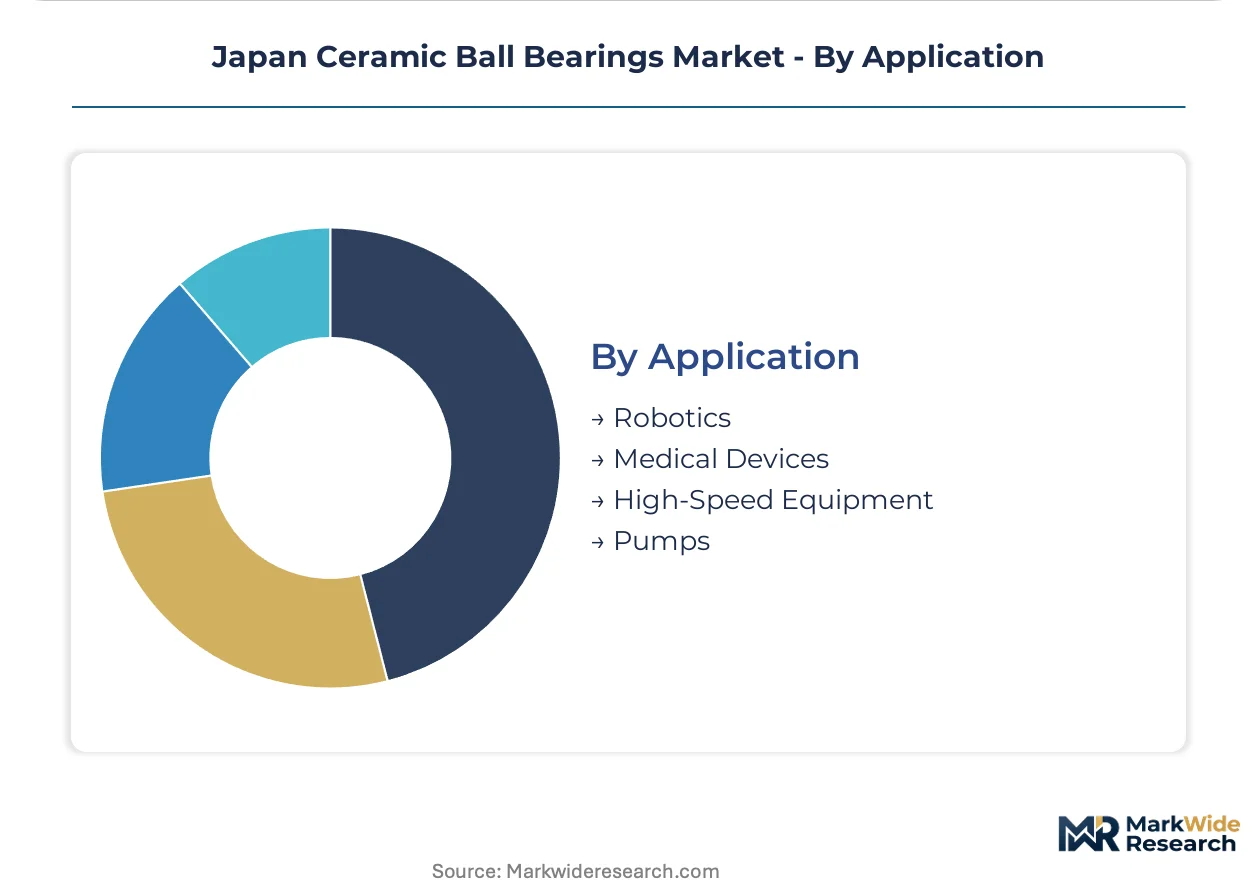
Application:
Duty cycle intensity separates premium ceramic specifications from standard-grade alternatives across Japanese precision manufacturing.
- Robotics:Servo motor assemblies in precision automation require JIS B 1514 precision class bearings for positioning repeatability. Manufacturers in Osaka and Nagoya are consolidating vendor counts for integrated spindle-bearing cartridges.
- High-Speed Equipment:Continuous-duty vacuum environments in semiconductor lithography demand engineered surface finishes that extend maintenance intervals beyond calendar-based replacement schedules.
- Medical Devices:Surgical instrument and diagnostic imaging applications.
- Pumps:Chemical and process industry rebuild programs.
Procurement concentration highest: Robotics. Condition-based maintenance adoption fastest: High-Speed Equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production capacity concentrates in the Kansai industrial corridor while consumption spreads across precision manufacturing clusters nationwide. METI's supply chain localization policies are redirecting investment toward domestic silicon nitride powder processing. Regional demand patterns reflect the geographic distribution of robotics, semiconductor equipment, and medical device manufacturers.
Kanto/Tokyo
Precision equipment headquarters and R&D centers drive specification-setting for ceramic bearing architectures. METI administers JIS certification pathways through standards bodies in the capital region. Medical device manufacturers in Tokyo and Saitama prefectures are mandating PMDA-compliant ceramic bearings for surgical robot motor assemblies.
Kansai/Osaka
Machine tool OEMs and servo motor assemblers anchor procurement volume for angular contact and deep groove configurations. The Ministry of Economy, Trade and Industry oversees carbon-neutrality-linked procurement incentives favoring domestic ceramic component sourcing. Robotics manufacturers spanning Kyoto, Osaka, and Hyogo prefectures are consolidating vendor counts for integrated spindle-bearing cartridges.
Chubu/Nagoya
Automotive and industrial automation supply chains generate demand for high-speed motor bearing applications. METI's semiconductor equipment localization mandate is compressing certification timelines for suppliers serving lithography systems. Precision component fabricators in Aichi and Gifu prefectures are expanding silicon nitride bearing integration into next-generation automation equipment.
Kyushu
Semiconductor fabrication facilities and related capital equipment suppliers create demand for vacuum-compatible bearing systems. Regional industrial policy supports domestic material traceability requirements for public infrastructure bids. Bearing distributors in Fukuoka and Kumamoto are positioning to serve the qualification needs of wafer-handling system OEMs.
Tohoku
Advanced materials research institutions and specialized powder metallurgy operations support upstream ceramic supply chain development. National technology programs fund fracture toughness optimization for silicon nitride grades exceeding six MPa·m½. Materials engineering talent concentrated in Sendai and surrounding prefectures underpins domestic powder processing capabilities.
Japan Ceramic Ball Bearings Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across Japan's ceramic ball bearings market. Integrated manufacturers controlling captive silicon nitride powder processing command supply security advantages over independent bearing producers. Three archetypes dominate: vertically integrated material-to-component suppliers, precision assembly specialists, and sub-tier component fabricators. Competitive dynamics center on JIS certification speed and PMDA biocompatibility pathway navigation rather than price alone.
Within the integrated manufacturer tier, NSK Ltd., JTEKT Corporation, and Tsubaki Nakashima occupy positions defined by upstream control over ceramic powder purity grades. These companies exemplify the captive production model that METI's domestic sourcing incentives favor. Independent specialists including NTN Corporation and Nachi-Fujikoshi Corp. represent alternative archetypes competing through precision assembly expertise and application-specific qualification speed. The competitive terrain rewards first-mover advantage in underdeveloped segments such as proton therapy equipment certification and sub-micron grade dental handpiece bearings.
| Leading Market Players |
|---|
| Tipton Corp. |
| NSK Ltd. |
| Tsubaki Nakashima |
| JTEKT Corporation |
| NTN Corporation |
| Niterra |
| Toshiba Materials |
| Nachi-Fujikoshi Corp. |
| Amatsuji Steel Ball |
| Others |
Cost & Logistics Intelligence
Captive silicon nitride powder processing anchors supply security and pricing power for integrated Japanese bearing manufacturers serving METI's domestic procurement mandates. NSK Ltd. and JTEKT Corporation leverage in-house ceramic purity control from raw material through finished component, insulating margin structures from independent producers dependent on external powder supply.
Pricing Analysis
Margin tightening in standard-grade deep groove configurations traces to steel bearing substitution pressure in pump rebuild and general industrial maintenance markets. Pricing stratifies across JIS B 1514 precision class tiers, with aerospace and medical device certifications commanding substantial premiums over commodity robotics specifications. Cost-down pressure on independent bearing producers accelerates because captive powder supply concentrates among integrated conglomerates. Automotive OEMs and pump rebuild contractors exhibit highest price sensitivity, while semiconductor lithography equipment builders prioritize qualification speed over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from precision robotics manufacturers in Osaka and Nagoya mandate multi-supplier qualification for integrated spindle-bearing cartridges. Silicon nitride powder supply draws from Japan's Kansai corridor and select South Korean ceramic metallurgy specialists, with zirconia feedstocks increasingly sourced from Chinese transformation-toughening processors. Single-source vulnerability concentrates in sub-micron grade ball production for dental handpiece applications. Distribution runs through authorized industrial distributors serving machine tool OEMs and medical device contract manufacturers, with direct procurement relationships dominating high-volume servo motor assembly accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream ceramic powder control and downstream PMDA certification speed determine competitive survival. Players are pursuing backward integration into silicon nitride feedstock processing to secure METI-linked public infrastructure bids.
For Market Incumbents: Hedge against independent powder supply disruption by expanding captive ceramic metallurgy capacity in Hyogo prefecture. Consolidate vendor relationships with machine tool OEMs through modular cartridge system standardization. JIS precision class revision cycles threaten requalification cost burdens; accelerate design freeze coordination with semiconductor equipment builders to preempt compliance friction. For New Entrants and Emerging Players: Sub-micron zirconia grade specialization for dental handpiece turbines offers the most penetrable white-space target, with tolerance specifications below 0.25 micrometers still underserved by incumbent portfolios. Proton therapy equipment certification pathways remain underdeveloped, creating first-mover advantage for radiation-resistant bearing system qualification. Pursue technology licensing partnerships with Tohoku-based materials research institutions to bypass fracture toughness optimization talent scarcity. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified industrial conglomerates seeking precision component platform expansion. Long-term viability favors vertically integrated manufacturers controlling silicon nitride purity grades from powder through finished bearing. Watch PMDA material submission requirement expansion into semiconductor lithography segments as inflection indicator for certification-speed valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Silicon Nitride Powder Processing | Secures METI domestic sourcing compliance and insulates margin from feedstock volatility. |
| JIS B 1514 Precision Class Certification Investment | Accelerates qualification timelines for aerospace and semiconductor equipment OEM procurement. |
| Modular Cartridge System Development | Reduces machine tool OEM field replacement complexity and consolidates vendor relationships. |
| PMDA Biocompatibility Pathway Navigation | Unlocks surgical robot and diagnostic imaging equipment segments with sterilization-compatible architectures. |
| Sub-Micron Grade Ball Production Scale-Up | Captures dental handpiece turbine specifications below 0.25 micrometer tolerances in Kansai corridor. |
Research Approach
Trade publications, JIS standards documentation, and METI industrial policy filings formed the secondary backbone for market sizing and regulatory trajectory assessment. Primary interviews with precision equipment procurement managers, ceramic powder metallurgy engineers, and medical device regulatory affairs specialists validated demand assumptions and certification timeline estimates. Bottom-up unit economics from bearing manufacturer disclosures combined with top-down industrial automation capex analysis to triangulate market value.
Bottom-up modeling segmented the market by product geometry, ceramic chemistry, and end-use vertical across the analysis window. Top-down validation cross-checked aggregate demand against robotics, semiconductor equipment, and medical device production forecasts from national industrial statistics. CAGRs derived from regression analysis of historical procurement patterns and policy-driven localization incentives. Fracture toughness specification evolution and PMDA submission requirement changes served as key forecast sensitivity inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated METI supply chain mandates or delayed JIS precision class revision implementation. Forecasts reflect documented assumptions regarding silicon nitride powder supply concentration and medical device sterilization standard adoption. A model refresh is warranted upon material change in METI carbon-neutrality procurement scoring protocols or PMDA biocompatibility pathway expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Windshield Repair Kit Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market
Automotive Parts
Argentina Automotive Lubricants Market
Automotive Parts
Apron Bus Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Colombia Passenger Vehicles Lubricants Market
Automotive Parts
Electric Power Steering System (EPS) Market
Automotive Parts
Automotive Spacer Ring Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Automotive Bearing Seals Market
Automotive Parts
Rear Spoiler Market
Automotive Parts
Automotive Axle and Propeller Shaft Market
Automotive Parts
India Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Daytime Running Lights Market
Automotive Parts
Global Automotive Differential System Market