
 Centrifugal Industrial Dryer Market | 2026-2036
Centrifugal Industrial Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Centrifugal Industrial Dryer Market Intelligence
The integration of IoT-enabled sensors and predictive maintenance algorithms is fragmenting the traditional market for standalone industrial drying equipment. This shift favors suppliers who can offer connected, data-rich systems. Gala Industries leverages its specialization in polymer drying to offer advanced process controls. Rosler Oberflachentechnik differentiates through its focus on integrated surface finishing solutions, while Sukup Manufacturing anchors its position in the agricultural sector with robust, large-scale drying systems.
A centrifugal industrial dryer is a mechanical dewatering machine that uses high rotational speeds to separate liquids from solid materials through centrifugal force. These systems are engineered to achieve specific final moisture content, often below 1%, by subjecting the material to high g-forces. Within applications, the chemical processing segment commands a significant share due to stringent purity requirements. High-speed product types are seeing accelerated use, driven by demand for increased throughput in food processing and metal finishing.
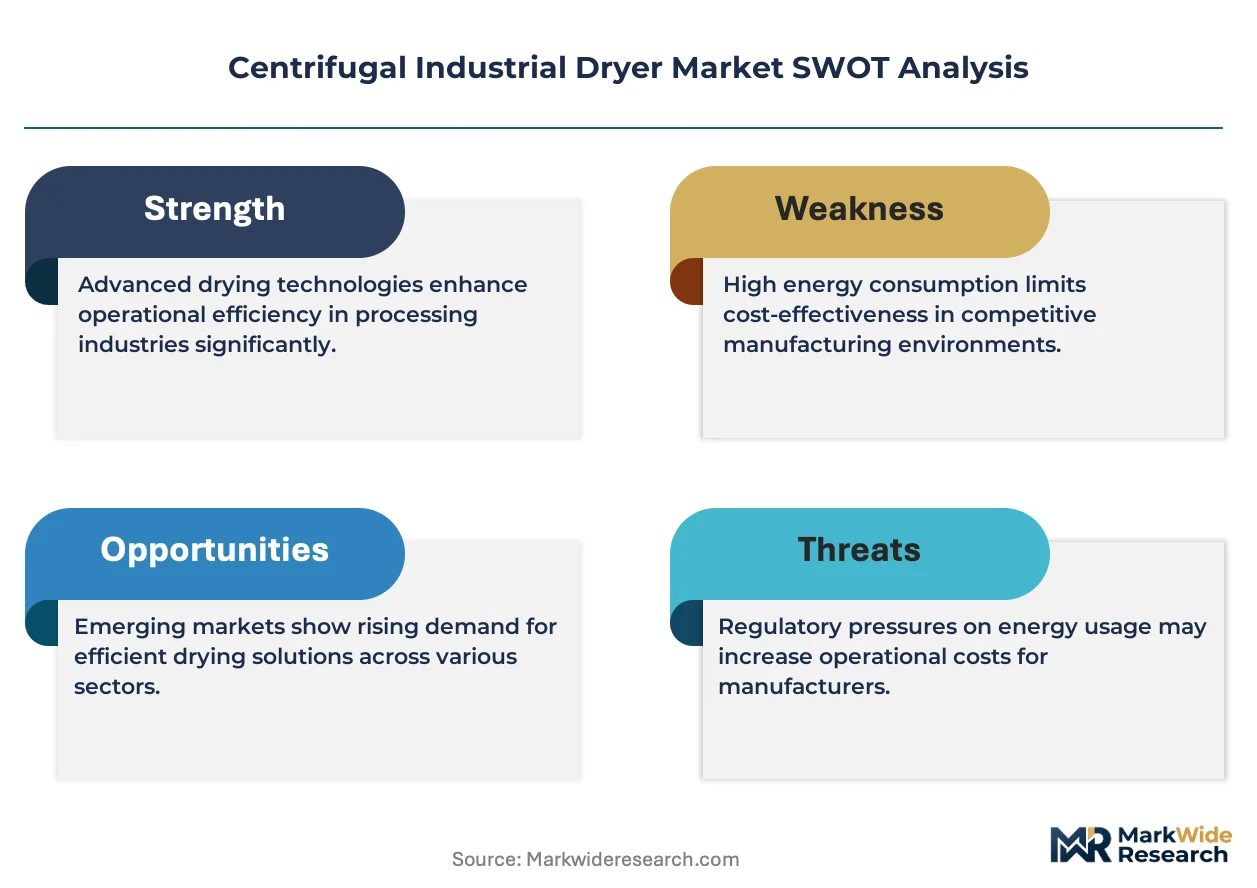
Equipment design and market access are governed by a complex web of regional standards, including the EU's CE marking for machinery safety and OSHA regulations in the United States. In China, compliance with GB standards for industrial machinery is mandatory for all manufacturers. Future competitive advantage will hinge on the ability to engineer systems that meet diverging regional energy efficiency mandates and material handling protocols.
Market Dynamics
The primary force shaping the market is the transition from standalone mechanical dewatering units to integrated, data-enabled systems. This shift is driven by end-user demand for process optimization and predictive analytics, particularly in high-purity sectors.
Growth Catalysts
- Food Safety Regulations:Mandates from the FDA in the US and FSSAI in India require sanitary, closed-loop dryers, driving adoption in food processing to prevent ingredient contamination.
- Clean-in-Place (CIP) Integration:The incorporation of automated CIP systems enables faster product changeovers, boosting efficiency in pharmaceutical and specialty chemical production lines.
- Industrial Cluster Demand:Concentrated demand within Germany's chemical sector fosters specialized innovation and creates a critical mass for dedicated service infrastructure.
Market Restraints
- High Capital Outlay:The significant upfront investment for high-speed dryers, especially those made from corrosion-resistant alloys, limits adoption by smaller enterprises without substantial capital budgets.
- Energy Consumption:High power requirements to achieve rotational speeds for sub-1% moisture content create large operational costs, conflicting with corporate energy reduction goals.
- Material Handling Limits:Standard designs struggle with friable or sticky solids, which can degrade product or damage equipment, necessitating expensive customization.
Strategic Opportunities
- Battery Materials Processing:A key opportunity exists in drying battery precursors like lithium carbonate and graphite, which demand precise moisture control and high purity levels.
- Service-Based Revenue Models:Manufacturers can offer remote monitoring and predictive maintenance subscriptions, creating recurring revenue from data generated by installed equipment.
- Polymer and Bioplastic Recycling:The circular economy push creates demand for efficient dewatering of washed post-consumer plastics, preparing them for reuse in extrusion.
Industry Challenges
- Skilled Workforce Scarcity:A shortage of technicians with dual expertise in mechanical systems and data analytics is a bottleneck for deploying and maintaining smart, IoT-enabled dryers.
- Legacy System Integration:Connecting modern, networked dryers to older plant-wide control systems often faces challenges with proprietary protocols and data incompatibility issues.
- Divergent Regional Standards:Engineering a single product to comply with the EU's CE marking, US OSHA rules, and China's GB standards is a major compliance burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centrifugal Industrial Dryer Market |
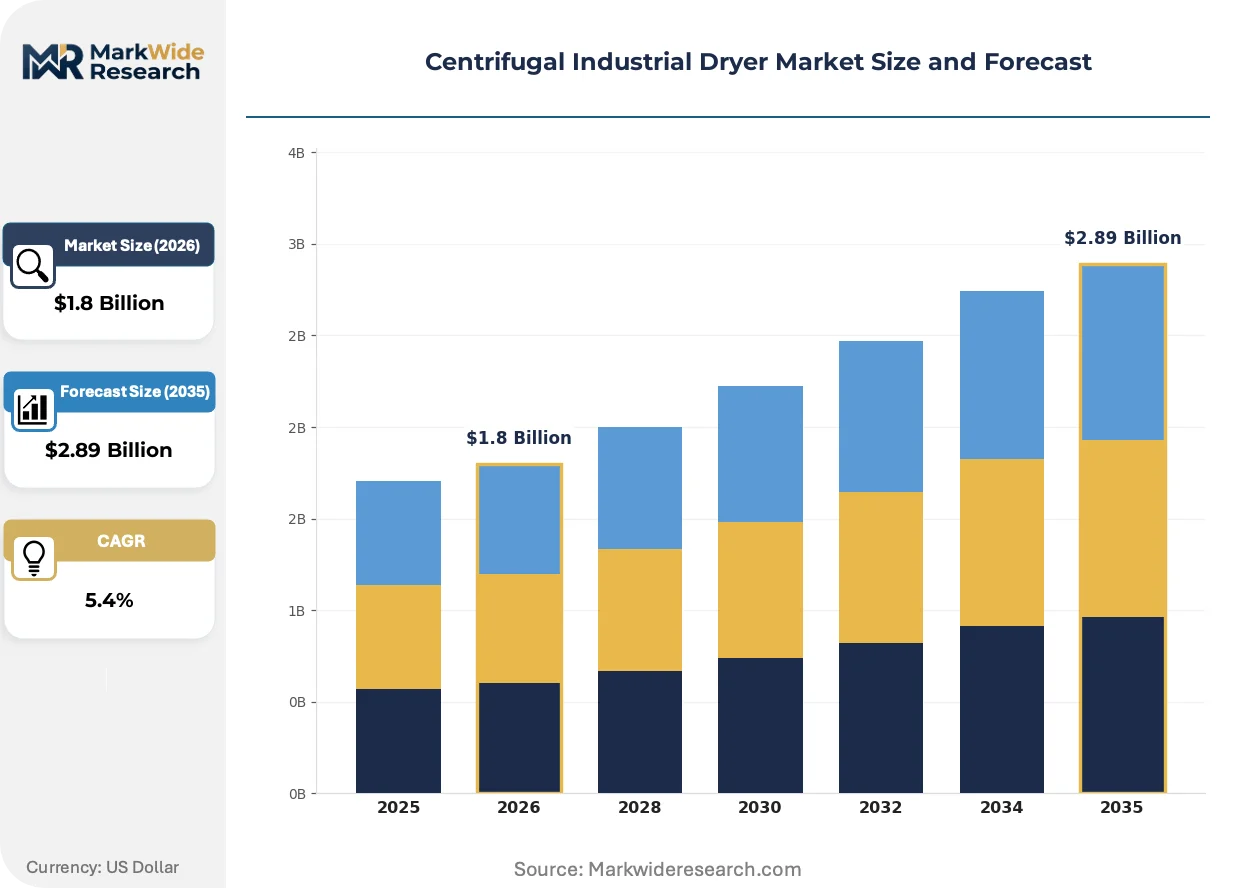
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-stage, Multi-stage, Vacuum, High-speed, Radial-flow Technology: Rotary, Screw, Fluidized Bed, Spray, Drum Application: Chemical Processing, Food Processing, Textile Manufacturing, Pulp & Paper Production, Metal Finishing End User Industry: Chemicals, Food & Beverage, Textiles, Pulp & Paper, Metalworking |
| Companies Covered | Wave Power Equipment, Zhejiang Humo Polishing Grinder Manufacture, Gala Industries, Gostol TST, Sino-alloy Machinery, ZIRBUS technology, Sukup Manufacturing, Genox Recycling Tech, Rosler Oberflachentechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centrifugal Industrial Dryer Market Strategic Shifts & Innovations
The market's evolution is defined by the transformation of centrifugal dryers from isolated mechanical units into intelligent nodes within a production ecosystem. This integration is driven by demands for greater process transparency and operational uptime.
IoT-enabled sensors on bearings and motors continuously monitor vibration and temperature for health diagnostics. Pharmaceutical and specialty chemical sectors are adopting this technology to maximize equipment uptime and validate processes. This data-driven strategy is rendering obsolete traditional, schedule-based maintenance that causes unnecessary downtime or premature component failure.
EU Machinery Directive mandates, enforced via CE marking, dictate stringent machine safety requirements like integrated guards and emergency stops. This regulation compels designers to embed safety into the core architecture, not as an add-on. Consequently, European chemical processors prioritize suppliers with pre-certified equipment to accelerate plant commissioning and safety audits.
A notable shift in purchasing involves buyers specifying and paying for guaranteed process outcomes, such as final moisture percentage and throughput rates. This performance-based model disrupts the conventional, transactional sale of a standalone dryer. The practice is most visible in high-value polymer industries where process consistency directly impacts product value.
Centrifugal Industrial Dryer Market Segmentation
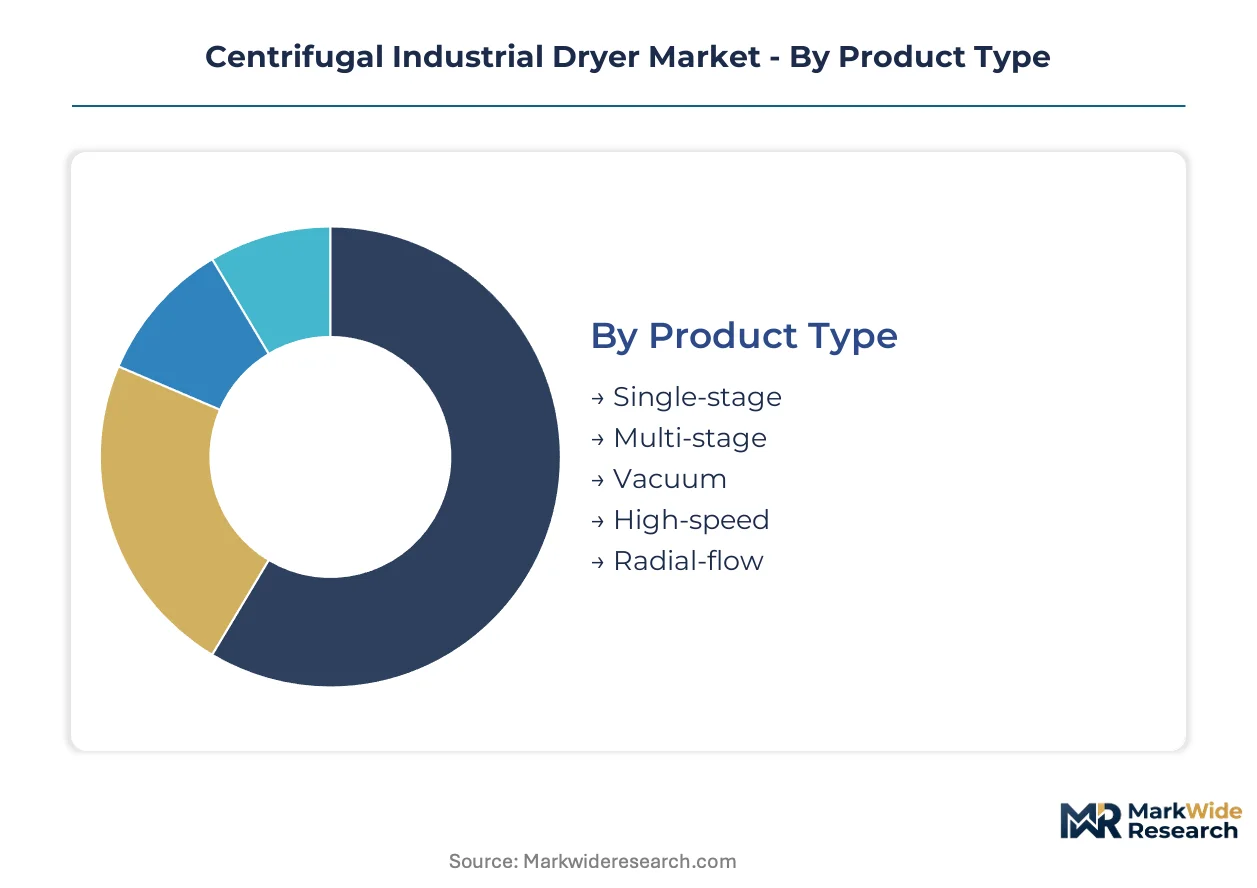
The centrifugal industrial dryer market's segmentation provides a granular view of specific product capabilities and their alignment with diverse industrial demands. Understanding these distinct segments allows manufacturers to tailor engineering solutions and market access strategies. Each category reflects unique operational requirements and purity standards across various processing environments.
Product Type:
The product type segmentation highlights the varying speeds at which materials can be processed, reflecting the cycle-time requirements of different industries. Some configurations prioritize rapid dewatering, while others focus on achieving ultra-low moisture content over longer periods.
- High-speed:These systems achieve rapid dewatering through extremely high rotational speeds, often exceeding 3,000 RPM, generating significant g-forces. Demand accelerates in food processing and metal finishing industries due to their need for increased throughput and efficient liquid-solid separation.
- Vacuum:Vacuum dryers operate under reduced atmospheric pressure, lowering the boiling point of liquids and enabling gentle drying of heat-sensitive materials. Pharmaceutical and specialty chemical sectors drive demand for these systems to prevent product degradation and maintain purity.
- Single-stage:These dryers perform a single dewatering operation, suitable for materials requiring moderate moisture reduction in a continuous flow.
- Multi-stage:Multi-stage systems integrate several dewatering steps, allowing for more precise control over the final moisture content and improved efficiency for complex materials.
- Radial-flow:Radial-flow dryers direct material outward from the center, optimizing liquid extraction for specific material consistencies and processing volumes.
Single-stage systems anchor the volume base while high-speed product types gain share at the steepest rate.
Technology:
The technological differentiation within centrifugal dryers reflects the diverse material properties and processing objectives across industries. Each technology offers distinct advantages in handling specific types of slurries or solids, from fine powders to granular materials.
- Rotary:Rotary dryers feature a rotating cylindrical shell that tumbles materials, ensuring uniform drying and efficient heat transfer for granular and coarse solids. These systems are foundational in mining and aggregate processing due to their robustness.
- Fluidized Bed:Fluidized bed dryers suspend solid particles in an upward-flowing stream of gas, providing excellent heat and mass transfer for fine powders and heat-sensitive products. The pharmaceutical industry leverages this technology for precise moisture control and gentle handling.
- Screw:Screw dryers use an internal screw mechanism to convey and dewater materials, particularly effective for viscous or sticky substances.
- Spray:Spray dryers atomize liquid feeds into fine droplets within a hot drying chamber, primarily used for producing dry powders from liquid solutions in food and chemical sectors.
- Drum:Drum dryers apply material onto heated rotating drums, suitable for drying slurries and pastes into flakes or films.
The adoption of rotary technology remains foundational, yet fluidized bed systems offer enhanced versatility for specialized processes.
Application:
Segmentation by application highlights where centrifugal dryers are deployed, illustrating the specific challenges and regulatory requirements of each end-use sector. Each application demands tailored drying solutions to meet product quality, safety, and operational efficiency standards.
- Chemical Processing:This segment involves drying various chemical compounds, polymers, and intermediates, often requiring corrosion-resistant alloys and precise temperature control. Stringent purity requirements in Germany's chemical sector drive demand for advanced dewatering systems.
- Food Processing:Centrifugal dryers in food processing remove moisture from ingredients like starches, proteins, and spices, necessitating sanitary designs and compliance with FDA and FSSAI regulations. The integration of Clean-in-Place (CIP) systems is critical for preventing contamination.
- Textile Manufacturing:Textile applications include dewatering fibers and fabrics post-washing or dyeing, focusing on efficiency and preserving material integrity.
- Pulp & Paper Production:Dryers in this sector remove water from pulp or paper stock, crucial for reducing energy consumption in subsequent drying stages.
- Metal Finishing:Metal finishing operations utilize centrifugal dryers to remove excess liquids from plated or treated parts, preventing spotting and corrosion.
Textile manufacturing represents a mature segment, while food processing is experiencing significant expansion due to evolving consumer demands.
End User Industry:
The end-user industry classification underscores the market's reliance on specific industrial sectors, each with unique material characteristics and operational priorities. This segmentation reveals how different industries prioritize factors like purity, throughput, and energy efficiency in their drying equipment procurement.
- Chemicals:The chemicals industry requires robust centrifugal dryers capable of handling corrosive substances and achieving high purity levels for end products. This sector often demands specialized materials of construction and precise control systems.
- Food & Beverage:This industry prioritizes hygienic design, ease of cleaning, and compliance with food safety regulations for drying ingredients and finished products. The demand for closed-loop systems is particularly strong here.
- Textiles:Textile manufacturers use these dryers for efficient dewatering of fabrics and yarns, focusing on throughput and minimizing damage to delicate fibers.
- Pulp & Paper:The pulp and paper industry employs large-scale centrifugal dryers to reduce moisture content in pulp, aiming for energy efficiency and high volume processing.
- Metalworking:Metalworking facilities use dryers to remove coolants and cleaning solutions from machined parts, preventing corrosion and preparing components for subsequent processes.
While textiles maintain a steady demand, industries like food & beverage are driving innovation through stringent process requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration significantly influences the regional demand for centrifugal industrial dryers. Specialized industrial clusters, particularly in chemical processing and food manufacturing, drive tailored innovation and infrastructure development. This geographic focus creates distinct market dynamics across key global economies.
Germany
Germany's robust chemical processing sector fuels demand for advanced centrifugal dryers, requiring corrosion-resistant materials and precise moisture control. The EU's CE marking mandates stringent safety and performance standards for all machinery sold within the bloc. Chemical parks like Ludwigshafen and Leverkusen demonstrate concentrated demand for specialized dewatering solutions.
India
India's expanding textile manufacturing hubs and food processing industry are accelerating the adoption of high-speed centrifugal dryers. The FSSAI mandates sanitary designs and closed-loop systems in food applications to prevent contamination. Industrial clusters in Gujarat and Maharashtra are seeing increased investment in modern drying technologies.
United States
The United States food processing sector drives significant demand for hygienic centrifugal dryers, especially for sensitive ingredients. OSHA regulations enforce strict safety protocols for industrial machinery, impacting design and operational standards. Major food manufacturing zones in the Midwest and California are adopting integrated dewatering systems.
China
China's rapid industrialization and diverse manufacturing base create substantial demand for centrifugal industrial dryers across multiple sectors. Compliance with GB standards for industrial machinery is mandatory for all manufacturers operating within the country. Industrial zones in the Yangtze River Delta and Pearl River Delta are key areas for dryer deployment.
France
French pharmaceutical and specialty chemical industries require high-purity drying solutions, often driving demand for vacuum and multi-stage centrifugal systems. European environmental regulations, including those related to energy efficiency, influence equipment design and operational choices. Chemical and pharmaceutical clusters in Lyon and Paris are key procurement centers.
Centrifugal Industrial Dryer Market Key Industry Players
Channel-controlling players compete with product-specialist players within the centrifugal industrial dryer market, leading to a tiered competitive structure. The market exhibits fragmentation among niche providers and consolidation among larger industrial equipment manufacturers. Strategic partnerships and technology licensing are dominant competitive moves, alongside continuous portfolio diversification.
Specialists in polymer drying, such as Gala Industries, exemplify focused expertise within specific material processing segments. Rosler Oberflachentechnik represents a segment focused on integrated surface finishing solutions, combining drying with other treatment stages. Sukup Manufacturing anchors the agricultural sector, providing robust, large-scale drying systems tailored for grain and feed processing.
| Leading Market Players |
|---|
| Wave Power Equipment |
| Zhejiang Humo Polishing Grinder Manufacture |
| Gala Industries |
| Gostol TST |
| Sino-alloy Machinery |
| ZIRBUS technology |
| Sukup Manufacturing |
| Genox Recycling Tech |
| Rosler Oberflachentechnik |
| Others |
Cost & Logistics Intelligence
Commodity volatility in specialized alloys for corrosion resistance determines both pricing tier spreads and the overall supply chain shape for centrifugal industrial dryers. This dependency creates specific cost pressures across different product categories.
Pricing Analysis
Cost-plus contracts, often indexed to stainless steel and specialized alloy prices, define the predominant pricing model in this market. Price differentiation stems from the level of customization required and the specific regulatory certifications, such as CE marking, embedded in the equipment. Pricing softness emerges in the high-volume single-stage segment due to increased competition from regional manufacturers. Smaller enterprises exhibit the highest price sensitivity, while large pharmaceutical and chemical processors prioritize performance and compliance over upfront cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common practices for managing working capital among manufacturers and their component suppliers. Geographic supply concentration for high-speed dryer components exists in Germany and China, while specialized alloys often originate from global mining hubs. Key raw material dependencies include corrosion-resistant steel, high-speed motors, and advanced IoT sensors. Single-source vulnerability for proprietary control systems represents a significant structural risk. Distribution runs through a mix of direct sales channels to large industrial clients and specialized equipment distributors serving smaller end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The centrifugal industrial dryer market faces a capability scarcity, particularly in integrating advanced data analytics with traditional mechanical engineering. This gap creates significant opportunities for specialized players.
For Market Incumbents:
Harden core intellectual property around advanced material handling and precise moisture control systems. Invest in R&D for next-generation predictive maintenance algorithms to counter the threat of operational downtime. Pursue strategic partnerships with IoT platform providers to offer integrated, data-rich solutions. Consolidate market share in established segments by leveraging existing channel control and brand recognition.
For New Entrants and Emerging Players:
Establish a beachhead in the rapidly expanding battery materials processing segment by offering specialized drying solutions for lithium carbonate and graphite. Target the unmet demand for efficient dewatering systems in polymer and bioplastic recycling applications. Focus on developing integrated clean-in-place (CIP) functionality to appeal to high-purity sectors like pharmaceuticals. A performance-based sales model, guaranteeing specific process outcomes, serves as a compelling go-to-market angle.
For Investors and Strategic Acquirers:
The market sits at a growth phase that favors technology-forward specialists with strong intellectual property in data integration and material science. Long-term viability over a 5-10 year window hinges on the ability to deliver systems that meet evolving energy efficiency and purity mandates. Acquisition targets should include niche providers of IoT-enabled sensors or firms specializing in advanced process controls. The increasing adoption rate of service-based revenue models is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate IoT-enabled Predictive Maintenance | Maximizes equipment uptime and reduces operational costs for end-users in high-purity sectors. |
| Develop Systems for Battery Materials | Captures share in a high-growth segment with stringent purity and moisture control requirements. |
| Invest in Advanced CIP Technologies | Addresses food safety and pharmaceutical purity mandates, enabling faster product changeovers. |
| Expand Service-Based Revenue Models | Generates recurring income streams and strengthens customer relationships through data analytics. |
| Obtain Diverse Regional Certifications | Ensures market access and compliance across major industrial economies like the EU, US, and China. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews, which were then validated against extensive secondary research. Stakeholders included plant managers, procurement leads, R&D directors, and maintenance directors across various industries. Secondary sources comprised industry association reports, trade publications, and regulatory body guidelines. This approach ensured a robust bottom-up and top-down triangulation of market data.
The calibration approach involved developing an analytical framework that modeled market dynamics across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional regulatory clusters. Compound annual growth rates were derived by analyzing historical trends and projecting future demand based on industrial output indices and food safety regulation updates.
Sensitivities concentrate around the pace of technological adoption and the stringency of new environmental regulations. Forecasts reflect assumptions regarding sustained industrial growth and continued investment in process optimization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Vertical Baling Press Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market
Material Handling Equipment
Circular Stacker and Reclaimer Market
Material Handling Equipment
Port Material Handling Equipment Vehicle Market
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Hydraulics Components Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
High Pressure Grease Hose Market
Material Handling Equipment
Flux Spraying Machine Market
Material Handling Equipment
Global Automatic Palletizer and Depalletizer Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Material Handling Equipment Tires Market
Material Handling Equipment
Compactor Market