
 Compactor Market | 2026-2036
Compactor Market Size, Share, and Industry Trends Forecast 2026-2036
Compactor Market Analysis
EPA Tier 4 Final standards is realigning the cost-of-entry calculus for compactor manufacturers serving North American construction and waste sectors. Caterpillar Inc. leverages its integrated engine manufacturing to absorb compliance costs internally. BOMAG GmbH differentiates through specialized asphalt compaction technologies that navigate stringent vibration and noise ordinances. Komatsu Ltd. anchors its position with telematics-enabled fleet management systems that extend equipment utilization rates for contractor end users.
A compactor is a heavy mechanical device that applies static or dynamic force to reduce material volume through compression, typically achieving densities of 1,000–2,500 kg/m³ depending on drum configuration and vibration frequency. The equipment serves primary industrial purposes in soil stabilization, asphalt laying, landfill operations, and recyclable material densification. Single drum variants dominate earthworks applications due to their maneuverability on uneven terrain, while double drum configurations command premium positioning in highway paving where surface finish tolerances are tightest. Trash compactors represent the fastest-growing product category as municipalities replace open-top collection with enclosed mechanized systems.
FERC guidelines on infrastructure project financing, EPA emissions mandates, and OSHA workplace noise exposure limits collectively shape equipment specification sheets and procurement criteria across North American end users. The EU Green Deal and F-Gas Regulation impose parallel constraints on European equipment imports, compressing the addressable market for non-compliant manufacturers. Stakeholders must monitor the pace of electric drivetrain maturation against the residual cost advantage of hydraulic systems in high-torque compaction cycles.
Market Dynamics
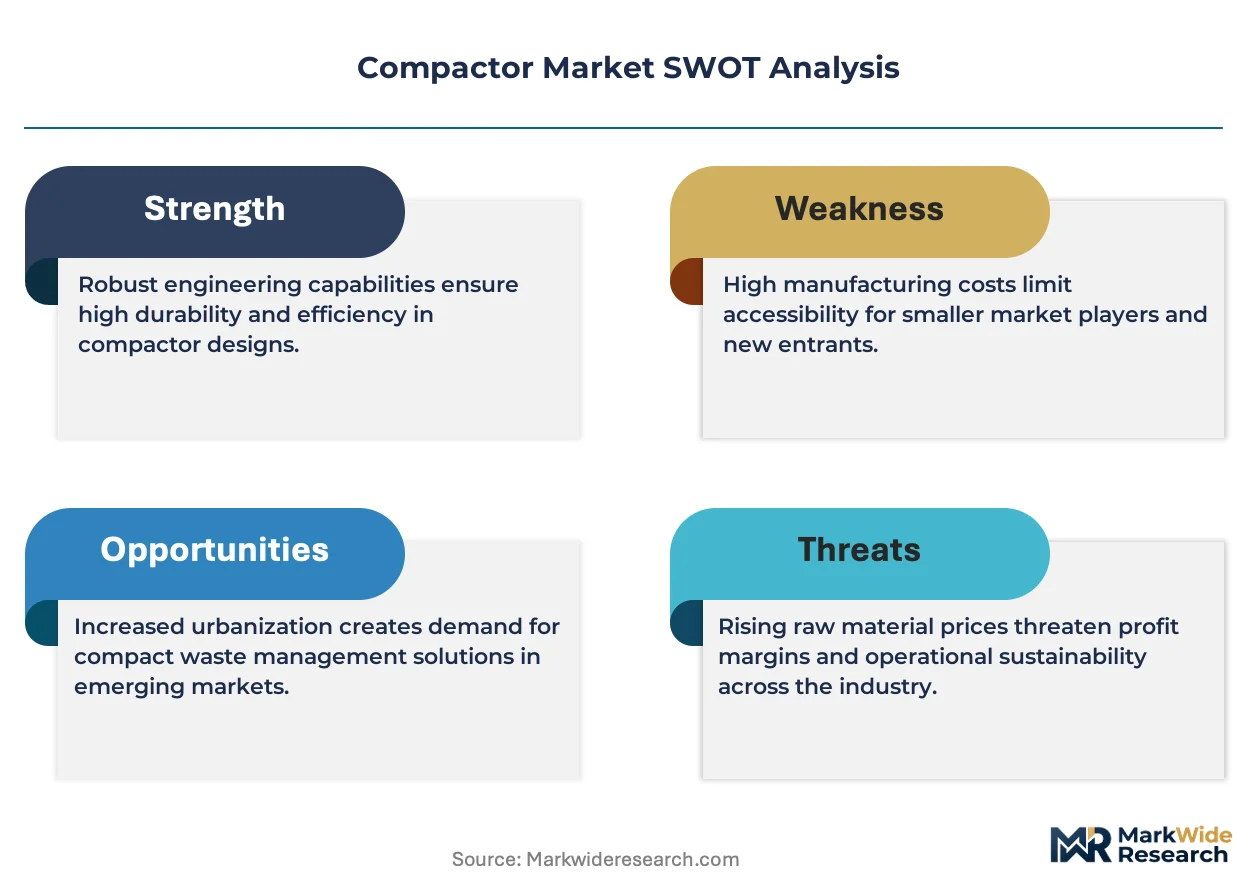
EPA Tier 4 Final emissions standards are compressing the competitive set for diesel-powered compaction equipment, forcing manufacturers to internalize engine development costs or exit North American construction and waste sectors entirely.
Growth Catalysts
- Municipal mechanization mandates:Indian urban infrastructure corridors facing landfill capacity constraints are accelerating procurement of enclosed trash compaction systems to replace open-top collection fleets.
- Telematics integration:Fleet management systems enabling real-time equipment utilization tracking are extending contractor asset turnover rates and reducing idle-time penalties.
- EU Green Deal alignment:European equipment importers must satisfy F-Gas Regulation and CE marking requirements, creating compliance-driven replacement cycles for aging hydraulic fleets.
Market Restraints
- High-torque hydraulic cost advantage:Electric drivetrain maturation remains incomplete for heavy compaction cycles, preserving incumbent technology lock-in despite operating cost premiums.
- Engine supply concentration:Integrated engine manufacturing capabilities concentrate among vertically integrated heavy equipment producers, raising barriers for component-assembly competitors.
- OSHA noise exposure limits:Workplace safety regulations constrain vibration frequency specifications for asphalt compaction equipment, limiting performance optimization headroom.
Strategic Opportunities
- India's urban corridors:Landfill capacity saturation in metropolitan waste management systems creates sustained demand for high-density compaction equipment procurement.
- Electric-hydraulic convergence:Battery-electric powertrains paired with regenerative braking systems are opening equipment categories previously reserved for diesel torque profiles.
- Rental channel expansion:Contractor preference for operational flexibility over capital ownership is shifting volume toward equipment-as-a-service distribution models.
Industry Challenges
- EPA certification timelines:Tier 4 Final compliance testing and documentation requirements extend product launch cycles, compressing revenue recognition windows.
- Legacy fleet integration:Telematics-enabled management systems face interoperability friction with unconnected equipment already deployed in contractor yards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compactor Market |
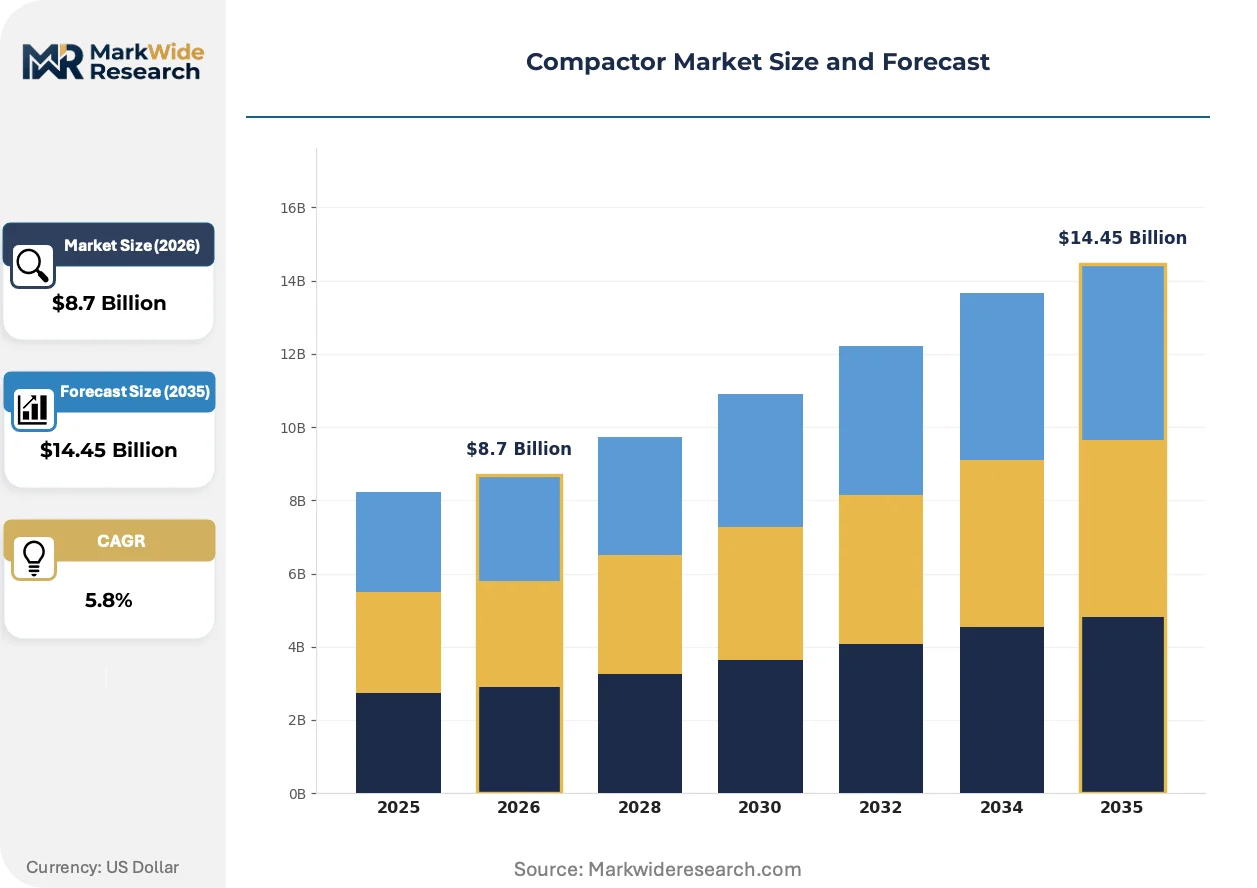
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Drum, Double Drum, Plate, Trash Compactors Application: Construction, Waste Management, Recycling, Mining End User: Contractors, Municipalities, Waste Management Firms, Manufacturing Technology: Hydraulic, Pneumatic, Electric, Manual |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, Hitachi Construction Machinery Co. Ltd., BOMAG GmbH, JCB, Terex Corporation, CASE Construction Equipment, Atlas Copco AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compactor Market Emerging Trajectories
Compaction equipment is undergoing a fundamental architecture shift as emissions compliance, connectivity layers, and powertrain electrification converge to redefine manufacturer value propositions and buyer procurement criteria.
Intelligent compaction systems integrating accelerometer-based density measurement with GPS mapping are consolidating quality control processes in highway paving operations. State transportation departments in the United States are embedding these technologies into specification sheets for federally funded infrastructure projects. Real-time drum vibration monitoring is consolidating the role of traditional manual core sampling, compressing inspection timelines and reducing material waste penalties.
REACH chemical restrictions and EU F-Gas Regulation are forcing refrigerant and hydraulic fluid reformulation across European equipment imports. Manufacturers serving EU member states must recertify component supply chains to maintain CE marking eligibility. Asphalt paver and soil compactor segments face the steepest compliance burden, with non-compliant producers losing tender access to German and French municipal procurement frameworks.
Contractor buying committees are unbundling after-sales service contracts from equipment purchase agreements, compressing manufacturer recurring revenue streams. Independent service providers equipped with diagnostic telematics access are capturing maintenance spend previously captive to OEM networks. This disintermediation is most pronounced in North American construction rental fleets, where third-party uptime guarantees are displacing factory service commitments in procurement evaluations.
Compactor Market Segmentation
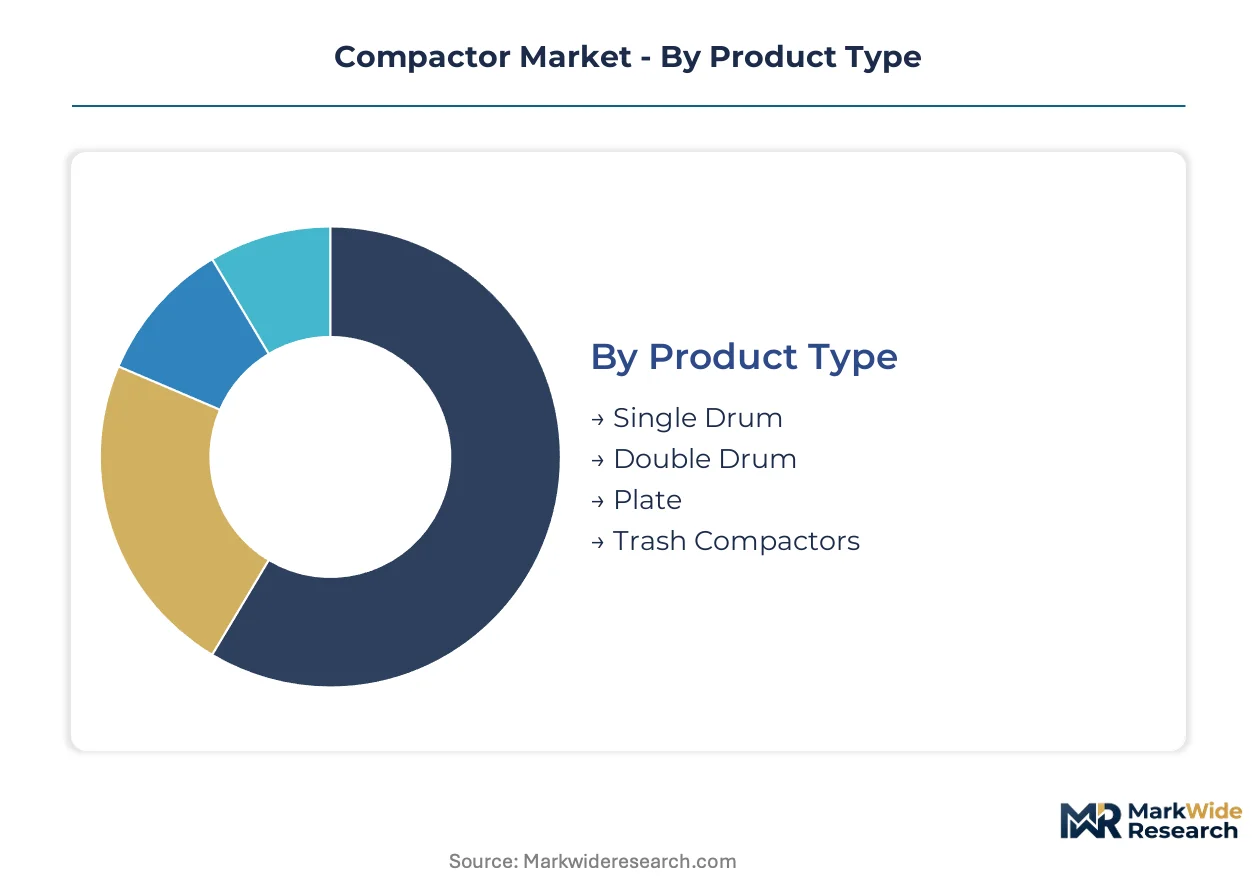
Compaction equipment purchasing hinges on matching drum configuration and powertrain technology to material density targets and site access constraints. Specification sheets diverge sharply across earthworks, asphalt paving, and enclosed waste collection applications.
Product Type:
Buyers prioritize maneuverability against surface finish requirements when selecting drum architecture.
- Single Drum:One vibrating steel drum paired with pneumatic rear tires generates traction on uneven terrain. Earthworks contractors in India's urban infrastructure corridors specify these units for soil stabilization where grade variability exceeds 15 percent.
- Double Drum:Dual steel drums with independent vibration control deliver uniform density for highway surface courses. State transportation departments in the United States embed intelligent compaction specifications into federally funded asphalt paving contracts.
- Plate:Small-format reciprocating plates achieve shallow lift compaction in trench backfill and landscaping applications.
- Trash Compactors:Enclosed hopper systems with hydraulically actuated plungers reduce municipal waste volume by 75 percent prior to landfill transport.
Volume sits with single drum configurations; growth tilts toward trash compactors.
Application:
Project scale and material specification determine equipment procurement channels.
- Construction:Highway paving and earthworks projects require density verification protocols that intelligent compaction systems automate through accelerometer-GPS integration.
- Waste Management:Landfill cell development and daily cover operations specify high-amplitude single drum units to achieve 1,200 kg/m³ refuse density. Indian metropolitan systems facing capacity constraints are accelerating enclosed collection fleet procurement.
- Recycling:Material recovery facilities deploy stationary and mobile compactors to densify cardboard, plastics, and metals for transport efficiency.
- Mining:Haul road maintenance and tailings compaction specify heavy-duty single drum variants with reinforced frames.
Construction commands installed base; waste management is climbing the fastest.
End User:
Capital deployment models separate fleet ownership strategies across customer categories.
- Contractors:Equipment utilization rates drive procurement decisions, with telematics-enabled fleet management systems extending asset turnover through idle-time reduction.
- Municipalities:Mechanized waste collection mandates in Indian urban corridors are displacing open-top truck fleets with enclosed compaction systems.
- Waste Management Firms:Landfill operators specify high-density compaction equipment to maximize airspace revenue per cell.
- Manufacturing:In-plant balers and compactors reduce outbound shipping costs for production scrap and packaging waste.
Contractors hold the largest fleet footprint; municipalities are gaining share fastest.
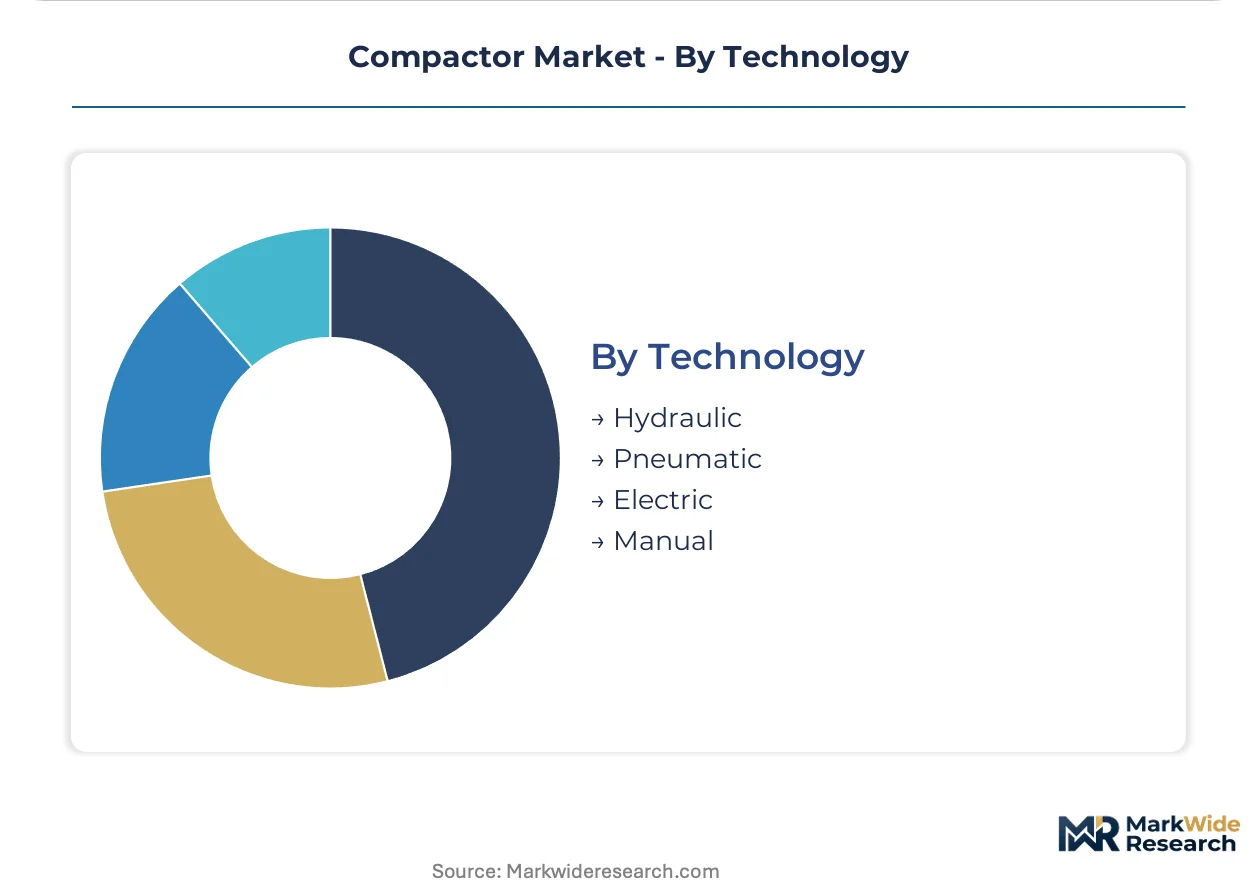
Technology:
Torque density requirements and emissions compliance timelines shape powertrain selection.
- Hydraulic:Closed-loop hydrostatic drives deliver sustained high torque for heavy compaction cycles, preserving incumbent positioning despite Tier 4 Final compliance costs.
- Electric:Battery-electric powertrains with regenerative braking are penetrating light compaction categories where duty cycles permit recharge intervals.
- Pneumatic:Compressed air systems serve explosive atmosphere applications in mining and chemical processing facilities.
- Manual:Walk-behind plate compactors address small-scale landscaping and utility trench restoration.
Hydraulic systems dominate heavy-cycle revenue; electric configurations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for compaction equipment concentrates in markets where landfill capacity constraints intersect with infrastructure investment cycles. The United States, Germany, India, China, and Brazil represent the primary procurement territories, each shaped by distinct regulatory and industrial drivers.
United States
Federal highway spending and municipal waste fleet modernization drive equipment procurement. EPA Tier 4 Final standards compress the competitive set for diesel-powered units. Texas and California anchor demand, with state transportation departments embedding intelligent compaction specifications into federally funded paving contracts.
Germany
EU Green Deal alignment and F-Gas Regulation impose refrigerant and hydraulic fluid reformulation requirements. CE marking recertification compresses tender access for non-compliant producers. The Baden-Württemberg and Bavaria industrial corridors concentrate asphalt compaction equipment manufacturing and testing facilities.
India
Urban infrastructure corridors in Maharashtra and Karnataka face acute landfill capacity saturation. Municipal mechanization mandates accelerate enclosed trash compaction fleet procurement. The Smart Cities Mission directs central funding toward mechanized waste collection systems in metropolitan regions.
China
Dual carbon goals and MEE emissions standards reshape equipment specification sheets for domestic and export markets. Yangtze River Delta infrastructure clusters specify high-density compaction for landfill cell development. GB standards compliance requirements concentrate procurement among domestic manufacturers with integrated engine capabilities.
Brazil
Mining haul road maintenance and agricultural soil stabilization sustain demand for single drum configurations. ANVISA workplace safety regulations constrain vibration exposure limits for operator cabins. São Paulo and Minas Gerais states anchor equipment distribution networks serving the southeastern industrial corridor.
Compactor Market Vendor Landscape
German producers anchor one tier of precision-engineered compaction equipment; Japanese and American manufacturers hold positions in scale-driven fleet supply and integrated powertrain development. The vendor base concentrates among vertically integrated heavy equipment conglomerates and specialized compaction technology firms. Three archetypes dominate: engine-integrated full-line producers, vibration-specialist equipment houses, and telematics-enabled fleet solution providers. Competitive moves center on emissions compliance cost absorption and aftermarket service contract retention.
Within the engine-integrated tier, Caterpillar Inc. and Komatsu Ltd. occupy positions defined by captive manufacturing capabilities and fleet management system deployment. BOMAG GmbH exemplifies the specialist archetype, with German engineering heritage concentrated in asphalt compaction technologies. These three anchors represent distinct strategic postures: cost internalization through backward integration, telematics-enabled utilization optimization, and regulatory navigation through precision vibration control.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Volvo Construction Equipment |
| Hitachi Construction Machinery Co. Ltd. |
| BOMAG GmbH |
| JCB |
| Terex Corporation |
| CASE Construction Equipment |
| Atlas Copco AB |
| Others |
Supply Flow & Price Mechanics
Precision welding and hydraulics engineering talent clusters in Baden-Württemberg and Bavaria create labor-cost differentials that separate premium German-engineered compaction equipment from mid-tier Asian manufacturing. Tier 4 Final engine certification costs and telematics development expenses widen spreads between premium positioning and economy alternatives.
Pricing Analysis
Volume concentrates in standard-tier hydraulic compactors while margins accrue to premium intelligent compaction systems with GPS-integrated density verification. Price differentiation hinges on EPA Tier 4 Final certification status and telematics bundling depth. Cost compression in the economy tier intensifies as Indian and Chinese manufacturers absorb engine compliance expenses through state subsidy programs. Municipal procurement committees exhibit highest price sensitivity; landfill operators prioritizing airspace density show lowest.
Supply Chain Analysis
Reverse-logistics networks for remanufactured drums and refurbished hydraulic components extend equipment lifecycle value across North American contractor fleets. Manufacturing concentrates in Germany, Japan, and the United States for precision-engineered vibration systems; China and India anchor high-volume hydraulic component production. Steel plate, high-grade bearings, and electronic control modules constitute critical input dependencies. Single-source vulnerability concentrates in specialized accelerometer suppliers for intelligent compaction systems. Distribution runs through OEM-owned dealer networks and independent rental channels serving contractor flexibility demands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated engine manufacturing capacity constitutes the binding constraint propping pricing power for Tier 4 Final-compliant equipment. Manufacturers without captive powertrain development face compressed margins or market exit.
For Market Incumbents: Acquire telematics platform capabilities to defend service contract retention against independent diagnostic providers. Expand remanufacturing footprint in Texas and California to capture aftermarket parts demand from aging fleet bases. Battery-electric powertrain development represents the critical R&D lever against emerging Chinese entrants with state-backed cell supply.
For New Entrants and Emerging Players: Begin with enclosed trash compactor segments in Indian metropolitan corridors where landfill capacity saturation outpaces domestic manufacturing capacity. Target municipal procurement frameworks in Maharashtra and Karnataka with equipment-as-a-service financing models that bypass capital budget constraints. Partner with regional engine remanufacturers to navigate Tier 4 Final certification timelines without vertical integration.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized vibration-technology firms given EU F-Gas Regulation and REACH compliance burdens that favor precision-engineered European producers. Long-term viability across the analysis window favors manufacturers with backward integration into engine development and telematics software stacks. Monitor electric-hydraulic powertrain cost convergence as the inflection signal for technology transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Intelligent Compaction System Deployment | Accelerometer-GPS integration satisfies state DOT specification requirements for federal highway funding eligibility. |
| Electric Powertrain Development | Battery-electric configurations with regenerative braking penetrate light compaction categories previously reserved for diesel torque. |
| Aftermarket Service Network Expansion | Independent uptime guarantees displace factory service commitments in North American rental fleet procurement evaluations. |
| Regional Manufacturing Localization | Domestic assembly in India and Brazil circumvents import duty exposure and accelerates municipal tender response timelines. |
| Remanufacturing and Refurbishment Programs | Extended lifecycle offerings capture maintenance spend from contractor fleets facing capital deployment constraints. |
Methodological Framework
Trade publications, equipment registration databases, and customs import records formed the secondary backbone for volume and trade flow estimation. Primary interviews with fleet maintenance directors, municipal procurement officers, landfill operations managers, and aftermarket service heads validated specification trends and replacement cycle assumptions. Bottom-up unit shipment tallies triangulated against top-down infrastructure spending allocations across the analysis window.
Historical trendline analysis established baseline growth patterns across single drum, double drum, and trash compactor categories. Segmentation modeling incorporated drum configuration, powertrain technology, application vertical, and end-user ownership model dimensions. CAGRs derived from fitted trend projections adjusted for regulatory compliance timelines and electrification penetration curves. Forecast inputs included EPA certification schedule delays, EU F-Gas Regulation phase-in dates, and Indian Smart Cities Mission funding disbursement patterns.
Underlying measurement precision varies by segment; trash compactor procurement data carries tighter precision than mining application estimates due to fragmented fleet reporting. Forecasts reflect documented assumptions regarding emissions standard adherence and infrastructure appropriation levels. Practitioners should monitor electric powertrain cost curves and municipal bond issuance rates for early signals of technology transition acceleration or procurement cycle compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Global Industrial Weighing Equipment Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Pipe Jacking Machines Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Robotic Palletizers and De-Palletizers Market
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Warehouse Freight Elevators Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Belt Scales Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Ship Loader and Unloader Market