
 Port Material Handling Equipment Vehicle Market | 2026-2036
Port Material Handling Equipment Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Port Material Handling Equipment Vehicle Market Analytics
Dealer networks serving African and Southeast Asian port authorities is rewriting equipment procurement pathways for mid-tier terminals. Kalmar leverages its automation software stack to anchor long-term service contracts across Nordic harbors. Liebherr Group competes on crane-lifting capacity ratings that exceed competitor specifications for ultra-large container vessels. Sany Heavy Industry dominates domestic replacement cycles through manufacturing scale that compresses lead times for Chinese port operators.
Port material handling equipment vehicles encompass mobile machinery engineered for cargo transfer, stacking, and horizontal transport within maritime terminal boundaries, typically operating at load capacities from 10 to 100 tonnes with diesel, electric, or hybrid powertrains. These machines integrate spreader mechanisms, telescopic booms, or fifth-wheel couplings to interface with ISO containers, bulk commodities, and roll-on/roll-on cargo across quay and yard zones. Reach stackers and terminal tractors capture expanding margin pools as electrification raises upfront equipment costs while reducing lifetime fuel expenditure. Forklifts retain volume leadership in general cargo applications where versatility outweighs specialization, though automated guided variants erode labor-dependent models in greenfield terminals. Cranes sustain premium positioning through structural steel intensity and precision control systems that limit new entrant replication.
EPA marine engine emission tiers and EU F-Gas Regulation constrain diesel-powered equipment specifications while accelerating electric and hybrid technology validation. China's GB standards and NMPA-equivalent harbor safety protocols mandate operator-assist systems that elevate base equipment cost structures. ISO container corner casting dimensions and IEC electrical safety codes create interoperability requirements that shape supplier R&D allocation. Stakeholders must weigh captive electrification infrastructure investment against residual diesel fleet utilization as regulatory phase-in schedules diverge across operating geographies.
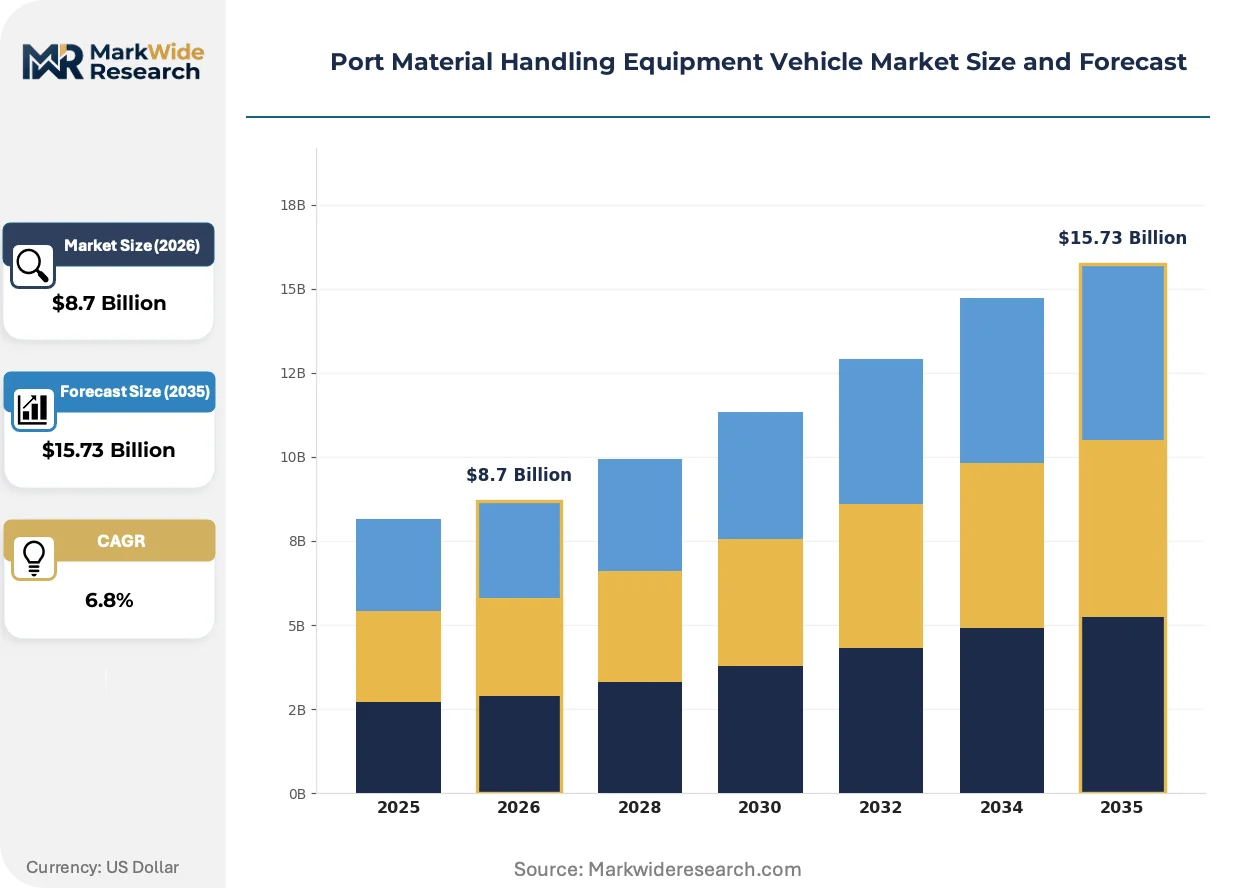
Market Dynamics
Electrification mandates from the EU Green Deal and China's dual carbon goals are forcing terminal operators to accelerate fleet replacement cycles while balancing residual diesel asset utilization against charging infrastructure capex requirements.
Growth Catalysts
- EPA Tier 4 Final marine engine standards:US harbor authorities face compliance deadlines that accelerate equipment turnover toward hybrid and electric terminal tractors.
- Automated terminal tractor fleets:Shanghai Yangshan and Rotterdam Maasvlakte terminals demonstrate throughput gains that justify automation capex for peer facilities.
- Battery energy density improvements:Lithium iron phosphate cell chemistry advances enable 8-hour continuous duty cycles for reach stackers without mid-shift charging.
Market Restraints
- Steel and copper price volatility:Structural steel intensity in crane manufacturing exposes producers to input cost swings that compress margin visibility on long-lead contracts.
- High-voltage charging infrastructure:Grid connection lead times and utility upgrade costs delay electric fleet deployment at secondary ports with constrained capital budgets.
- Skilled technician scarcity:Electrified equipment maintenance requires electrical systems expertise that existing diesel-mechanic workforces lack, inflating service labor rates.
Strategic Opportunities
- Southeast Asian greenfield terminals:Vietnam's Lach Huyen and Indonesia's Patimban developments specify automation-ready equipment from commissioning, bypassing legacy retrofit constraints.
- EU F-Gas Regulation phase-down:Refrigerant restrictions on diesel-powered auxiliary systems create openings for all-electric alternatives in EU-27 port tenders.
- Predictive maintenance software:Telematics integration with OEM service contracts generates recurring revenue streams that offset equipment sales cyclicality.
Industry Challenges
- IEC 61508 functional safety certification:Automated guided vehicle validation timelines extend 18-24 months, delaying revenue recognition for suppliers and deployment for operators.
- Interoperability between legacy and automated fleets:Mixed-traffic yard operations require safety system integration that complicates phased automation rollouts at brownfield terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Port Material Handling Equipment Vehicle Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forklifts, Cranes, Reach Stackers, Terminal Tractors End User: Shipping Lines, Port Operators, Freight Forwarders, Logistics Companies Technology: Electric, Diesel, Hybrid, Automated Application: Container Handling, Bulk Material Handling, General Cargo, RoRo Operations |
| Companies Covered | Kalmar, Konecranes, Liebherr Group, Sany Heavy Industry, Shanghai Zhenhua Heavy Industries, Terberg, Caterpillar, Toyota Industries, Hyster-Yale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Port Material Handling Equipment Vehicle Market Evolving Landscape
Port equipment design is pivoting from mechanical reliability toward software-defined functionality, with electrification and automation converging to redefine operator roles and asset utilization models.
High-voltage battery architectures are migrating from niche demonstration projects to mainstream specifications for reach stackers and terminal tractors. European terminal operators at Hamburg and Antwerp are specifying 350V platforms as baseline requirements in new tenders. This voltage standardization is compressing supplier R&D fragmentation and enabling cross-fleet charging infrastructure sharing.
The EU F-Gas Regulation's hydrofluorocarbon phase-down is eliminating refrigerant-dependent climate control systems from harbor equipment specifications. Manufacturers are substituting thermoelectric cooling and battery thermal management integration to maintain operator cab conditions. Diesel-powered auxiliary systems face accelerated obsolescence in EU-27 tenders as compliance deadlines approach.
Long-term service contracts are displacing transactional spare parts sales as the dominant aftermarket revenue model. Nordic port authorities now require 10-year availability guarantees bundled with original equipment purchases. This contractual shift concentrates aftermarket value with OEMs possessing embedded software stacks and remote diagnostic capabilities.
Port Material Handling Equipment Vehicle Market Segmentation
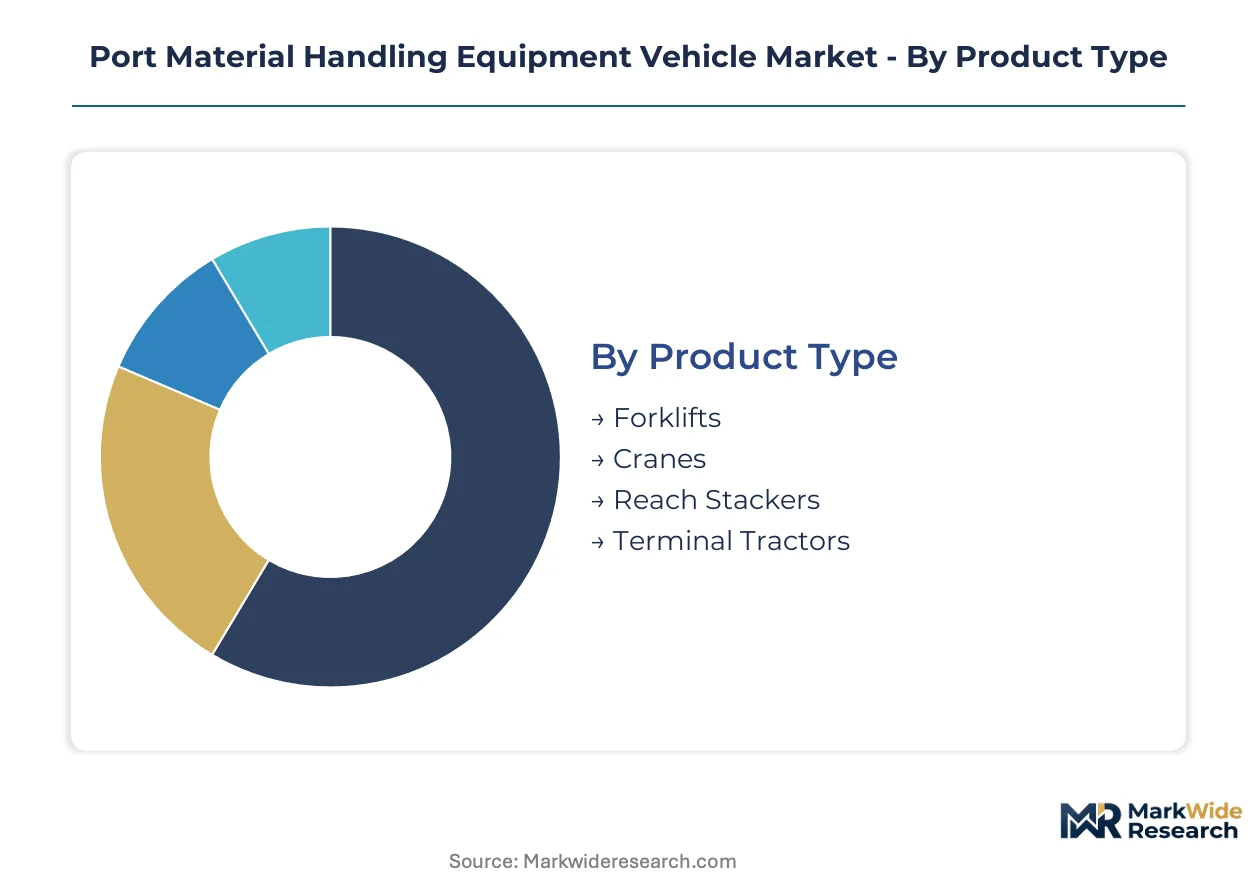
Segmentation in port material handling equipment reveals how terminal operators balance capital intensity against operational flexibility. Equipment specifications diver sharply between greenfield automation projects and legacy fleet replacement cycles.
Product Type:
Mature equipment categories dominate installed base volumes while emerging variants capture specification momentum in new tenders.
- Reach Stackers:Telescopic boom vehicles with spreader attachments handle container stacking at capacities from 10 to 45 tonnes. Rotterdam and Hamburg terminal operators specify electric reach stackers as baseline equipment under EU Green Deal procurement rules, though charging infrastructure gaps delay deployment at secondary ports.
- Terminal Tractors:Fifth-wheel coupling tractors perform horizontal container transport between quay and yard zones. Shanghai Yangshan and Rotterdam Maasvlakte automated terminals validate autonomous terminal tractor fleets, compressing labor costs and extending operational windows.
- Forklifts:Versatile counterbalance and reach trucks manage general cargo with load ratings from 2 to 25 tonnes.
- Cranes:Rubber-tired gantry and mobile harbor cranes deliver structural lifting capacity for ultra-large container vessels.
Reach stackers handle the majority of throughput; terminal tractors are expanding most quickly on specification share.
End User:
Customer concentration varies by contract scale, with volume buyers driving standardization while fragmented operators sustain aftermarket service demand.
- Port Operators:State-owned and private terminal authorities control fleet procurement for quay and yard operations. Chinese port groups under NMPA-equivalent safety mandates accelerate replacement cycles through centralized purchasing power, compressing supplier margins on volume contracts.
- Shipping Lines:Container carriers operating dedicated terminals specify equipment interoperability with vessel loading systems. Mediterranean Shipping Company and Maersk Line terminal subsidiaries demand ISO container corner casting compatibility across mixed-vendor fleets.
- Freight Forwarders:Third-party logistics providers lease equipment for short-term cargo surges.
- Logistics Companies:Integrated supply chain operators require equipment flexibility across multi-modal handoffs.
Port operators command the largest fleet volumes; shipping lines are climbing the fastest on automation specification intensity.
Technology:
Cost tier stratification separates premium electrified platforms from legacy diesel equipment, with hybrid architectures bridging transition timelines.
- Electric:Battery-powered systems with lithium iron phosphate cell chemistry enable 8-hour duty cycles. Hamburg and Antwerp terminals mandate 350V architectures as tender baselines, standardizing cross-fleet charging infrastructure.
- Hybrid:Diesel-electric powertrains retain operational flexibility while reducing fuel consumption. EPA Tier 4 Final compliance deadlines accelerate hybrid adoption at US harbor authorities facing emission enforcement.
- Diesel:Conventional internal combustion engines dominate residual fleet utilization.
- Automated:Sensor-guided vehicles with IEC 61508 functional safety certification enable unmanned yard operations.
Electric systems anchor new tender specifications; automated variants show the steepest expansion trajectory despite 18-24 month validation timelines.
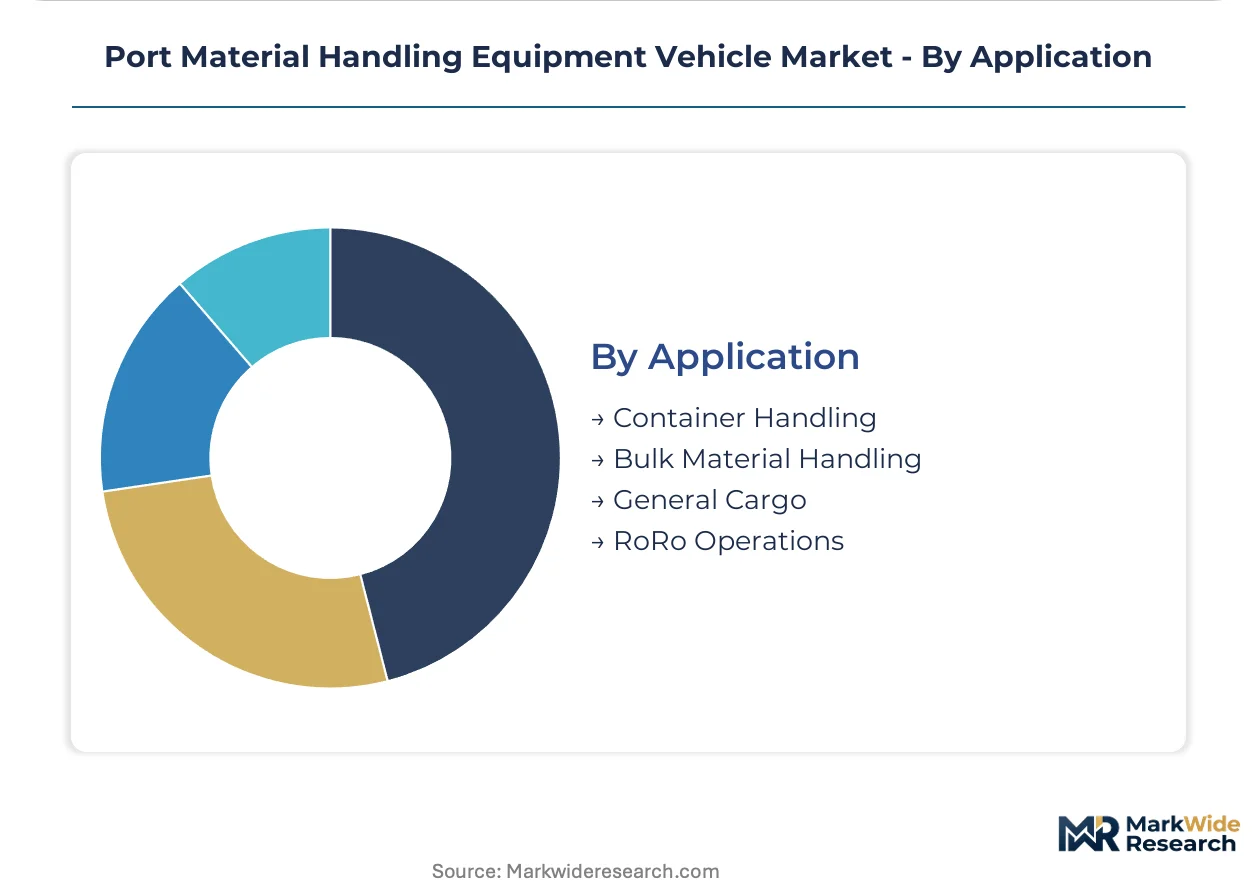
Application:
Geography shapes application demand, with container throughput concentration in East Asian and North European hubs driving equipment specialization.
- Container Handling:ISO container transfer, stacking, and vessel loading operations dominate capital allocation. China's GB standards and EU F-Gas Regulation constrain diesel auxiliary systems, redirecting procurement toward all-electric alternatives.
- Bulk Material Handling:Grain, ore, and liquid bulk cargo operations require specialized grab and conveyor interfaces.
- General Cargo:Breakbulk and project cargo flexibility sustains forklift and mobile crane demand.
- RoRo Operations:Roll-on/roll-off vessel loading demands low-ground-pressure terminal tractors.
Container handling absorbs the majority of equipment investment; bulk material handling is gaining specification share fastest in commodity-exporting economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's Maasvlakte terminals anchor European electrification momentum as the EU Green Deal tightens emission standards for harbor equipment. Terminal operators across major maritime hubs are balancing charging infrastructure capex against residual diesel fleet utilization as regulatory phase-in schedules diverge.
China
Shanghai Yangshan automated terminal validates autonomous terminal tractor fleets at scale, compressing labor costs and extending operational windows. The country's GB standards and NMPA-equivalent harbor safety protocols mandate operator-assist systems that elevate base equipment cost structures. Shanghai Zhenhua Heavy Industries and domestic port operators scale automated terminal tractor fleets through centralized purchasing power.
Germany
Hamburg and Bremerhaven terminals mandate 350V electric architectures as tender baselines, standardizing cross-fleet charging infrastructure across northern harbors. The EU F-Gas Regulation's hydrofluorocarbon phase-down eliminates refrigerant-dependent climate control systems from equipment specifications. Industrial clusters in the Hamburg metropolitan region anchor automation software validation for long-term service contracts.
United States
EPA Tier 4 Final marine engine standards accelerate equipment turnover toward hybrid and electric terminal tractors at harbor authorities facing compliance deadlines. The Port of Los Angeles and Port of Long Beach drive electrification procurement through California Air Resources Board mandates. Pacific Northwest terminals concentrate battery energy density validation projects for 8-hour continuous duty cycles.
Netherlands
Rotterdam Maasvlakte terminals demonstrate throughput gains from automated reach stacker fleets that justify automation capex for peer facilities. EU Green Deal procurement rules specify electric reach stackers as baseline equipment, though charging infrastructure gaps delay deployment at secondary ports. The Randstad port complex anchors predictive maintenance software integration with OEM service contracts.
India
Jawaharlal Nehru Port Trust and Mundra Port operators accelerate replacement cycles for diesel-powered yard equipment as harbor traffic volumes expand. The country's national safety regulator mandates equipment certification protocols that extend supplier validation timelines. Industrial corridors in Gujarat and Maharashtra concentrate bulk material handling equipment demand from commodity-exporting economies.
Port Material Handling Equipment Vehicle Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying structural steel assemblies and precision control modules. The vendor base stratifies across three tiers: automation-software bundlers anchoring long-term service contracts, scale manufacturers compressing lead times through captive production, and regional fabricators serving secondary ports with standardized specifications. Consolidation pressure concentrates among mid-tier suppliers lacking embedded diagnostic capabilities or electrification portfolios. Dominant competitive moves include vertical integration into battery thermal management systems and strategic partnerships with charging infrastructure providers.
Among Nordic automation-software bundlers, Kalmar leverages its embedded stack to anchor long-term service contracts across harbor authorities. Liebherr Group exemplifies the premium-capability tier through crane-lifting specifications that exceed competitor ratings for ultra-large container vessels. Shanghai Zhenhua Heavy Industries represents the scale-manufacturing archetype, occupying a position where manufacturing scale compresses lead times for volume port operators. Sany Heavy Industry sits within the domestic-replacement-cycle tier, anchoring equipment turnover through centralized procurement relationships with Chinese port groups.
| Leading Market Players |
|---|
| Kalmar |
| Konecranes |
| Liebherr Group |
| Sany Heavy Industry |
| Shanghai Zhenhua Heavy Industries |
| Terberg |
| Caterpillar |
| Toyota Industries |
| Hyster-Yale |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese structural steel fabrication is compressing supplier margins while simultaneously granting volume buyers procurement leverage across long-lead crane contracts. This utilization dynamic forces European and North American OEMs to absorb input cost volatility or cede specification share to scale manufacturers with captive production.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with port operators commanding 15-25% unit cost reductions on fleet-scale orders above 50 units. Price differentiation hinges on electrification certification grade and after-sales service bundling, with EU Green Deal-compliant electric reach stackers carrying premium positioning against Tier 4 Final diesel equivalents. Pricing pressure stems from steel and copper input cost volatility that erodes margin visibility on multi-year contracts. State-owned Chinese port groups exhibit lowest price sensitivity due to centralized purchasing power, while Southeast Asian secondary ports face acute budget constraints that favor standardized specifications.
Supply Chain Analysis
Supplier-financing facilities with 180-day extended payment terms have become standard for European and North American port authorities managing electrification capex cycles. Manufacturing concentrates in China, Germany, and Finland, with Shanghai Zhenhua Heavy Industries and Kalmar anchoring respective scale and automation tiers. Raw material dependencies center on high-grade structural steel, lithium iron phosphate battery cells, and precision hydraulic control modules. Single-source vulnerability in semiconductor-dependent automation controllers creates exposure to foundry allocation disruptions. Distribution runs through OEM-direct channels for major terminal operators and dealer networks for secondary ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Port equipment demand is recovering from cyclical lows as container throughput rebounds and EU emission enforcement accelerates fleet replacement timelines.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance software into 10-year availability guarantees, countering margin compression from electrification hardware commoditization. Deepen backward integration into battery thermal management systems to capture value migrating from mechanical assemblies to powertrain electronics. Prioritize certification investment in IEC 61508 functional safety to defend automation specification share against emerging software entrants. For New Entrants and Emerging Players: Build out aftermarket service capabilities targeting secondary ports in Vietnam and Indonesia where OEM coverage gaps persist. Southeast Asian greenfield terminals present the most penetrable segment, with automation-ready specifications from commissioning bypassing legacy retrofit barriers. Pursue charging infrastructure partnerships as the primary go-to-market angle, bundling equipment supply with grid connection project management. For Investors and Strategic Acquirers: Long-term, this sits as a electrification-infrastructure play because port decarbonization mandates will sustain equipment replacement demand regardless of trade volume cyclicality. Acquisition targets should emphasize OEMs with embedded software stacks and remote diagnostic capabilities that lock in recurring service revenue. Watch battery energy density validation timelines as the critical inflection signal—8-hour continuous duty cycle certification will separate viable electric platforms from demonstration projects.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Grid connection lead times delay electric fleet deployment at capital-constrained secondary ports. |
| Predictive Maintenance Software Integration | Telematics bundling generates recurring revenue that offsets equipment sales cyclicality for OEMs. |
| Battery Thermal Management Backward Integration | In-house production of powertrain electronics captures value migrating from mechanical assemblies. |
| Automation-Ready Equipment Specification | Greenfield terminals in Vietnam and Indonesia bypass legacy retrofit constraints from commissioning. |
| Long-Term Service Contract Anchoring | Nordic port authorities now require 10-year availability guarantees bundled with original purchases. |
Research Methodology
Desk research of customs trade databases, OEM technical specifications, and port authority procurement records preceded structured interviews with terminal operations directors, fleet procurement managers, and aftermarket service heads. Primary fieldwork with equipment maintenance supervisors and automation software engineers was cross-validated against secondary sources including EU regulatory filings, EPA emission certification databases, and Chinese GB standard documentation. Bottom-up unit demand estimates were triangulated against top-down port throughput capacity expansion plans.
Assumptions regarding regulatory phase-in schedules, battery cost decline curves, and container trade volume trajectories were held fixed across baseline scenarios while stress-testing sensitivity to steel price volatility and charging infrastructure deployment rates. Segmentation modeling incorporated product type, technology architecture, end-user concentration, and application intensity dimensions. CAGRs were derived from logistic diffusion curves fitted to electrification adoption patterns observed in early-mover terminals.
Stress conditions across lithium cell supply availability, grid interconnection timelines, and emission enforcement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding technology cost trajectories and regulatory implementation schedules. Macroeconomic contraction, trade policy disruption, or breakthrough automation validation timelines would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Stair Lifts and Climbing Devices Market
Material Handling Equipment
Rough Terrain Lift Truck Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Automated Material Handling (AMH) Market
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
High-Density Racks Market
Material Handling Equipment
Global Hydraulic Equipment Market
Material Handling Equipment
Sweep Depalletizers Market
Material Handling Equipment
Asia Pacific Mobile Crane Market
Material Handling Equipment
Industrial Girth Gear Market
Material Handling Equipment
Eye and Eye Turnbuckle Market