

High Pressure Grease Hose Market Size, Share, and Industry Trends Forecast 2026-2036
High Pressure Grease Hose Market Insights
Capital-intensity divergence between integrated manufacturers and assembly-focused competitors is bifurcating competitive outcomes in the high pressure grease hose sector. Parker Hannifin leverages captive steel-braiding capacity and in-house elastomer compounding to command premium positioning in North American energy infrastructure. Gates Corporation anchors its position through vertical control over crimping technology and global distribution density for replacement cycles. Manuli Hydraulics competes via specialized marine and offshore certifications that few rivals replicate at scale.
High pressure grease hose denotes reinforced elastomeric conduit engineered to transmit lubricating grease at operating pressures typically exceeding 3,000 PSI, with steel wire braiding or textile plies providing burst resistance and dimensional stability under impulse loading; its primary purpose is maintaining bearing surfaces and friction points in mobile and stationary equipment where centralized lubrication systems reduce downtime. Wire braided construction dominates OEM installations for mining and construction equipment where impulse fatigue governs replacement intervals. Steel reinforced variants sustain margin pools in energy sector applications requiring API-compliant pressure ratings and sour gas compatibility. Composite configurations represent the fastest-growing product category as thermoplastic liners displace rubber in food-processing and clean-environment manufacturing plants.
EPA emissions enforcement for non-road diesel equipment indirectly tightens grease containment standards, while REACH restrictions on phthalate plasticizers force reformulation of cover compounds for European export eligibility. OSHA machinery guarding regulations in US manufacturing plants mandate reliable lubrication access points, embedding hose integrity into workplace safety compliance. ISO 18752 pulse-test specifications increasingly filter supplier qualification for multinational OEM contracts. Stakeholders must monitor material substitution timelines and regional certification divergence to align capacity investments with shifting specification baselines.
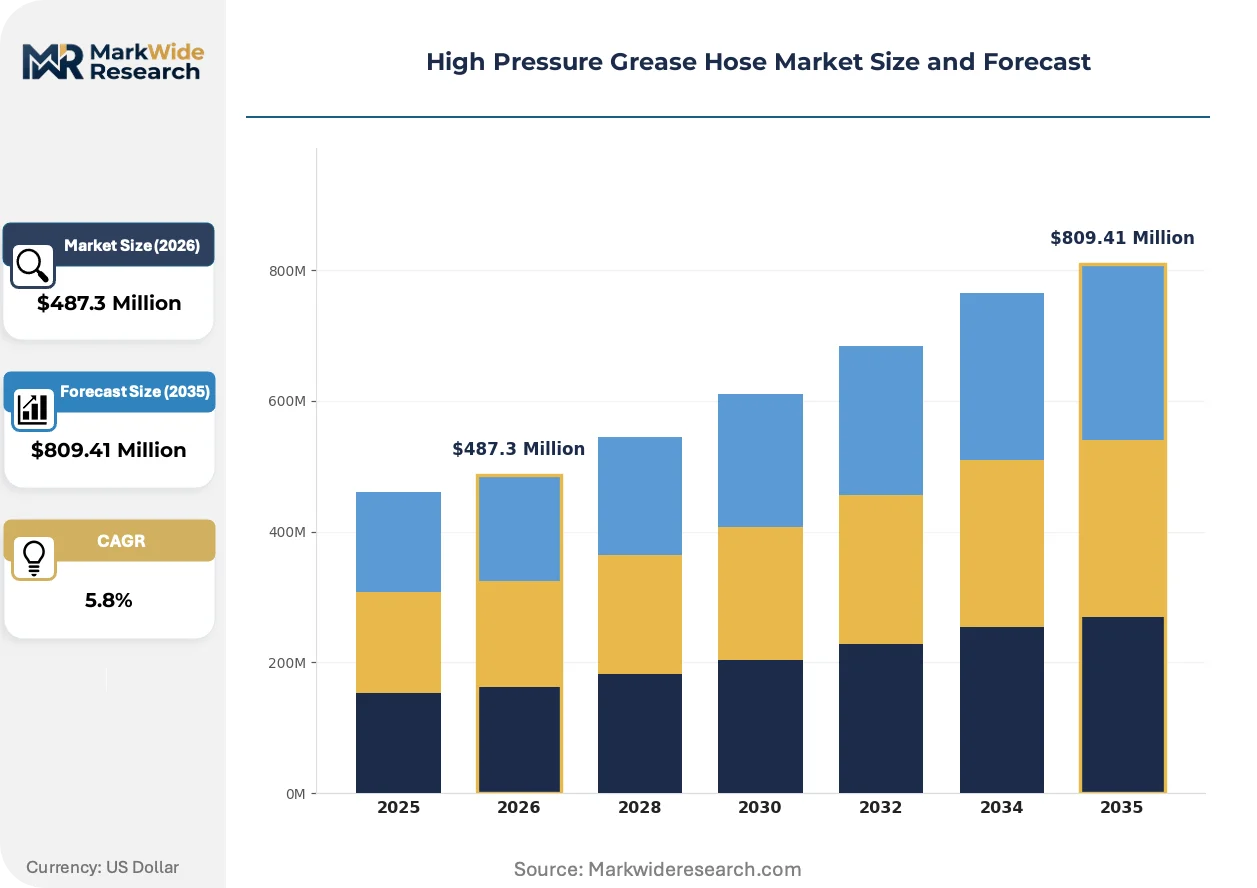
Market Dynamics
Steel-braided construction faces systematic displacement by thermoplastic composite architectures as OEMs pursue weight reduction and impulse-fatigue resistance in centralized lubrication systems. REACH-mandated phthalate reformulation and EPA emissions enforcement are simultaneously rewriting material qualification baselines across export markets.
Growth Catalysts
- Construction equipment uptime mandates:Mining operators in Australia and Canada specify 10,000-hour impulse-life ratings for hydraulic shovels and haul trucks, forcing hose upgrades at shorter replacement cycles.
- REACH Article 33 compliance:ECHA restrictions on SVHC substances in rubber compounds compel European manufacturers to certify alternative plasticizers, creating specification-driven replacement demand.
- Steel wire braiding automation:Captive braiding capacity at integrated producers compresses lead times for OEM bundling contracts in German and US heavy machinery supply chains.
Market Restraints
- Specialty elastomer concentration:Hydrogenated nitrile butadiene rubber supply concentrates among three petrochemical suppliers in Germany and Japan, exposing compounders to input volatility.
- API 16C certification barriers:Sour gas compatibility testing for energy sector hoses requires 18-month qualification timelines that freeze out mid-scale competitors from premium margin pools.
- Thermoplastic liner substitution:Polyamide 11 and 12 tubes in food-processing applications eliminate steel reinforcement entirely, eroding addressable volume in clean-environment manufacturing.
Strategic Opportunities
- India infrastructure buildout:National highway and rail corridor projects under the Ministry of Road Transport and Highways are deploying imported mining equipment with unserved aftermarket replacement needs.
- EU Green Deal machinery retrofit:Circular economy mandates for extending equipment life are accelerating centralized lubrication retrofits in Polish and Romanian steel mills.
- Digital crimping integration:RFID-embedded hose assemblies converging with IoT maintenance platforms enable predictive replacement scheduling for fleet operators in Brazilian agriculture.
Industry Challenges
- ISO 18752 pulse-test certification backlog:Accredited laboratory capacity constraints in North America and Europe are delaying supplier qualification for multinational OEM contracts by 8-12 months.
- Legacy equipment compatibility:Metric-to-imperial fitting standard divergence across 1980s-era European and Japanese installed bases complicates aftermarket kit standardization for distributors.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Pressure Grease Hose Market Trends and Innovations
Material science convergence with digital traceability systems is restructuring how specification compliance gets verified and monetized across the value chain. Three developments are compressing traditional competitive advantages.
Thermoplastic elastomer liners bonded to high-tensile synthetic fiber braids are supplanting conventional rubber-and-steel architectures in food-processing and pharmaceutical clean rooms. Swiss and Dutch equipment OEMs specify these configurations for CIP/SIP compatibility, eliminating metallic contamination risks while reducing assembly weight by 40%. The shift is compressing margin pools for steel-braiding specialists unable to retool fiber winding capacity.
REACH Annex XVII restrictions on short-chain chlorinated paraffins are forcing cover compound reformulations for European export eligibility. German compounders are qualifying bio-based plasticizers from rapeseed and castor oil feedstocks, adding 15-20% to raw material costs but securing ECHA pre-registration for downstream OEM bundling. North American producers serving EU markets face parallel compliance investments or exclusion from specification tenders.
Condition-monitoring procurement is displacing calendar-based replacement contracts for fleet operators in Australian mining and Canadian oil sands. Predictive algorithms analyzing pressure spike frequency and temperature cycling are unbundling hose supply from maintenance labor, favoring suppliers with integrated sensor-assembly capabilities. This pattern concentrates purchasing authority with reliability engineering functions rather than traditional MRO procurement desks.
High Pressure Grease Hose Market Segmentation
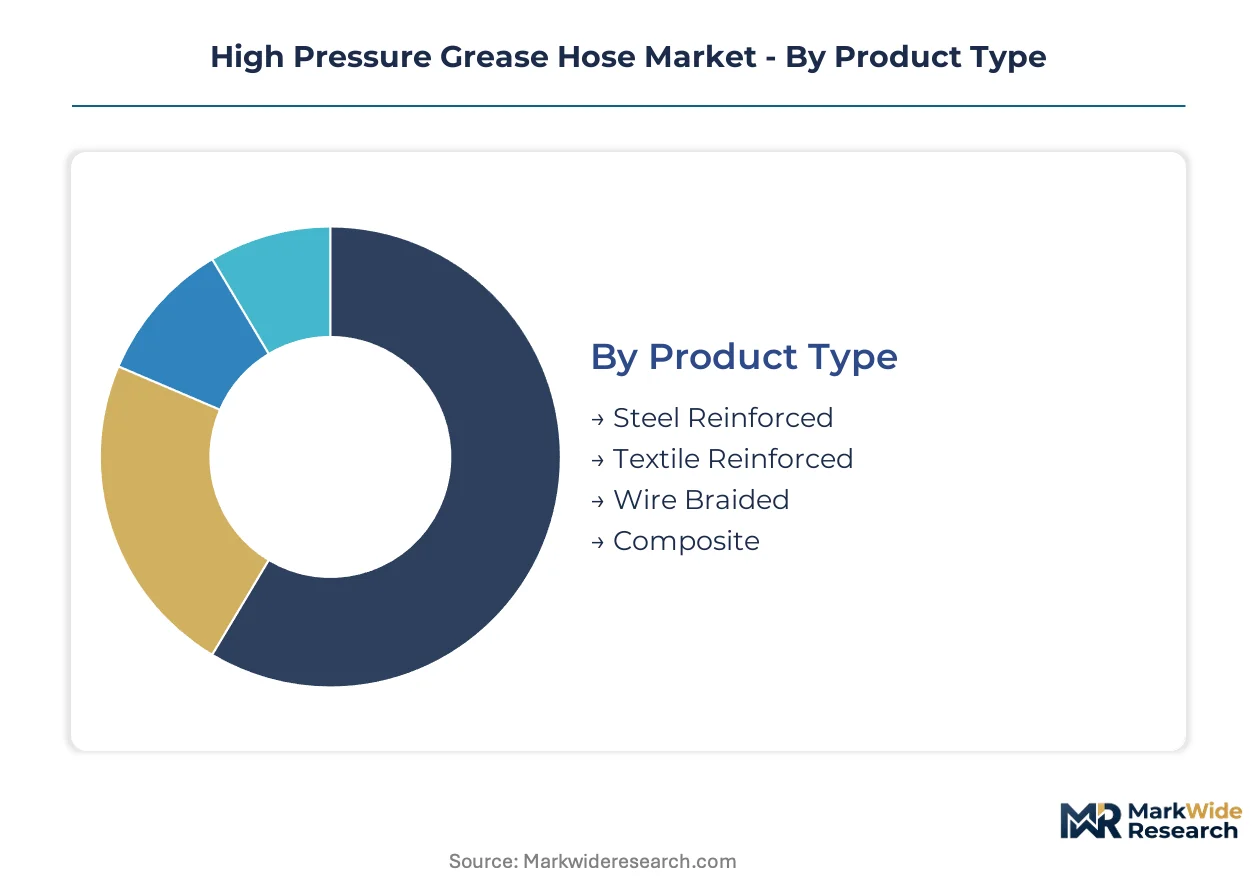
Specification divergence across pressure ratings and material architectures creates distinct margin pools in the high pressure grease hose sector. Procurement patterns bifurcate between OEM bundling contracts demanding certified impulse-life ratings and aftermarket replacement cycles governed by fleet maintenance protocols.
Product Type:
REACH Article 33 SVHC restrictions and EPA emissions enforcement are segmenting qualification pathways for rubber compound formulations across export markets.
- Wire Braided:Steel wire braiding with elastomeric cores dominates mining and construction equipment where ISO 18752 pulse-test certification filters supplier eligibility. Australian and Canadian operators specify 10,000-hour impulse-life ratings for hydraulic shovels, compressing replacement cycles and anchoring OEM bundling demand.
- Composite:Thermoplastic elastomer liners bonded to synthetic fiber braids are displacing steel architectures in food-processing clean rooms where CIP/SIP compatibility eliminates metallic contamination risks. Swiss and Dutch equipment OEMs specify these configurations, reducing assembly weight by 40% while securing REACH-compliant plasticizer formulations.
- Steel Reinforced:API 16C-certified variants serve energy sector applications requiring sour gas compatibility and pressure ratings exceeding 5,000 PSI.
- Textile Reinforced:Lower-pressure textile ply construction addresses agricultural and light industrial equipment where cost sensitivity outweighs impulse-fatigue requirements.
Wire Braided handles the majority of throughput; Composite is the fastest mover on share.
Application:
Equipment uptime mandates and centralized lubrication retrofits are redistributing volume across mobile and stationary machinery categories.
- Heavy Machinery:Mining haul trucks and hydraulic shovels in Australia and Canada drive specification intensity through 10,000-hour rated impulse-life requirements. OEM bundling contracts with German and US machinery manufacturers concentrate procurement authority for this segment.
- Construction Equipment:Centralized lubrication systems in highway and rail corridor projects under India's Ministry of Road Transport and Highways are generating unserved aftermarket replacement demand for imported equipment fleets.
- Hydraulic Systems:Stationary industrial presses and machine tools require consistent pressure maintenance for bearing surface longevity.
- Agricultural Tools:Brazilian fleet operators are integrating RFID-embedded hose assemblies with IoT maintenance platforms for predictive replacement scheduling.
Heavy Machinery commands the largest installed base; Construction Equipment is expanding most quickly on project-driven procurement.
End User Industry:
Margin concentration follows certification complexity and replacement cycle predictability across industrial verticals.
- Mining Operators:Condition-monitoring procurement is displacing calendar-based replacement contracts in Australian mining and Canadian oil sands. Predictive algorithms analyzing pressure spike frequency concentrate purchasing authority with reliability engineering functions.
- Energy Sector:API 16C certification barriers require 18-month qualification timelines for sour gas compatibility, freezing out mid-scale competitors from premium margin pools in North American shale operations.
- Manufacturing Plants:OSHA machinery guarding regulations mandate reliable lubrication access points, embedding hose integrity into workplace safety compliance.
- Transportation Services:Fleet maintenance protocols for rail and heavy trucking emphasize standardized crimping technology and rapid replacement availability.
Mining Operators generate the highest specification intensity; Energy Sector delivers the steepest margin expansion trajectory.
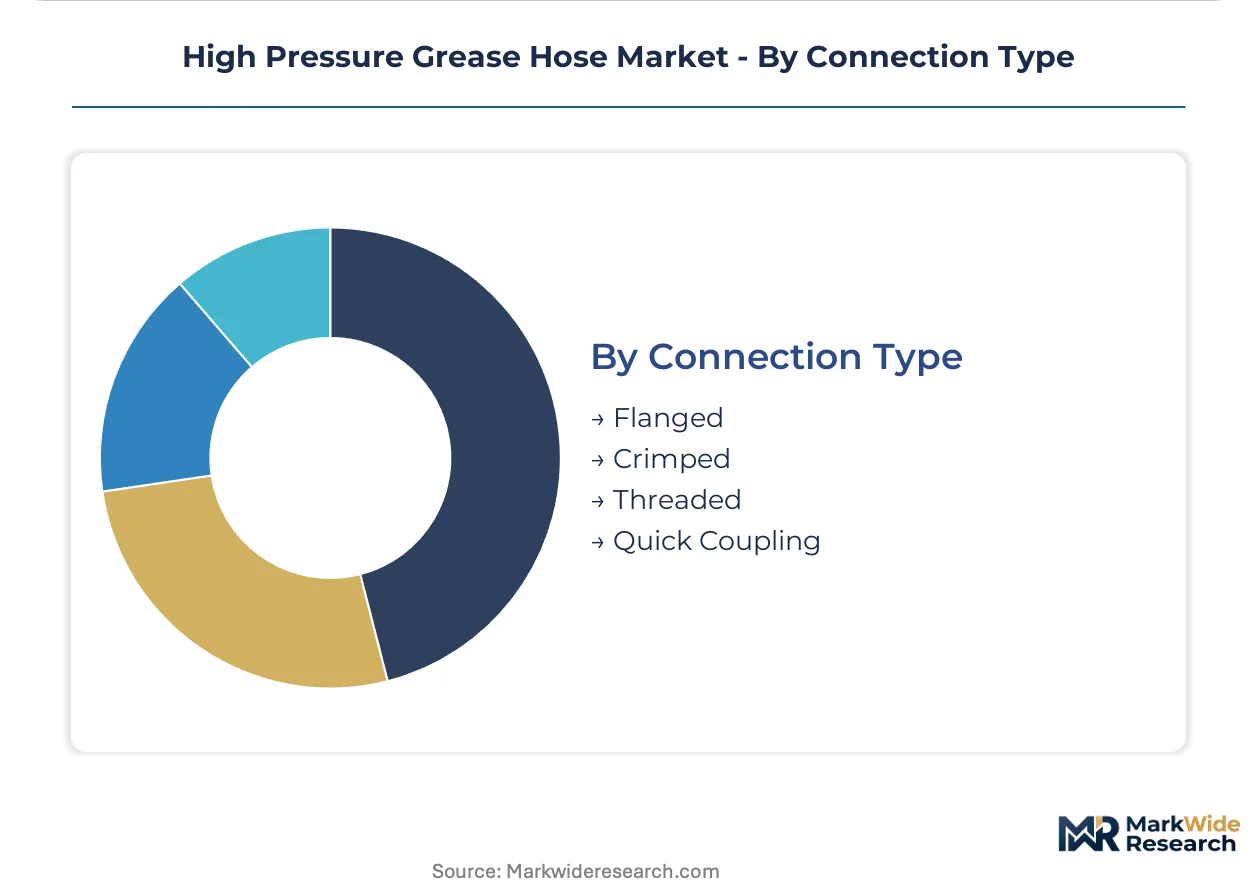
Connection Type:
Assembly automation and legacy equipment compatibility are segmenting crimping technology adoption curves.
- Crimped:Gates Corporation anchors market position through vertical control over crimping technology and global distribution density for replacement cycles. Digital crimping integration with RFID-embedded assemblies enables predictive maintenance platforms.
- Quick Coupling:Mobile equipment operators in construction and agriculture favor rapid connection architectures minimizing downtime during field service.
- Flanged:High-pressure stationary installations in energy and manufacturing specify bolted flange connections for secure containment.
- Threaded:Legacy metric-to-imperial fitting standard divergence across 1980s-era European and Japanese installed bases complicates aftermarket kit standardization.
Crimped dominates replacement volume; Quick Coupling is gaining share fastest on mobile equipment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German and US manufacturing corridors where OEM bundling contracts anchor specification intensity, while cost-sensitive procurement in Indian infrastructure projects compresses margin realization for standard-grade assemblies.
United States
Shale field operators in Texas and North Dakota specify API 16C-certified assemblies for sour gas compatibility, tightening supplier qualification timelines. EPA emissions enforcement for non-road diesel equipment indirectly elevates grease containment standards across construction fleets. Houston anchors energy sector demand through oilfield services concentration.
Germany
REACH Article 33 SVHC restrictions compel rubber compound reformulations using bio-based plasticizers from rapeseed and castor oil feedstocks. Stuttgart and Munich machinery OEMs bundle certified impulse-life hose assemblies with mining and construction equipment exports. ECHA pre-registration requirements filter supplier eligibility for European tender participation.
China
State-owned mining conglomerates in Shanxi and Inner Mongolia deploy imported hydraulic shovels with unserved aftermarket replacement cycles. MIIT industrial equipment upgrade programs accelerate centralized lubrication retrofits in steel mills. Yangtze River Delta manufacturing clusters concentrate domestic hose fabrication capacity.
Australia
Queensland and Western Australia mining operators specify 10,000-hour impulse-life ratings for haul trucks, compressing replacement cycles and embedding condition-monitoring procurement. TGA-equivalent equipment safety standards align with ISO 18752 certification requirements. Perth serves as the regional distribution hub for Pilbara iron ore operations.
India
National highway and rail corridor projects under the Ministry of Road Transport and Highways deploy imported mining equipment with specification gaps in aftermarket service networks. BIS standards for hydraulic hose assemblies remain in draft phase, creating certification uncertainty for domestic fabricators. Mumbai and Delhi industrial zones concentrate distribution infrastructure.
High Pressure Grease Hose Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturers commanding premium positioning through captive steel-braiding capacity while assembly-focused competitors compete on replacement cycle availability and distribution density. The vendor base spans three tiers: multinational fluid power conglomerates with in-house elastomer compounding, specialized hydraulic hose fabricators with regional certification depth, and commodity assemblers serving price-sensitive aftermarket demand. Dominant competitive moves include backward integration into steel wire braiding automation and strategic partnerships with IoT maintenance platform providers.
Among diversified industrial conglomerates, Parker Hannifin and Gates Corporation exemplify contrasting strategic positions within the premium tier, while Manuli Hydraulics occupies a specialized niche through marine and offshore certification concentration. Parker Hannifin represents the integrated manufacturer archetype with captive upstream capacity. Gates Corporation anchors distribution-intensive positioning through vertical control over crimping technology. Manuli Hydraulics exemplifies certification-driven specialization that few rivals replicate at scale.
| Leading Market Players |
|---|
| Parker Hannifin |
| Gates Corporation |
| Eaton |
| Continental AG |
| Manuli Hydraulics |
| Danfoss |
| Hansa-Flex |
| Alfagomma |
| Kuriyama Holdings |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements with German and US mining equipment OEMs lock in both hydrogenated nitrile butadiene rubber supply access and 18-24 month price visibility for integrated manufacturers, insulating them from spot volatility in specialty elastomer feedstocks. These contracts embed REACH-compliant compound certification costs into baseline pricing, compressing margin flexibility for assembly-focused competitors sourcing cover materials on open markets.
Pricing Analysis
Configured-to-order pricing for API 16C-certified assemblies commands 35-50% premiums over standard wire-braided configurations due to 18-month qualification timelines and sour gas compatibility testing. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and impulse-life rating, with Australian mining operators least price-sensitive given uptime mandates and Indian infrastructure contractors most cost-constrained. Pricing pressure stems from thermoplastic composite substitution eroding steel-braided volumes in food-processing applications. OEM bundling contracts favor suppliers with captive steel-braiding capacity, while aftermarket distributors compete on replacement cycle availability.
Supply Chain Analysis
Hydrogenated nitrile butadiene rubber supply concentrates among three petrochemical suppliers in Germany and Japan, creating single-source vulnerability for compounders serving REACH-compliant export markets. Raw material dependencies span synthetic rubber polymers, high-tensile steel wire, and bio-based plasticizers from rapeseed and castor oil feedstocks. Distribution runs through OEM bundling contracts for mining and construction equipment, with aftermarket replacement cycles served by regional fabrication networks. Tariff exposure on steel wire imports from China compounds cost pressure for North American assemblers lacking captive braiding capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM procurement consolidation in German and US heavy machinery supply chains is shifting bargaining power toward bundled hose-assembly contracts, fragmenting aftermarket pricing authority among distributors.
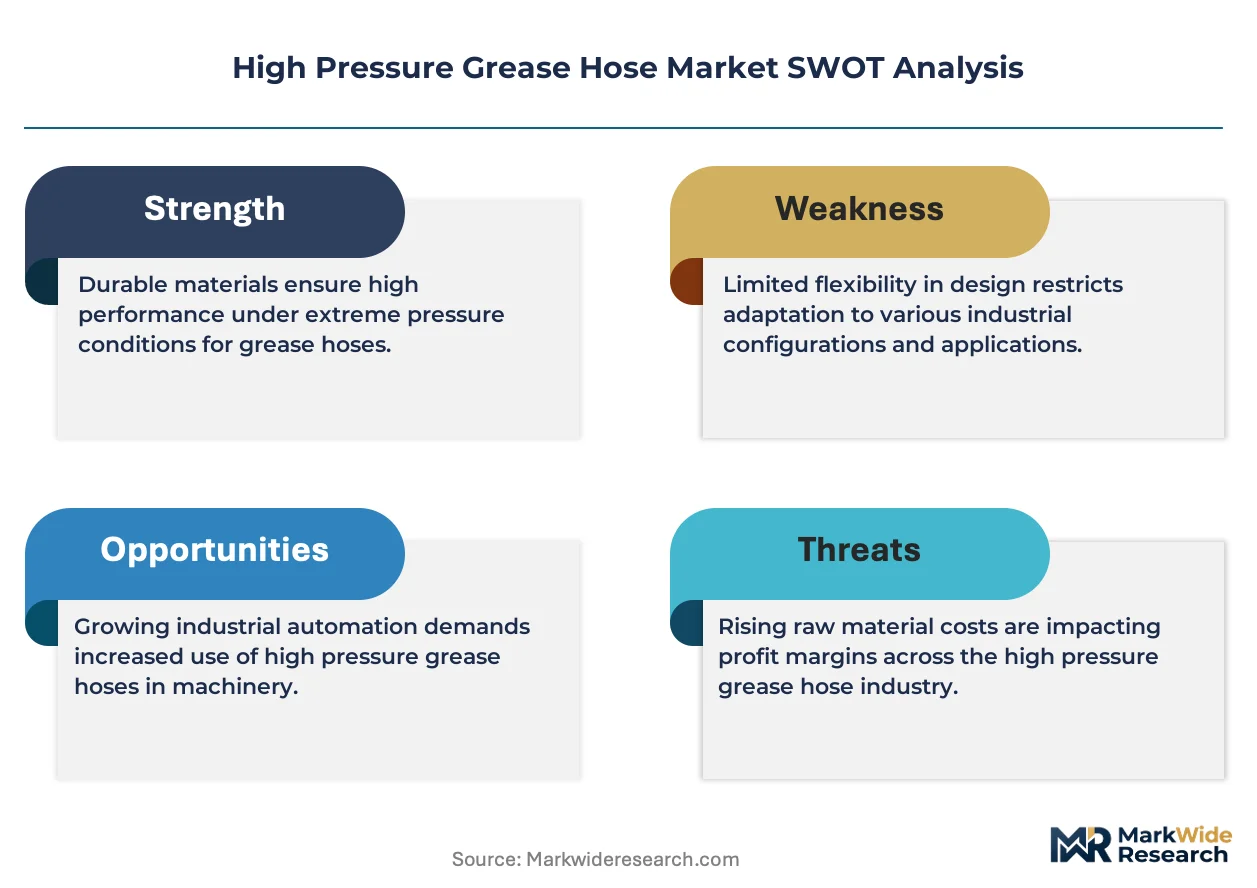
For Market Incumbents: Consolidate backward integration into steel wire braiding automation to compress lead times for OEM bundling contracts, while securing ECHA pre-registration for bio-based plasticizer formulations to defend European export eligibility against REACH Article 33 enforcement. Thermoplastic composite substitution in food-processing applications threatens traditional rubber-and-steel architectures, requiring fiber winding capacity investments or partnership with Swiss and Dutch clean-room equipment OEMs. For New Entrants and Emerging Players: Differentiate on digital crimping integration with RFID-embedded hose assemblies converging to IoT maintenance platforms, targeting Brazilian agricultural fleet operators and Australian mining condition-monitoring procurement shifts. India's unserved aftermarket for imported highway and rail corridor equipment offers the most penetrable geography, with BIS certification uncertainty creating first-mover advantage for early standard adopters. Partner with reliability engineering functions rather than traditional MRO procurement desks to access predictive replacement scheduling contracts. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale fabricators with regional certification depth in API 16C or ISO 18752 compliance, positioned for acquisition by multinational fluid power conglomerates seeking qualification backlog resolution. Long-term viability hinges on material substitution timelines and regulatory divergence between EPA emissions enforcement and REACH SVHC restrictions. Watch thermoplastic liner adoption rates in food-processing and pharmaceutical clean rooms as inflection indicators for steel-braided volume erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Wire Braiding | Captive braiding capacity compresses lead times for German and US OEM bundling contracts. |
| REACH-Compliant Compound Reformulation | Bio-based plasticizer certification from rapeseed and castor oil secures ECHA pre-registration for European tenders. |
| Digital Crimping with RFID Integration | Sensor-embedded assemblies converge with IoT platforms for predictive maintenance in Australian mining. |
| Fiber Winding Capacity Expansion | Thermoplastic elastomer liner production addresses Swiss and Dutch clean-room equipment specifications. |
| Regional Certification Depth Investment | API 16C qualification capabilities unlock premium margin pools in North American shale operations. |
Research Methodology
A standing panel of maintenance directors at Australian and Canadian mining operations, OEM procurement teams at German and US heavy machinery manufacturers, aftermarket service heads at regional hose fabricators, and technical R&D directors at specialty elastomer compounders provided ongoing calibration across primary interview cycles. Secondary validation drew from customs and trade data, SEC 10-K filings of listed fluid power conglomerates, ECHA SVHC registration databases, and ISO 18752 certification records. Bottom-up volume estimates from country-level equipment fleet data triangulated against top-down OEM production forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including pressure rating tier, material architecture, end-use industry, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating equipment replacement cycle data, infrastructure project pipelines, and regulatory compliance timelines. Industry-specific forecast inputs encompassed mining uptime mandates, REACH reformulation deadlines, and thermoplastic substitution rates in clean-environment manufacturing.
Decision-makers should treat outputs as directional under base assumptions of stable EPA emissions enforcement and REACH Article 33 implementation timelines; material deviation in regulatory stringency or composite material adoption would warrant model refresh. Practitioners should keep alternative scenarios live as hydrogenated nitrile butadiene rubber supply concentration and ISO 18752 laboratory capacity constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.