
 Global Loading Dock Lifts Market | 2026-2036
Global Loading Dock Lifts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Loading Dock Lifts Market Outlook
Steel-reinforced aluminum decking is restructuring product economics across the loading dock lifts sector by reducing unit weight without sacrificing load-bearing thresholds. Rite-Hite Holding Corporation leverages vertical integration in hydraulic component manufacturing to sustain margin control across North American distribution. Blue Giant Equipment Corporation anchors its position through specialized scissor lift engineering for cold-storage warehousing applications. ASSA ABLOY Group competes on channel breadth, extending its dock equipment portfolio through established commercial door and loading system networks.
Loading dock lifts are electro-hydraulic or mechanically actuated platforms engineered to bridge height differentials between delivery vehicles and facility floors, typically rated for dynamic loads from 1,000 kg to 3,000 kg and governed by EN 1570 and ANSI MH29.1 stability standards. Their primary purpose centers on eliminating manual handling injuries while accelerating throughput at freight transfer points. Hydraulic lifts dominate installed base volumes due to proven durability in continuous-cycle operations, while portable lifts represent the fastest-expanding configuration as third-party logistics providers seek flexible capacity without permanent infrastructure commitment. Fixed installations retain the deepest margin pools, particularly in refrigerated warehousing where custom pit-mounted systems command specification premiums.
OSHA, the EU Machinery Directive, and China's SAMR enforce divergent but converging safety mandates that elevate certification costs while restricting market access for uncertified equipment. OSHA's powered industrial truck standards directly influence dock lift guarding and interlock requirements in U.S. facilities. Stakeholders must monitor evolving carbon-border adjustments and regional content rules that threaten to fragment supply chains for steel-intensive platform fabrication.
Market Dynamics
Hydraulic scissor lift platforms are displacing mechanical pit-mounted systems as e-commerce fulfillment centers prioritize rapid reconfiguration over permanent infrastructure. Steel price volatility and regional carbon-border adjustments are compressing fabrication margins while fragmenting supplier bases across North America, Europe, and Asia-Pacific.
Growth Catalysts
- OSHA workplace safety mandates:Powered industrial truck standards tighten guarding requirements, forcing facility upgrades and replacement cycles for non-compliant legacy equipment.
- EU Machinery Directive certification:EN 1570 stability standards elevate entry barriers, concentrating demand among certified manufacturers with testing infrastructure.
- Cold-storage warehousing expansion:Refrigerated logistics operators specify corrosion-resistant aluminum decking for temperature-cycling durability.
Market Restraints
- Steel input cost volatility:Platform fabrication depends on hot-rolled steel pricing, exposing margins to commodity swings without pass-through mechanisms.
- Regional content rule fragmentation:Carbon-border adjustments and local-content mandates in the EU, China, and the US complicate cross-border supply chains for steel-intensive components.
- Portable lift substitution:Third-party logistics providers favor rental and lease models over capital-intensive fixed installations, compressing OEM revenue per site.
Strategic Opportunities
- India warehouse automation:PLI scheme incentives for logistics infrastructure create first-mover positioning for hydraulic lift suppliers establishing local assembly.
- IoT-enabled predictive maintenance:Sensor-integrated lift systems converge with warehouse management platforms, enabling recurring software revenue streams.
- EU Green Deal procurement rules:Public-sector tender preferences for low-carbon equipment favor manufacturers with verified lifecycle emissions data.
Industry Challenges
- Hydraulic technician scarcity:Specialized maintenance skills for high-pressure systems lag equipment deployment rates, extending downtime and service costs.
- Legacy integration complexity:Retrofitting intelligent controls into installed mechanical lifts requires custom engineering, delaying upgrade timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Loading Dock Lifts Market |
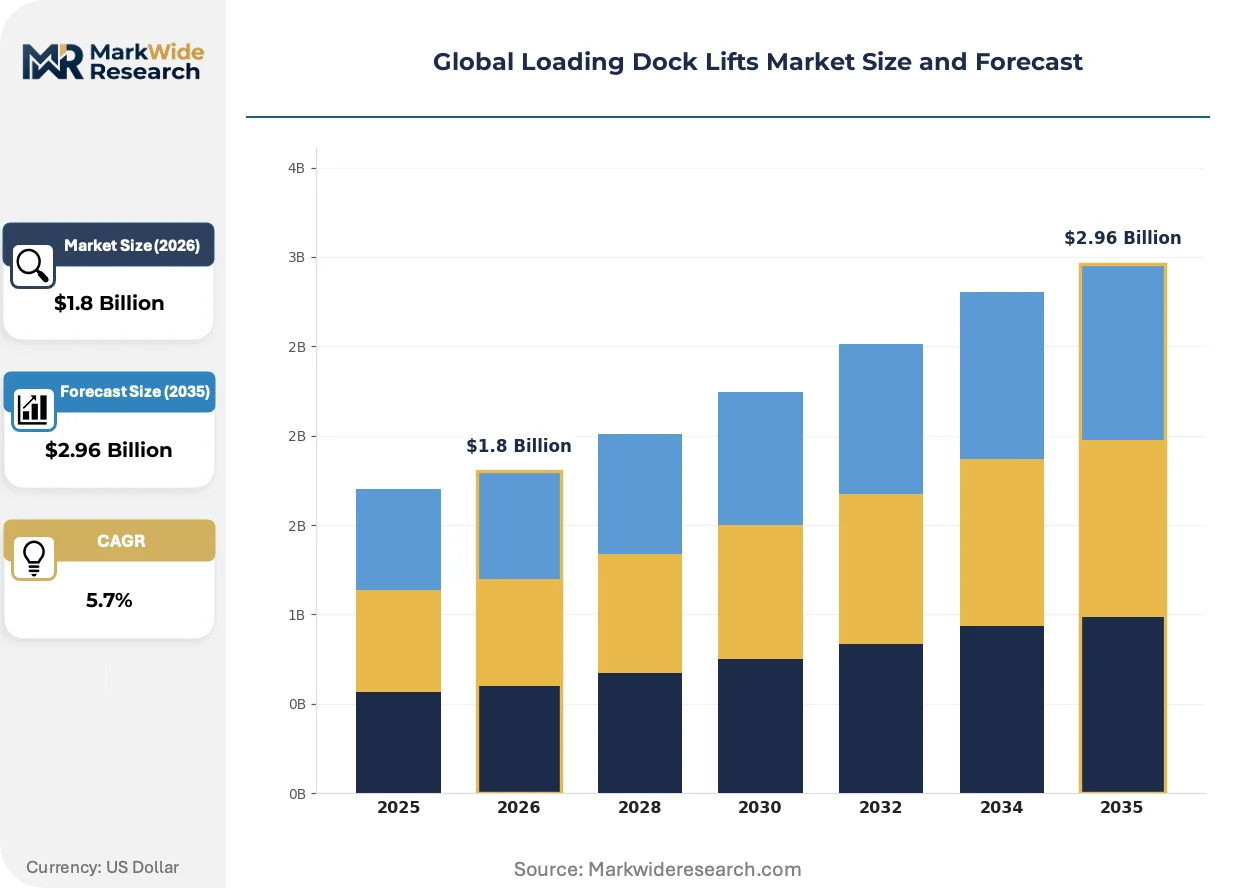
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Lifts, Mechanical Lifts, Scissor Lifts, Portable Lifts End User: Manufacturing, Warehousing, Retail, Logistics Capacity: 1000 kg, 1500 kg, 2000 kg, 3000 kg Installation Type: Fixed, Mobile, Removable, Customized |
| Companies Covered | Kelley Entrematic, Rite-Hite Holding Corporation, Blue Giant Equipment Corporation, Pentalift Equipment Corporation, Serco, Southworth, Presto Lifts, Hormann Group, ASSA ABLOY Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Loading Dock Lifts Market Strategic Shifts
Electrification and digital integration are compressing equipment lifecycles while elevating service-content economics. Manufacturers now compete on telemetry-enabled uptime guarantees rather than hardware durability alone.
Steel-reinforced aluminum decking is rewriting material specifications across the sector. The composite construction reduces unit weight by approximately thirty percent while maintaining EN 1570 load ratings. Cold-storage operators in Germany and the Netherlands are specifying this configuration for pit-mounted systems. The technology is rewriting total-cost-of-ownership calculations by cutting foundation requirements and installation labor.
China's SAMR enforcement of GB standards for industrial machinery safety is tightening conformity assessment procedures for imported equipment. Foreign manufacturers must now complete domestic testing protocols before market entry. European and North American suppliers are responding by establishing certified testing partnerships with Chinese notified bodies.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-sized third-party logistics providers. Monthly fee structures bundle hardware, maintenance, and software updates. This shift is most visible in the United States, where warehouse automation budgets favor operating expenditure classification over capital allocation cycles.
Global Loading Dock Lifts Market Segmentation
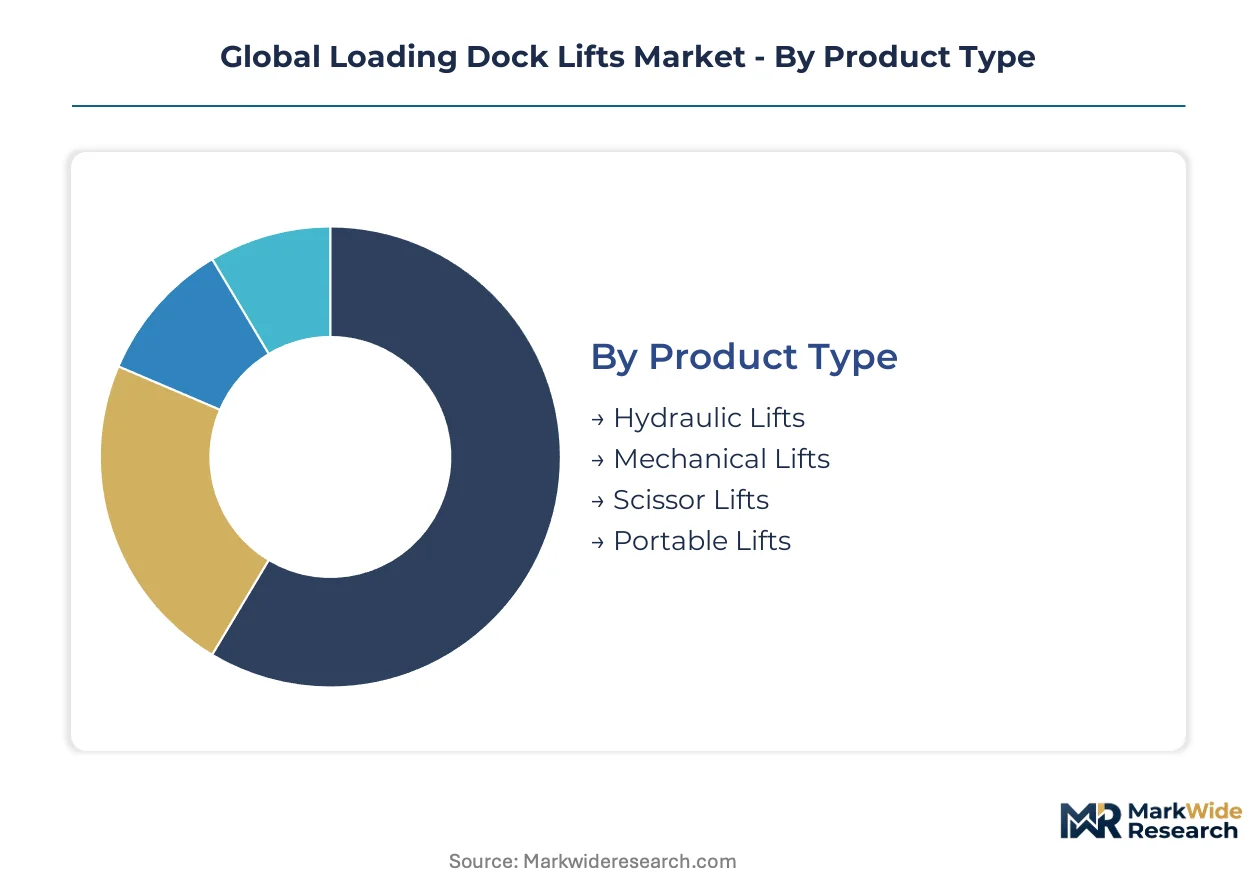
Loading dock lift procurement decisions hinge on duty-cycle intensity, facility permanence, and regulatory compliance requirements. Buyers weigh hydraulic durability against mechanical simplicity, while capacity ratings and installation flexibility determine total cost of ownership across warehouse and manufacturing footprints.
Product Type:
Facility operators select lift mechanisms based on throughput demands and maintenance infrastructure availability.
- Hydraulic Lifts:Electro-hydraulic actuation delivers continuous-cycle durability for high-volume freight transfer points. German cold-storage operators specify these for EN 1570-compliant pit-mounted installations where uptime guarantees dominate procurement criteria.
- Scissor Lifts:Collapsible scissor mechanisms enable vertical travel with minimal horizontal footprint. E-commerce fulfillment centers in the United States deploy these for rapid reconfiguration between seasonal demand peaks.
- Mechanical Lifts:Screw-jack or rack-and-pinion systems suit low-cycle applications with limited maintenance access.
- Portable Lifts:Self-contained units with integrated power supply serve third-party logistics providers seeking flexible capacity without permanent infrastructure commitment.
Hydraulic lifts lead on installed scale; portable lifts lead on momentum as rental models expand.
End User:
Application environment dictates corrosion resistance, load rating, and integration complexity requirements.
- Warehousing:Temperature-cycling operations in refrigerated logistics demand aluminum-deck configurations with specialized sealing. Dutch distribution hubs specify corrosion-resistant pit systems for continuous cold-chain handling.
- Manufacturing:Just-in-time production lines require synchronized lift cycles with conveyor systems. Automotive assembly plants in China integrate hydraulic platforms with AGV traffic management.
- Logistics:Cross-dock facilities prioritize rapid deployment and standardized guarding for mixed fleet compatibility.
- Retail:Back-of-store receiving areas favor compact footprints with manual override capabilities for low-volume deliveries.
Warehousing dominates revenue concentration; manufacturing shows steepest expansion trajectory as reshoring accelerates facility investment.
Capacity:
Load ratings align with vehicle fleet composition and palletized freight density patterns.
- 2000 kg:Standard rating for mixed freight handling accommodates two standard pallets or dense single loads. United States parcel hubs specify this tier for compatibility with common delivery vehicle bed heights.
- 3000 kg:Heavy-duty rating serves industrial machinery and beverage distribution with concentrated weight profiles. German manufacturing facilities deploy these for steel coil and bulk liquid container transfer.
- 1000 kg:Light-capacity units suit retail backrooms and small-package sorting operations.
- 1500 kg:Intermediate rating bridges standard and heavy-duty applications for specialized freight categories.
2000 kg ratings anchor volume deployment; 3000 kg ratings gain share fastest as industrial freight density increases.
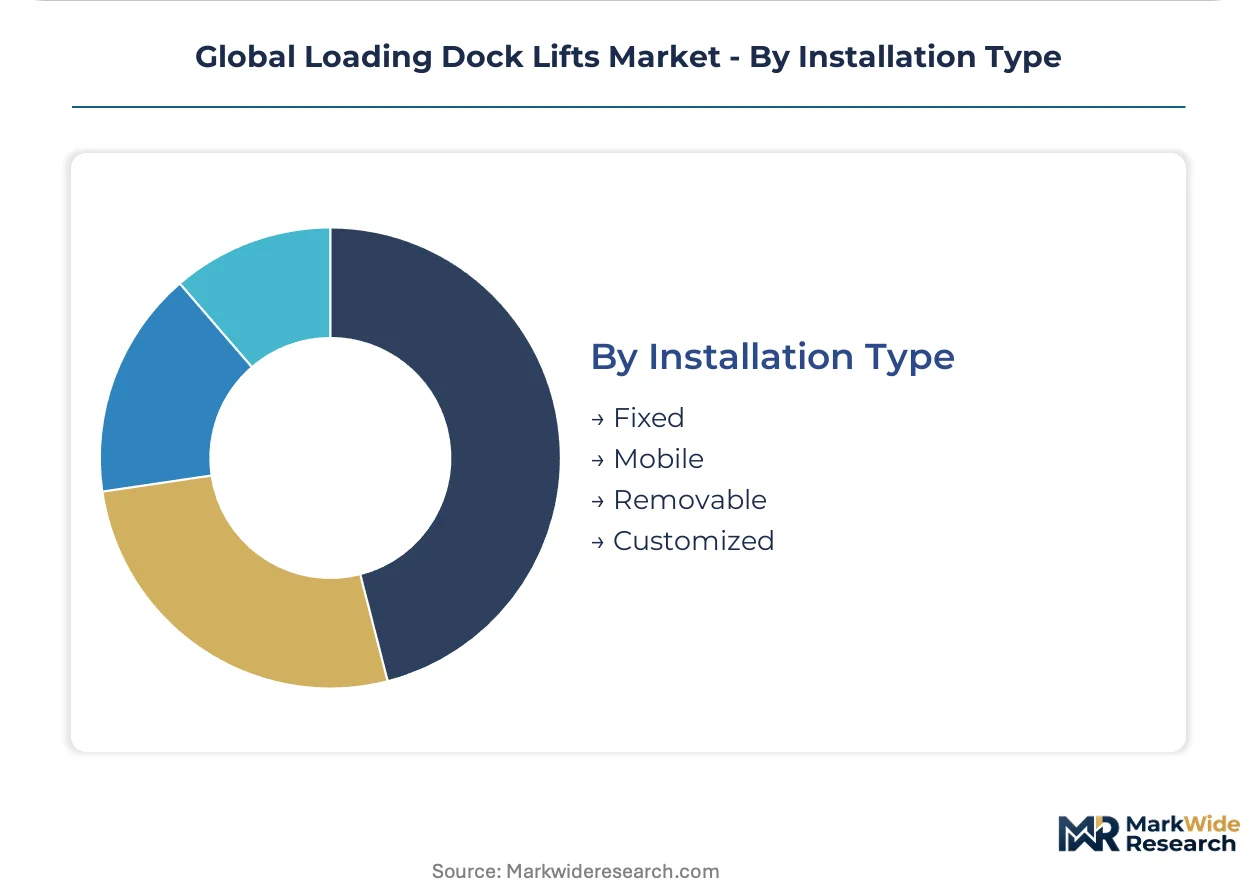
Installation Type:
Capital commitment horizons and facility lease structures determine permanence preferences.
- Fixed:Pit-mounted permanent installations deliver maximum stability and lowest cycle times for dedicated high-throughput lanes. Refrigerated warehousing commands specification premiums for custom foundation integration.
- Mobile:Wheeled or rail-mounted units enable lane reconfiguration without structural modification. Third-party logistics providers in India favor these for PLI scheme warehouse automation projects with uncertain tenure.
- Removable:Surface-mounted bolt-down systems offer intermediate flexibility for medium-term lease commitments.
- Customized:Engineered solutions address non-standard dock heights, sloped approaches, or integrated conveyor interfaces.
Fixed installations command the deepest margin pools; mobile configurations expand most quickly as equipment-as-a-service contracting displaces capital purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago's freight corridor anchors hydraulic lift procurement volumes as Midwest distribution hubs modernize legacy dock infrastructure to accommodate e-commerce fulfillment density.
United States
Parcel hubs in Memphis and Louisville drive specification demand for 2000 kg-rated pit-mounted systems synchronized with automated sortation. OSHA's powered industrial truck standards mandate guarding upgrades that accelerate replacement cycles for pre-2010 installations. Dallas-Fort Worth's cold-storage cluster commands premium pricing for corrosion-resistant aluminum decking configurations.
Germany
Ruhr Valley manufacturing facilities specify EN 1570-compliant heavy-duty platforms for steel coil transfer operations. The EU Machinery Directive's conformity assessment procedures concentrate procurement among certified domestic fabricators with testing infrastructure. Hamburg's port modernization program integrates hydraulic lifts with AGV traffic management for container freight handling.
China
Yangtze River Delta warehouse automation projects absorb mobile lift configurations under equipment-as-a-service contracting models. SAMR enforcement of GB standards for industrial machinery safety tightens import conformity procedures for foreign suppliers. Shenzhen's cross-border e-commerce hubs deploy rapid-reconfiguration scissor lifts to manage seasonal demand volatility.
India
Mumbai-Pune logistics corridor expansion under PLI scheme incentives creates first-mover positioning for hydraulic lift suppliers establishing local assembly. BIS certification requirements for material handling equipment elevate entry barriers for uncertified imports. Delhi-NCR's third-party logistics providers favor rental models over capital-intensive fixed installations.
Netherlands
Rotterdam-Antwerp distribution cluster specifications prioritize aluminum-deck pit systems for temperature-cycling durability in refrigerated logistics. EU Green Deal procurement rules favor tender participants with verified lifecycle emissions data. Eindhoven's automated fulfillment centers integrate sensor-enabled lifts with warehouse management platforms.
Global Loading Dock Lifts Market Competitive Environment
Global majors compete with regional champions across certification infrastructure and channel breadth. The vendor base stratifies into three tiers: integrated hydraulic specialists with captive component manufacturing, diversified industrial conglomerates leveraging commercial door networks, and regional fabricators competing on customization velocity. Strategic moves center on backward integration into steel-aluminum composite fabrication and equipment-as-a-service contracting models that convert capital expenditure to recurring revenue.
Among North American integrated specialists, Rite-Hite Holding Corporation and Blue Giant Equipment Corporation exemplify the hydraulic-component control archetype. ASSA ABLOY Group occupies a position representing conglomerate diversification into dock equipment through established loading system networks. Pentalift Equipment Corporation and Southworth sit within the regional customization tier, serving non-standard height and slope requirements without global scale overhead. Kelley Entrematic and Serco anchor mid-market positioning through distribution partnerships rather than captive manufacturing.
| Leading Market Players |
|---|
| Kelley Entrematic |
| Rite-Hite Holding Corporation |
| Blue Giant Equipment Corporation |
| Pentalift Equipment Corporation |
| Serco |
| Southworth |
| Presto Lifts |
| Hormann Group |
| ASSA ABLOY Group |
| Others |
Value Chain & Pricing Dynamics
E-commerce fulfillment center procurement teams concentrate buying power across standardized hydraulic lift configurations, anchoring contract pricing to steel-input indices and volume-tier rebates rather than specification premiums. This buyer concentration forces OEMs toward transparent cost-plus structures with limited brand markup elasticity.
Pricing Analysis
Hot-rolled steel index pass-through clauses dominate hydraulic lift contracting, with quarterly adjustments tethering platform fabrication costs to commodity benchmarks. Pricing stratifies across EN 1570-certified premium tiers, standard OSHA-compliant configurations, and economy-grade mechanical alternatives lacking stability interlocks. Cost compression in economy-tier portable units is intensifying because third-party logistics rental models strip away aftermarket service bundling. Cold-storage operators show lowest price sensitivity, accepting specification premiums for aluminum-deck corrosion resistance.
Supply Chain Analysis
Dual-sourcing mandates from German automotive and Dutch refrigerated logistics buyers require qualified hydraulic cylinder suppliers from both China and Germany, fragmenting component procurement across regulatory jurisdictions. Platform fabrication draws from hot-rolled steel mills in China, Germany, and the United States, with hydraulic power units sourced from specialized component houses in Italy and Japan. Tariff exposure on Chinese steel inputs threatens margin stability for North American fabricators lacking alternative qualified suppliers. Distribution runs through OEM-direct specification sales for fixed installations and equipment-as-a-service intermediaries for portable lift rental fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage between German EN 1570 certification costs and Indian PLI scheme assembly incentives creates margin expansion potential for suppliers establishing localized fabrication with qualified testing partnerships.
For Market Incumbents: Deepen backward integration into steel-aluminum composite decking fabrication to defend margin pools against commodity volatility and capture specification premiums from cold-storage operators. Prioritize captive hydraulic component manufacturing to offset technician scarcity risks that extend service response times and erode uptime guarantee credibility. For New Entrants and Emerging Players: Capture mobile lift rental market share in India's PLI scheme warehouse corridors through equipment-as-a-service contracting that converts capital expenditure classification barriers into recurring revenue traction. Target mid-sized third-party logistics providers in the United States with telemetry-enabled predictive maintenance bundles that differentiate against legacy OEM hardware-only positioning. For Investors and Strategic Acquirers: Industrial conglomerates with commercial door and loading system networks are the most active acquirers in this space, seeking dock equipment portfolio extension. Over a multi-year horizon, consolidation viability hinges on certification infrastructure ownership rather than fabrication scale alone. Monitor BIS and SAMR enforcement intensity as the signal indicating whether local assembly requirements will accelerate or permit continued import-based market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Decking | Captures aluminum-steel specification premiums from Rotterdam-Antwerp cold-storage operators. |
| Equipment-as-a-Service Contracting | Converts capital expenditure barriers into recurring revenue with third-party logistics providers. |
| IoT-Enabled Predictive Maintenance | Generates software revenue streams through sensor integration with warehouse management platforms. |
| Local Assembly in PLI Scheme Corridors | Qualifies for Indian logistics infrastructure incentives while satisfying BIS certification requirements. |
| Certified Testing Partnership Expansion | Secures SAMR market access for foreign suppliers facing tightened GB standards enforcement. |
Study Parameters
Direct dialogue with maintenance directors at e-commerce fulfillment centers, plant engineers at cold-storage operators, OEM procurement teams at hydraulic lift manufacturers, and aftermarket service heads at rental fleet operators grounded qualitative findings in operational reality. Secondary validation drew from OSHA enforcement records, EU Machinery Directive conformity assessment databases, SEC filings from listed industrial conglomerates, and customs trade data on steel-aluminum composite imports. Bottom-up equipment deployment tallies triangulated against top-down facility investment forecasts.
Unit shipment and revenue projections across the analysis window reflect segmented modeling by lift mechanism type, installation permanence category, capacity rating tier, and end-use vertical. CAGRs derived from regression analysis against warehouse automation capital expenditure indices and port modernization program announcements. Cold-storage expansion trajectories and reshoring-driven manufacturing facility investments served as industry-specific demand inputs.
Underlying measurement precision varies by segment; fixed installation revenue pools carry tighter precision than portable lift rental fleet estimates due to equipment-as-a-service contract disclosure gaps. Forecasts reflect documented assumptions regarding PLI scheme disbursement continuity and carbon-border adjustment implementation timelines. Deviation in Chinese steel export tariff policy or SAMR enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Retractable Lift Market
Material Handling Equipment
Linear Slides Market
Material Handling Equipment
Industrial Lift Ladder Market
Material Handling Equipment
Log Loaders Market
Material Handling Equipment
Hook Lifts and Skip Loaders Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Global Metal Expansion Joints Market
Material Handling Equipment
Electric Tugger Market
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
Ship Loader and Unloader Market